
 Autoimmune Hemolytic Anemia Therapeutics Market | 2026-2036
Autoimmune Hemolytic Anemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Autoimmune Hemolytic Anemia Therapeutics Market Outlook
Biologic excipients are replacing traditional small-molecule stabilizers in parenteral formulations, which is realigning cost structures for cold-chain dependent therapies. Sanofi leverages its established immunology manufacturing footprint to sustain corticosteroid supply leadership. F. Hoffmann-La Roche Ltd anchors its position through specialized monoclonal antibody production capabilities. Rigel Pharmaceuticals Inc. competes in the complement inhibition niche with focused development programs.
Autoimmune hemolytic anemia therapeutics comprise pharmaceutical agents designed to suppress aberrant immune-mediated erythrocyte destruction, including corticosteroids that modulate T-cell activity, monoclonal antibodies targeting B-cell or complement pathways, and intravenous immunoglobulin that competitively blocks Fc receptors. These agents function primarily to halt hemolysis, reduce transfusion dependency, and prevent end-organ damage in acute and chronic presentations. Monoclonal antibodies command the highest margin pools due to complex bioprocessing requirements and limited biosimilar penetration. Corticosteroids remain the volume leader across therapy areas, though chronic AIHA indications are shifting toward longer-acting biologic alternatives. The end user landscape shows hospitals retaining the majority of infusion-administered therapies while home care settings expand for subcutaneous delivery formats.
The FDA's orphan drug designation framework shapes clinical trial incentives and exclusivity periods for developers targeting warm and cold AIHA subtypes. EMA's MDR and pharmacovigilance requirements govern post-market surveillance for complement inhibitors distributed across European hospital networks. Stakeholders must monitor evolving payer evidence requirements for biologic therapies, as health technology assessments increasingly demand head-to-head hemolysis control data rather than placebo-controlled endpoints.
Market Dynamics
The FDA's accelerated approval pathways for rare disease treatments are compressing development timelines for complement inhibitors and monoclonal antibodies, while hospital systems across North America and Europe race to expand infusion capacity for cold-chain dependent biologic therapies.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation framework grants clinical trial tax credits and seven-year market exclusivity for developers targeting warm and cold AIHA subtypes, accelerating pipeline progression for novel mechanisms.
- Biologics Manufacturing Scale-Up:Specialized monoclonal antibody production capabilities in Switzerland and Germany are expanding batch yields for complement inhibitors, reducing per-dose production costs for hospital-administered therapies.
- Tertiary Care Concentration:United States academic medical centers are consolidating AIHA patient management into dedicated hematology units, creating predictable demand centers for high-complexity infusion therapies.
Market Restraints
- Plasma-Derived Input Volatility:Intravenous immunoglobulin production depends on fractionated human plasma supplies concentrated in United States collection networks, exposing manufacturers to donor availability fluctuations.
- Cold-Chain Infrastructure Gaps:Subcutaneous biologic delivery formats require uninterrupted temperature control through last-mile distribution, limiting penetration in regions with fragmented logistics networks.
- EMA Pharmacovigilance Burden:Post-market surveillance requirements for complement inhibitors under the MDR impose ongoing safety reporting obligations that extend compliance costs beyond approval.
Strategic Opportunities
- Home Administration Expansion:Subcutaneous monoclonal antibody formulations are opening patient self-administration channels outside hospital infusion centers, capturing chronic AIHA maintenance therapy volumes.
- Health Technology Assessment Alignment:European payer evidence requirements are shifting toward head-to-head hemolysis control data, creating first-mover advantage for developers with active comparator trials.
- Biologic Excipient Substitution:Novel stabilizer technologies are replacing traditional small-molecule excipients in parenteral formulations, enabling room-temperature storage extensions that reduce distribution complexity.
Industry Challenges
- Specialized Hematology Talent Scarcity:Clinical trial design for rare autoimmune indications requires expertise in immunohematology and complement biology, with limited investigator availability outside major academic centers.
- Biosimilar Defense Complexity:Monoclonal antibody developers must prepare lifecycle management strategies as regulatory pathways for biosimilar complement inhibitors mature in the United States and European Union.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autoimmune Hemolytic Anemia Therapeutics Market |
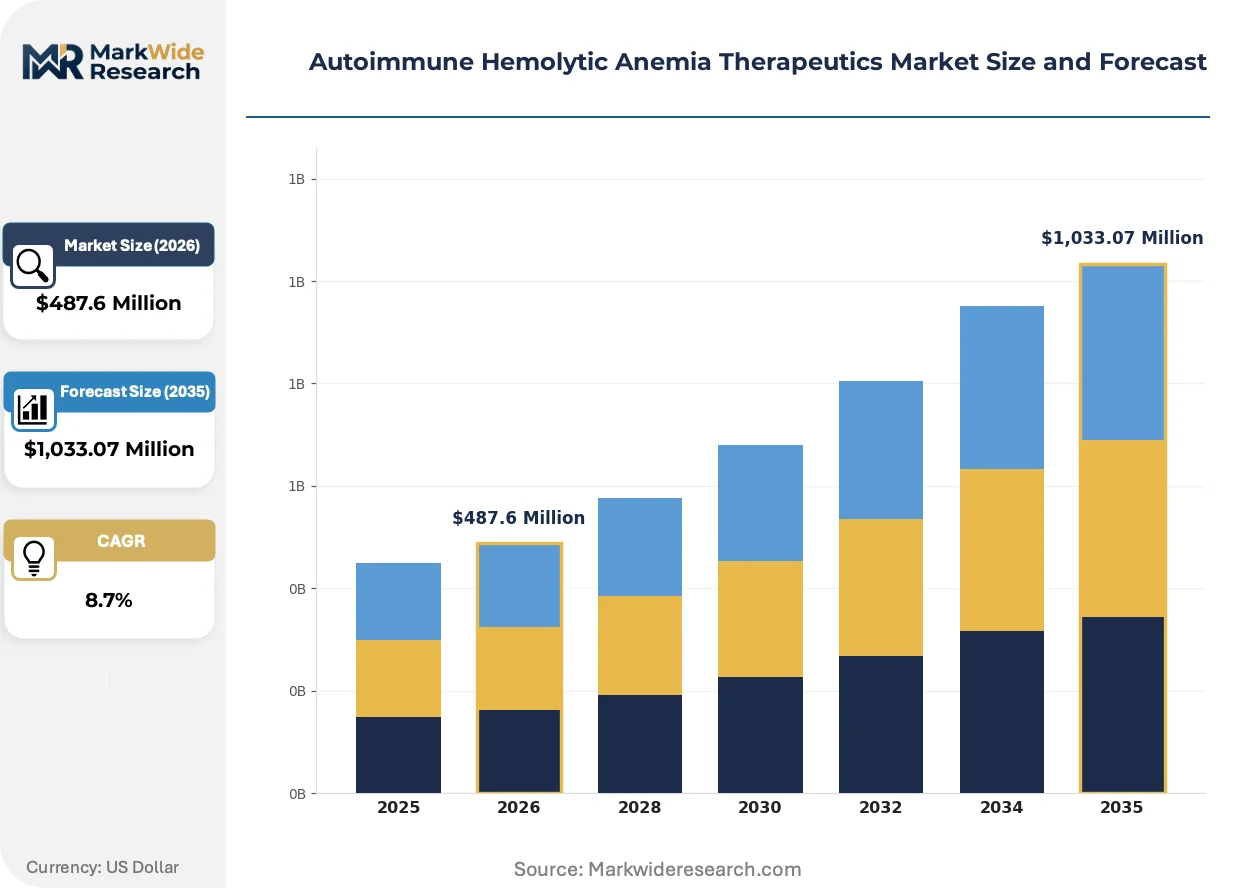
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Intravenous Immunoglobulin, Monoclonal Antibodies, Eculizumab Therapy Area: Chronic AIHA, Warm AIHA, Cold AIHA, Secondary AIHA End User: Hospitals, Specialty Clinics, Home Care Settings, Ambulatory Surgical Centers Administration Route: Intravenous, Subcutaneous, Oral, Intraosseous |
| Companies Covered | Sanofi, F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, Johnson & Johnson Services, Inc., Amneal Pharmaceuticals Inc., Rigel Pharmaceuticals Inc., Amgen Inc., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autoimmune Hemolytic Anemia Therapeutics Market Strategic Shifts
Biologic formulation science and regulatory science are converging to reshape how autoimmune hemolytic anemia therapies reach patients, with manufacturing innovation outpacing traditional distribution models.
Complement C5 inhibitors are overtaking corticosteroid-dependent maintenance protocols in tertiary care protocols. Hematology departments at United States academic medical centers are adopting these agents for refractory cold agglutinin disease cases within eighteen months of label expansion. The shift is overtaking established corticosteroid tapering regimens and forcing restructuring of hospital pharmacy formulary committees around biologic acquisition.
EMA's MDR implementation is tightening post-approval surveillance requirements for complement inhibitor developers distributing across European hospital networks. Manufacturers must now maintain active risk management systems and periodic safety update reports beyond traditional pharmacovigilance obligations. Hospital pharmacy procurement in Germany and France is responding by consolidating supplier relationships to reduce vendor qualification overhead.
Patient administration preferences are driving format innovation toward subcutaneous delivery systems that bypass infusion center dependency. Home care nursing networks and specialty pharmacy channels are capturing chronic maintenance volumes previously retained in hospital outpatient settings. This behavioral shift is most visible in the United States, where payers are steering stable patients toward lower-site-of-care cost structures through benefit design incentives.
Autoimmune Hemolytic Anemia Therapeutics Market Segmentation
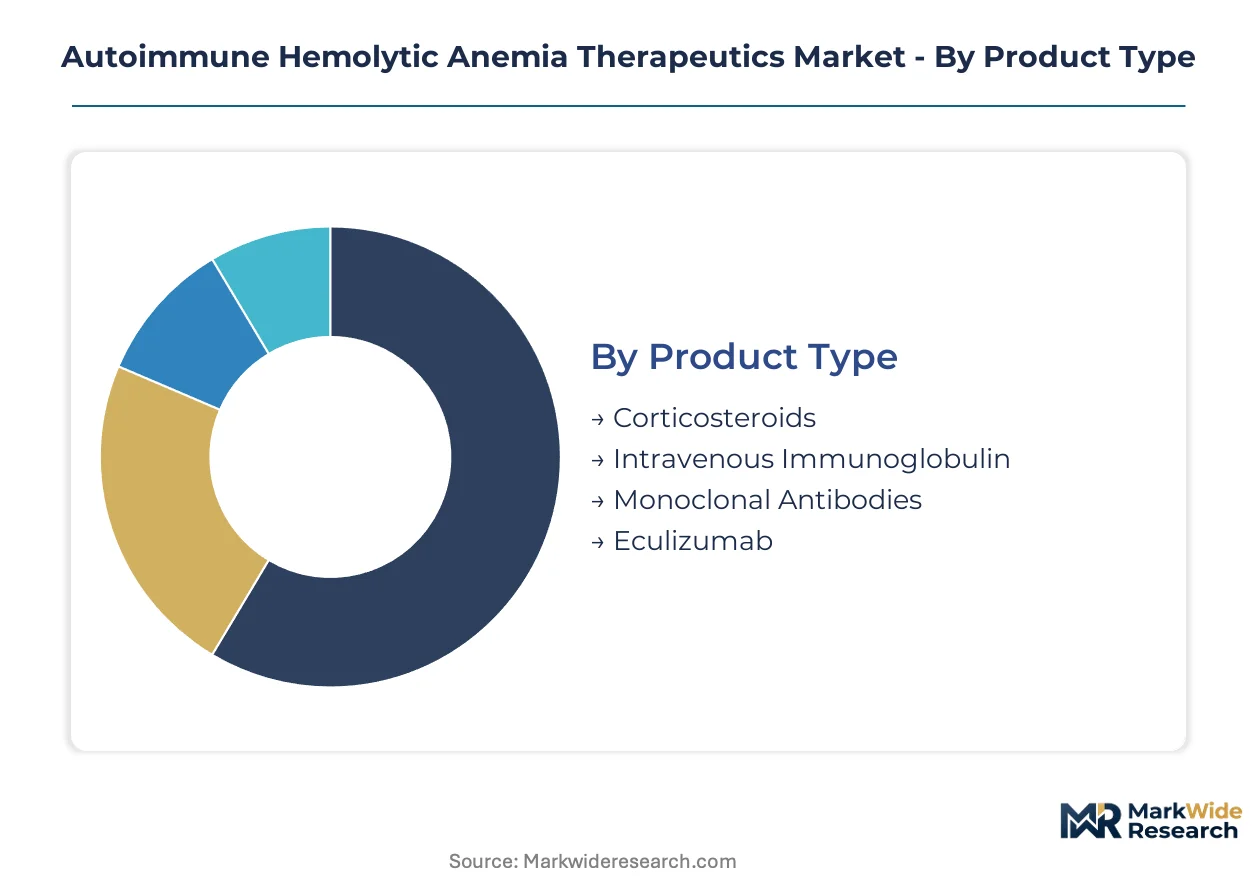
Segmentation in autoimmune hemolytic anemia therapeutics reveals distinct demand patterns across treatment modalities and care settings. Understanding how product types, therapy areas, end users, and administration routes intersect enables precise resource allocation for manufacturers and healthcare systems managing this rare disease population.
Product Type:
Corticosteroids function as standalone first-line interventions, while monoclonal antibodies and complement inhibitors embed into specialized treatment protocols for refractory cases.
- Corticosteroids:Synthetic glucocorticoids such as prednisone and dexamethasone modulate T-cell activity and cytokine signaling to suppress erythrocyte destruction. Prednisone dominates initial therapy in United States emergency departments due to rapid availability and established reimbursement pathways. Chronic corticosteroid exposure drives bone density loss and metabolic complications, pushing tertiary care centers toward steroid-sparing protocols.
- Monoclonal Antibodies:Engineered immunoglobulins target CD20, CD52, or complement proteins to interrupt B-cell mediated hemolysis. Rituximab infusion volumes concentrate at academic medical centers in Boston and San Francisco where hematology specialists manage complex warm AIHA cases. Cold-chain requirements and extended infusion durations limit deployment in smaller hospital systems.
- Intravenous Immunoglobulin:Polyclonal antibody pools from fractionated human plasma competitively block Fc receptor engagement on macrophages.
- Eculizumab:Terminal complement inhibitor requiring specialized pharmacy handling and meningococcal vaccination protocols.
Corticosteroids lead volumes today; monoclonal antibodies are gaining share fastest.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance regimens requiring sustained pharmaceutical expenditure.
- Warm AIHA:IgG-mediated extravascular hemolysis responsive to corticosteroid induction and splenectomy alternatives. United States academic medical centers report highest per-patient pharmaceutical costs due to rituximab dependency in relapsing cases. Autoantibody specificity testing at specialized reference laboratories guides therapy selection.
- Cold AIHA:IgM-driven complement activation causing intravascular hemolysis at lower temperatures. Eculizumab adoption accelerates in Minnesota and Wisconsin where seasonal temperature fluctuations exacerbate hemolysis severity. Sutimlimab has displaced corticosteroid monotherapy in newly diagnosed cases at Mayo Clinic and Cleveland Clinic.
- Chronic AIHA:Persistent hemolysis exceeding six months requiring long-term immunosuppression.
- Secondary AIHA:Immune destruction triggered by lymphoproliferative disorders, infections, or drug exposure.
Warm AIHA leads volumes today; cold AIHA is expanding most quickly.
End User:
Patient acuity and therapy complexity determine whether administration occurs in monitored hospital environments or decentralized care settings.
- Hospitals:Tertiary care centers retain high-complexity cases requiring intensive monitoring, transfusion support, and multidisciplinary hematology teams. Johns Hopkins Hospital and MD Anderson Cancer Center manage the highest annual case volumes in the United States. Infusion center capacity constraints create bottlenecks during complement inhibitor ramp-up phases.
- Home Care Settings:Subcutaneous monoclonal antibody formulations enable self-administration for stable chronic patients. UnitedHealthcare and CVS Specialty Pharmacy networks capture maintenance therapy volumes through home nursing visits. Patient training programs at Dana-Farber Cancer Institute demonstrate adherence rates exceeding hospital-based alternatives.
- Specialty Clinics:Community hematology practices handle corticosteroid titration and routine monitoring.
- Ambulatory Surgical Centers:Limited role restricted to diagnostic procedures and splenectomy referrals.
Hospitals lead volumes today; home care settings are climbing the fastest.
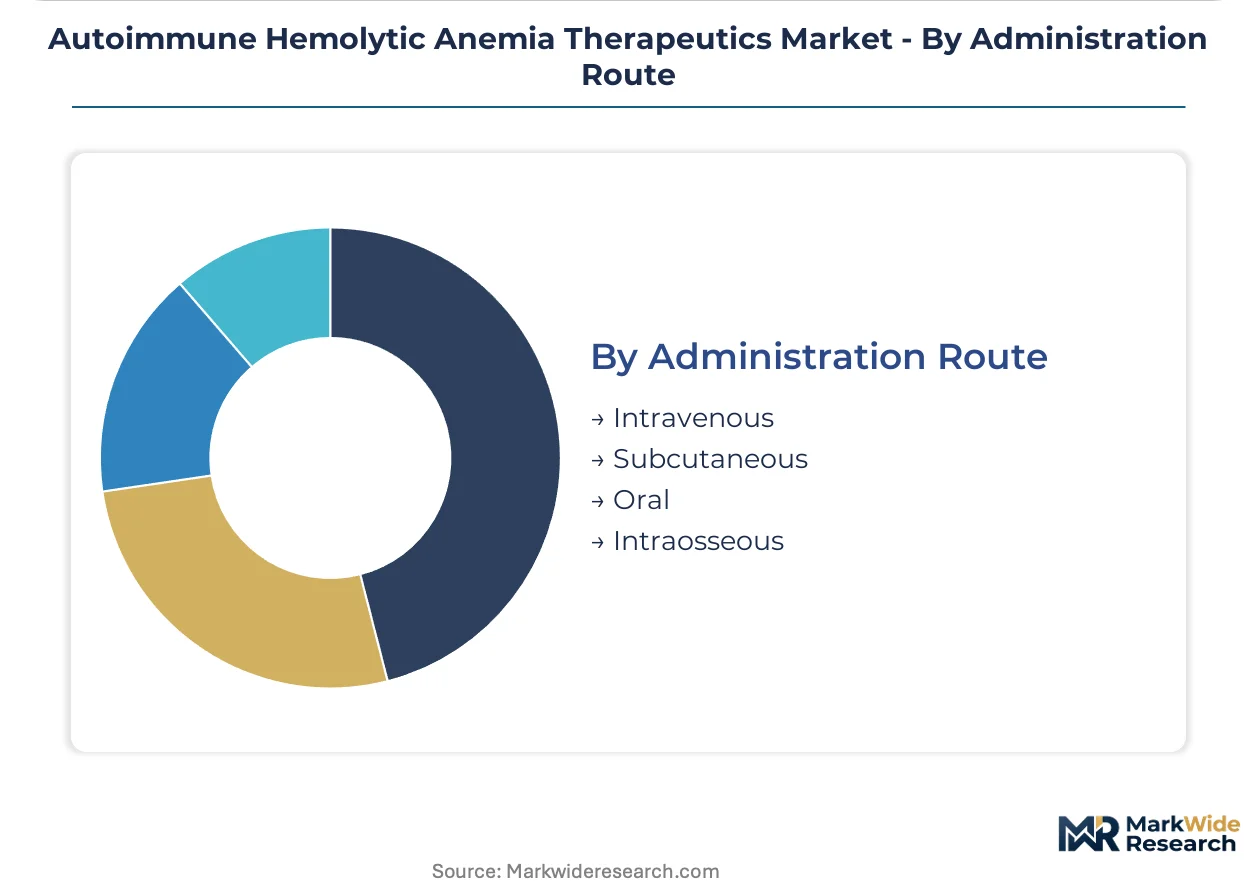
Administration Route:
Supply concentration for cold-chain biologics favors intravenous delivery, while pharmaceutical innovation shifts investment toward patient-administered alternatives.
- Intravenous:Direct bloodstream delivery enables rapid therapeutic levels for acute hemolytic crises. Hospital pharmacy departments in Philadelphia and Los Angeles maintain dedicated biologic infusion suites with cardiac monitoring capability. Batch scheduling optimization reduces per-dose nursing costs at high-volume centers.
- Subcutaneous:Depot formulations extend dosing intervals and eliminate infusion center dependency. Patient preference studies at Stanford University School of Medicine identify injection site reactions as the primary discontinuation driver. Specialty pharmacy distribution networks in Texas and Florida manage temperature-controlled home delivery logistics.
- Oral:Corticosteroid tablets remain the default outpatient prescription format.
- Intraosseous:Emergency vascular access for pediatric patients in critical hemolytic episodes.
Intravenous leads volumes today; subcutaneous is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers anchor demand concentration for autoimmune hemolytic anemia therapeutics, with tertiary care systems in Minnesota, Massachusetts, and Texas managing the highest patient volumes. Hospital pharmacy procurement patterns diverge sharply across national boundaries as regulatory frameworks reshape reimbursement and distribution economics.
United States
Mayo Clinic in Rochester and Cleveland Clinic anchor cold agglutinin disease treatment volumes, with eculizumab and sutimlimab adoption accelerating in northern-tier states where seasonal temperature fluctuations exacerbate hemolysis. FDA orphan drug tax credits compress development timelines for complement inhibitors targeting warm and cold AIHA subtypes. Johns Hopkins Hospital and MD Anderson Cancer Center in Texas retain the highest annual case volumes for complex rituximab-dependent warm AIHA management.
Germany
University hospitals in Munich and Heidelberg concentrate infusion capacity for biologic therapies, with pharmacy procurement committees restructuring around complement inhibitor acquisition costs. EMA MDR implementation tightens post-approval surveillance requirements for terminal complement inhibitors distributed across hospital networks. The Rhine-Ruhr metropolitan region maintains specialized cold-chain logistics infrastructure serving tertiary care centers in North Rhine-Westphalia and Baden-Württemberg.
Japan
PMDA accelerated approval pathways for rare disease treatments compress regulatory timelines for monoclonal antibody developers, with Tokyo and Osaka academic medical centers managing refractory case volumes. National health insurance reimbursement rates for intravenous immunoglobulin fluctuate with plasma collection economics. The Kanto region surrounding Tokyo anchors biologics distribution infrastructure for complement-dependent hemolytic disorders.
Switzerland
Roche's Basel manufacturing footprint anchors specialized monoclonal antibody production capabilities serving European hospital networks, with Swissmedic maintaining stringent pharmacovigilance requirements for complement inhibitors. Geneva and Zurich university hospitals concentrate expertise in immunohematology clinical trial design. The country's fractionalized health insurance system creates heterogeneous payer evidence requirements across cantonal boundaries.
United Kingdom
NHS England specialized commissioning frameworks concentrate AIHA patient management into designated hematology centers in London, Manchester, and Birmingham, with NICE technology appraisals demanding head-to-head hemolysis control data for biologic therapies. The MHRA operates under retained EU MDR alignment for post-market surveillance of complement inhibitors. Home care nursing networks in the Southeast are capturing maintenance therapy volumes through subcutaneous delivery formats.
Autoimmune Hemolytic Anemia Therapeutics Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and specialized bioprocessing capabilities. Market structure tilts toward consolidated leadership in monoclonal antibody production, with corticosteroid supply maintaining fragmented generic competition. Three archetypes dominate: integrated immunology conglomerates with captive biologics capacity, plasma fractionation specialists dependent on donor network economics, and focused complement inhibition developers with niche pipeline assets. Competitive dynamics center on biosimilar defense preparation and subcutaneous formulation patent positioning.
Among integrated pharmaceutical conglomerates, Sanofi and F. Hoffmann-La Roche Ltd occupy positions reflecting established immunology manufacturing footprints and specialized monoclonal antibody production capabilities respectively. Rigel Pharmaceuticals Inc. exemplifies the focused development archetype, competing within complement inhibition niches where complex bioprocessing requirements limit biosimilar penetration. These three entities represent distinct strategic postures: volume leadership through corticosteroid supply, premium positioning via specialized biologics infrastructure, and targeted development in mechanistically distinct therapeutic areas.
| Leading Market Players |
|---|
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson Services, Inc. |
| Amneal Pharmaceuticals Inc. |
| Rigel Pharmaceuticals Inc. |
| Amgen Inc. |
| GlaxoSmithKline plc |
| Others |
Value Chain & Pricing Dynamics
Hospital pharmacy procurement committees at United States academic medical centers concentrate purchasing power for complement inhibitors, anchoring contract-based pricing structures that tie annual volume commitments to per-dose rebates and formulary tier placement.
Pricing Analysis
Plasma-derived input costs pass through directly into intravenous immunoglobulin pricing, with fractionation economics in United States donor networks creating margin compression for manufacturers exposed to collection volatility. Three-tier pricing structure across premium biologics, standard monoclonal antibodies, and economy corticosteroids reflects certification complexity and cold-chain handling requirements. Pricing pressure stems from health technology assessment demands for head-to-head hemolysis control data in European markets. Community hematology practices exhibit highest price sensitivity due to fixed reimbursement rates, while tertiary care centers absorb premium positioning through bundled episode payments.
Supply Chain Analysis
Specialized hematology talent shortages in Basel and Boston constrain batch scheduling optimization for monoclonal antibody production, forcing manufacturers to prioritize yield efficiency over geographic diversification. Supply concentrates in Switzerland for specialized bioprocessing, Germany for fill-finish operations, and the United States for plasma fractionation. Raw material dependencies include fractionated human plasma, recombinant protein cell lines, and novel biologic excipients replacing traditional stabilizers. Single-source vulnerability runs through Swiss monoclonal antibody manufacturing hubs. Distribution runs through hospital pharmacy procurement networks with consolidated supplier relationships reducing vendor qualification overhead.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as tertiary care protocols shift toward complement inhibitor maintenance regimens that demand superior hemolysis control profiles over corticosteroid tapering alternatives.
For Market Incumbents: Acquire specialized bioprocessing facilities in Basel and Munich to secure monoclonal antibody production capacity against biosimilar entry threats. Consolidate supplier relationships with hospital pharmacy procurement committees to reduce vendor qualification overhead and defend formulary tier placement. Expand backward integration into plasma collection networks to mitigate donor availability volatility affecting intravenous immunoglobulin margins. For New Entrants and Emerging Players: Enter via subcutaneous formulation development for chronic AIHA maintenance therapy, capturing patient administration preference shifts away from infusion center dependency. Target home care nursing networks and specialty pharmacy channels in Texas and Florida where temperature-controlled logistics infrastructure supports biologic delivery. Pursue licensing agreements with established immunology manufacturers to bypass specialized hematology talent scarcity in clinical trial design. For Investors and Strategic Acquirers: Integrated immunology conglomerates with captive biologics capacity are the most active acquirers in this space, seeking complement inhibition pipeline assets to round out rare disease portfolios. Five-to-ten year viability hinges on successful biosimilar defense preparation and subcutaneous formulation patent positioning. Watch for FDA accelerated approval pathway utilization rates as inflection indicators for development timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Patient self-administration preferences at Stanford University School of Medicine drive home care channel capture. |
| Plasma Collection Network Integration | United States donor availability fluctuations threaten intravenous immunoglobulin production economics. |
| Health Technology Assessment Alignment | European payer demands for head-to-head hemolysis data at NICE create first-mover clinical trial advantages. |
| Specialized Bioprocessing Capacity Expansion | Swiss and German batch yield improvements reduce per-dose production costs for hospital-administered therapies. |
| Orphan Drug Designation Pursuit | FDA tax credits and exclusivity periods compress development timelines for warm and cold AIHA subtypes. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume estimates and top-down pharmaceutical expenditure patterns were triangulated to anchor market sizing.
Comparable historical periods anchored the forecast window, with analytical frameworks modeling treatment line progression, administration route migration, patient population segmentation, and regional regulatory clustering across the projection horizon. CAGRs were derived from therapy area adoption curves and biologics manufacturing scale trajectories, incorporating infusion capacity expansion rates and subcutaneous formulation pipeline advancement as industry-specific inputs.
Inputs from clinical trial registries and hospital procurement databases were available through the study window; gaps in real-world hemolysis control outcome data introduce uncertainty bands around complement inhibitor adoption assumptions. Forecasts reflect documented assumptions regarding regulatory pathway utilization and payer evidence requirements. Material deviation in FDA accelerated approval grant rates or EMA MDR surveillance enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Tularemia Therapeutics Market
Specialty Medicine
Dry Eye Syndrome Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Stress Urinary Incontinence Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market
Specialty Medicine
Growth Hormone Deficiency Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Primary Immunodeficiency Market
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Urinary Retention Market