
 Hypophosphatasia Treatment Market | 2026-2036
Hypophosphatasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hypophosphatasia Treatment Market Foresight
Asset-light licensing and milestone-based partnership structures is tilting competitive dynamics toward biotech firms with platform technologies rather than fully integrated pharmaceutical giants. Alexion Pharmaceuticals leverages its rare disease commercial infrastructure to sustain market presence in ultra-orphan metabolic disorders. Ultragenyx Pharmaceutical anchors its position through deep specialization in genetic disease therapeutics and direct patient access programs. AM-Pharma competes by advancing novel biologic platforms targeting alkaline phosphatase restoration pathways.
Hypophosphatasia treatment encompasses therapeutic interventions addressing deficient tissue-nonspecific alkaline phosphatase activity, a rare inborn error of metabolism characterized by impaired bone mineralization, respiratory complications, and premature tooth loss; enzyme replacement therapies deliver recombinant alkaline phosphatase to restore phosphate metabolism and skeletal integrity. The product type landscape shows enzyme replacement therapy occupying the dominant clinical position due to established efficacy in perinatal and infantile forms, while gene therapy represents the fastest-growing segment as vector delivery technologies mature for durable correction. Among administration routes, intravenous delivery maintains primacy for hospital-based initiation, though subcutaneous formulations are gaining traction for homecare transition and reduced infusion center dependency.
The FDA's orphan drug designation program and the EMA's priority medicines scheme jointly shape development incentives, accelerating trial timelines and extending exclusivity periods for hypophosphatasia innovators. The European Medicines Agency enforces centralized pediatric investigation plans that mandate age-appropriate formulation studies, influencing pipeline prioritization across developer portfolios. Stakeholders must monitor evolving gene therapy reimbursement frameworks and site-of-care policy shifts that will determine patient access velocity and manufacturer commercial economics.
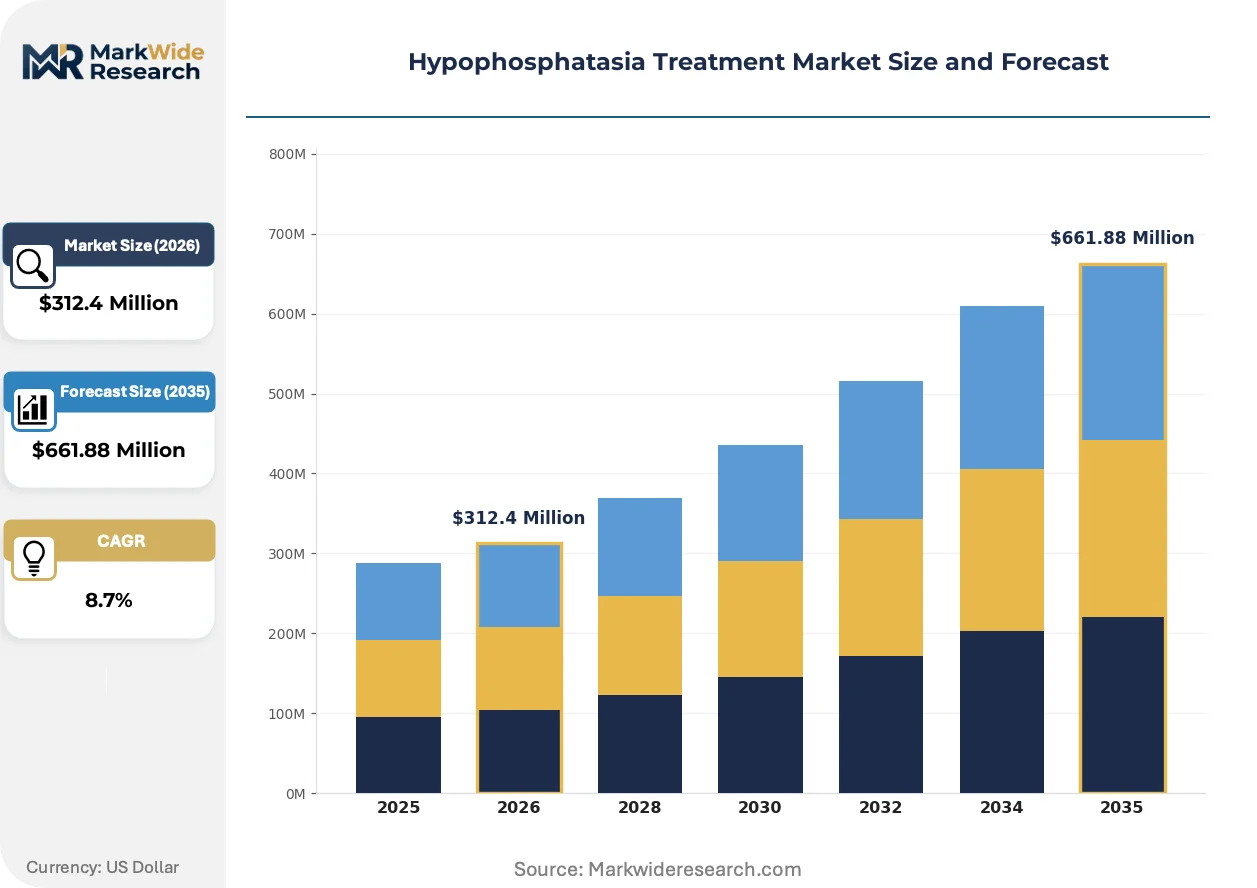
Market Dynamics
Enzyme replacement therapy commercialization is concentrating market control among developers with established rare disease infrastructure, while gene therapy pipelines threaten to compress long-term revenue durability for incumbent biologics.
Growth Catalysts
- EMA Priority Medicines Scheme:Accelerated assessment timelines for hypophosphatasia candidates compress development-to-market intervals, incentivizing European trial site activation.
- Subcutaneous formulation advancement:Home administration protocols reduce infusion center burden and expand addressable patient pools beyond academic medical centers.
- Pediatric endocrinology networks:Specialized referral pathways in the United States concentrate diagnosis velocity and treatment initiation for perinatal presentations.
Market Restraints
- Recombinant protein manufacturing concentration:Contract development organizations with mammalian cell culture expertise cluster in Switzerland and Massachusetts, creating single-source vulnerability.
- FDA orphan drug exclusivity duration:Seven-year market protection limits biosimilar entry but also constrains pricing negotiation leverage for payers.
- Gene therapy durability uncertainty:Long-term expression persistence in alkaline phosphatase restoration remains unvalidated, delaying payer confidence.
Strategic Opportunities
- Adult-onset underdiagnosis:Odonto-hypophosphatasia and adult skeletal forms in Germany and France represent expansion targets beyond infantile crisis management.
- Site-of-care policy evolution:Medicare reimbursement for home infusion services creates channel diversification potential for subcutaneous product transitions.
- AAV vector manufacturing scale-up:Contract viral production capacity expansion in North Carolina and Belgium enables gene therapy cost structure compression.
Industry Challenges
- Biologics talent scarcity:Rare disease clinical operations expertise concentrates at established developers, constraining pipeline expansion for emerging entrants.
- Multi-year pediatric investigation plans:EMA-mandated age-stratified studies extend development timelines and inflate program burn rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypophosphatasia Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Replacement Therapy, Antibody Therapy, Gene Therapy, Small Molecule Inhibitors End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Administration Route: Intravenous, Subcutaneous, Oral, Topical Distribution Channel: Direct Sales, Online Pharmacy, Distributor Sales, Others |
| Companies Covered | AstraZeneca, Alexion Pharmaceuticals, AM-Pharma, Ultragenyx Pharmaceutical, Kirin Holdings Company, Pfizer, Novartis, BioMarin Pharmaceutical, Mereo BioPharma Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypophosphatasia Treatment Market Shifts & Advancements
Vector engineering and patient access model reinvention are compressing traditional biologic commercialization timelines while reshaping stakeholder economics across the hypophosphatasia treatment continuum.
Adeno-associated virus serotype selection is virtualizing gene therapy development economics. Biotech developers in Massachusetts and the Netherlands are adopting computationally optimized capsid libraries to accelerate tissue targeting validation. This capability is virtualizing the preclinical-to-clinic transition, compressing capital requirements for alkaline phosphatase gene correction programs.
EMA centralized pediatric investigation plans are mandating age-appropriate formulation development across all hypophosphatasia trials. Developers must now complete neonatal pharmacokinetic studies before adult label expansion, restructuring pipeline prioritization. European trial sponsors are responding by embedding neonatal intensive care unit recruitment into Phase I/II protocols.
Specialty pharmacy networks are consolidating patient onboarding and adherence monitoring functions previously fragmented across hospital systems. Payers in the United States are directing high-cost biologic dispensing toward limited distribution channels with embedded clinical support. This concentration is most visible in California and Texas, where integrated specialty pharmacies now coordinate home nursing for subcutaneous enzyme replacement transitions.
Hypophosphatasia Treatment Market Segmentation
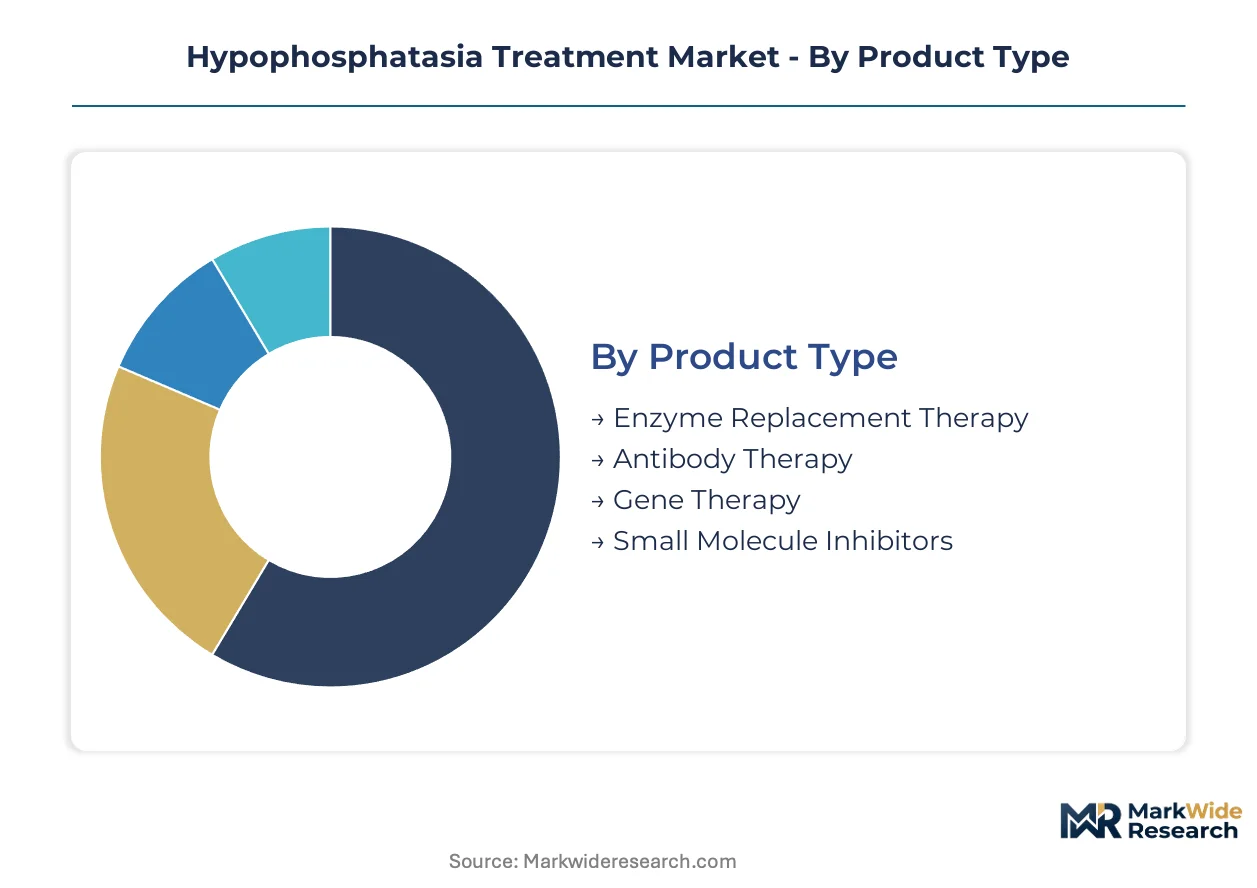
Segmentation in hypophosphatasia treatment reveals how clinical complexity, patient mobility constraints, and reimbursement architecture jointly determine product-market fit. Each dimension exposes distinct operational requirements for developers navigating ultra-rare disease commercialization.
Product Type:
Mature biologic platforms dominate current revenue, while emerging modalities are compressing development timelines through novel mechanism validation.
- Enzyme Replacement Therapy:Recombinant tissue-nonspecific alkaline phosphatase delivered via parenteral infusion restores phosphate metabolism in deficient patients. Demand concentrates in pediatric endocrinology networks across the United States, where FDA orphan drug exclusivity sustains developer commitment to manufacturing scale-up.
- Gene Therapy:Adeno-associated virus vectors encoding functional alkaline phosphatase transgenes target durable correction with single-dose administration. Massachusetts and Netherlands biotech clusters are driving capsid engineering advances, accelerating tissue targeting validation for this modality.
- Antibody Therapy:Monoclonal approaches modulating bone mineralization pathways offer alternative mechanism intervention.
- Small Molecule Inhibitors:Oral compounds targeting enzymatic regulators of phosphate metabolism provide non-biologic alternatives for milder phenotypes.
Enzyme replacement therapy handles the majority of throughput; gene therapy is the fastest mover on share.
End User:
Care site selection reflects disease severity staging, reimbursement authorization requirements, and patient geographic distribution.
- Hospitals:Academic medical centers manage perinatal and infantile crisis presentations requiring intensive monitoring and multidisciplinary coordination. These sites in California and Texas anchor initial diagnosis and treatment initiation for severe forms.
- Specialty Pharmacies:Limited distribution channels with embedded clinical support coordinate high-cost biologic dispensing and adherence monitoring. United States payers are consolidating patient onboarding through these networks to manage total cost of care.
- Clinics:Pediatric endocrinology and metabolic disease outpatient facilities manage stable patients post-initiation.
- Homecare:Home nursing services enable subcutaneous administration transitions, reducing infusion center dependency for ambulatory patients.
Hospitals retain the highest patient acuity concentration; specialty pharmacies are expanding their coordination role fastest.
Administration Route:
Delivery modality selection balances bioavailability requirements, patient compliance, and site-of-care economics.
- Intravenous:Hospital-based infusion maintains primacy for enzyme replacement initiation and severe phenotype management. This route dominates perinatal and infantile treatment protocols where therapeutic monitoring is essential.
- Subcutaneous:Home administration formulations reduce facility burden and expand addressable pools beyond academic medical centers. Medicare reimbursement evolution for home infusion services in the United States is accelerating channel diversification.
- Oral:Small molecule delivery offers patient convenience for chronic maintenance in milder disease forms.
- Topical:Localized application targets odonto-hypophosphatasia manifestations with limited systemic exposure.
Intravenous delivery handles current treatment volume; subcutaneous transition is climbing the fastest.
Distribution Channel:
Channel structure reflects product temperature sensitivity, patient access requirements, and payer cost containment priorities.
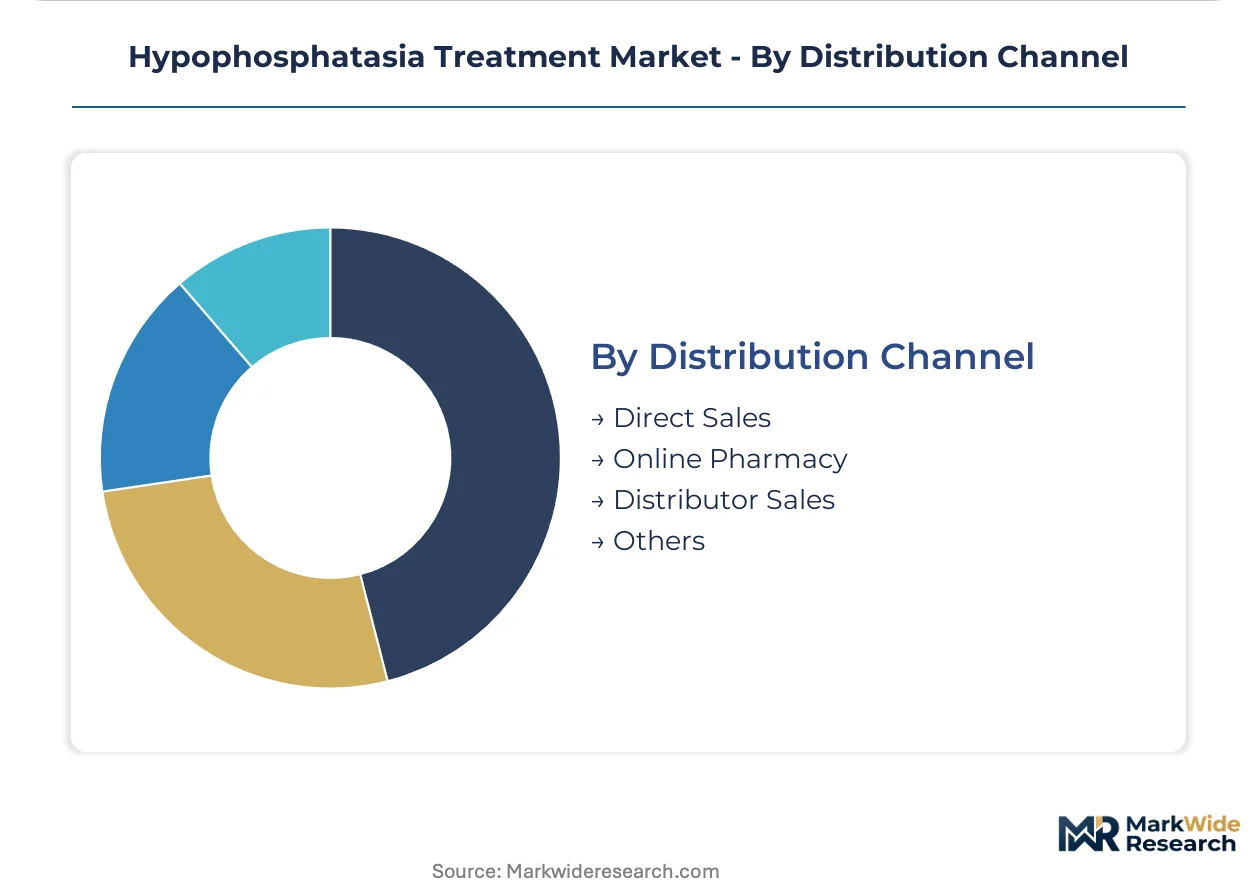
- Direct Sales:Manufacturer-to-provider relationships dominate enzyme replacement therapy distribution for ultra-rare diseases. This channel ensures cold chain integrity and patient registry compliance for FDA-mandated pharmacovigilance.
- Distributor Sales:Regional specialty distributors with rare disease logistics expertise extend reach to dispersed pediatric endocrinology practices. Switzerland and Massachusetts-based contract organizations with mammalian cell culture capabilities anchor this network.
- Online Pharmacy:Digital dispensing platforms are emerging for oral small molecule maintenance therapies.
- Others:Compassionate access and named patient programs bridge regulatory gaps for pre-approval availability.
Direct sales channels handle the majority of biologic throughput; specialty distributor partnerships are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug exclusivity and EMA priority medicines schemes are concentrating developer investment in jurisdictions with mature rare disease commercial infrastructure. The United States anchors current revenue concentration through specialty pharmacy networks and academic medical center coordination.
United States
Pediatric endocrinology referral networks in California and Texas accelerate diagnosis velocity for perinatal presentations. The FDA's seven-year orphan drug exclusivity framework sustains pricing power for enzyme replacement innovators. Massachusetts hosts contract development organizations with mammalian cell culture expertise that anchor recombinant protein manufacturing.
Germany
Adult-onset odonto-hypophosphatasia and skeletal forms drive expansion beyond infantile crisis management. The country's national pharmaceutical regulator enforces centralized pediatric investigation plans mandating age-appropriate formulation studies. Bavaria's biotech clusters coordinate neonatal intensive care unit recruitment into early-phase protocols.
France
Academic medical centers in Paris manage multidisciplinary care coordination for severe phenotypes. ANSM oversight of gene therapy trials shapes vector engineering investment priorities. The Île-de-France region concentrates clinical research sites for alkaline phosphatase restoration pathway validation.
Switzerland
Contract manufacturing organizations with rare disease logistics expertise extend reach to dispersed European pediatric practices. Swissmedic accelerated assessment pathways compress development timelines for ultra-orphan metabolic candidates. Basel and Zürich anchor mammalian cell culture capabilities serving biologic developers.
Netherlands
Amsterdam and Rotterdam biotech clusters drive adeno-associated virus capsid engineering advances for gene therapy programs. EMA centralized procedures from Amsterdam headquarters influence pediatric investigation plan structures across developer portfolios. Dutch academic medical centers participate in European neonatal pharmacokinetic study networks.
Hypophosphatasia Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the hypophosphatasia treatment continuum. The market structure concentrates around developers with established rare disease infrastructure and direct patient access capabilities. Three archetypes dominate: integrated rare disease specialists with commercial scale, platform-technology biotechs with novel mechanism pipelines, and large-cap pharmaceutical companies with orphan drug portfolio diversification. Competitive moves center on subcutaneous formulation advancement for homecare transition and gene therapy manufacturing scale-up for cost structure compression.
Among rare disease specialists, Alexion Pharmaceuticals, Ultragenyx Pharmaceutical, and AM-Pharma occupy distinct positioning archetypes. Alexion exemplifies the integrated commercial infrastructure model leveraging ultra-orphan metabolic disorder expertise. Ultragenyx anchors the genetic disease deep-specialization segment with direct patient access program capabilities. AM-Pharma represents the novel biologic platform approach targeting alkaline phosphatase restoration pathways through distinct mechanism validation.
| Leading Market Players |
|---|
| AstraZeneca |
| Alexion Pharmaceuticals |
| AM-Pharma |
| Ultragenyx Pharmaceutical |
| Kirin Holdings Company |
| Pfizer |
| Novartis |
| BioMarin Pharmaceutical |
| Mereo BioPharma Group |
| Others |
Supply & Pricing Matrix
Mammalian cell culture capacity in Switzerland and Massachusetts anchors recombinant alkaline phosphatase production, concentrating margin capture with contract manufacturers possessing rare disease biologics expertise. This upstream concentration limits pricing flexibility for developers while reinforcing the premium positioning of enzyme replacement therapies.
Pricing Analysis
Orphan drug exclusivity status creates the primary spread between on-patent biologics and future competitive entries. Pricing stratifies across FDA-designated orphan therapies, standard-of-care supportive treatments, and economy-tier symptom management protocols. Cost compression in supportive care segments is intensifying because gene therapy pipelines threaten long-term revenue durability for incumbent enzyme products. Pediatric endocrinology networks exhibit lowest price sensitivity due to limited therapeutic alternatives, while adult-onset odonto-hypophosphatasia patients demonstrate higher sensitivity to out-of-pocket cost exposure.
Supply Chain Analysis
Lonza and Catalent hold dominant contract manufacturing capacity for mammalian cell culture production of recombinant proteins. Supply concentrates in Switzerland, Massachusetts, and North Carolina, with viral vector production for gene therapy candidates expanding in Belgium. Raw material dependencies include Chinese hamster ovary cell lines, serum-free media formulations, and single-use bioreactor components. Single-source vulnerability in fill-finish operations creates supply chain risk. Distribution runs through limited specialty pharmacy networks with embedded cold chain integrity and patient registry compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce expertise in neonatal pharmacokinetic study design and rare disease regulatory navigation constrains pipeline expansion, favoring incumbents with established pediatric investigation plan execution capabilities.
For Market Incumbents: Build manufacturing scale moats through captive mammalian cell culture capacity in Massachusetts or Switzerland. Expand subcutaneous formulation portfolios to capture homecare transition revenue before gene therapy durability validation. Vertical integration into viral vector production hedges against AAV manufacturing bottlenecks threatening long-term pipeline economics.
For New Entrants and Emerging Players: Adult-onset skeletal hypophosphatasia in Germany and France represents the most penetrable entry point, given diagnostic underpenetration and milder phenotype management requirements. Odonto-hypophosphatasia manifestations offer oral small molecule development pathways with reduced clinical trial complexity. Partner with established European neonatal intensive care unit networks to accelerate patient recruitment for regulatory submission.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with platform-technology biotechs holding AAV capsid engineering capabilities but lacking commercial infrastructure. Five-to-ten year viability hinges on gene therapy reimbursement framework maturation and durability data emergence. Watch EMA centralized pediatric investigation plan completion rates as inflection indicator for pipeline velocity and capital efficiency.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Home administration protocols reduce infusion center dependency and expand addressable patient pools. |
| AAV Manufacturing Scale-Up | Contract viral production capacity expansion in North Carolina and Belgium compresses gene therapy cost structures. |
| Pediatric Investigation Plan Execution | EMA-mandated neonatal pharmacokinetic studies accelerate regulatory timelines for developers with established protocols. |
| Specialty Pharmacy Network Integration | Limited distribution channels with embedded clinical support consolidate payer-directed high-cost biologic dispensing. |
| Site-of-Care Policy Engagement | Medicare reimbursement evolution for home infusion services creates channel diversification potential for subcutaneous transitions. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population estimates and top-down market sizing triangulated to constrain variance across segmentation dimensions.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by treatment modality, administration route, patient age stratum, and regional regulatory cluster. CAGRs derived from epidemiological prevalence trends, diagnosis rate assumptions, and treatment penetration curves. Forecast inputs incorporated orphan drug exclusivity expiration schedules and gene therapy reimbursement framework evolution.
Practitioners should monitor EMA pediatric investigation plan completion delays, FDA gene therapy durability guidance revisions, and site-of-care policy shifts for early signals of forecast variance. Quarterly review of specialty pharmacy network expansion rates and AAV manufacturing capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Global Overactive Bladder Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Kaposi Sarcoma Market