
 Short Bowel Syndrome Market | 2026-2036
Short Bowel Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Short Bowel Syndrome Market Outlook
Buyer concentration among homecare providers and specialty infusion pharmacies is restructuring procurement dynamics across the Short Bowel Syndrome landscape. Takeda Pharmaceutical Company Limited leverages its established GLP-2 therapy portfolio to anchor premium positioning in parenteral nutrition-adjacent drug markets. Zealand Pharma competes through differentiated peptide engineering capabilities that sustain pipeline momentum for next-generation intestinal rehabilitation agents.
Short bowel syndrome denotes a malabsorptive disorder arising from surgical resection or congenital defect leaving less than 200 cm of functional small intestine, requiring lifelong nutritional intervention and often parenteral support. The condition's primary commercial purpose centers on sustaining patient survival and reducing dependency on intravenous nutrition through intestinal adaptation pharmacotherapy and optimized enteral feeding protocols. Parenteral nutrition retains the dominant value share within product type segmentation, though medications represent the fastest-expanding margin pool as GLP-2 receptor agonists penetrate treatment guidelines. Homecare delivery mode growth outpaces hospital-based administration, reflecting payer pressure to shift chronic administration outside institutional settings.
The FDA orphan drug framework and EMA's parallel designation pathway for rare gastrointestinal disorders shape clinical trial incentives and extended market exclusivity for novel entrants. Reimbursement coding complexity under Medicare's durable medical equipment provisions and comparable European hospital outpatient mechanisms directly determines patient access to high-cost parenteral formulations. Stakeholders must monitor evolving FDA guidance on real-world evidence submissions for intestinal failure therapies while assessing how state-level Medicaid managed care transitions affect homecare reimbursement stability.
Market Dynamics
The migration of parenteral nutrition administration from hospital infusion centers to homecare settings is restructuring reimbursement flows and procurement relationships across the Short Bowel Syndrome therapeutic landscape. This channel shift concentrates purchasing power among specialty infusion pharmacies and durable medical equipment suppliers, altering how GLP-2 analogs and nutritional formulations reach patients.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated review pathway and seven-year market exclusivity provisions incentivize biopharmaceutical investment in novel intestinal rehabilitation agents, compressing development timelines for GLP-2 receptor agonist candidates.
- Homecare Infrastructure Expansion:Medicare's durable medical equipment provisions and comparable European hospital outpatient mechanisms now reimburse ambulatory parenteral nutrition delivery, enabling patient discharge and chronic disease management outside institutional settings.
- Peptide Engineering Advances:Recombinant DNA and solid-phase synthesis technologies yield longer-acting GLP-2 analogs with improved pharmacokinetic profiles, reducing injection frequency and enhancing adherence in long-term therapy.
Market Restraints
- Biologic Input Cost Volatility:Recombinant peptide production relies on mammalian cell culture systems and specialized growth media, exposing manufacturers to supply fluctuations in fetal bovine serum and single-use bioreactor components.
- Reimbursement Coding Complexity:Medicare's J-code classification system and European DRG-based hospital payment mechanisms create administrative friction, delaying patient access to high-cost parenteral lipid emulsions and amino acid formulations.
- Enteral Nutrition Substitution:Optimized polymeric and elemental enteral formulas with enhanced bioavailability compete for intestinal rehabilitation market share, particularly in patients with residual bowel lengths exceeding 100 centimeters.
Strategic Opportunities
- Real-World Evidence Pathways:FDA guidance on patient registry data and electronic health record submissions creates regulatory tailwinds for post-market surveillance of intestinal failure therapies, potentially accelerating label expansions.
- Pediatric Indication Development:Congenital short bowel syndrome in neonatal populations represents an underserved therapeutic segment, with distinct pharmacokinetic requirements and caregiver-administered delivery protocols.
- Telehealth-Integrated Monitoring:Remote patient monitoring platforms and connected infusion pumps enable proactive intervention for catheter-related bloodstream infections and metabolic complications, reducing emergency department utilization.
Industry Challenges
- Specialized Infusion Nursing Shortage:Central venous catheter maintenance and parenteral nutrition compounding require certified home infusion nurses, with workforce gaps constraining patient enrollment in ambulatory programs.
- Compounding Pharmacy Compliance:USP <797> sterile compounding standards and state board of pharmacy inspections impose capital-intensive cleanroom infrastructure requirements on regional infusion providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Bowel Syndrome Market |
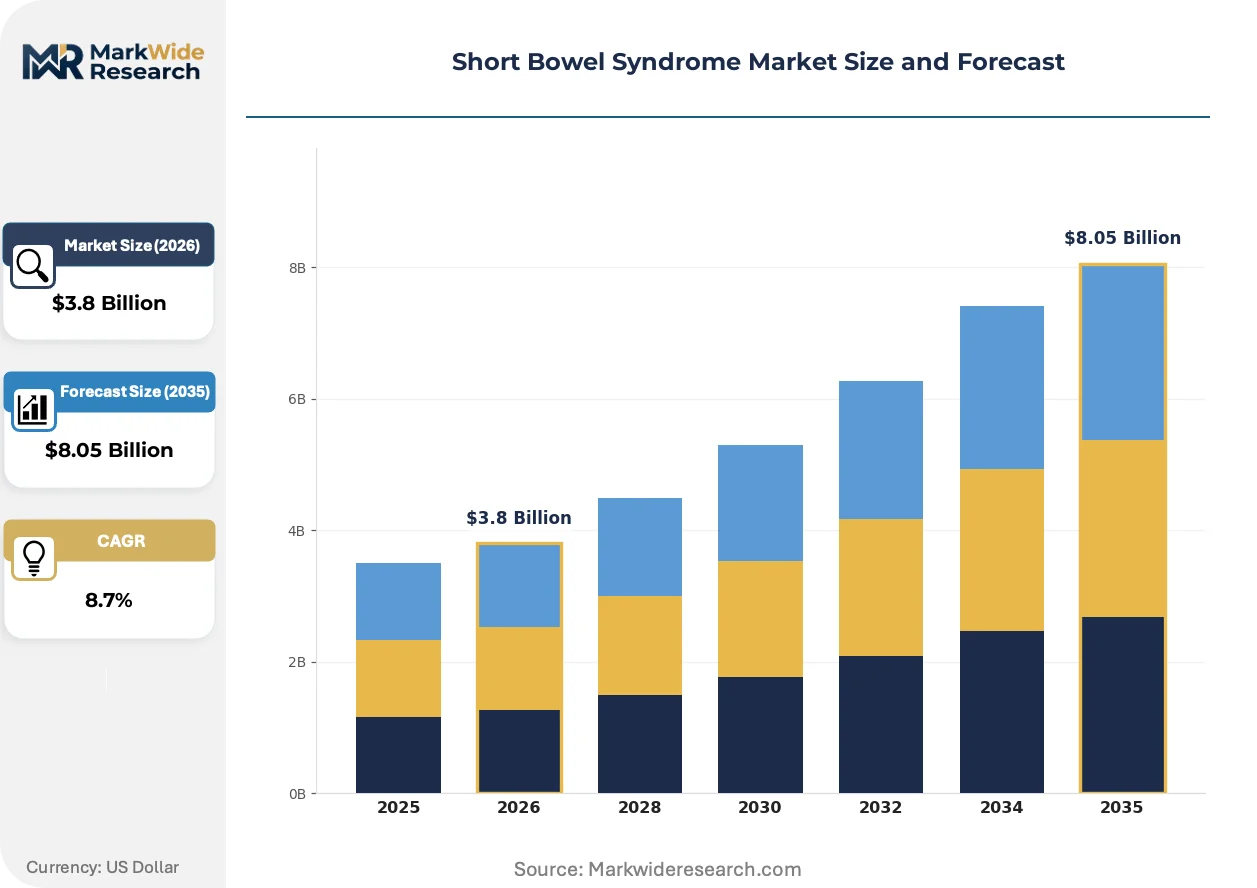
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parenteral Nutrition, Enteral Nutrition, Medications, Medical Devices Delivery Mode: Intravenous, Oral, Subcutaneous, Enteral End User: Hospitals, Clinics, Homecare, Specialty Centers Formulation: Liquid, Powder, Gel, Capsule |
| Companies Covered | Takeda Pharmaceutical Company Limited, Zealand Pharma, Ironwood Pharmaceuticals, OxThera, Ardelyx, VectivBio, Hanmi Pharmaceutical, Nestlé Health Science, Nutricia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Bowel Syndrome Market Strategic Shifts
Novel GLP-2 receptor agonist formulations and connected delivery devices are compressing treatment paradigms, while regulatory frameworks adapt to accommodate real-world evidence generation for rare disease therapeutics.
Extended-release depot formulations of GLP-2 analogs is overtaking daily subcutaneous injection regimens in clinical development pipelines. Homecare providers and specialty pharmacies are prioritizing these longer-acting candidates to reduce nursing visit frequency and improve patient compliance. The technology is enabling pharmaceutical manufacturers to differentiate on convenience metrics rather than efficacy endpoints alone, reshaping competitive positioning in intestinal rehabilitation.
EMA's parallel orphan designation pathway for rare gastrointestinal disorders harmonizes clinical trial incentives with FDA frameworks, creating transatlantic regulatory convergence. The policy reduces redundant pediatric investigation plan requirements and enables centralized marketing authorization procedures for novel enteral and parenteral nutrition adjuncts. Small and mid-cap biotechnology developers are responding by structuring Phase III protocols to satisfy both agencies simultaneously, compressing time-to-market for GLP-2 pipeline assets.
Consolidation among specialty infusion pharmacies is concentrating procurement leverage for high-cost parenteral nutrition formulations. Hospital outpatient departments are losing volume to independent home infusion providers as payers mandate site-of-care optimization programs. The behavioral shift is most visible in United States Medicare Advantage plans and comparable German Krankenkassen contracting arrangements, where capitated payment models reward ambulatory administration.
Short Bowel Syndrome Market Segmentation
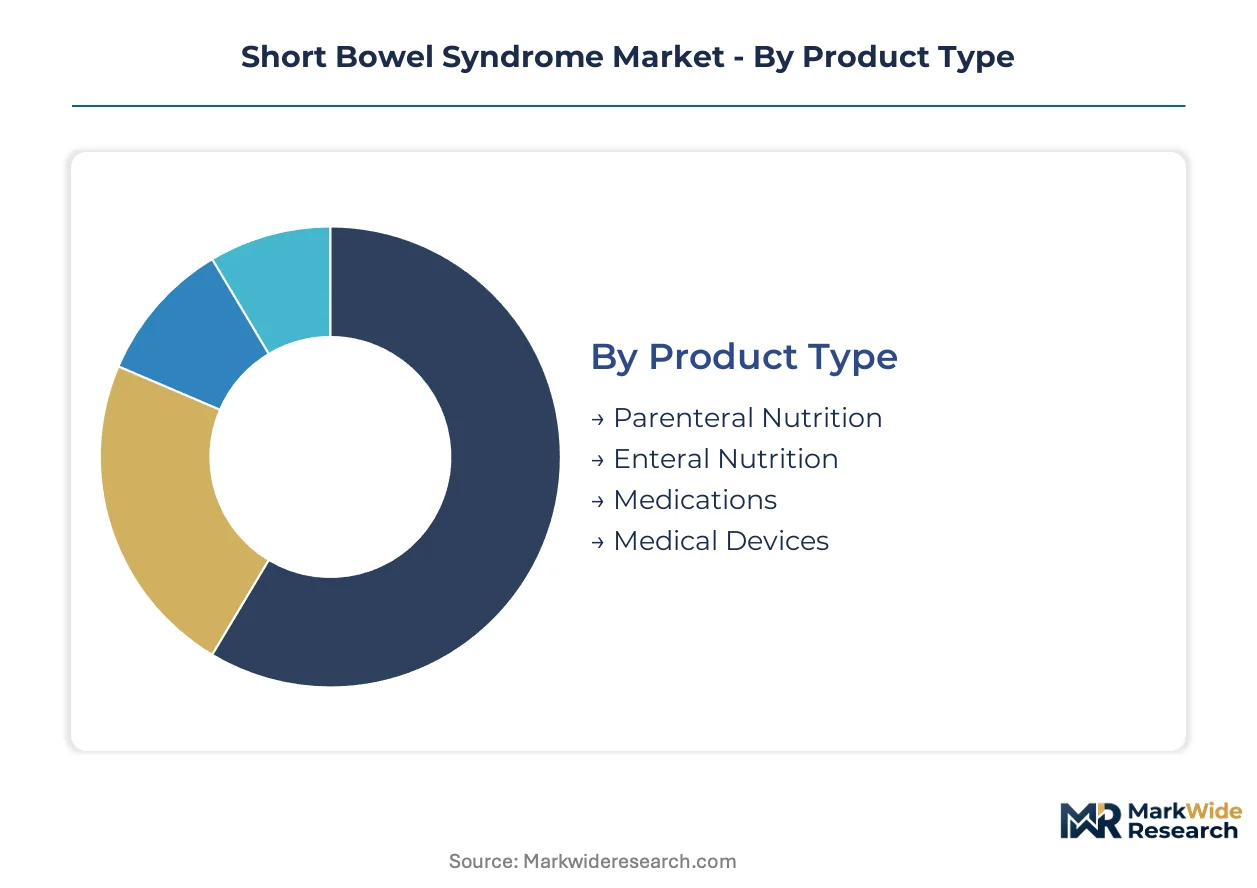
Segmentation in the Short Bowel Syndrome market reveals distinct procurement patterns across nutritional support modalities and care delivery settings. Understanding how product type, delivery mode, and end-user preferences diverge enables targeted positioning for GLP-2 therapies and parenteral formulations.
Product Type:
Buyers differentiate primarily by clinical dependency level and reimbursement intensity.
- Medications:GLP-2 receptor agonists and anti-secretory agents reduce parenteral nutrition dependency through enhanced intestinal adaptation. Demand concentrates among United States specialty pharmacies and academic medical centers with established intestinal rehabilitation programs, driven by FDA orphan drug exclusivity and Medicare Part D coverage for high-cost biologics.
- Parenteral Nutrition:Complete intravenous feeding formulations containing amino acids, dextrose, lipids, and micronutrients sustain patients with <100 cm residual small bowel. Homecare infusion providers in Germany and France now account for the majority of volume procurement, reflecting site-of-care optimization mandates from statutory health insurers.
- Enteral Nutrition:Polymeric and elemental formulas support patients with partial intestinal absorption capacity.
- Medical Devices:Central venous catheters, infusion pumps, and enteral feeding tubes enable chronic administration.
Parenteral nutrition leads volumes today; medications are gaining share fastest.
Delivery Mode:
Volume concentration tracks nursing workforce availability and patient self-administration capability.
- Subcutaneous:GLP-2 analogs administered via injection pen or syringe enable patient-directed therapy outside institutional settings. United States Medicare home health benefit expansions and comparable French HAS reimbursement approvals accelerate adoption among ambulatory patients with preserved manual dexterity.
- Intravenous:Parenteral nutrition requires central venous access for hypertonic solution delivery. Hospital outpatient departments in Japan and Australia retain substantial volume despite payer pressure, reflecting conservative clinical protocols and limited home infusion nursing density in rural prefectures and territories.
- Oral:Enteral nutrition formulas and electrolyte supplements serve patients with preserved gastrointestinal continuity.
- Enteral:Tube-delivered formulations bypass compromised upper digestive function.
Intravenous administration retains the largest volume footprint; subcutaneous delivery is expanding most quickly.
End User:
Margin profiles diverge sharply between institutional procurement and homecare reimbursement.
- Homecare:Independent infusion providers and durable medical equipment suppliers manage chronic parenteral nutrition for stable patients. United States Medicare Advantage plans and German Krankenkassen capitation models concentrate purchasing leverage among regional home infusion networks, compressing formulation margins while expanding patient census.
- Specialty Centers:Dedicated intestinal rehabilitation programs at Cleveland Clinic, King's College Hospital London, and Hopital Beaujon Paris coordinate multidisciplinary care for complex cases. These centers generate disproportionate influence over prescribing patterns for novel GLP-2 agents through protocol development and registry participation.
- Hospitals:Acute care facilities manage initial stabilization and surgical complications.
- Clinics:Outpatient gastroenterology practices monitor stable patients between hospitalizations.
Homecare leads current volume; specialty centers command the steepest expansion trajectory.
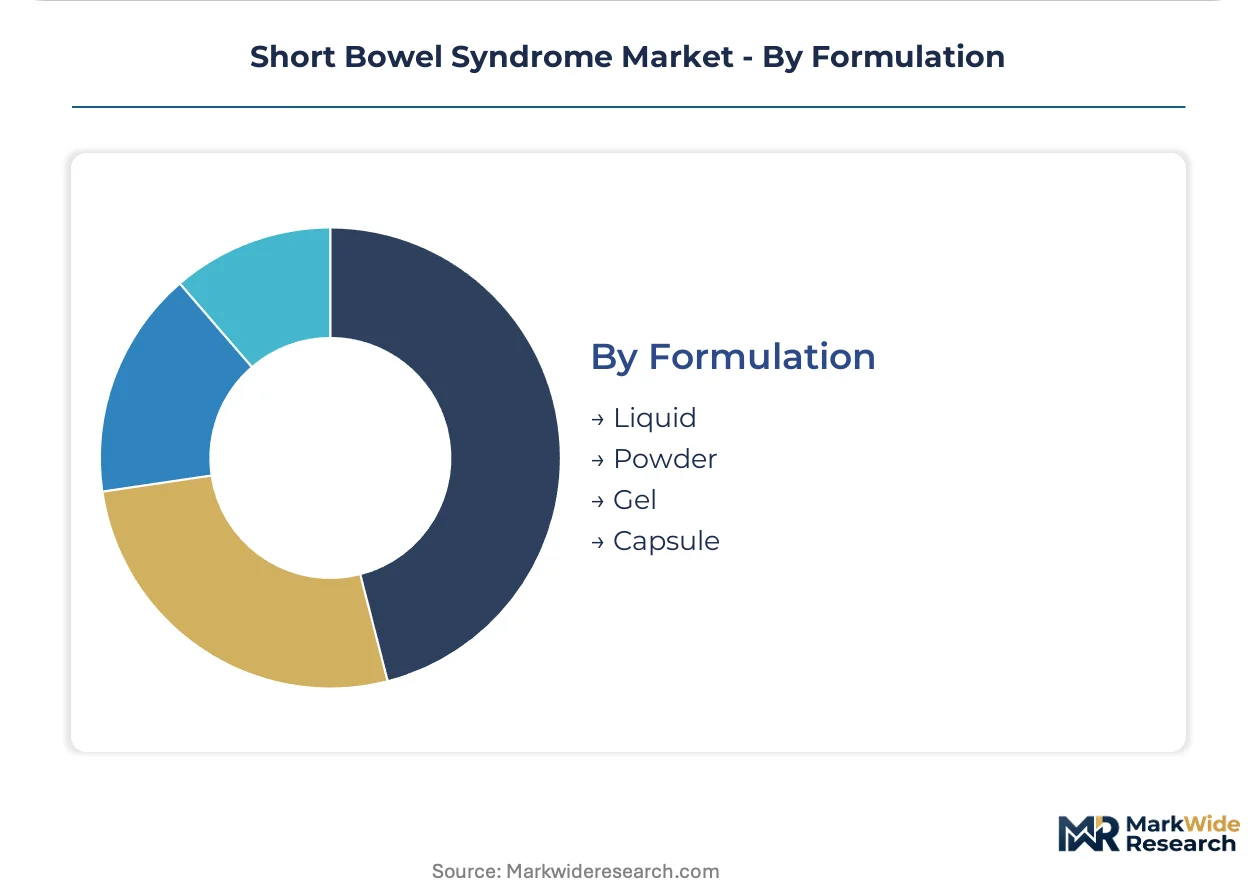
Formulation:
Supply chain configuration determines geographic availability and shelf-life constraints.
- Liquid:Ready-to-hang parenteral nutrition bags and pre-mixed enteral formulas reduce compounding labor and contamination risk. Manufacturers like Baxter and Fresenius Kabi operate regional sterile filling facilities in Illinois, Germany, and Singapore to minimize cold-chain distribution distances to hospital and homecare customers.
- Powder:Reconstitutable enteral nutrition products offer extended stability and reduced shipping weight. Australian and Canadian homecare programs favor powder formulations for remote patient populations, balancing caregiver burden against logistics cost advantages.
- Gel:Thickened enteral formulas address dysphagia and gastroesophageal reflux.
- Capsule:Solid-dose medications including anti-secretory agents and micronutrient supplements.
Liquid formulations dominate volume today; powder is climbing the fastest among ambulatory programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized intestinal rehabilitation nurses and home infusion pharmacists concentrate in the United States and Western Europe, anchoring patient access to parenteral nutrition and GLP-2 therapies. Their geographic clustering shapes where novel drug formulations achieve commercial traction first. This workforce distribution directly influences regional market development trajectories.
United States
Medicare Advantage capitation models and specialty pharmacy networks drive homecare adoption of parenteral nutrition and GLP-2 analogs. The FDA's orphan drug designation pathway accelerates clinical trial incentives for intestinal rehabilitation agents. Boston and Cleveland host leading intestinal failure centers that generate protocol influence and registry data for novel therapies.
Germany
Statutory health insurer Krankenkassen contracting mandates site-of-care optimization, shifting parenteral nutrition volume to independent home infusion providers. The EMA's parallel orphan designation harmonizes regulatory incentives with FDA frameworks for rare gastrointestinal disorders. The Rhine-Ruhr metropolitan region concentrates compounding pharmacy infrastructure serving ambulatory intestinal failure patients.
Japan
PMDA's sakigake designation pathway compresses review timelines for innovative intestinal rehabilitation therapies addressing unmet need. Conservative clinical protocols and limited home infusion nursing density in rural prefectures sustain hospital outpatient parenteral nutrition administration. Tokyo and Osaka academic medical centers coordinate multidisciplinary intestinal rehabilitation programs.
France
Haute Autorité de Santé reimbursement approvals for home parenteral nutrition enable patient discharge and chronic disease management outside institutional settings. The EMA centralized marketing authorization procedure facilitates pan-European market access for novel enteral and parenteral nutrition adjuncts. The Paris metropolitan region hosts Hopital Beaujon, a reference center influencing prescribing patterns across the national network.
Australia
Medicare Benefits Schedule provisions reimburse ambulatory parenteral nutrition delivery, supporting homecare infrastructure expansion for stable intestinal failure patients. The TGA's orphan drug framework provides fee waivers and priority review for therapies addressing rare gastrointestinal conditions. Sydney and Melbourne academic hospitals maintain intestinal rehabilitation programs that participate in international patient registries.
Short Bowel Syndrome Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the Short Bowel Syndrome therapeutic landscape, creating a tiered competitive structure. Large pharmaceutical companies leverage established rare disease infrastructure and GLP-2 therapy portfolios to anchor premium positioning. Mid-cap biotechnology developers differentiate through peptide engineering capabilities and next-generation intestinal rehabilitation pipelines. The dominant competitive moves include strategic partnerships for homecare distribution access and portfolio diversification into adjacent rare gastrointestinal disorders.
Within the diversified pharmaceutical tier, Takeda Pharmaceutical Company Limited occupies a position representing established GLP-2 therapy market presence. Zealand Pharma exemplifies the focused biotechnology archetype through differentiated peptide engineering specialization. Ironwood Pharmaceuticals sits within the mid-cap developer segment addressing gastrointestinal and rare disease indications.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Zealand Pharma |
| Ironwood Pharmaceuticals |
| OxThera |
| Ardelyx |
| VectivBio |
| Hanmi Pharmaceutical |
| Nestlé Health Science |
| Nutricia |
| Others |
Value Chain & Pricing Dynamics
Homecare procurement consolidation among United States Medicare Advantage plans and German Krankenkassen is compressing formulation margins and forcing manufacturers toward regional sterile filling investments that reshape cost structures across parenteral nutrition and GLP-2 analog supply.
Pricing Analysis
Capacity additions in Singapore and Germany are reshaping price floors for sterile parenteral nutrition compounding. Three-tier pricing structure across premium biologic GLP-2 therapies, standard amino acid formulations, and economy lipid emulsions dominates procurement negotiations. Price differentiation hinges on FDA orphan drug exclusivity status and homecare nursing bundling depth. Cost compression in standard parenteral formulations is intensifying because statutory health insurers mandate site-of-care shifts. Homecare infusion providers exhibit highest price sensitivity; academic intestinal rehabilitation centers show lowest.
Supply Chain Analysis
USP <797> sterile compounding certification and EMA GMP qualification requirements gate regional supply participation, favoring capital-intensive cleanroom operators. Manufacturing concentrates in the United States, Germany, and Singapore. Production draws from fetal bovine serum, single-use bioreactor components, and specialized peptide growth media. Single-source vulnerability in mammalian cell culture systems threatens continuity. Distribution runs through specialty infusion pharmacy networks and hospital outpatient procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Short Bowel Syndrome market compounds steadily as chronic patient survival requirements sustain perpetual demand for parenteral nutrition and intestinal rehabilitation pharmacotherapy.
For Market Incumbents: To counter enteral nutrition substitution in patients with residual bowel exceeding 100 centimeters, Takeda and Zealand Pharma should deepen backward integration into peptide manufacturing and secure exclusive homecare distribution partnerships with top-ten United States specialty infusion networks. FDA real-world evidence pathway investment accelerates label expansion against emerging long-acting depot threats. For New Entrants and Emerging Players: Capture the pediatric congenital short bowel segment in Japan and Australia where PMDA sakigake and TGA orphan frameworks compress regulatory timelines. Telehealth-integrated monitoring platforms represent the most penetrable white-space, enabling remote catheter surveillance and metabolic complication prevention. Partner with established intestinal rehabilitation centers for protocol development and registry enrollment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotechnology developers possessing differentiated peptide engineering capabilities and Phase II GLP-2 assets. Five-to-ten year viability rests on pipeline durability and regulatory exclusivity runway. Watch FDA guidance evolution on real-world evidence submissions as the inflection signal for accelerated approval timelines and valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity compresses competitive entry timelines for novel GLP-2 candidates. |
| Homecare Distribution Partnership | Specialty infusion pharmacy alliances secure patient census under Medicare Advantage capitation. |
| Pediatric Indication Development | Congenital short bowel in neonates addresses unmet need with distinct pharmacokinetic protocols. |
| Real-World Evidence Infrastructure | Patient registry participation enables post-market surveillance and label expansion acceleration. |
| Peptide Manufacturing Scale-Up | In-house recombinant production reduces fetal bovine serum cost volatility exposure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged intestinal rehabilitation program directors, home infusion pharmacy procurement managers, payer access specialists at Medicare Advantage plans, and regulatory affairs leads at GLP-2 developers. Secondary validation drew from FDA orphan drug designations, EMA centralized marketing authorization procedures, ClinicalTrials.gov entries, and CMS durable medical equipment reimbursement coding. Bottom-up patient census modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Historical reference periods spanning pre-orphan drug exclusivity through current GLP-2 penetration established baseline trajectories for projection. Segmentation modeling addressed product type, delivery mode, end-user setting, and regional regulatory cluster across the analysis window. CAGRs derived from patient prevalence epidemiology, treatment guideline evolution, and reimbursement stability indices. Forecast inputs incorporated parenteral nutrition dependency duration and intestinal adaptation pharmacotherapy penetration curves.
Regulatory guidance revision, reimbursement coding disruption, and biologic input cost shocks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on patient survival improvement and homecare infrastructure expansion rates. A model refresh is warranted upon material change in FDA real-world evidence submission requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Zygomycosis Treatments Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Mucinoses Management Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Mucous Membrane Pemphigoid Treatment Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Global Cryptococcosis Treatment Market