
 Botulism Treatment Market | 2026-2036
Botulism Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Botulism Treatment Market Analysis
Hospital procurement channels for botulism countermeasures is fragmenting as regional health systems develop direct sourcing relationships with antitoxin manufacturers. Emergent BioSolutions anchors the landscape through its established government contracting infrastructure for medical countermeasures. XOMA Corporation competes via its monoclonal antibody pipeline targeting botulinum neurotoxin subtypes. Merz Pharma differentiates through its specialized neurology portfolio and European hospital networks.
Botulism treatment encompasses antitoxin neutralization of circulating botulinum neurotoxin, antibiotic eradication of Clostridium botulinum colonization, and mechanical ventilation for respiratory paralysis; equine-derived heptavalent antitoxin remains the primary intervention with human-derived alternatives under development for reduced hypersensitivity risk. The antitoxin segment dominates value capture due to high production costs and limited manufacturing sources, while the intravenous delivery mode leads procedure volumes in emergency settings. Supportive care occupies expanding share as prolonged intensive care stays generate ancillary revenue streams for hospitals.
FDA biologics licensing requirements and CDC Strategic National Stockpile specifications shape product development priorities and procurement eligibility for domestic manufacturers. EMA orphan drug incentives and the EU Health Emergency Preparedness and Response Authority framework influence European development timelines and cross-border distribution protocols. Stakeholders must monitor evolving biodefense funding appropriations and pandemic preparedness restructuring to anticipate shifts in government purchasing behavior and stockpile refresh cycles.
Market Dynamics
CDC stockpile refresh cycles and biodefense procurement reforms are compressing manufacturer planning horizons while tightening antitoxin shelf-life requirements. The heptavalent antitoxin supply chain operates under single-source concentration risk, with equine plasma dependency creating biological input vulnerability.
Growth Catalysts
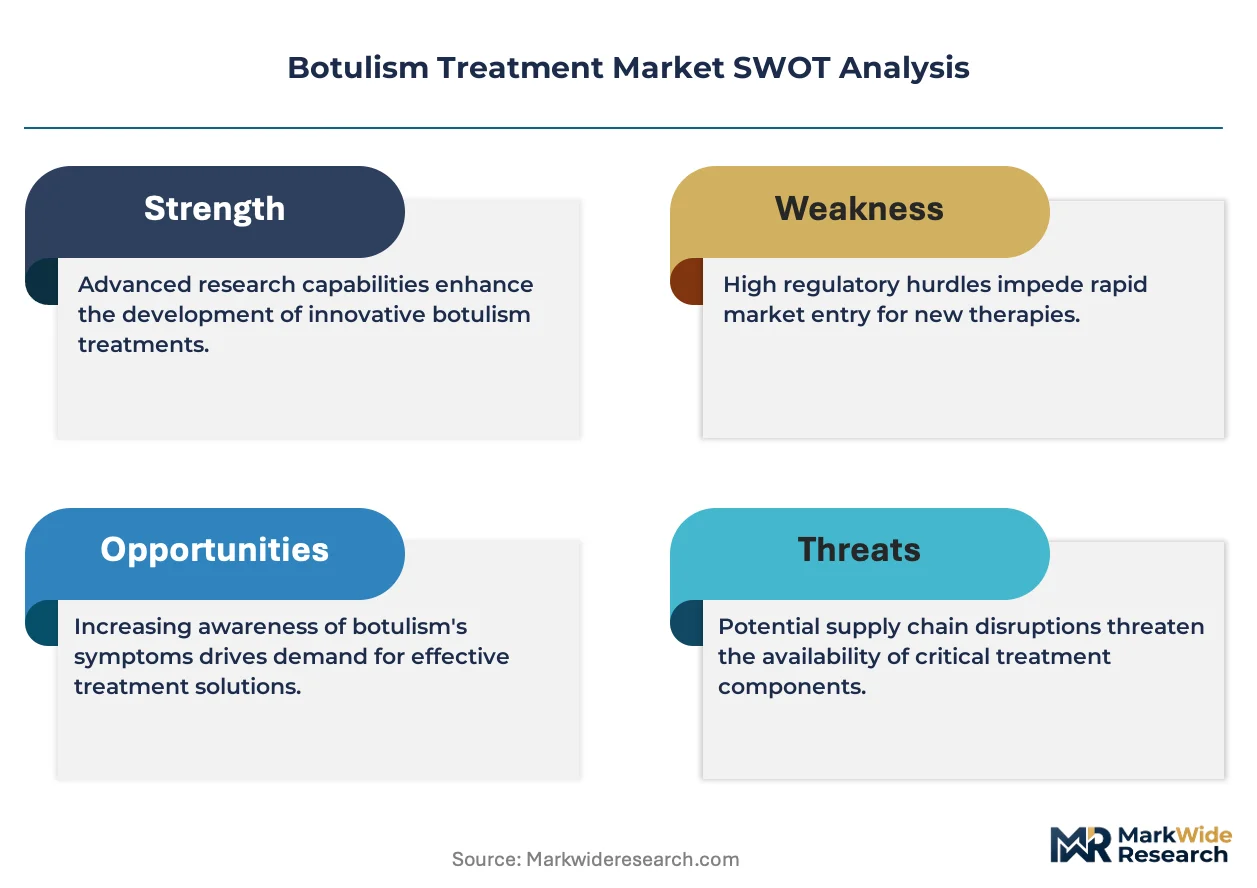
- Strategic National Stockpile mandates:US federal procurement guarantees minimum volume commitments for domestic antitoxin manufacturers, de-risking production capacity investments.
- Equine plasma fractionation advances:Improved immunoglobulin purification yields are expanding per-batch antitoxin output without proportional herd expansion.
- Foodborne surveillance expansion:Enhanced CDC PulseNet detection protocols are shortening outbreak-to-treatment intervals, accelerating antitoxin deployment velocity.
Market Restraints
- Biological input scarcity:Hyperimmunized horse herd maintenance costs constrain plasma collection economics, with veterinary labor shortages compounding breeding program delays.
- Manufacturing site concentration:Domestic heptavalent antitoxin production centers on a single FDA-licensed facility, creating catastrophic supply interruption exposure.
- Hypersensitivity liability:Equine protein immunogenicity necessitates desensitization protocols that extend emergency department treatment timelines.
Strategic Opportunities
- Recombinant monoclonal antibodies:Cell-culture production platforms eliminate equine dependency while enabling subtype-specific neutralization cocktails.
- EMA orphan drug exclusivity:European pediatric indication extensions offer seven-year market protection for human-derived antitoxin alternatives.
- Direct hospital contracting:Bypassing group purchasing organizations allows manufacturers to capture specialty pharmacy margin in tier-one trauma centers.
Industry Challenges
- Cold chain integrity maintenance:Antitoxin stability requirements demand uninterrupted -20°C storage from production through emergency deployment, with rural hospital infrastructure gaps creating wastage risk.
- Clinical trial recruitment scarcity:Botulism incidence rates below 200 annual US cases necessitate adaptive trial designs and historical control arm reliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botulism Treatment Market |
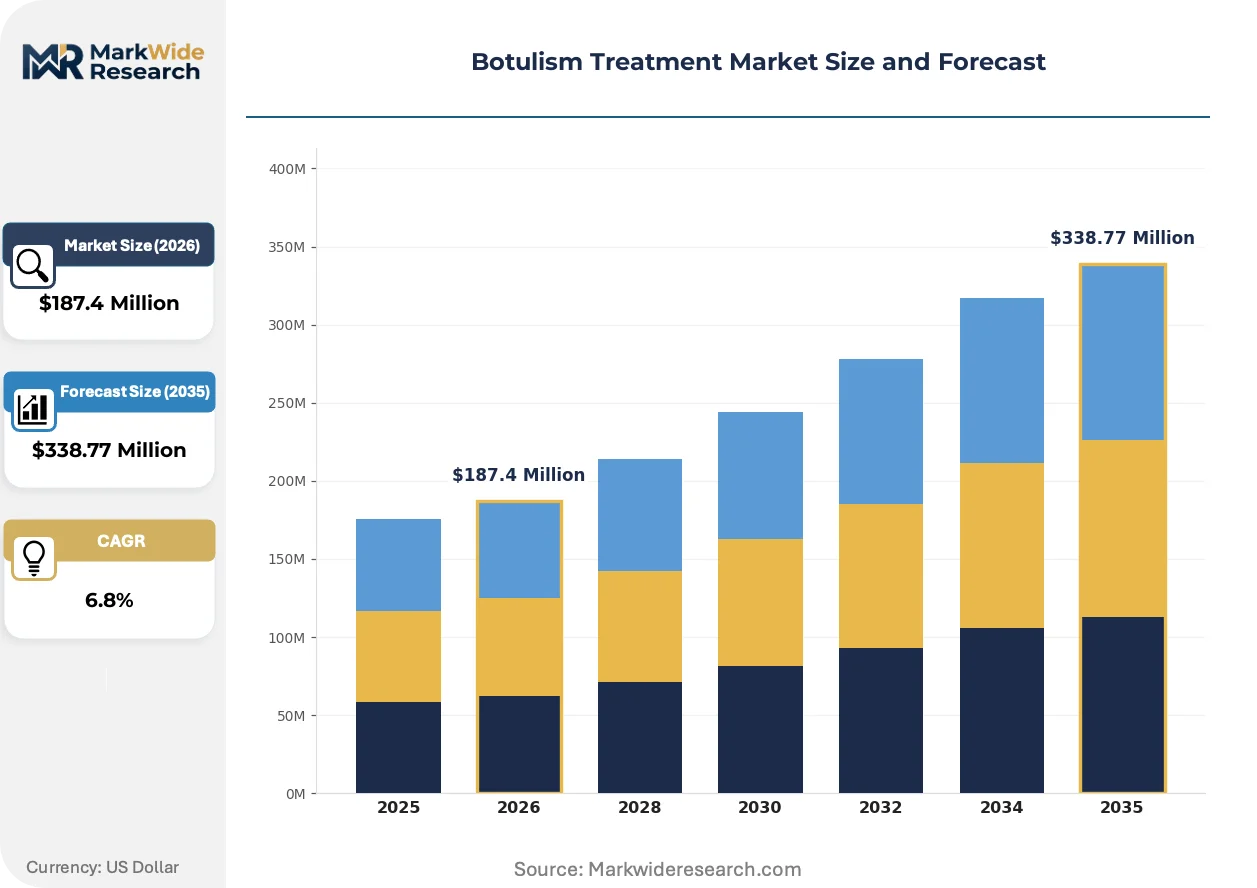
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antitoxin, Antibiotics, Supportive Care, Vaccines Therapy Area: Neurology, Infectious Diseases, Emergency Medicine, Critical Care End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Delivery Mode: Intravenous, Intramuscular, Oral, Inhalation |
| Companies Covered | XOMA Corporation, Microbiotix, Bausch Health Companies Inc, Eisai Inc., Merz Pharma, Galderma, AbbVie Inc., Molecular Targeting Technologies, Inc., Emergent BioSolutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botulism Treatment Market Emerging Trajectories
Antitoxin manufacturing is pivoting from plasma-dependent extraction toward recombinant expression systems, with regulatory science lagging behind molecular engineering capabilities. This transition is compressing development timelines while expanding therapeutic specificity.
Recombinant monoclonal antibody platforms are virtualizing traditional antitoxin production by replacing equine immunization with yeast and mammalian cell culture expression. Biodefense contractors are adopting these systems to reduce biological supply risk. The shift is virtualizing century-old plasma fractionation infrastructure while enabling rapid subtype-specific formulation.
FDA's Animal Rule pathway for highly lethal toxins is compressing clinical evidence requirements for new antitoxin candidates, permitting efficacy extrapolation from animal challenge studies. This regulatory flexibility is accelerating IND-to-BLA timelines for recombinant alternatives. Manufacturers are responding with enhanced non-human primate model investments to satisfy immunogenicity benchmarks.
Hospital emergency departments are consolidating antitoxin procurement through regional health system formularies, displacing individual facility stockpiling. This concentration is forcing manufacturers toward direct contracting relationships with integrated delivery networks. The pattern is most visible in Texas and California, where multi-hospital systems coordinate biodefense materiel allocation.
Botulism Treatment Market Segmentation
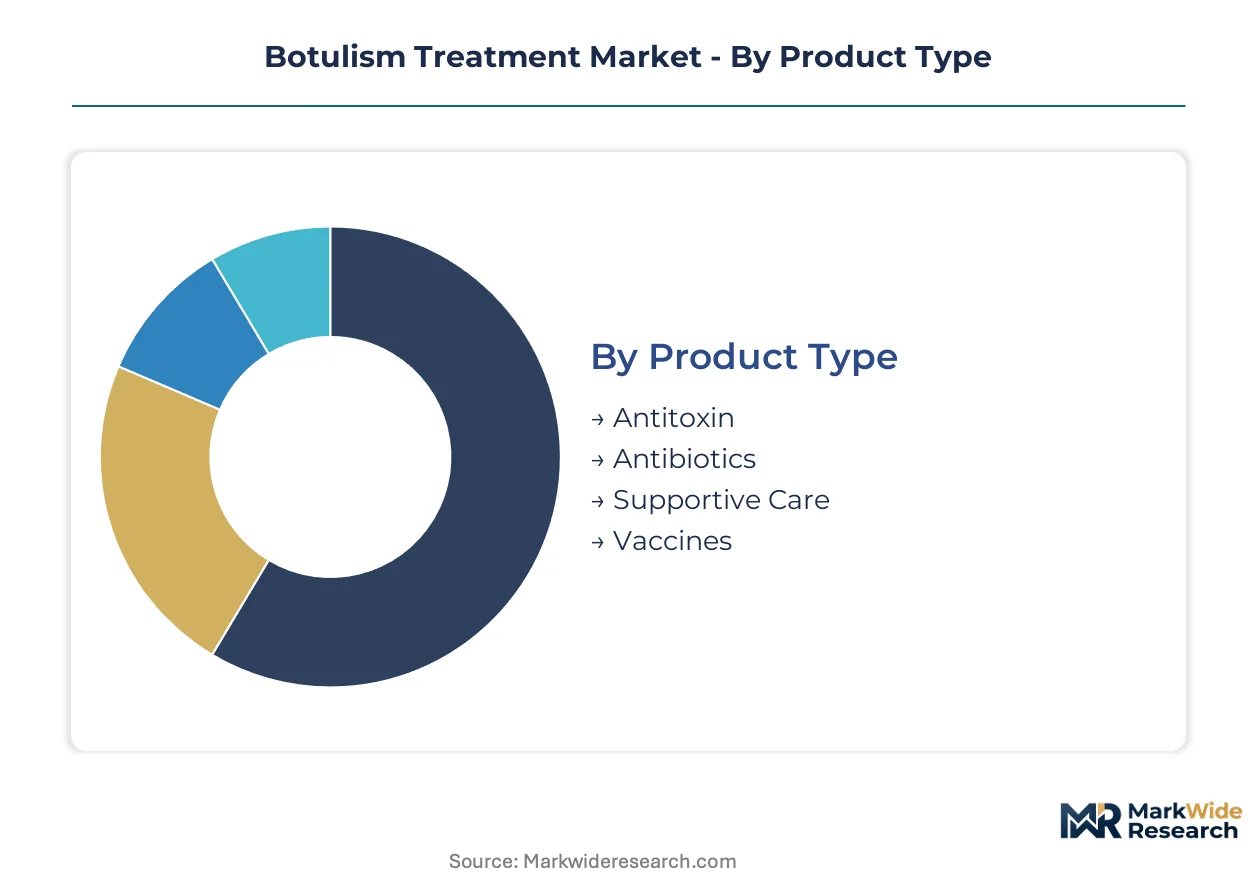
Botulism treatment segmentation reveals distinct procurement patterns across acute care settings. Each category reflects divergent reimbursement pathways, cold-chain requirements, and clinical decision hierarchies that shape manufacturer go-to-market strategies.
Product Type:
After-sales service intensity varies sharply across product categories, with antitoxin requiring 24/7 emergency deployment support while antibiotics rely on standard pharmaceutical distribution.
- Antitoxin:Equine-derived heptavalent formulations neutralize circulating botulinum neurotoxin through immunoglobulin binding. Demand concentrates in CDC Strategic National Stockpile procurement and tier-one trauma centers, driven by biodefense preparedness mandates and outbreak response protocols.
- Antibiotics:Metronidazole and penicillin derivatives eradicate Clostridium botulinum colonization in wound and infant botulism cases. Hospital pharmacies in the United States anchor volume, constrained by narrow therapeutic windows and the need for concurrent antitoxin administration.
- Supportive Care:Mechanical ventilation and intensive care monitoring address respiratory paralysis complications.
- Vaccines:Investigational toxoid formulations target laboratory workers and military personnel with occupational exposure risk.
Antitoxin holds the largest share; momentum sits with supportive care as prolonged ICU stays expand ancillary revenue capture.
Therapy Area:
Cost tier stratification separates emergency intervention from chronic management, with neurology commanding premium pricing for antitoxin administration.
- Neurology:Specialized neurotoxin reversal protocols and electromyographic monitoring define clinical workflows. Academic medical centers in Germany and the United States drive adoption, pressured by EMA orphan drug incentives and FDA biologics licensing requirements.
- Infectious Diseases:Outbreak investigation and source tracing integrate treatment with public health surveillance. CDC PulseNet laboratories coordinate specimen analysis, accelerating antitoxin deployment velocity through shortened diagnostic intervals.
- Emergency Medicine:Rapid differential diagnosis and airway stabilization dominate frontline intervention.
- Critical Care:Prolonged ventilator dependence and autonomic dysfunction management extend treatment duration.
Neurology commands premium reimbursement; critical care exhibits steepest expansion trajectory as ICU capacity investments deepen.
End User:
Customer type fragmentation distinguishes centralized stockpile procurement from decentralized hospital purchasing, with divergent contract terms and logistics requirements.
- Hospitals:Emergency departments and intensive care units manage acute presentation and respiratory failure. Integrated delivery networks in Texas and California consolidate formulary decisions, displacing individual facility procurement through regional coordination mechanisms.
- Clinics:Outpatient recognition of early botulism symptoms triggers referral pathways. Federally qualified health centers in rural United States face cold-chain infrastructure gaps that compromise antitoxin storage integrity.
- Rehabilitation Centers:Post-acute neuromuscular recovery and physical therapy address residual paralysis.
- Home Care:Infant botulism supportive feeding and respiratory monitoring extend into domestic settings.
Hospitals dominate volume; home care is climbing the fastest as pediatric indication extensions expand reimbursement eligibility.
Delivery Mode:
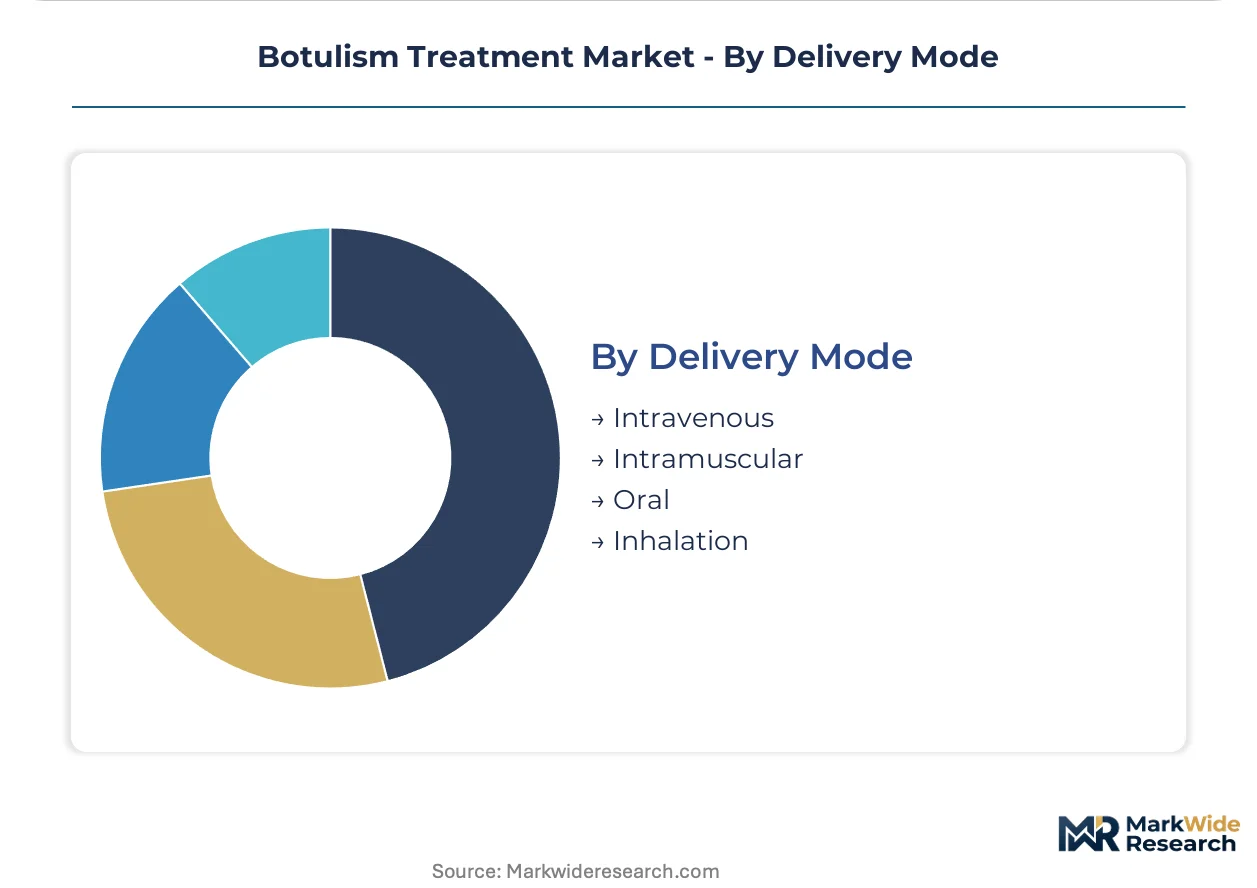
Supply concentration in intravenous formulations reflects emergency administration requirements and bioavailability considerations for large-molecule antitoxins.
- Intravenous:Rapid systemic distribution of antitoxin immunoglobulin neutralizes circulating neurotoxin before neuronal uptake. Emergency departments across the United States standardize IV access protocols, constrained by hypersensitivity risk requiring desensitization readiness.
- Intramuscular:Alternative administration for specific antitoxin formulations and antibiotic depot injections. Military field medical units and remote deployment settings favor this modality where IV infrastructure proves impractical.
- Oral:Antibiotic bioavailability for gastrointestinal Clostridium botulinum eradication.
- Inhalation:Investigational delivery for recombinant monoclonal antibody platforms targeting respiratory exposure scenarios.
Intravenous holds the largest share; inhalation represents the fastest-growing trajectory as recombinant manufacturing platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement premiums exceed European hospital pricing by margins reflecting CDC stockpile commitments and biodefense urgency. German manufacturers capture value through EMA orphan drug pathways. Japanese demand concentrates in metropolitan emergency networks with specialized neurotoxin preparedness.
United States
CDC Strategic National Stockpile mandates drive volume commitments through single-source contracting mechanisms. FDA biologics licensing requirements tighten manufacturing standards for heptavalent antitoxin production. Texas and California integrated delivery networks consolidate regional formulary decisions, displacing individual hospital procurement through coordinated biodefense materiel allocation.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor neurology-specialized antitoxin administration with electromyographic monitoring protocols. EMA orphan drug incentives accelerate pediatric indication development timelines for human-derived alternatives. Berlin-Brandenburg hosts regulatory science clusters advancing recombinant monoclonal antibody platform validation.
Japan
Metropolitan emergency departments in Tokyo and Osaka standardize rapid differential diagnosis protocols for foodborne outbreak response. PMDA consultation pathways compress review timelines for biodefense countermeasure candidates. Kansai region hospitals invest in cold-chain infrastructure supporting antitoxin stability requirements.
Switzerland
Swissmedic oversight of biological products maintains manufacturing quality benchmarks for European distribution. Basel and Zurich hospital networks coordinate cross-border antitoxin sharing protocols with neighboring jurisdictions. Alpine region logistics providers specialize in uninterrupted -20°C storage for emergency deployment.
United Kingdom
London and Southeast England concentrate specialist neurology referral capacity for wound botulism cases linked to injection drug use. MHRA recognition of FDA-approved antitoxins accelerates emergency use authorization pathways. Midlands regional health systems develop direct sourcing relationships bypassing national procurement frameworks.
Botulism Treatment Market Vendor Landscape
Biodefense contractors and specialized neurology pharmaceutical firms split the market along procurement channel lines. The vendor base concentrates around government contracting infrastructure and hospital network penetration capabilities. Three strategic archetypes dominate: plasma-dependent antitoxin manufacturers, recombinant monoclonal antibody developers, and diversified neurology portfolio holders. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for stockpile refresh cycles and recombinant platform transitions.
Within the biodefense contracting tier, Emergent BioSolutions anchors government procurement relationships through established medical countermeasure infrastructure. XOMA Corporation occupies a position exemplifying recombinant monoclonal antibody platform development for subtype-specific neutralization. Merz Pharma represents the neurology-specialized archetype with European hospital network penetration. These three entities collectively illustrate the competitive segmentation between federal stockpile dependence, molecular engineering advancement, and clinical specialty channel access.
| Leading Market Players |
|---|
| XOMA Corporation |
| Microbiotix |
| Bausch Health Companies Inc |
| Eisai Inc. |
| Merz Pharma |
| Galderma |
| AbbVie Inc. |
| Molecular Targeting Technologies, Inc. |
| Emergent BioSolutions |
| Others |
Supply Flow & Price Mechanics
Memphis-to-Bethesda cold-chain freight corridors absorb disproportionate logistics cost premiums, compressing margins for plasma-dependent manufacturers while amplifying price differentiation between CDC stockpile contracts and spot hospital procurement. This freight-cost asymmetry reinforces single-source supplier dominance and widens the spread between emergency deployment pricing and standard pharmaceutical distribution.
Pricing Analysis
The customization-premium spread separates CDC-configured bulk antitoxin lots from standard hospital vial packaging, with the former capturing volume-commitment discounts and the latter bearing per-unit cold-chain surcharges. Price differentiation rests on biodefense certification tier and equine plasma batch traceability grade. Pricing pressure stems from recombinant monoclonal antibody competition threatening to commoditize traditional plasma-derived products. Government stockpile buyers exhibit lowest price sensitivity; tier-two rural hospitals face acute budget constraints.
Supply Chain Analysis
Supplier-financing facilities from specialized healthcare logistics providers extend payment terms for plasma fractionation inputs, easing working capital burdens on hyperimmunized horse herd operators. Geographic supply concentration centers on the United States, Germany, and Switzerland for fractionation capacity. Raw material dependencies include equine plasma, chromatography resins, and cryopreservation excipients. Single-source manufacturing site vulnerability constitutes the dominant structural risk. Distribution runs through CDC Strategic National Stockpile depots and direct hospital contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as recombinant monoclonal antibody manufacturing virtualizes century-old plasma infrastructure, with interoperability between cell-culture expression systems and existing biodefense logistics networks determining competitive survival.
For Market Incumbents: Harden plasma supply security through captive equine herd investments in Kentucky and Tennessee, insulating against veterinary labor shortages threatening biological input flows. Accelerate recombinant platform licensing to FDA before animal-rule exclusivity windows narrow. Lock in multi-year CDC stockpile refresh commitments ahead of congressional appropriation cycles. For New Entrants and Emerging Players: Establish a beachhead in European pediatric indication extensions, where EMA orphan drug pathways offer seven-year market protection absent in mature US procurement channels. Target German academic medical centers with electromyographic monitoring integration capabilities. Lead with human-derived antitoxin alternatives to bypass equine hypersensitivity liability. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical parents with neglected biodefense countermeasure divisions lacking government contracting infrastructure. Long-term viability favors recombinant platform operators with cell-culture scale-up capabilities over plasma-dependent legacy assets. Watch FDA biologics licensing timeline compression as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Manufacturing Scale-Up | Cell-culture platforms eliminate equine plasma dependency while enabling subtype-specific neutralization cocktails. |
| FDA Animal Rule Pathway Navigation | Accelerated approval timelines compress IND-to-BLA intervals for lethal-toxin countermeasures. |
| Strategic National Stockpile Partnership | Direct CDC contracting secures volume commitments and de-risks capacity investments. |
| EMA Orphan Drug Exclusivity Pursuit | Seven-year market protection in pediatric indications blocks competitor entry. |
| Integrated Delivery Network Direct Contracting | Bypassing GPOs captures specialty pharmacy margin in tier-one trauma centers. |
Methodological Framework
Operator-level perspectives from equine plasma collection facility managers, CDC stockpile procurement officers, hospital formulary directors, and recombinant platform manufacturing executives anchored the qualitative base. Secondary validation drew from FDA biologics licensing files, EMA orphan drug designation records, CDC Strategic National Stockpile inventory disclosures, and hospital GPO contract databases. Bottom-up antitoxin production volume estimates triangulated against top-down biodefense appropriation flows.
Scenario-bracketing framed projections across stockpile refresh cycle timing and recombinant platform adoption velocity. Segmentation dimensions spanned product type, therapy area, end user category, and delivery mode. CAGRs were derived from production capacity buildout trajectories and procurement commitment visibility. Forecast inputs included equine herd population trends and cell-culture yield improvement curves.
Stress conditions across plasma supply disruption, regulatory approval delays, and recombinant manufacturing scale-up failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from biodefense funding volatility or technological substitution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Transthyretin Amyloidosis Treatment Market
Specialty Medicine
Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market