
 Congenital Neutropenia Treatment Market | 2026-2036
Congenital Neutropenia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Congenital Neutropenia Treatment Market Outlook
Pediatric hospitals are decoupling from general hematology wards into dedicated neutropenia treatment centers. Amgen leverages decades of G-CSF manufacturing scale to anchor North American supply. Spectrum Pharmaceuticals competes through specialized oncology and hematology channel control. BeyondSpring Pharmaceuticals positions its pipeline assets toward severe congenital neutropenia subsets.
Congenital neutropenia treatment encompasses therapeutic interventions for rare inherited disorders marked by persistently low absolute neutrophil counts below 500 cells per microliter, primarily using recombinant human granulocyte colony-stimulating factor to stimulate myeloid progenitor cell proliferation and reduce infection frequency. The primary purpose centers on preventing life-threatening bacterial and fungal infections while maintaining quality of life in pediatric and adult patients. Granulocyte colony-stimulating factor occupies the dominant revenue pool due to established reimbursement and chronic administration patterns, while gene therapy segments attract R&D capital despite clinical immaturity. Pediatric hospitals concentrate the highest procedure volumes and longest patient relationships across all technology categories.
The FDA's orphan drug designation framework and EMA's pediatric investigation plan requirements shape trial enrollment criteria and exclusivity timelines for developers. Health Canada's Special Access Programme and Japan's PMDA sakigake designation create parallel regulatory pathways that influence multinational clinical strategy. Stakeholders must monitor emerging gene therapy readouts and stem cell therapy durability data to recalibrate portfolio priorities ahead of label expansions.
Market Dynamics
The congenital neutropenia treatment landscape is restructuring around chronic G-CSF administration economics and the impending commercialization of gene therapies that threaten to displace decades of recombinant protein dependency.
Growth Catalysts
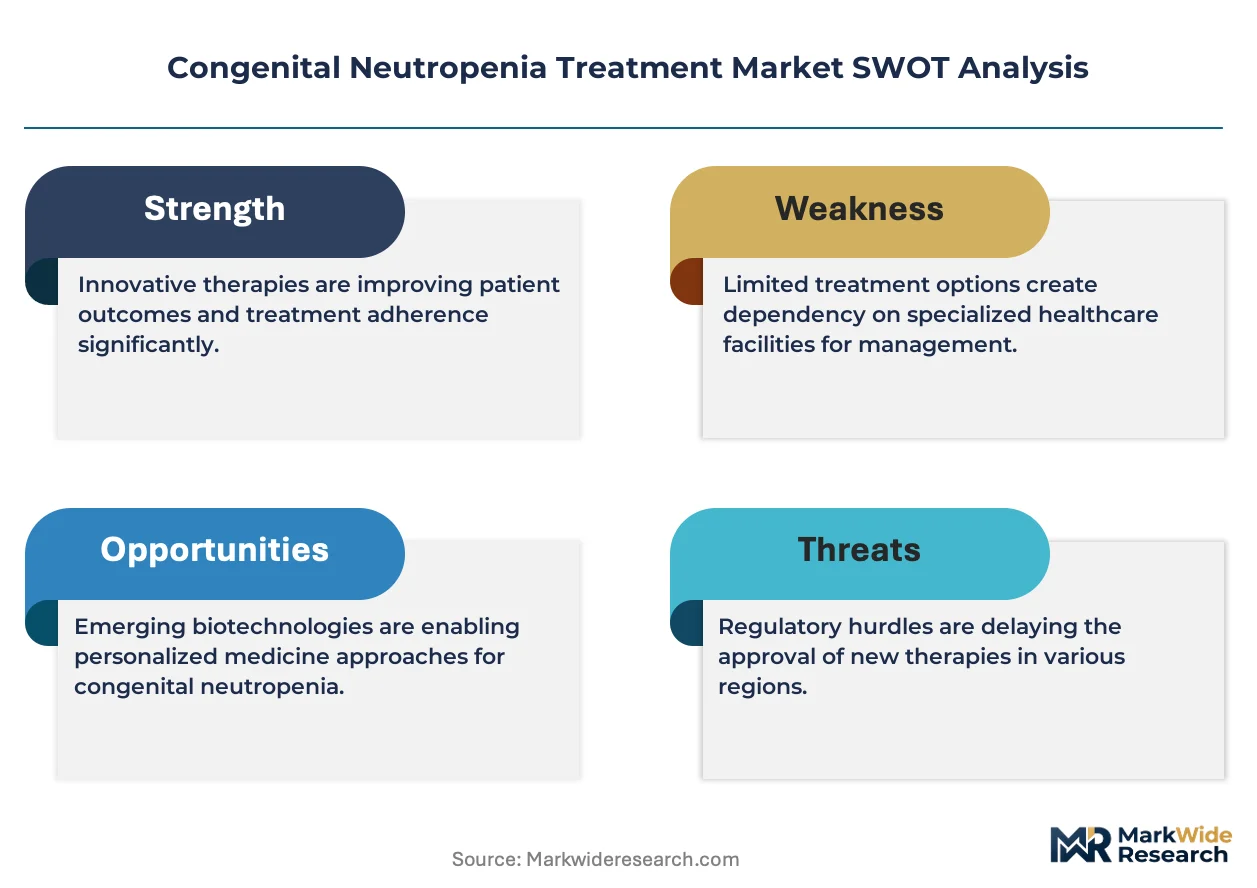
- FDA Orphan Drug Incentives:Tax credits for clinical trial costs and seven-year market exclusivity accelerate developer entry into severe congenital neutropenia subsets previously deemed commercially unviable.
- Pediatric Hospital Expansion:Dedicated neutropenia care units in tertiary children's hospitals concentrate patient volumes and extend treatment adherence monitoring beyond standard oncology protocols.
- Granulocyte Colony-Stimulating Factor Manufacturing Scale:Decades of process optimization in recombinant protein production have collapsed per-dose costs and enabled daily administration regimens.
Market Restraints
- Recombinant Protein Input Concentration:Active pharmaceutical ingredient supply for G-CSF concentrates among three contract manufacturing organizations, creating single-source vulnerability for chronic therapy supply.
- Gene Therapy Manufacturing Complexity:Lentiviral vector production requires dedicated cleanroom infrastructure that limits contract development and manufacturing organization capacity and extends lead times.
- EMA Pediatric Investigation Plan Compliance Burden:Mandatory pediatric study requirements for all new molecular entities extend development timelines by 18-24 months regardless of adult indication priority.
Strategic Opportunities
- Japan's PMDA Sakigake Designation:Priority review and dedicated consultation pathways for regenerative medicines compress regulatory timelines for gene therapy developers targeting severe congenital neutropenia.
- Stem Cell Therapy Durability Data:Emerging allogeneic hematopoietic stem cell approaches promise single-intervention cures that would eliminate chronic G-CSF dependency and capture lifetime value.
- Direct-to-Patient Specialty Pharmacy Channels:Cold-chain logistics specialization enables home administration of temperature-sensitive biologics, reducing hospital burden and improving adherence.
Industry Challenges
- Gene Therapy Vector Manufacturing Talent Scarcity:Lentiviral production expertise concentrates among a narrow cohort of process development scientists, constraining capacity expansion.
- Cross-Border Reimbursement Harmonization:Divergent health technology assessment criteria between Germany's IQWiG and France's HAS complicate parallel market access for novel therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congenital Neutropenia Treatment Market |
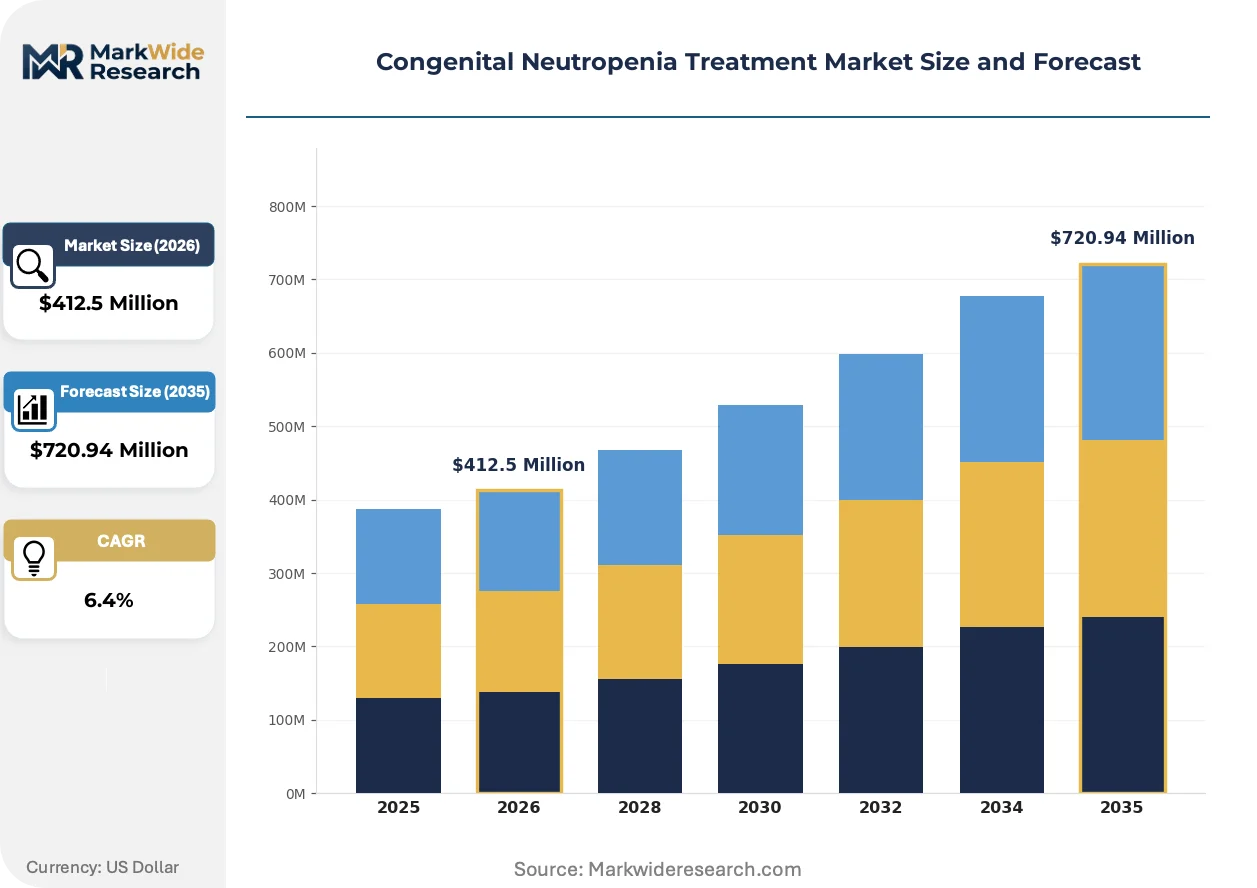
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulocyte Colony-Stimulating Factor, Antibiotics, Immunoglobulin Therapy, Bone Marrow Transplant End User: Pediatric Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes Technology: Gene Therapy, Stem Cell Therapy, Immunotherapy, Pharmacological Therapy Application: Infection Management, Immune Support, Hematological Restoration, Clinical Trials |
| Companies Covered | Amgen, Spectrum Pharmaceuticals, BeyondSpring Pharmaceuticals, Myelo Therapeutics, Cellerant Therapeutics, Generon, Sandoz, Biocon Biologics, Kyowa Kirin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congenital Neutropenia Treatment Market Strategic Shifts
Gene therapy platforms are overtaking recombinant protein maintenance regimens as the focal point of R&D investment, while regulatory frameworks and care delivery models adapt to accommodate curative intent rather than chronic management.
Lentiviral vector-based gene therapy is overtaking plasmid electroporation approaches for hematopoietic stem cell modification in severe congenital neutropenia. Academic medical centers in the United States and Germany are establishing dedicated gene therapy infusion units with 18-month patient follow-up protocols. This technology is overtaking the historical standard of lifetime G-CSF administration by promising single-treatment cures that eliminate neutropenic infection risk.
The EMA's Advanced Therapy Medicinal Products framework is accelerating centralized marketing authorization pathways for gene and cell therapies while imposing manufacturing quality standards that exceed conventional biologics. Developers must demonstrate vector copy number consistency and insertional mutagenesis risk mitigation to secure approval. Pediatric hematology centers across France, Italy, and Spain are restructuring pharmacy operations to accommodate ATMP storage and handling requirements.
Specialized neutropenia clinics are consolidating previously fragmented care across infectious disease, hematology, and genetics disciplines into single-visit multidisciplinary models. Children's hospitals in the United States are unbundling after-hours fever management from emergency departments into dedicated neutropenia hotlines staffed by hematology nurse practitioners. This reorganization is most visible in Boston, Cincinnati, and Seattle where pediatric hematology volumes justify dedicated infrastructure.
Congenital Neutropenia Treatment Market Segmentation
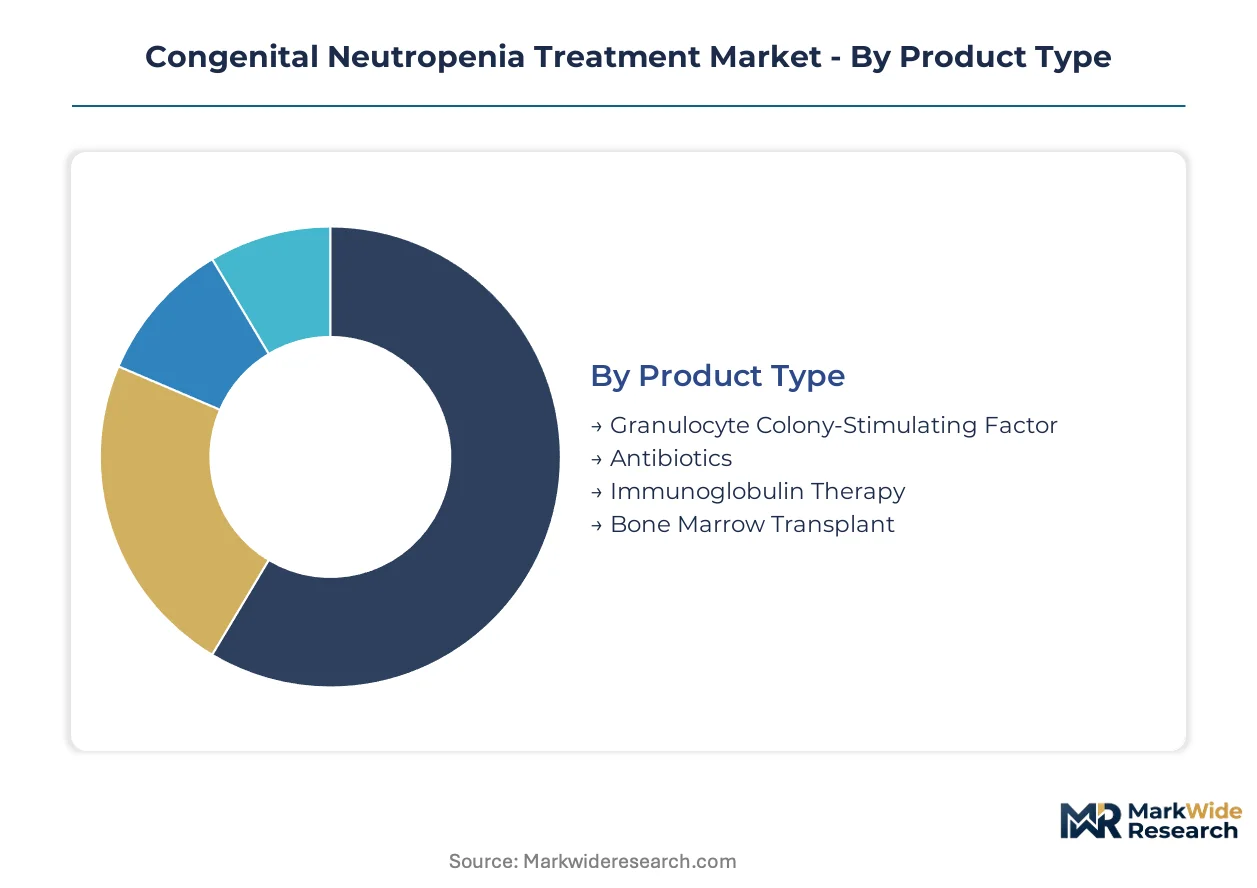
Segmentation in congenital neutropenia treatment reveals distinct reimbursement and patient flow patterns across product categories and care settings. Pediatric hospitals command disproportionate procedure volumes due to disease onset timing and specialized monitoring requirements. Technology differentiation separates chronic maintenance regimens from curative interventions with fundamentally different pricing and follow-up economics.
Product Type:
Volume concentration favors established recombinant proteins with decades of manufacturing scale, while premium pricing attaches to cellular interventions requiring specialized handling infrastructure.
- Granulocyte Colony-Stimulating Factor:Recombinant human G-CSF stimulates myeloid progenitor cell proliferation through binding to colony-stimulating factor 3 receptors. Demand concentrates in pediatric hematology wards across the United States, Germany, and Japan where daily administration protocols require dedicated nursing staff and cold-chain logistics. Chronic reimbursement codes anchor revenue predictability despite biosimilar pressure.
- Antibiotics:Prophylactic and empiric antibacterial regimens target gram-negative and gram-positive organisms during neutropenic fever episodes. Prescribing concentrates in tertiary children's hospitals with infectious disease co-management protocols, driven by institutional antibiogram surveillance and febrile neutropenia risk stratification tools.
- Immunoglobulin Therapy:Intravenous immunoglobulin replacement addresses hypogammaglobulinemia comorbidities in select congenital neutropenia subtypes.
- Bone Marrow Transplant:Allogeneic hematopoietic stem cell transplantation offers curative potential for severe cases with HLA-matched donors.
Mature deployment sits with Granulocyte Colony-Stimulating Factor. Newer deployment is concentrated in Bone Marrow Transplant.
End User:
Patient acuity and reimbursement intensity separate inpatient pediatric facilities from outpatient and research-oriented settings.
- Pediatric Hospitals:Tertiary children's hospitals maintain dedicated neutropenia clinics with 24-hour fever hotlines and multidisciplinary care teams spanning hematology, infectious disease, and genetics. These centers capture the longest patient relationships and highest procedure volumes across all technology categories, supported by Medicaid and private payer carve-outs for rare disease management.
- Ambulatory Surgical Centers:Outpatient facilities handle port placement, bone marrow biopsy, and stable patient monitoring.
- Specialty Clinics:Private hematology practices concentrate stable adult patients with established G-CSF regimens.
- Research Institutes:Academic medical centers host gene therapy trials and longitudinal natural history studies.
Revenue concentration follows Pediatric Hospitals. Steepest expansion trajectory belongs to Research Institutes.
Technology:
Development-stage maturity creates a bimodal split between approved pharmacological maintenance and experimental curative platforms.
- Gene Therapy:Lentiviral vector-mediated gene transfer into autologous hematopoietic stem cells promises single-intervention cures for severe congenital neutropenia subtypes. Clinical activity concentrates at academic medical centers in the United States and Germany with established gene therapy infusion units and 18-month follow-up protocols.
- Stem Cell Therapy:Allogeneic hematopoietic stem cell approaches leverage matched unrelated donor registries and haploidentical protocols.
- Immunotherapy:Investigational approaches modulate neutrophil production through cytokine engineering.
- Pharmacological Therapy:Small-molecule enhancers of G-CSF signaling and alternative myeloid growth factors occupy earlier development stages.
Regulatory approval sits with Pharmacological Therapy. Pipeline investment concentrates in Gene Therapy.
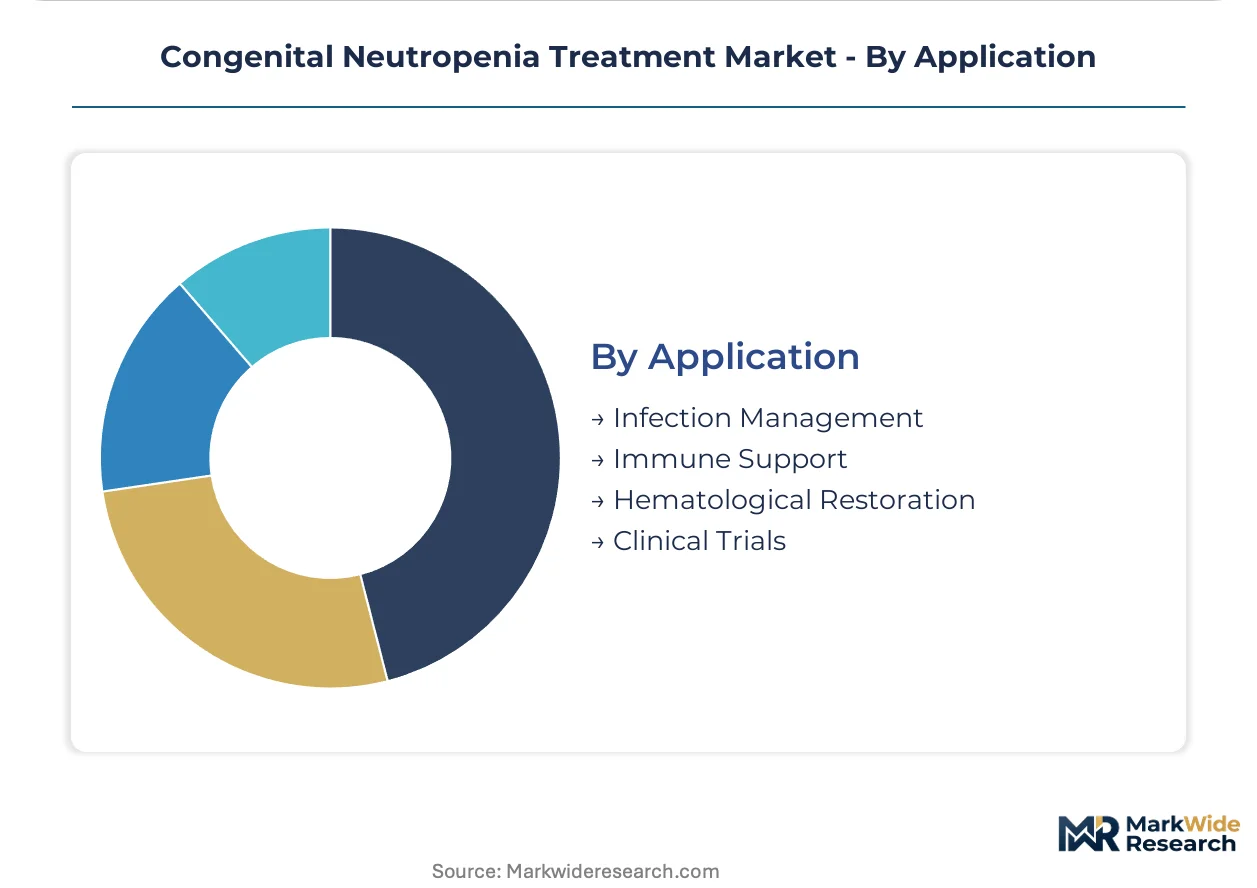
Application:
Clinical purpose separates acute intervention from chronic prevention and research participation.
- Infection Management:Febrile neutropenia protocols, prophylactic antimicrobials, and hospital admission criteria dominate acute care resource allocation. Implementation concentrates in pediatric emergency departments with dedicated neutropenia risk stratification pathways and rapid antibiotic administration targets.
- Immune Support:G-CSF prophylaxis and immunoglobulin replacement maintain neutrophil thresholds and antibody coverage.
- Hematological Restoration:Curative interventions aim to reconstitute normal myelopoiesis.
- Clinical Trials:Natural history registries and interventional studies capture phenotypic diversity across genotypes.
Standard of care sits with Infection Management. Protocol innovation concentrates in Clinical Trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for rare disease therapeutics concentrate clinical trial infrastructure and manufacturing investment across select high-income markets, creating geographic asymmetry in patient access to advanced congenital neutropenia interventions.
United States
Pediatric hematology centers in Boston, Cincinnati, and Seattle drive procedure volumes through dedicated neutropenia clinics with 24-hour fever hotlines. The FDA's orphan drug designation framework provides seven-year market exclusivity and tax credits for clinical trial costs. Academic medical centers in these metropolitan clusters host the majority of gene therapy trials and natural history registries.
Germany
Tertiary children's hospitals in Munich and Hamburg maintain multidisciplinary care teams spanning hematology, infectious disease, and genetics disciplines. EMA pediatric investigation plan requirements extend development timelines but create standardized enrollment criteria across member states. The country's IQWiG health technology assessment body evaluates novel therapies against chronic G-CSF administration economics.
Japan
PMDA's sakigake designation for regenerative medicines compresses regulatory timelines and attracts gene therapy developers targeting severe congenital neutropenia subtypes. Pediatric hematology volumes concentrate in Tokyo and Osaka metropolitan medical centers. The country's national health insurance system maintains distinct reimbursement carve-outs for rare disease biologics administered in designated cancer centers.
United Kingdom
The National Health Service's specialized commissioning framework routes severe congenital neutropenia cases to designated supra-regional centers in London and Manchester. MHRA's recognition of EMA approvals accelerates market access for ATMP-class therapies. Academic medical centers in these cities participate in European gene therapy consortiums with standardized 18-month follow-up protocols.
France
Reference centers for rare hematological diseases in Paris and Lyon coordinate national patient registries and natural history studies. HAS health technology assessment criteria emphasize quality-adjusted life year gains over cost-minimization for curative versus chronic interventions. Pediatric hematology centers in these regions restructure pharmacy operations to accommodate gene therapy storage and handling requirements.
Congenital Neutropenia Treatment Market Competitive Environment
Top-tier vendors anchor recombinant protein manufacturing scale, while emerging gene therapy specialists occupy development-stage positions with unproven commercial infrastructure. The market structure reflects a bifurcation between decades-established G-CSF suppliers and venture-backed platform developers. Three archetypes dominate: legacy biologics manufacturers with captive fermentation capacity, specialized hematology channel operators, and gene therapy platform companies. Competitive moves concentrate on manufacturing capacity expansion and strategic partnerships for vector production.
Within the legacy biologics tier, Amgen exemplifies manufacturing scale advantages derived from decades of process optimization in recombinant protein production. Spectrum Pharmaceuticals occupies a position among specialized oncology and hematology channel controllers with established hospital formulary relationships. BeyondSpring Pharmaceuticals represents the gene therapy archetype, positioning pipeline assets toward severe congenital neutropenia subsets with curative intent.
| Leading Market Players |
|---|
| Amgen |
| Spectrum Pharmaceuticals |
| BeyondSpring Pharmaceuticals |
| Myelo Therapeutics |
| Cellerant Therapeutics |
| Generon |
| Sandoz |
| Biocon Biologics |
| Kyowa Kirin |
| Others |
Value Chain & Pricing Dynamics
Venture-backed gene therapy platform companies anchored supply behavior and pricing discipline through captive vector manufacturing investments and premium positioning against chronic G-CSF reimbursement benchmarks. Their capital intensity forced pricing models that recover R&D through single-intervention premiums while contract manufacturing organizations extract margin from recombinant protein commoditization.
Pricing Analysis
Short lead-time premiums attach to lentiviral vector slots at qualified contract development and manufacturing organizations, while spot inventory discounts appear for excess G-CSF fermentation capacity. Three-tier pricing structure across premium gene therapy, standard biologic maintenance, and economy biosimilar tiers reflects FDA orphan exclusivity windows and manufacturing complexity differentials. Price differentiation rests on certification grade and vertical integration depth. Pricing pressure stems from biosimilar entry in chronic G-CSF segments. Pediatric hospitals exhibit highest price sensitivity due to Medicaid reimbursement constraints, while research institutes accept premium pricing for early vector access.
Supply Chain Analysis
Dual-sourcing requirements from pediatric hospital procurement committees mandate qualified backup suppliers for G-CSF active pharmaceutical ingredient and lentiviral vector production. Geographic supply concentration centers on the United States, Germany, and Switzerland for gene therapy infrastructure, with India and South Korea anchoring recombinant protein fermentation. Raw material dependencies include plasmid DNA, transfection reagents, and serum-free media formulations. Single-source vulnerability concentrates in lentiviral vector production expertise. Distribution runs through cold-chain specialty pharmacy channels with direct-to-patient logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The congenital neutropenia treatment market reads as a cost-of-compliance story where EMA pediatric investigation plan requirements create a 18-24 month barrier-to-entry moat for developers with established regulatory affairs infrastructure.
For Market Incumbents: Deepen backward integration into plasmid DNA production to secure vector manufacturing inputs against contract development and manufacturing organization capacity constraints. Expand dedicated neutropenia clinic partnerships in Boston and Cincinnati to lock in patient flow ahead of gene therapy commercialization. Gene therapy platform entrants threaten chronic G-CSF revenue pools. For New Entrants and Emerging Players: Enter via Japan's PMDA sakigake designation pathway to compress regulatory timelines for severe congenital neutropenia subsets. Target research institute partnerships in Germany for natural history study participation and vector manufacturing qualification. White space concentrates in allogeneic stem cell approaches with haploidentical protocols. Go-to-market angle: direct-to-patient specialty pharmacy channels with home administration support. For Investors and Strategic Acquirers: Distressed-cycle entries favor gene therapy platform companies with manufacturing capacity in the United States or Germany during capital market dislocations. Long-term viability hinges on curative intent therapies capturing lifetime value from chronic G-CSF displacement. Acquisition target archetype: lentiviral vector specialists with pediatric hematology center relationships. Signal to watch: stem cell therapy durability data extending beyond 24 months.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Dedicated cleanroom infrastructure at academic medical centers in Boston and Hamburg accelerates patient access. |
| Pediatric Investigation Plan Compliance | EMA standardized enrollment criteria create transferable regulatory assets across member state markets. |
| Specialty Pharmacy Channel Partnership | Cold-chain logistics specialization enables home G-CSF administration reducing hospital burden. |
| Orphan Drug Designation Pursuit | FDA seven-year exclusivity and tax credits improve economics for severe congenital neutropenia subsets. |
| Natural History Registry Participation | Longitudinal data from French reference centers de-risks gene therapy development timelines. |
Study Parameters
Multi-period observation of gene therapy trial enrollment, G-CSF reimbursement code utilization, and pediatric hospital capacity expansion anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA orphan drug designation filings, EMA pediatric investigation plan submissions, ClinicalTrials.gov protocols, and formulary databases. Bottom-up patient flow modeling and top-down revenue pool estimates were triangulated against manufacturer-reported volume data.
Segment-weighting across product type, end user, technology, and application dimensions structured the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and pricing scenario analysis. Treatment line positioning and regional regulatory cluster adoption curves served as industry-specific forecast inputs.
Revisions become necessary when gene therapy durability data extends beyond current observation windows or when vector manufacturing capacity constraints intensify. Forecasts reflect assumptions about reimbursement persistence for chronic biologics and regulatory pathway timelines. Deviation in EMA pediatric investigation plan enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Immunology Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Middle East and Africa Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
HTLV-1 Associated Myelopathy (HAM) Market