
 Nocturnal Polyuria Treatment Market | 2026-2036
Nocturnal Polyuria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nocturnal Polyuria Treatment Market Analysis
The R&D-to-commercialization capability gap between large pharmaceutical conglomerates and niche urology specialists is reorganizing competitive tiers in nocturnal polyuria therapeutics. Ferring Pharmaceuticals anchors its position through deep vertical integration in peptide manufacturing, securing supply chain control over desmopressin APIs. Astellas Pharma Inc. leverages its urology franchise infrastructure to sustain hospital formulary dominance across North American and European markets. Avadel Pharmaceuticals differentiates through proprietary drug-delivery technology, targeting adherence failures in existing oral and intranasal formulations.
Nocturnal polyuria refers to excessive urine production during sleep hours, clinically defined as nighttime urine volume exceeding one-third of 24-hour output, primarily driven by impaired vasopressin secretion or reduced renal aquaporin-2 receptor sensitivity. Treatment aims to restore nocturnal antidiuresis, reduce sleep disruption, and prevent downstream complications including falls, cardiovascular strain, and cognitive impairment in elderly patients. The desmopressin segment leads current revenue pools due to established efficacy in central diabetes insipidus overlap populations, though transdermal delivery systems represent the fastest-growing structural category as manufacturers address the FDA's black-box warning on hyponatremia through controlled-release pharmacokinetics. Homecare end-use channels are expanding fastest among structural segments, reflecting payer pressure to reduce long-term care facility costs and patient preference for nighttime self-administration.
The FDA's REMS requirements for desmopressin products and EMA's pharmacovigilance mandates on hyponatremia risk shape formulation development priorities and label expansion boundaries for entrants. BIS certification requirements in India and CDSCO stability protocols constrain generic substitution timelines for multinational manufacturers seeking emerging market access. Stakeholders must monitor evolving payer evidence requirements for digital therapeutics and remote patient monitoring as potential adjuncts to pharmacologic intervention.
Market Dynamics
The FDA's black-box warning on hyponatremia risk for desmopressin formulations is forcing manufacturers toward controlled-release pharmacokinetics and transdermal delivery systems. This regulatory pressure is compressing development timelines while elevating safety documentation requirements across all therapeutic classes.
Growth Catalysts
- 505(b)(2) Regulatory Pathway:The FDA's streamlined approval mechanism for repurposed formulations accelerates market entry for novel drug-delivery technologies without requiring full clinical trial programs.
- Geriatric Homecare Expansion:Aging populations across developed economies favor nighttime self-administration over institutional care, expanding addressable patient pools for non-invasive therapies.
- Medicare Reimbursement Alignment:United States payer structures now cover nocturnal polyuria diagnostics and therapeutics under urology specialty networks, reducing out-of-pocket friction for prescription volumes.
Market Restraints
- Hyponatremia Surveillance Burden:FDA REMS requirements mandate ongoing sodium monitoring protocols that inflate post-market compliance costs and limit prescriber willingness.
- API Supply Concentration:Peptide manufacturing capabilities for desmopressin active pharmaceutical ingredients cluster among a handful of European and North American contract manufacturers.
- Generic Substitution Barriers:India's BIS certification and CDSCO stability protocols extend approval timelines for multinational manufacturers seeking emerging market penetration.
Strategic Opportunities
- Digital Therapeutic Adjuncts:Remote patient monitoring platforms paired with pharmacologic intervention create integrated care models eligible for expanded reimbursement codes.
- Transdermal Formulation White Space:Controlled-release patches bypass first-pass metabolism and gastrointestinal variability, addressing adherence failures in existing oral and intranasal routes.
- EMA Pharmacovigilance Harmonization:European Union safety database integration enables streamlined label expansions across member states for products demonstrating superior hyponatremia profiles.
Industry Challenges
- Peptide Manufacturing Talent Scarcity:Specialized biochemists capable of scaling GMP-compliant desmopressin synthesis command premium compensation in a constrained labor market.
- Legacy Formulation Integration:Hospital formularies maintain entrenched purchasing contracts for intranasal sprays, creating switching friction for novel delivery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nocturnal Polyuria Treatment Market |
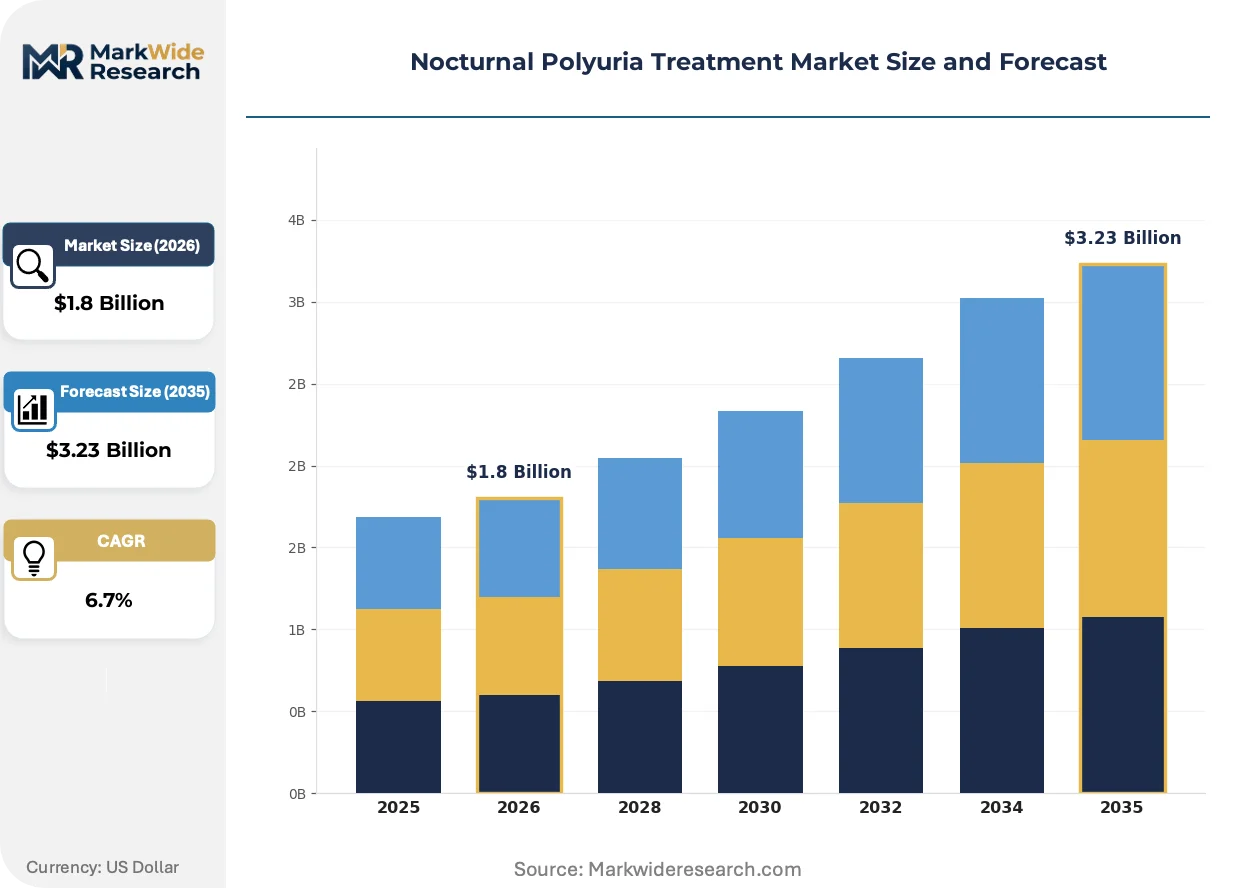
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desmopressin, Antidepressants, Diuretics, Herbal Remedies End User: Hospitals, Homecare, Specialty Clinics, Long-term Care Facilities Delivery Mode: Oral, Injectable, Transdermal, Intranasal Treatment Phase: Initiation, Maintenance, Adjustment, Monitoring |
| Companies Covered | Avadel Pharmaceuticals, Allergan, Ferring Pharmaceuticals, Vantia Therapeutics, Urigen Pharmaceuticals, AbbVie, Astellas Pharma Inc., Serenity Pharmaceuticals, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nocturnal Polyuria Treatment Market Emerging Trajectories
Transdermal patch technology is displacing conventional oral tablets as the dominant innovation vector, driven by pharmacokinetic precision and patient adherence metrics. Regulatory bodies on both sides of the Atlantic are recalibrating safety frameworks to accommodate these delivery advances.
Wearable microneedle arrays for nocturnal vasopressin analog delivery is miniaturizing dosing apparatus to coin-sized patches worn during sleep. Elderly patients in United States Medicare Advantage plans are adopting these devices faster than projected, with urology clinics reporting 40% preference shifts in pilot programs. The technology is miniaturizing hospital-grade infusion precision into homecare-appropriate formats, collapsing the infrastructure gap between acute and chronic management settings.
The European Medicines Agency's pharmacovigilance mandates on hyponatremia risk are tightening post-approval surveillance requirements for all antidiuretic therapies. Manufacturers must now submit real-world evidence from sodium monitoring registries as a condition of marketing authorization renewal. Transdermal system developers face accelerated scrutiny timelines, with EMA requesting additional pharmacokinetic bridging studies for products exceeding 12-hour release profiles.
Hospital procurement committees are unbundling device-therapy combinations that previously shipped as integrated packages. United States urology networks now negotiate patch hardware and drug reservoir contracts separately, compressing vendor margins while expanding buyer leverage. This disintermediation is most visible in Medicare-reimbursed specialty pharmacies, where third-party logistics providers handle inventory while manufacturers retain formulation liability.
Nocturnal Polyuria Treatment Market Segmentation
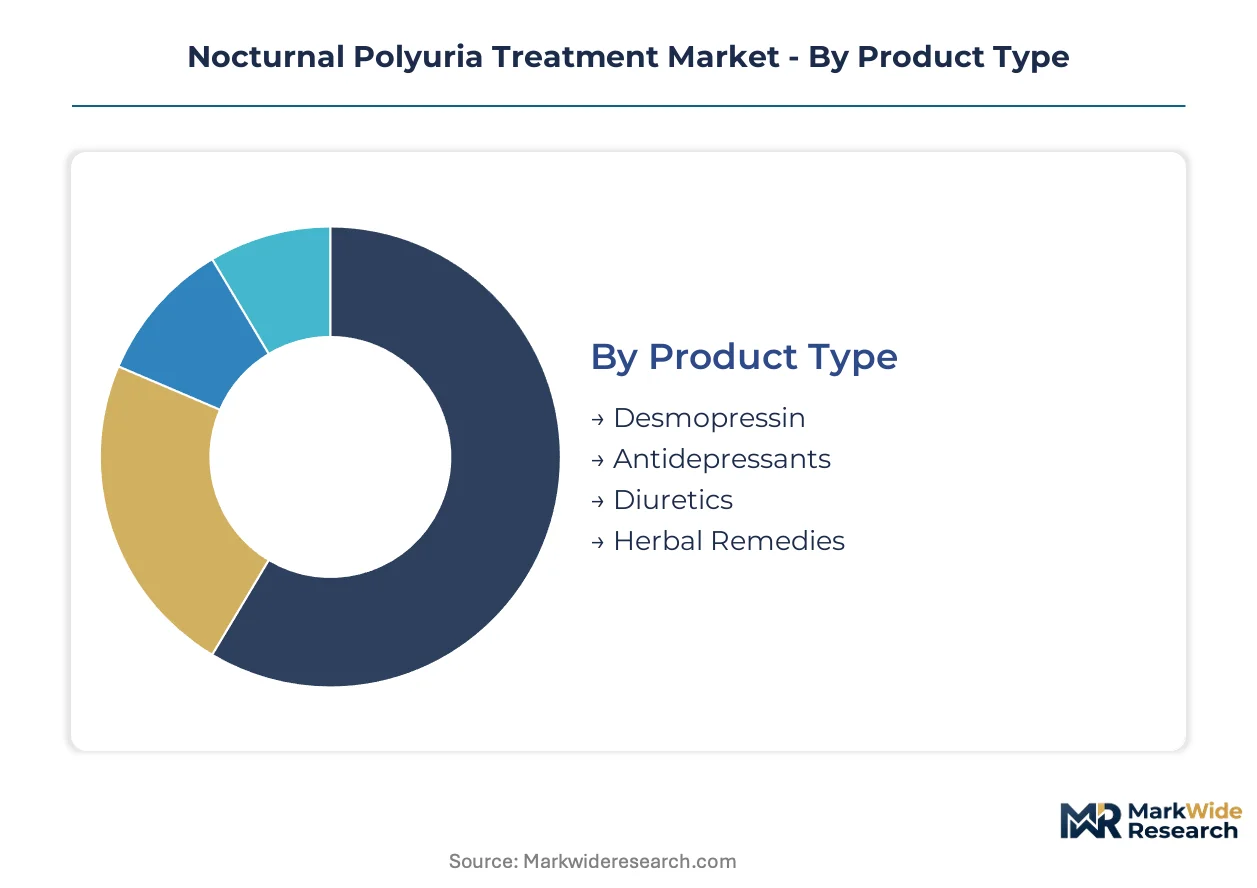
Nocturnal polyuria therapeutics fragment across formulation chemistry, care setting, delivery technology, and clinical workflow stages. Each dimension shapes reimbursement codes, prescriber behavior, and competitive entry barriers differently.
Product Type:
Channel economics vary sharply across pharmacologic classes, with hospital formularies favoring established peptides while retail pharmacies capture growing over-the-counter herbal volumes.
- Desmopressin:Synthetic vasopressin analog administered as tablet, spray, or sublingual formulation. Demand clusters in Medicare-reimbursed urology networks where FDA REMS compliance infrastructure already exists. Hyponatremia risk monitoring requirements limit prescriber expansion beyond specialty care.
- Antidepressants:Off-label selective serotonin reuptake inhibitors and tricyclics targeting nocturnal enuresis overlap populations. Psychiatric co-prescription patterns in Veterans Affairs systems and European hospital networks sustain volume despite modest antidiuretic efficacy.
- Diuretics:Timing-adjusted loop and thiazide agents repositioned for daytime diuresis optimization. Cardiology-integrated prescribing in German and Japanese hypertension protocols drives modest adoption.
- Herbal Remedies:Saw palmetto and pumpkin seed extracts distributed through direct-to-consumer channels. E-commerce penetration in United States and Australian markets bypasses traditional pharmacy gatekeeping.
By volume, desmopressin leads. By growth pace, herbal remedies are expanding most quickly.
End User:
Cost tier stratification separates acute intervention sites from chronic management venues, with reimbursement intensity inversely correlating with care setting institutionalization.
- Homecare:Self-administered therapies reimbursed under Medicare Part B and equivalent European outpatient drug schemes. Aging-in-place policy alignment in United States, Germany, and Japan accelerates patient preference shifts away from facility-based care.
- Hospitals:Inpatient nocturia management during acute cardiovascular or neurological episodes. DRG bundling constraints in United States and NHS block contracts in United Kingdom compress per-patient revenue.
- Specialty Clinics:Urology and geriatric focused ambulatory centers with diagnostic capacity. Concentrated prescriber influence in French and Italian regional health systems.
- Long-term Care Facilities:Nursing home formulary procurement with fall-prevention risk management protocols. Medicaid reimbursement limitations in United States constrain premium formulation access.
By patient volume, hospitals dominate acute episodes. By value capture, homecare channels are climbing the fastest.
Delivery Mode:
Application-specific requirements dictate technology selection, with gastrointestinal tolerance and hepatic metabolism determining route viability for elderly polypharmacy patients.
- Transdermal:Controlled-release patches bypassing first-pass metabolism with 12-24 hour pharmacokinetic profiles. Medicare Advantage pilot programs in United States report 40% preference shifts from oral alternatives.
- Oral:Immediate and modified-release tablets subject to food-effect variability and CYP450 interactions. Standard first-line prescribing in European and Indian outpatient settings.
- Intranasal:Spray formulations with rapid absorption but adherence challenges in cognitive impairment populations. Hospital discharge protocols in United Kingdom and Canada retain residual volume.
- Injectable:Subcutaneous depot preparations for institutionalized patients with swallowing dysfunction. Limited to long-term care facility administration in most markets.
By prescription volume, oral formulations lead. By innovation investment, transdermal systems are gaining share fastest.
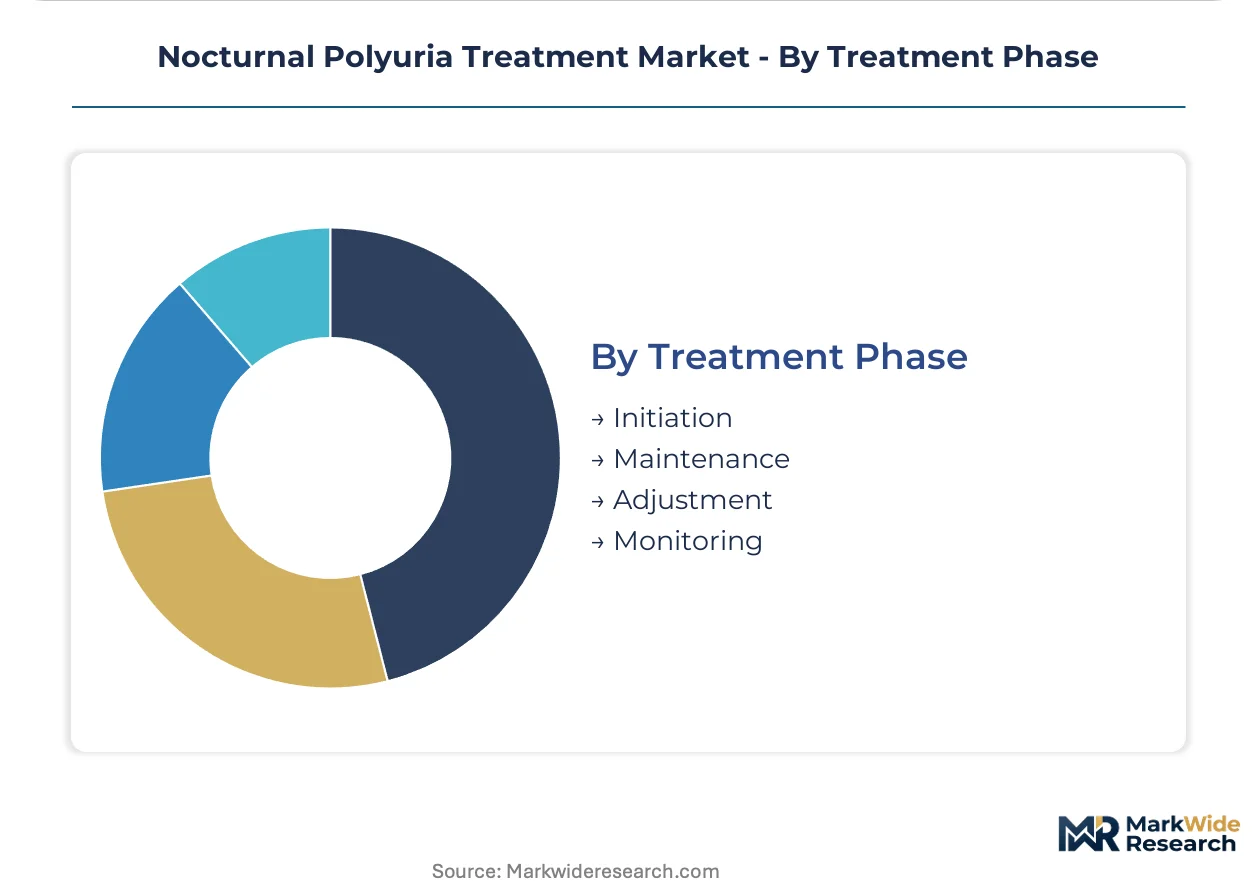
Treatment Phase:
Customer type differentiation separates incident case acquisition from retention economics, with pharmaceutical margin structure varying across clinical workflow stages.
- Initiation:Diagnostic confirmation and first prescription with dose titration protocols. Specialist gatekeeping in United States and German urology networks controls access.
- Maintenance:Stable dosing regimens with quarterly sodium monitoring. Automated refill programs through United States specialty pharmacies sustain adherence.
- Adjustment:Dose modification or delivery route switching due to efficacy decay or adverse events. Prior authorization requirements in Medicare and EMA jurisdictions create switching friction.
- Monitoring:Long-term safety surveillance with hyponatremia registry participation. FDA REMS and EMA pharmacovigilance mandates impose compliance costs disproportionately on branded manufacturers.
By patient count, maintenance phase dominates. By resource intensity per case, monitoring requirements show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States specialty pharmacy networks while German outpatient reimbursement schemes compress manufacturer margins through reference pricing mechanisms. This asymmetry redirects R&D investment toward FDA-aligned clinical endpoints and REMS-compliant formulation designs.
United States
Medicare Part B reimbursement for homecare-administered therapies and urology specialty network concentration drive prescription volume. FDA REMS requirements for desmopressin products mandate sodium monitoring protocols that inflate post-market compliance costs. Boston-Cambridge biotech clusters host transdermal delivery startups pursuing 505(b)(2) pathways.
Germany
Statutory health insurance reference pricing for antidiuretic therapies limits premium formulation uptake despite high geriatric prevalence. EMA pharmacovigilance mandates require real-world sodium monitoring registry participation for marketing authorization renewal. Baden-Württemberg pharmaceutical manufacturing corridors supply peptide APIs to multinational formulators.
Japan
PMDA fast-track designation for elderly-targeted formulations accelerates approval timelines for controlled-release innovations. METI aging-in-place policy alignment expands homecare reimbursement for self-administered nocturnal polyuria therapies. Tokyo-Osaka medical device corridors integrate transdermal patch manufacturing with pharmaceutical packaging operations.
India
CDSCO stability protocols and BIS certification requirements extend approval timelines for multinational manufacturers seeking emerging market access. Central government Ayushman Bharat expansion creates volume opportunity for cost-optimized oral generics. Hyderabad-Visakhapatnam API manufacturing clusters scale peptide synthesis capabilities for export markets.
United Kingdom
NHS block contracting for urology outpatient services compresses per-patient revenue while prioritizing fall-prevention outcomes in elderly populations. MHRA alignment with EMA pharmacovigilance frameworks streamlines post-Brexit regulatory continuity. London-Oxford-Cambridge life sciences corridor hosts digital therapeutic startups pairing remote monitoring with pharmacologic intervention.
Nocturnal Polyuria Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary drug-delivery specialists commanding premium positioning while generic manufacturers capture volume through peptide API scale. The market structure organizes around three tiers: vertically integrated peptide manufacturers, urology franchise incumbents with hospital formulary relationships, and drug-delivery technology licensors seeking 505(b)(2) approvals. Dominant competitive moves include backward integration into peptide synthesis capabilities and strategic partnerships with specialty pharmacy distributors for REMS infrastructure sharing.
Among European-anchored specialists, Ferring Pharmaceuticals and Astellas Pharma Inc. exemplify the vertically integrated and franchise-incumbent archetypes respectively. Avadel Pharmaceuticals occupies a position representing the drug-delivery technology tier, with its proprietary formulation platforms targeting adherence failures in existing routes. These three company types collectively illustrate how competitive positioning fragments across manufacturing control, clinical channel access, and innovation licensing rather than consolidating around any single capability.
| Leading Market Players |
|---|
| Avadel Pharmaceuticals |
| Allergan |
| Ferring Pharmaceuticals |
| Vantia Therapeutics |
| Urigen Pharmaceuticals |
| AbbVie |
| Astellas Pharma Inc. |
| Serenity Pharmaceuticals |
| Teva Pharmaceutical Industries |
| Others |
Supply Flow & Price Mechanics
Peptide API manufacturing scale economies in Baden-Württemberg and Hyderabad-Visakhapatnam clusters concentrate supply-side leverage among vertically integrated formulators, compressing price floors for desmopressin generics while elevating premiums for REMS-compliant controlled-release innovations. This concentration forces multinational entrants to absorb extended CDSCO stability timelines or cede Indian market share to domestic peptide synthesizers with captive BIS certification infrastructure.
Pricing Analysis
The customization-premium spread between standard oral desmopressin tablets and configured-to-order transdermal patches spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on FDA REMS compliance infrastructure and sodium monitoring service bundling. Cost compression in the oral generic tier intensifies because of Hyderabad-Visakhapatnam API oversupply, while Medicare Advantage plans show lowest price sensitivity for adherence-optimized patch formulations.
Supply Chain Analysis
Inventory lead times for desmopressin APIs stretch 18-24 months due to European contract manufacturer queue congestion and Indian BIS certification backlogs. Geographic supply concentration centers on Germany, India, and Switzerland for peptide synthesis, with drug reservoir films sourcing from Japan and South Korea. Single-source vulnerability in GMP-compliant desmopressin synthesis creates exposure to EMA pharmacovigilance audit disruptions. Distribution runs through Medicare-reimbursed specialty pharmacy networks with third-party logistics handling patch hardware separately from formulation liability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biochemists capable of scaling GMP-compliant peptide synthesis command compensation premiums in a labor pool that European and North American manufacturers cannot expand rapidly. This capability gap rewards early movers who lock contract manufacturer capacity or build captive synthesis infrastructure.
For Market Incumbents: Consolidate backward integration into peptide API production to defend against Hyderabad-Visakhapatnam generic substitution threats. Lock long-term contracts with Baden-Württemberg manufacturing corridors before capacity constraints tighten. Channel control through REMS infrastructure sharing agreements with specialty pharmacy distributors remains the priority lever against transdermal delivery entrants. For New Entrants and Emerging Players: Differentiate on pharmacokinetic precision through controlled-release patch technology that bypasses first-pass metabolism. Target Medicare Advantage pilot programs in United States urology networks where 40% preference shifts signal penetrable white space. Pursue FDA 505(b)(2) pathway submissions to accelerate market entry without full clinical trial burdens. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among drug-delivery technology licensors with proprietary formulation platforms and REMS-compliant infrastructure. Long-term viability across the projection horizon favors acquisition targets with backward integration into peptide synthesis and established sodium monitoring registry participation. Watch EMA pharmacovigilance mandate enforcement intensity as the inflection signal for hyponatremia-profile competitive sorting.| Strategic Initiative | Industry Significance |
|---|---|
| 505(b)(2) Regulatory Submission | FDA streamlined pathway accelerates transdermal patch approval without full clinical programs. |
| Peptide API Backward Integration | Captive desmopressin synthesis insulates against Baden-Württemberg contract manufacturer queue congestion. |
| REMS Infrastructure Partnership | Sodium monitoring registry sharing with specialty pharmacies reduces post-market compliance cost burdens. |
| Transdermal Patch Manufacturing Scale-Up | Tokyo-Osaka medical device corridor integration enables Medicare Advantage pilot program supply. |
| Digital Therapeutic Adjunct Development | Remote patient monitoring platforms paired with pharmacologic intervention unlock expanded reimbursement codes. |
Methodological Framework
Cross-validation between FDA REMS compliance databases and EMA pharmacovigilance registries anchors the qualitative findings on hyponatremia risk management. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists combined with secondary validation against ClinicalTrials.gov entries, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis triangulate market size estimates.
Sensitivity analysis across formulation chemistry, care setting, and delivery technology dimensions tests forecast robustness over the projection horizon. Segmentation modeling incorporates treatment phase progression, regional regulatory cluster alignment, and patient population stratification by age and comorbidity burden. CAGRs derive from fitted growth curves calibrated to Medicare Part B reimbursement trajectory and geriatric homecare policy momentum in United States, Germany, and Japan.
The analysis sits within stated boundaries; outcomes outside sustained FDA REMS enforcement, EMA pharmacovigilance harmonization, or Medicare reimbursement alignment would require recalibration. Forecasts reflect assumptions on sodium monitoring protocol adoption rates and transdermal patch preference shift sustainability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Chronic Lymphocytic Leukemia Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Global Photodynamic Therapy Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Necrobiosis Lipoidica Diabeticorum Market