
 North America Sugar Confectionery Market | 2026-2036
North America Sugar Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sugar Confectionery Market Insights
Premium clean-label tier is collapsing into mainstream positioning as cost structures normalize and scale economies emerge. Mars Incorporated leverages its North American manufacturing footprint to sustain volume leadership across multiple product formats. The Hershey Company anchors its position through deep chocolate specialization and controlled cocoa sourcing networks. Mondelēz International competes aggressively in the gummy and hard candy segments through diversified brand architecture.
North America sugar confectionery comprises sweetened edible products formulated with sucrose, glucose syrups, and flavoring agents, typically manufactured through cooking, depositing, or extrusion processes at controlled temperatures and moisture levels, serving primarily as impulse-purchase consumer goods for recreational consumption and gift occasions. Hard candy and gummy candy occupy the most dynamic structural positions, with gummy formats capturing accelerated investment due to functional ingredient integration and adult-targeted positioning, while chocolate maintains the largest absolute margin pool despite slower velocity. Marshmallows and specialty formats sustain niche profitability through seasonal concentration and premium gifting applications.
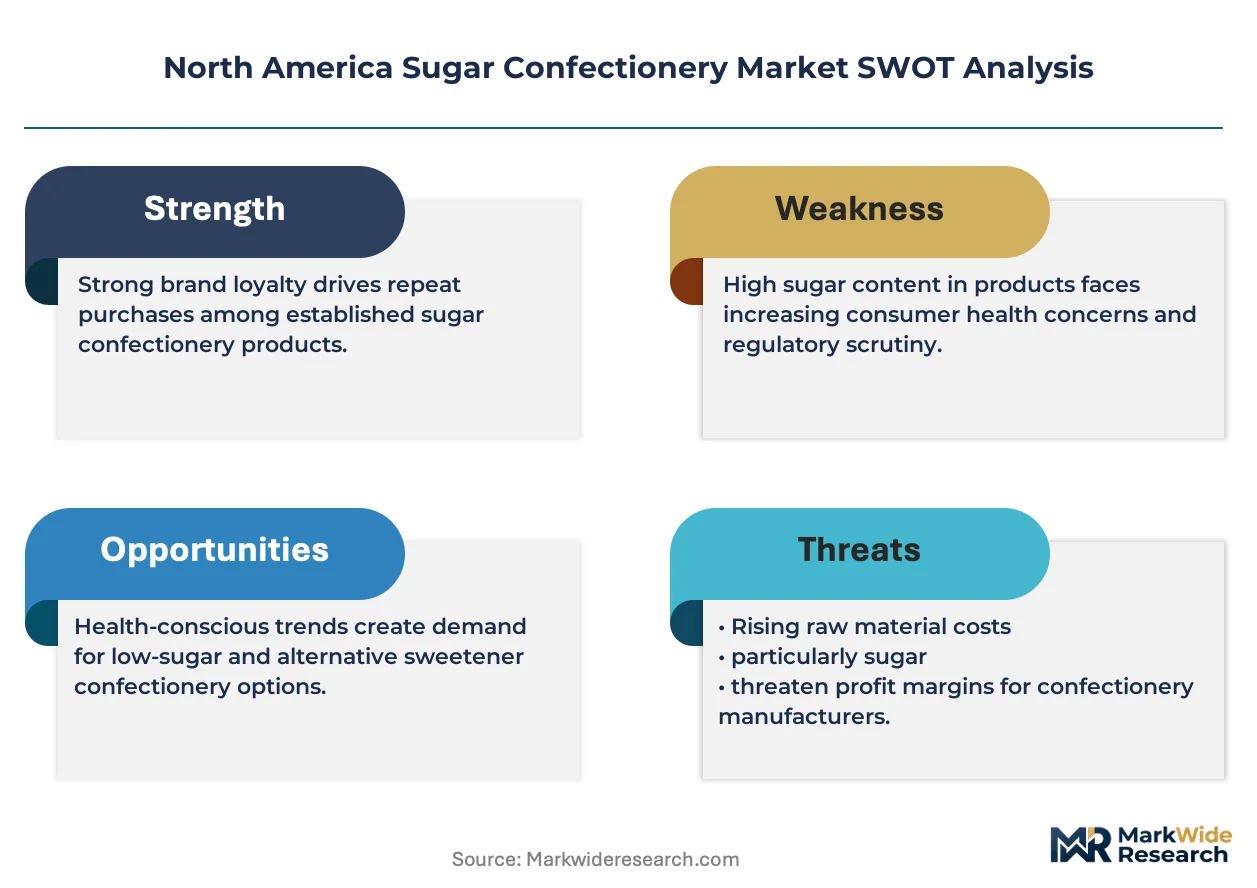
The FDA enforces nutrition labeling and added-sugar disclosure requirements that directly constrain formulation choices and marketing claims for products distributed across the United States. Health Canada and the CFIA administer parallel compositional standards and bilingual labeling mandates that create distinct compliance thresholds for Canadian market access. Stakeholders must monitor evolving federal and state-level sugar taxation proposals alongside clean-label certification trends to anticipate portfolio restructuring requirements.
Market Dynamics
Clean-label formulation mandates from the FDA and Health Canada are compressing legacy recipe architectures while forcing rapid ingredient substitution across manufacturing footprints in the United States and Canada.
Growth Catalysts
- Functional Ingredient Integration:Gummy formats incorporating vitamins, adaptogens, and probiotics are capturing adult wellness-oriented demand segments previously served by supplement categories.
- Added-Sugar Disclosure Mandates:FDA nutrition labeling requirements are accelerating transparency investments that premium-tier brands leverage for competitive differentiation against conventional formulations.
- Convenience Store Channel Expansion:Impulse-purchase placement in United States c-store networks is sustaining velocity for single-serve and grab-and-go packaging formats.
Market Restraints
- Cocoa Butter Price Volatility:Weather-driven supply disruptions in West African growing regions are compressing margin structures for chocolate-dependent product lines.
- High-Fructose Corn Syrup Substitution Limits:Technical formulation constraints prevent complete sucrose replacement without texture degradation in hard candy applications.
- State-Level Sugar Tax Proposals:Legislative initiatives in California, Colorado, and Washington threaten volume erosion in key metropolitan consumption clusters.
Strategic Opportunities
- Canadian Bilingual Labeling Arbitrage:Health Canada CFIA compliance infrastructure enables first-mover positioning for clean-label products targeting underserved French-speaking demographics.
- Direct-to-Consumer Subscription Models:Curated seasonal assortments bypass traditional retail slotting fees while capturing recurring revenue from millennial gifting occasions.
- Regenerative Agriculture Certification:USDA Organic and emerging soil-health standards create premium pricing justification for supply chain investments in domestic beet sugar sourcing.
Industry Challenges
- Confectionery Technologist Talent Scarcity:Specialized expertise in low-moisture cooking processes and flavor stability engineering commands premium compensation in tight labor markets.
- Legacy Equipment Retrofit Costs:Depositing and extrusion lines require capital-intensive modification to handle alternative sweetener rheology profiles.
- Dual-Jurisdiction Compliance Complexity:Simultaneous FDA and CFIA audit protocols extend product launch timelines for cross-border distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sugar Confectionery Market |
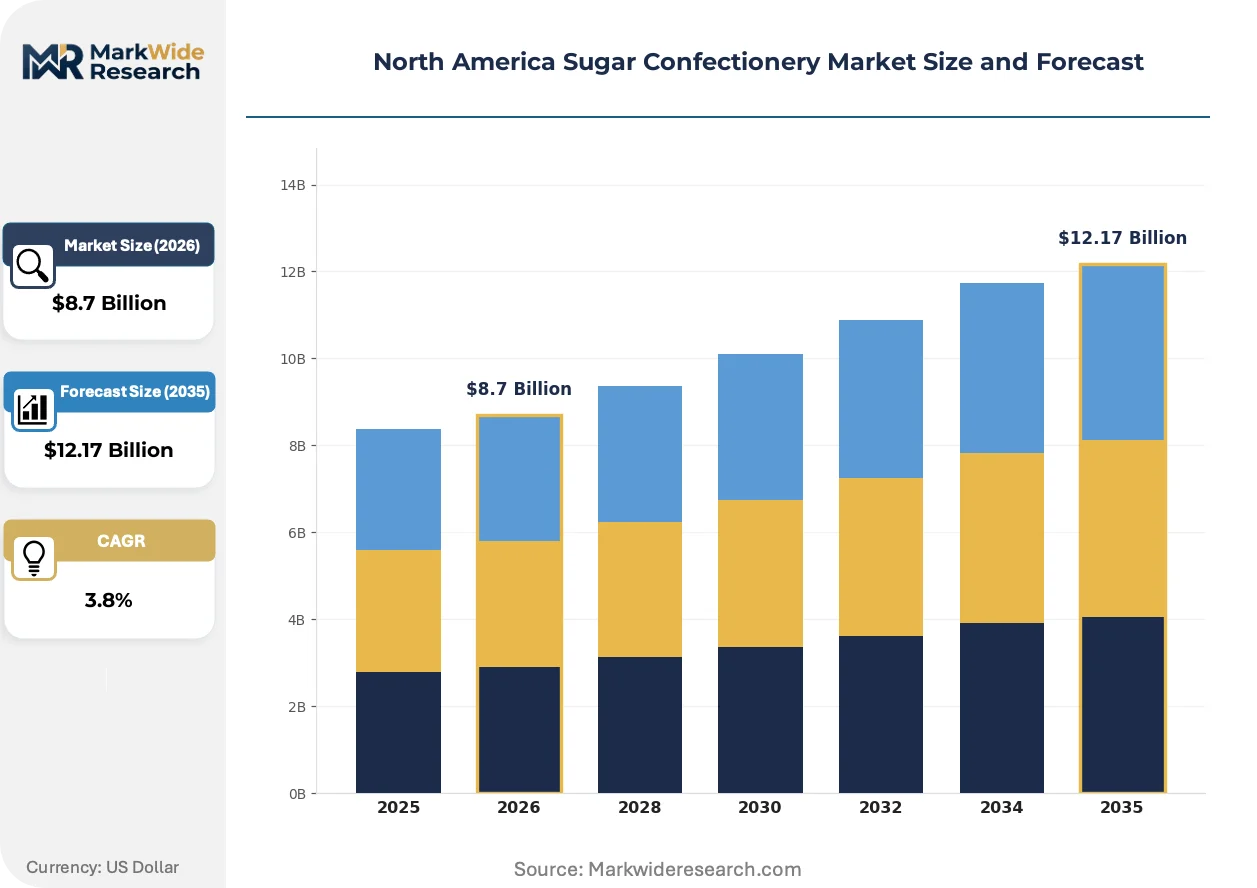
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Candy, Gummy Candy, Marshmallows, Chocolates End User: Children, Young Adults, Adults, Seniors Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Bags, Boxes, Tubs, Individual Wrappers |
| Companies Covered | Mars Incorporated, The Hershey Company, Mondelēz International Inc., Ferrero International S.p.A, Perfetti Van Melle BV, Haribo GmbH & Co., Ferrara Candy Company, Lindt & Sprüngli, Jelly Belly Candy Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sugar Confectionery Market Trends and Innovations
Reformulation chemistry and digital channel architecture are converging to reshape how sugar confectionery reaches and retains adult consumers across North American markets.
Allulose and rare sugar blends are displacing traditional sucrose-glucose syrup bases in gummy and chewy applications without triggering added-sugar line items on nutrition facts panels. Mid-tier manufacturers in the United States are adopting these ingredients at accelerating rates to maintain shelf placement as retail buyers enforce clean-label gatekeeping. This displacement is compressing conventional formulation suppliers while elevating specialty ingredient distributors with proprietary enzymatic conversion capabilities.
Health Canada's updated Food Guide and front-of-package nutrition symbol requirements are forcing bilingual reformulation decisions that favor simplified ingredient decks. The industrial consequence is portfolio rationalization toward shorter, recognizable component lists that satisfy both English and French-speaking inspection protocols. Hard candy and licorice segments in Quebec and Ontario are most affected, with regional processors accelerating natural colorant substitution to avoid disqualifying warning labels.
Millennial and Gen-Z purchasing through quick-commerce platforms is fragmenting traditional impulse-buy concentration in physical retail. Convenience store operators are responding with localized micro-fulfillment partnerships, while direct-to-consumer brands bypass wholesale entirely through TikTok Shop and Instagram checkout integration. This behavioral shift is most visible in United States coastal metropolitan corridors where delivery speed expectations now match or exceed in-store immediacy.
North America Sugar Confectionery Market Segmentation
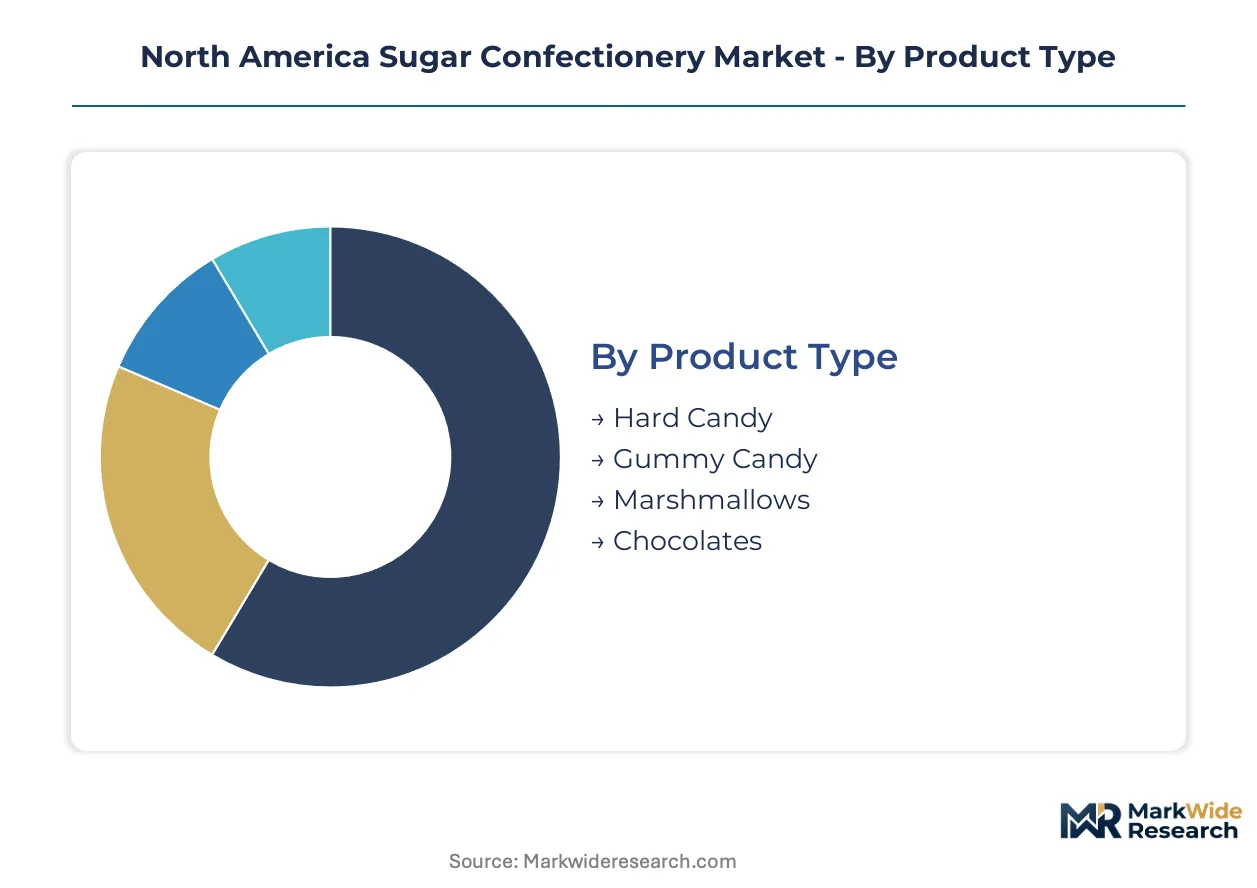
Sugar confectionery segmentation reveals distinct channel affinities and demographic targeting strategies that manufacturers must calibrate against formulation constraints and regulatory thresholds across the United States and Canada.
Product Type:
Channel placement varies sharply by product format, with gummy and hard candy dominating convenience store velocity while chocolate and marshmallows concentrate in gift-oriented retail.
- Hard Candy:Low-moisture cooked sucrose or glucose syrup matrices formed through depositing or die-casting at controlled temperatures. United States convenience store networks sustain the highest per-square-foot velocity for single-serve peg-bag formats, though high-fructose corn syrup substitution limits constrain clean-label migration.
- Gummy Candy:Starch-molded or starchless deposited formulations combining gelatin or pectin with glucose syrups and acidulants. Young adult wellness demand in California and New York coastal corridors is accelerating functional ingredient integration, with vitamins and adaptogens commanding premium shelf positioning.
- Marshmallows:Aerated sucrose-gelatin matrices produced through continuous whipping processes, concentrated in seasonal gifting applications and hot-beverage companions.
- Chocolates:Cocoa butter-based confectionery spanning enrobed, molded, and compound categories, anchoring margin pools through controlled sourcing networks despite cocoa price volatility pressures.
By volume, chocolates lead. By growth pace, gummy candy is expanding most quickly.
End User:
Purchasing authority and consumption occasion fragmentation create tiered pricing opportunities across demographic cohorts with divergent ingredient sensitivity thresholds.
- Children:Primary consumption concentrated in licensed character promotions and portion-controlled formats, with parental gatekeeping intensifying around artificial colorant and preservative scrutiny.
- Young Adults:Millennial and Gen-Z cohorts in United States metropolitan areas drive quick-commerce adoption and functional gummy demand, prioritizing transparency claims and TikTok-discoverable brands.
- Adults:Gifting and workplace consumption sustain premium chocolate and seasonal specialty demand, with direct-to-consumer subscription models capturing recurring purchase patterns.
- Seniors:Sugar-restricted and dental-sensitive requirements favor sugar-free hard candy formulations, with pharmacy and specialty store channels dominating access.
Young adults generate the steepest per-capita spending growth trajectory, while children retain the highest absolute volume throughput.
Distribution Channel:
Margin structures and compliance burdens diverge across channel types, with slotting fee economics and bilingual labeling requirements shaping cross-border strategies.
- Supermarkets:Mass-market volume concentration with elevated trade promotion requirements and planogram compliance costs, favoring scaled manufacturers with broad SKU portfolios.
- Convenience Stores:Impulse-purchase velocity engines for single-serve formats across the United States, with localized micro-fulfillment partnerships emerging in urban corridors.
- Online Retail:Direct-to-consumer and third-party marketplace growth concentrated in curated assortments and subscription gifting, bypassing traditional wholesale margin extraction.
- Specialty Stores:Premium and imported positioning with higher per-unit margins, particularly in Canadian French-speaking markets where Health Canada CFIA bilingual mandates create compliance arbitrage opportunities.
Supermarkets capture the largest absolute revenue pool, while online retail is climbing the fastest.
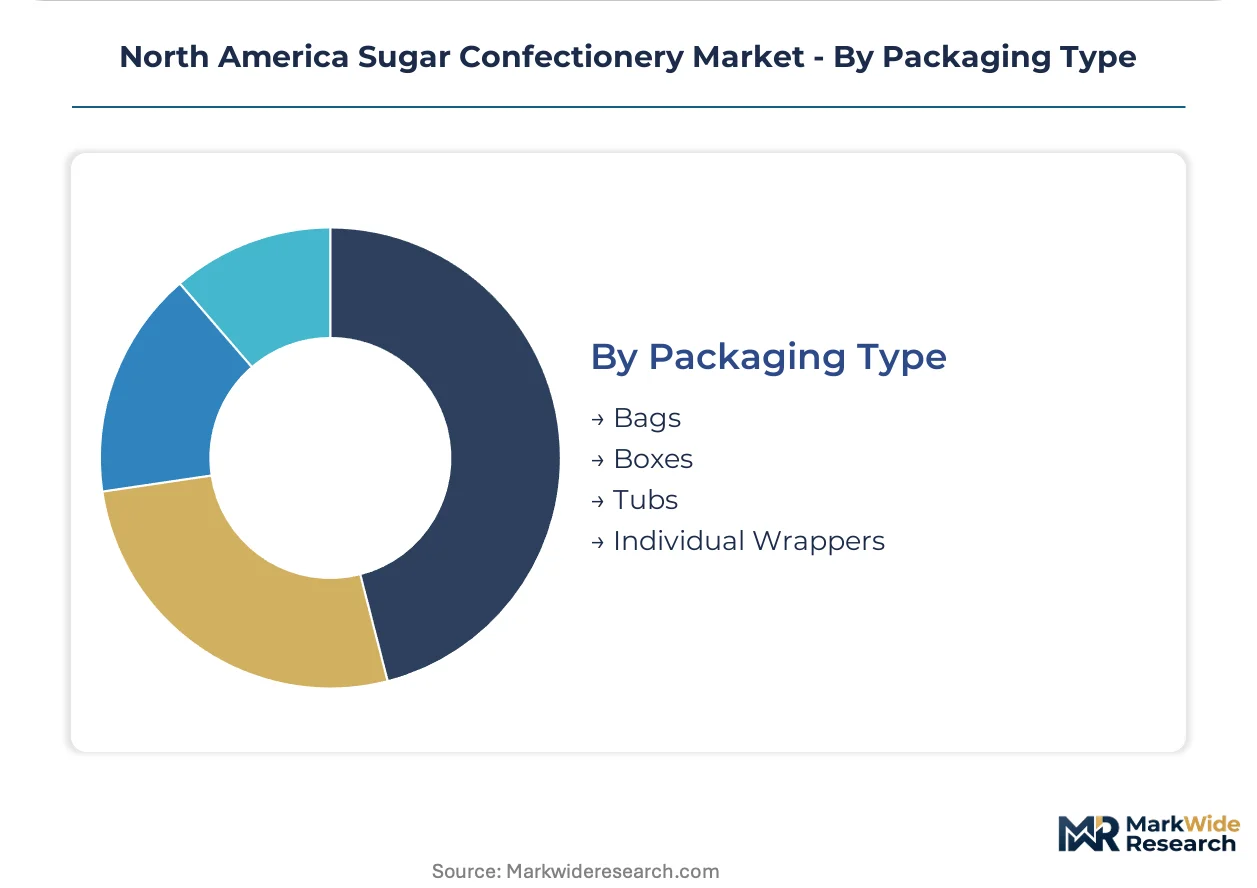
Packaging Type:
Packaging format selection directly interfaces with shelf-life engineering, portion control regulations, and sustainability certification demands across manufacturing footprints.
- Bags:Flexible film structures for multi-serve hard candy and gummy formats, with recyclable mono-material transitions accelerating under retailer sustainability mandates.
- Boxes:Rigid paperboard formats dominating seasonal gifting and premium chocolate presentation, with Quebec and Ontario markets requiring bilingual graphic design compliance.
- Tubs:Rigid plastic containers for bulk and sharing occasions, concentrated in warehouse club and value-oriented retail channels.
- Individual Wrappers:Primary packaging for portion-controlled and foodservice applications, with metallized films sustaining barrier properties for moisture-sensitive formulations.
Bags hold the dominant volume position, though boxes command the highest per-unit margin premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border trade flows in sugar confectionery remain relatively balanced between the United States and Canada, with Mexico emerging as a growing production hub serving North American retail networks. Import dependency for specialty cocoa derivatives and natural colorants sustains supply chain linkages with European and Latin American suppliers.
United States
Convenience store velocity in California, Texas, and New York metropolitan corridors drives single-serve format demand, with millennial and Gen-Z consumers accelerating quick-commerce adoption. FDA nutrition labeling mandates and added-sugar disclosure requirements constrain formulation architectures while creating transparency premiums for clean-label brands. Chicago and Pennsylvania manufacturing clusters concentrate chocolate and hard candy production, with regional processors retrofitting extrusion lines for allulose-based recipes.
Canada
Bilingual packaging compliance under Health Canada and CFIA protocols shapes portfolio rationalization toward simplified ingredient decks recognizable in both English and French. Quebec's confectionery processors face accelerated natural colorant substitution requirements to avoid front-of-package warning symbols. Toronto and Montreal distribution hubs serve as entry points for European premium brands targeting French-speaking demographics with certified clean-label positioning.
Mexico
Maquiladora manufacturing zones along the northern border states concentrate contract production for United States private-label programs, leveraging tariff-advantaged access under USMCA provisions. Mexican sugar beet and cane supply chains reduce raw material costs for regional processors serving cross-border retail channels. Guadalajara and Monterrey industrial corridors host expanding gummy and hard candy facilities targeting Hispanic consumer segments in southwestern United States markets.
California
State-level sugar taxation proposals and municipal health ordinances in Los Angeles and San Francisco metropolitan areas threaten volume erosion for conventional formulations. Functional gummy demand concentrates in Silicon Valley and coastal wellness corridors, with vitamins and adaptogens commanding premium shelf positioning. Sacramento's regulatory environment accelerates clean-label migration faster than national averages, compressing legacy recipe margins.
Texas
Houston and Dallas-Fort Worth distribution networks serve as southern United States fulfillment anchors for both retail and direct-to-consumer confectionery flows. Convenience store density along interstate corridors sustains impulse-purchase velocity for single-serve hard candy and gummy formats. State-level regulatory permissiveness relative to California attracts manufacturing investment from brands seeking formulation flexibility.
North America Sugar Confectionery Market Competitive Landscape
Concentration sits with diversified multinational food conglomerates controlling manufacturing footprints across multiple North American jurisdictions. Mars Incorporated, The Hershey Company, and Mondelēz International anchor volume leadership through distinct specialization vectors—chocolate mastery, diversified format coverage, and gummy innovation respectively. Mid-tier regional processors compete through seasonal gifting specialization and clean-label certification speed-to-market. Dominant competitive moves include portfolio diversification into functional ingredient integration and strategic partnerships with quick-commerce platforms bypassing traditional wholesale channels.
Within the multinational tier, Mars Incorporated, The Hershey Company, and Mondelēz International occupy positions exemplifying three distinct competitive archetypes. Mars represents diversified format scale with manufacturing depth across chocolate, gum, and sugar confectionery categories. The Hershey Company anchors chocolate specialization with controlled cocoa sourcing networks extending into West African growing regions. Mondelēz International exemplifies brand architecture diversification, competing aggressively in gummy and hard candy segments through acquired and organic portfolio development. These three entities collectively shape pricing benchmarks and slotting fee economics that constrain smaller regional competitors in United States and Canadian retail networks.
| Leading Market Players |
|---|
| Mars Incorporated |
| The Hershey Company |
| Mondelēz International Inc. |
| Ferrero International S.p.A |
| Perfetti Van Melle BV |
| Haribo GmbH & Co. |
| Ferrara Candy Company |
| Lindt & Sprüngli |
| Jelly Belly Candy Company |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for West African cocoa butter lock in both supply access and price visibility for chocolate-dependent manufacturers, insulating tier-one processors from spot-market volatility while compressing margin flexibility for mid-tier competitors lacking equivalent sourcing scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing across premium, standard, and economy tiers, with tier boundaries set by cocoa butter content percentage and clean-label certification status. Price differentiation hinges on USDA Organic tier and volume scale, with private-label programs commanding steepest discounts. Pricing pressure stems from allulose substitution costs as FDA disclosure mandates accelerate ingredient migration. Convenience store operators exhibit highest price sensitivity, while direct-to-consumer subscription buyers accept premium positioning.
Supply Chain Analysis
Côte d'Ivoire and Ghana anchor cocoa butter supply, with Ecuador and Brazil expanding fine-flavor sourcing for premium tiers. Manufacturing draws from beet sugar in United States Great Plains regions and cane sugar through Gulf Coast refineries. Single-source vulnerability concentrates in West African cocoa cooperatives exposed to weather-driven disruptions. Distribution runs through Chicago and Pennsylvania production clusters serving retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized confectionery technologists capable of low-moisture cooking process optimization and alternative sweetener rheology engineering represent the critical capability gap constraining clean-label migration timelines across North American manufacturing footprints.
For Market Incumbents: Fortify controlled cocoa sourcing networks through cooperative equity stakes in Côte d'Ivoire and Ghana, while accelerating extrusion line retrofit capacity to handle allulose-based recipes ahead of FDA enforcement waves. Vertical integration into domestic beet sugar processing hedges against tariff exposure on imported cane derivatives. For New Entrants and Emerging Players: Quick-commerce fulfillment gaps in Canadian French-speaking markets present immediate white-space opportunity, with Health Canada CFIA bilingual compliance infrastructure serving as barrier-to-entry moat against United States competitors. Direct-to-curated-subscription models targeting millennial gifting occasions bypass slotting fee economics entirely. For Investors and Strategic Acquirers: Regional processors with established clean-label certification speed-to-market and seasonal gifting specialization represent optimal acquisition targets for portfolio diversification into functional gummy segments. Watch for state-level sugar tax passage in California, Colorado, or Washington as inflection indicator for accelerated conventional formulation obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Allulose Formulation Migration | FDAs added-sugar disclosure mandates are forcing rapid recipe architecture overhaul across legacy manufacturing footprints. |
| Direct-to-Consumer Subscription Launch | Curated seasonal assortments bypass traditional retail slotting fees while capturing recurring millennial gifting revenue. |
| Canadian Bilingual Labeling Compliance | Health Canada CFIA protocols create first-mover positioning for clean-label products targeting underserved French-speaking demographics. |
| Regenerative Agriculture Certification | USDA Organic and emerging soil-health standards justify premium pricing for domestic beet sugar supply chain investments. |
| Quick-Commerce Platform Integration | TikTok Shop and Instagram checkout partnerships fragment traditional impulse-buy concentration in physical retail channels. |
Research Methodology
Desk research of FDA enforcement actions, Health Canada CFIA guidance documents, and United States customs trade data preceded structured interviews with confectionery technologists, retail category buyers, ingredient procurement managers, and regulatory affairs specialists. Primary fieldwork captured formulation migration timelines and slotting fee economics across convenience store and supermarket channels. Secondary validation drew from Nielsen retail audit data, SEC 10-K filings of publicly traded manufacturers, and cooperative sustainability reports. Bottom-up volume modeling triangulated against top-down category spend estimates.
Variance decomposition across product type, end-user demographic, distribution channel, and packaging format segmentation dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segment-level growth rate convergence modeling. Forecast inputs incorporated cocoa butter futures curve trajectories and state-level sugar tax proposal probability assessments.
Forecasts assume regulatory continuity in FDA nutrition labeling and Health Canada front-of-package symbol regimes; material policy shifts would require re-modeling of clean-label migration timelines and pricing tier boundaries. Cocoa supply disruption, allulose production capacity constraints, and quick-commerce platform algorithm changes represent specific revision triggers. Recalibration cycles align with material shifts in enforcement priorities and ingredient technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Milk Chocolate Market
Confectionery
South Africa Confectionery Market
Confectionery
Citrus Gummies Market
Confectionery
United Arab Emirates Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
North America Compound Chocolate Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Gum Base Candy Market
Confectionery
Chocolate Couverture Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Italy Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Cookie Dough Market
Confectionery
Boiled-Cooked Icing Market
Confectionery
Chocolate Spread Market