
 North America Compound Chocolate Market | 2026-2036
North America Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Compound Chocolate Market Analytics
A shift from single-source cocoa butter supply toward multi-source vegetable fat procurement is realigning how North American compound chocolate makers secure raw materials. Cargill, Incorporated leverages its integrated oilseed processing network to secure consistent shea and palm oil streams for coating formulations. Barry Callebaut sustains extensive technical service operations across U.S. and Canadian industrial bakeries. Blommer Chocolate Company anchors Midwest production capacity with direct rail-served facilities serving major confectionery accounts.
Compound chocolate denotes a cocoa-containing confectionery material where cocoa butter is partially or fully replaced by vegetable fats such as palm kernel oil or coconut oil, permitting melt profiles tuned to ambient stability and snap characteristics. Industrial users specify fat fractions and tempering curves to achieve gloss retention and clean mold release in automated enrobing lines. Milk chocolate formulations occupy the largest volume share across baking and confectionery applications where cost-positioned coatings replace couverture. Dark chocolate segments gain traction among specialty shops and premium snack producers seeking reduced-sugar positioning. Online retailers represent the fastest-expanding distribution channel as food manufacturers and artisan bakeries adopt direct procurement for specialized compound grades.
The FDA maintains standards of identity for chocolate and chocolate-flavored products that govern vegetable fat substitution limits and labeling disclosures across U.S. interstate commerce. Health Canada enforces parallel compositional requirements through its Food and Drug Regulations, creating a harmonized but distinct compliance landscape for cross-border suppliers. The USDA's bioengineered food disclosure standard and emerging state-level packaging regulations in California and New York add layered compliance obligations. Stakeholders must monitor evolving plant-based fat sourcing certifications and traceability mandates that will determine supplier qualification criteria and formulation flexibility across the North American supply base.
Market Dynamics
FDA labeling requirements for cocoa butter alternatives are tightening formulation standards across U.S. interstate commerce, forcing compound chocolate manufacturers to reformulate fat blends and redesign packaging disclosures ahead of enforcement windows.
Growth Catalysts
- Industrial Bakery Expansion:Food manufacturers across the U.S. Great Lakes corridor are scaling enrobed snack production, pulling compound chocolate volumes for automated coating lines.
- REACH-aligned Fat Certification:EU-equivalent traceability standards for palm and shea sourcing are opening export channels for North American suppliers into European confectionery accounts.
- Vegetable Fat Flexibility:Multi-source procurement of palm kernel and coconut oil fractions allows real-time melt profile tuning for seasonal ambient stability demands.
Market Restraints
- Input Cost Volatility:Palm oil price swings tied to Malaysian export duties compress margin predictability for coating-grade formulations.
- Supply Concentration Risk:Rail-served Midwest processing clusters create single-point vulnerability for major confectionery accounts dependent on just-in-time delivery.
- Technical Limitation:Vegetable fat crystallization behavior limits snap and gloss replication versus cocoa butter in premium positioning tiers.
Strategic Opportunities
- Canadian Regulatory Harmonization:Health Canada's parallel compositional standards create cross-border formulation efficiencies for suppliers operating dual U.S.-Canada production.
- Direct E-Commerce Procurement:Artisan bakeries and specialty snack producers are bypassing traditional distribution to source specialized compound grades online.
- Reduced-Sugar Positioning:Dark chocolate compound segments targeting specialty shops align with USDA dietary guidance and state-level sugar disclosure trends in California.
Industry Challenges
- Fat Chemistry Expertise Gap:Formulation chemists capable of tuning tempering curves for automated enrobing lines command scarcity premiums in Midwest labor markets.
- Compliance Timeline Compression:Overlapping FDA identity standards, USDA bioengineered disclosures, and emerging state packaging rules strain regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Compound Chocolate Market |
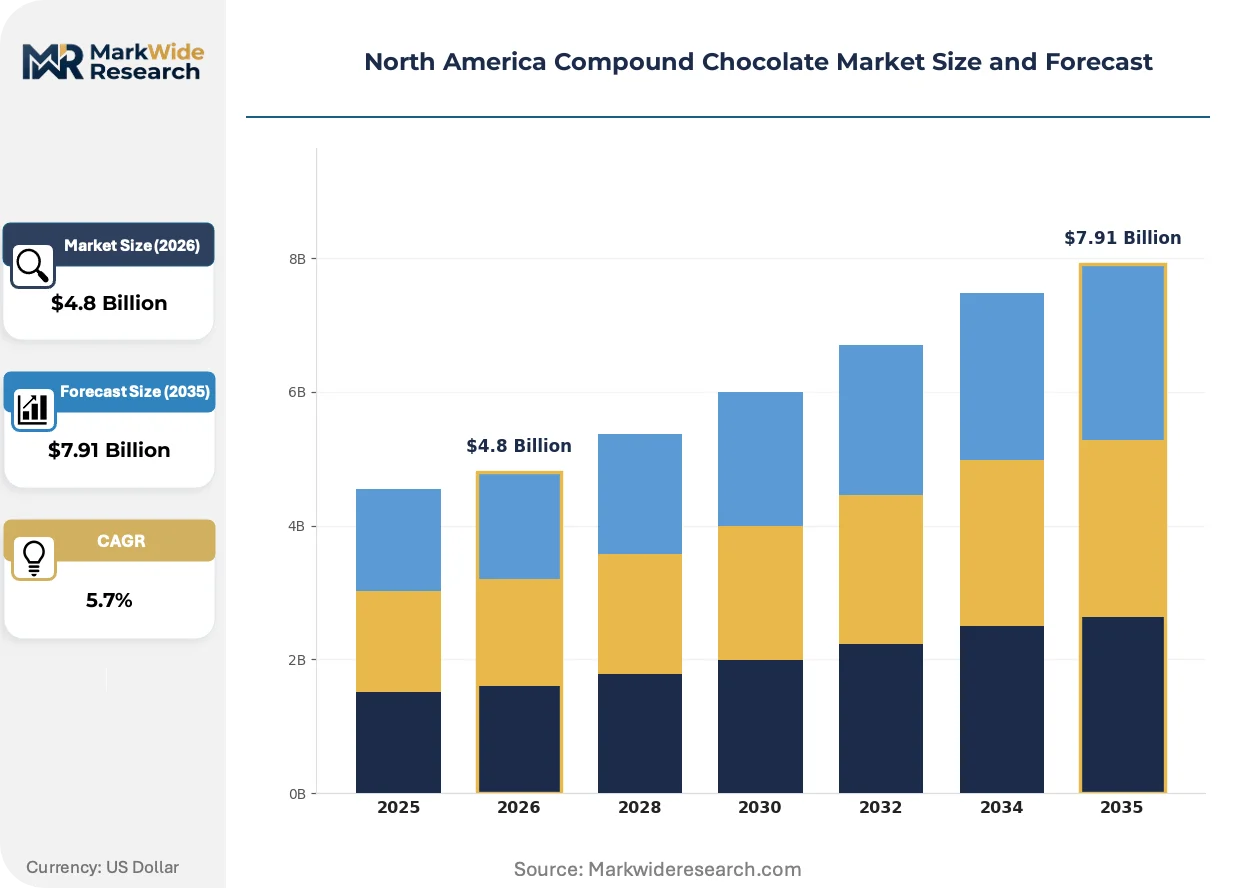
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Other Flavors Application: Baking, Confectionery, Snacks, Spreads Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Shops Customer Type: Retail Consumers, Food Manufacturers, Bakeries, Cafés |
| Companies Covered | Blommer Chocolate Company, Fuji Oil Holdings Inc., Barry Callebaut, Clasen Quality Chocolate, AAK AB, Cargill, Incorporated, The Hershey Company, Nestlé Professional, Puratos Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Compound Chocolate Market Evolving Landscape
Reformulation priorities are converging with traceability mandates and channel restructuring to reshape how compound chocolate moves from oilseed processing through finished confectionery.
Fractionation technology for vegetable fat blends is decentralizing production planning across North American compound chocolate makers. Industrial bakeries in Ontario and Illinois are adopting on-site fat tempering systems that bypass traditional centralized coating supply. This capability shift is compressing lead times for seasonal product launches and reducing frozen inventory exposure.
FDA standards of identity for chocolate-flavored products are tightening disclosure requirements for vegetable fat substitution limits. Manufacturers must now redesign labels to distinguish cocoa butter alternatives from true chocolate across interstate shipments. The U.S. enrobed snack segment is responding with dual-SKU strategies that segregate FDA-compliant formulations from export-oriented recipes.
Direct procurement patterns among artisan bakeries are fragmenting historical distributor relationships in the compound chocolate channel. Food manufacturers are building captive supplier portals that bypass regional ingredient distributors for specialized coating grades. This disintermediation is most visible in California and New York metropolitan markets where bakery density supports minimum order thresholds.
North America Compound Chocolate Market Segmentation
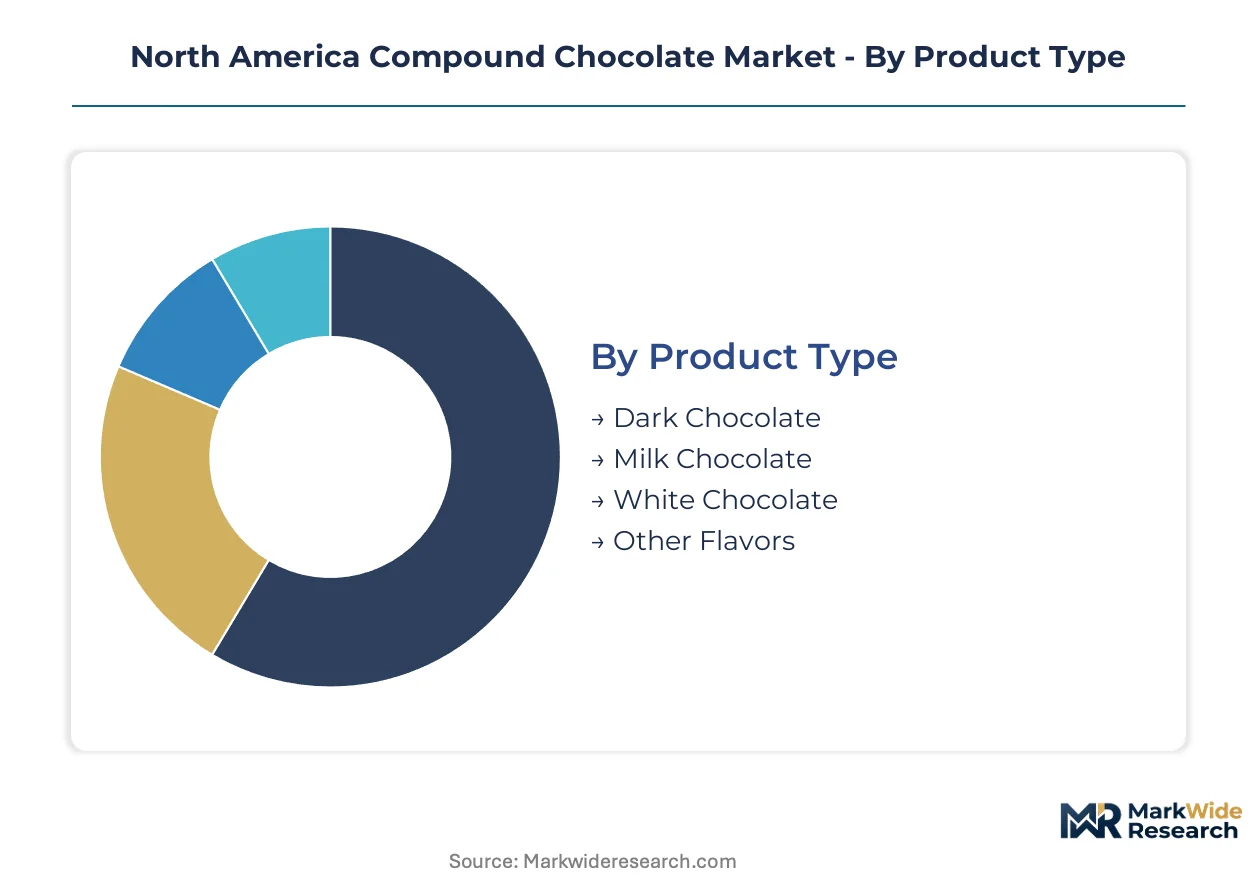
Compound chocolate formulation varies sharply by end-use thermal demands and finished product positioning. Industrial buyers specify fat crystallization profiles differently for automated enrobing versus artisan hand-dipping operations. Understanding segment boundaries clarifies where margin pools concentrate and where procurement patterns are fragmenting.
Product Type:
Customization intensity spans from standardized bulk coatings to precision-tempered specialty grades requiring exact snap and gloss specifications.
- Milk Chocolate:Dominant volume position combining cocoa solids with milk powder and vegetable fat matrices for cost-efficient enrobing. Demand concentrates in Midwest industrial bakeries serving mass-market snack accounts where FDA-compliant vegetable fat disclosure requirements shape label architecture.
- Dark Chocolate:Higher cocoa content formulations with reduced sugar positioning for premium snack producers. California and New York specialty shops drive specification intensity as state-level sugar disclosure mandates accelerate clean-label procurement.
- White Chocolate:Cocoa butter-free formulations relying entirely on milk solids and vegetable fat blends for coating applications.
- Other Flavors:Seasonal and novelty variants incorporating inclusions or flavor systems for limited-run confectionery.
Most installed capacity flows through Milk Chocolate. Expansion is steepest in Dark Chocolate.
Application:
Volume scale and margin structure diverge sharply between commodity-scale industrial runs and precision-batch artisan production.
- Confectionery:Automated enrobing lines in U.S. Great Lakes processing clusters demand consistent melt profiles and rapid crystallization for high-throughput molding. FDA standards of identity compliance adds formulation complexity for interstate shipment qualification.
- Baking:Fillings and inclusions for industrial bakeries require ambient stability through distribution cycles. Ontario and Illinois facilities specify fat fractions tuned to frozen storage compatibility and thaw recovery performance.
- Snacks:Compound coatings for puffed and extruded bases where snap and adhesion compete with cost positioning.
- Spreads:Lower-viscosity formulations for jarred applications requiring spreadability at refrigerated temperatures.
Confectionery commands the largest share of installed coating capacity. Snack applications are expanding most quickly as enrobed formats proliferate.
Distribution Channel:
Channel economics reflect order minimum thresholds and technical service intensity required for compound grade specification.
- Online Retailers:Direct procurement portals allowing artisan bakeries to bypass regional distributors for specialized fat blends. California and New York metropolitan markets support minimum order viability through bakery density and consolidated delivery routing.
- Supermarkets:Mass retail shelf presence for consumer-packaged compound chocolate requiring standard formulation and national distribution scale.
- Convenience Stores:Impulse-oriented pack sizes with extended ambient shelf stability specifications.
- Specialty Shops:High-touch technical consultation for custom tempering curve development and small-batch sourcing.
Supermarkets retain the deepest penetration of existing supply relationships. Online Retailers are climbing the fastest as disintermediation accelerates.
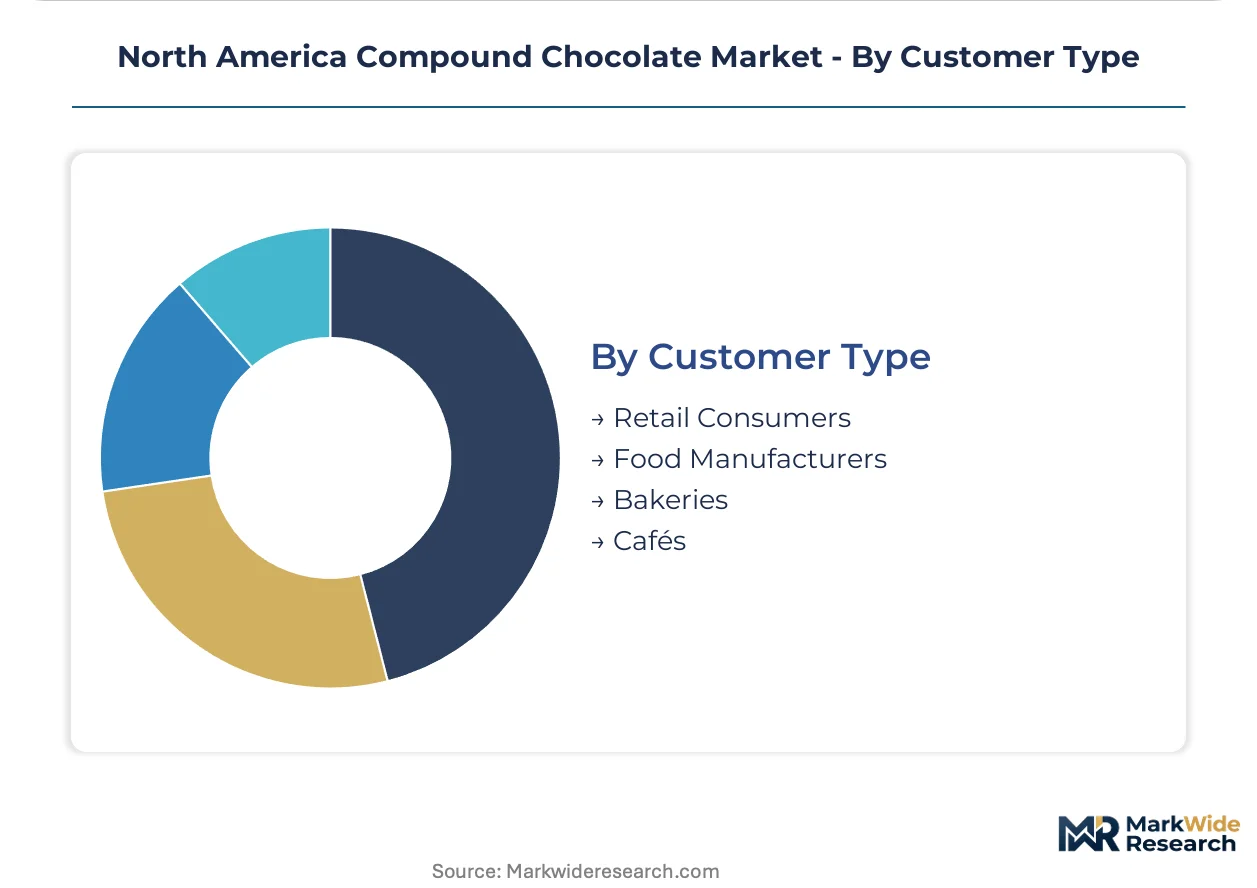
Customer Type:
Procurement sophistication ranges from specification-driven industrial buyers to price-sensitive food service operators.
- Food Manufacturers:Automated coating line operators in U.S. Great Lakes and Canadian industrial corridors demanding consistent fat supply and technical troubleshooting support. Rail-served Midwest facilities prioritize just-in-time delivery reliability over unit cost minimization.
- Bakeries:Mid-scale operators balancing formulation flexibility with volume pricing, increasingly adopting on-site fat tempering systems to compress lead times.
- Retail Consumers:Supermarket and online purchasers of finished compound chocolate products with limited formulation visibility.
- Cafés:Small-batch users requiring melt-and-use convenience with minimal tempering expertise.
Food Manufacturers absorb the majority of industrial compound volume. Bakeries are gaining share fastest as captive tempering capabilities expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Great Lakes industrial corridor anchors North American compound chocolate demand through clustered confectionery processing facilities serving retail and export channels. FDA labeling requirements for cocoa butter alternatives reshape formulation standards across U.S. interstate commerce. Health Canada enforces parallel compositional rules, creating a harmonized compliance landscape for cross-border suppliers.
United States
Midwest industrial bakeries in Illinois and Ohio scale enrobed snack production, pulling compound chocolate volumes for automated coating lines. FDA standards of identity govern vegetable fat substitution limits and labeling disclosures across interstate shipments. The Great Lakes processing cluster concentrates rail-served facilities where just-in-time delivery reliability dominates procurement decisions over unit cost minimization.
Canada
Ontario food manufacturers expand procurement of compound chocolate for bakery fillings and frozen dessert applications. Health Canada's Food and Drug Regulations enforce compositional requirements distinct from but parallel to FDA rules, creating dual compliance obligations. Toronto-area industrial bakeries adopt on-site fat tempering systems that compress lead times for seasonal product launches.
Mexico
Confectionery processors in Mexico City and Monterrey absorb compound chocolate for cost-positioned coatings serving domestic retail and U.S. export accounts. The country's national food safety regulator enforces labeling standards for vegetable fat disclosures in chocolate-flavored products. Bajío Region snack manufacturers specify palm kernel oil blends tuned to ambient stability through distribution cycles.
North America Compound Chocolate Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and supply chain proximity in the North American compound chocolate market. The structure concentrates around integrated oilseed processors and specialized confectionery ingredient suppliers, with tiered differentiation by technical service intensity and fat chemistry capabilities. Three archetypes dominate: multinational agribusinesses with captive vegetable oil supply, European-headquartered chocolate specialists with extensive U.S. technical operations, and Midwest-anchored regional producers with rail-served distribution advantages. Competitive moves center on backward integration into oilseed processing and geographic expansion of technical service footprints.
Among integrated agribusinesses, Cargill, Incorporated and Barry Callebaut occupy positions defined by supply chain control and formulation support scale. Cargill exemplifies the oilseed-integrated archetype through its network of shea and palm oil streams. Barry Callebaut represents the European-specialist model with extensive U.S. and Canadian technical service operations. Blommer Chocolate Company anchors the regional-producer tier with Midwest production capacity and direct rail access serving major confectionery accounts.
| Leading Market Players |
|---|
| Blommer Chocolate Company |
| Fuji Oil Holdings Inc. |
| Barry Callebaut |
| Clasen Quality Chocolate |
| AAK AB |
| Cargill, Incorporated |
| The Hershey Company |
| Nestlé Professional |
| Puratos Group |
| Others |
Value Network & Pricing Analysis
EU-equivalent traceability standards for palm and shea sourcing are gating qualified supply access for North American compound chocolate manufacturers while simultaneously stratifying premium-tier pricing for REACH-aligned certification holders. FDA labeling requirements for cocoa butter alternatives compress formulation flexibility, forcing suppliers to absorb compliance costs or pass them through to industrial bakery accounts.
Pricing Analysis
Input-cost pass-through from Malaysian palm oil export duty volatility shapes margin predictability across coating-grade formulations. Contract-based long-term offtake agreements dominate volume procurement for Great Lakes industrial bakeries, while spot-market exposure concentrates among artisan bakery segments. Price differentiation rests on REACH-aligned fat certification and automated enrobing technical support tiers. Cost compression in standard-grade milk chocolate compounds is intensifying as rail-served Midwest facilities compete on delivery reliability rather than unit cost alone. Food manufacturers with captive tempering capabilities exhibit lowest price sensitivity; small-batch specialty shops show highest.
Supply Chain Analysis
Direct-to-industrial-bakery channels handle hyperscale buyer demand across the U.S. Great Lakes corridor and Ontario processing clusters. Raw material supply concentrates in Malaysia and Indonesia for palm kernel oil fractions, West Africa for shea butter, and the Philippines for coconut oil derivatives. Rail-served Midwest facilities create single-point vulnerability for just-in-time delivery-dependent confectionery accounts. Distribution runs through integrated oilseed processors with captive vegetable fat supply and specialized confectionery ingredient distributors with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America compound chocolate market functions as a geographic-arbitrage play where Health Canada's parallel compositional standards create cross-border formulation efficiencies against FDA disclosure requirements.
For Market Incumbents: Anchor rail-served production capacity in the Midwest industrial corridor to defend against emerging on-site fat tempering adoption by Ontario and Illinois bakeries. Deepen backward integration into shea and palm oil fractionation to secure supply continuity amid Malaysian export duty volatility. Prioritize REACH-aligned certification investment to maintain premium-tier pricing access for European export channels. For New Entrants and Emerging Players: The premium-to-economy price-point gap in dark chocolate compounds for California and New York specialty shops offers white-space entry. Target direct e-commerce procurement channels where bakery density supports minimum order thresholds and disintermediation is fragmenting historical distributor relationships. Pursue reduced-sugar positioning aligned with state-level sugar disclosure mandates as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional producers lacking integrated oilseed supply but holding rail-served Midwest production assets. Long-term viability over the mid-term projection horizon favors acquisition targets with captive tempering technical capabilities and Health Canada dual-compliance infrastructure. Watch for FDA enforcement window acceleration as the inflection signal for compliance-cost consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's shea and palm oil network secures consistent supply streams for coating formulations. |
| REACH-Aligned Fat Certification Program | EU-equivalent traceability standards open export channels for North American suppliers into European confectionery accounts. |
| Direct E-Commerce Procurement Portal | Food manufacturers bypass regional distributors for specialized compound grades in California and New York markets. |
| On-Site Fat Tempering System Deployment | Ontario and Illinois industrial bakeries compress lead times for seasonal product launches. |
| Dual U.S.-Canada Formulation Harmonization | Cross-border production efficiencies emerge from parallel FDA and Health Canada compliance structures. |
Research Methodology
Bottom-up industrial bakery and confectionery processor modeling reconciled against top-down oilseed processing and vegetable fat trade tracking forms the analytical core of this study. Primary interviews with formulation chemists, procurement leads at major confectionery accounts, rail logistics coordinators, and regulatory affairs specialists combined with secondary validation from FDA standards of identity filings, Health Canada Food and Drug Regulations, USDA bioengineered food disclosure records, and Malaysian Palm Oil Board export duty data. Triangulation across supply-side capacity assessments and demand-side coating line expansion plans ensures cross-verified volume estimates.
Historical trendline analysis of enrobed snack production growth and compound chocolate procurement patterns informed the projection framework across the analysis window. Segmentation modeling spans product type, application, distribution channel, and customer type dimensions, with additional granularity on fat crystallization profile specifications. CAGRs derive from regression-weighted capacity expansion schedules and seasonal ambient stability demand cycles. Palm oil price volatility indices and FDA enforcement timeline scenarios serve as key forecast sensitivity inputs.
The model assumes a particular technology adoption path for on-site fat tempering systems; alternative pathways for decentralized fractionation capability would alter the outlook for centralized coating supply economics. Forecasts reflect documented assumptions regarding REACH-aligned certification adoption rates and Health Canada-FDA harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
US Confectionery Market
Confectionery
Chocolate Flavors Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Global Compound Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Global Candy Market
Confectionery
Ruby Chocolate Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Infused Fruits Jellies Market
Confectionery
UK Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Gummy Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Italy Chocolate Market