
 Bean-To-Bar Chocolate Market | 2026-2036
Bean-To-Bar Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Bean-To-Bar Chocolate Market Analysis
Craft cocoa processing capacity in Ecuador and Madagascar is hardening as small-batch roasters expand fermentation infrastructure. Dandelion Chocolate leverages direct-trade relationships with Ecuadorian cooperatives to secure rare heirloom varietals. Askinosie Chocolate sustains its competitive edge through in-house production of every supply chain stage from bean sorting to wrapping. Taza Chocolate differentiates via its stone-ground texture and certified organic sourcing protocols that appeal to transparency-focused buyers.
Bean-to-bar chocolate denotes chocolate manufactured entirely within a single facility where raw cacao beans undergo roasting, winnowing, grinding, conching, and tempering without intermediate outsourcing, typically maintaining cacao content above 70% in dark formulations for craft-grade designation. The product exists to deliver terroir-specific flavor expression and supply chain transparency unavailable in industrial couverture. Dark chocolate occupies the dominant revenue position due to consumer association with antioxidant properties and minimal processing, while flavor profiles centered on fruity and nutty notes capture the fastest-growing segment as palates shift toward origin-distinguished tasting experiences. Distribution through specialty stores and direct sales channels commands the highest margin pools by eliminating wholesale intermediaries.
FDA food labeling requirements and the EU Deforestation Regulation compel bean-to-bar producers to document farm-level traceability and allergen declarations, elevating compliance costs for smaller makers while creating market access barriers for non-compliant imports. Organic certification under USDA National Organic Program and EU organic standards further segments pricing tiers and retail placement eligibility. Stakeholders must monitor evolving deforestation due diligence mandates and origin-country export certification changes to maintain supply continuity and premium positioning.
Market Dynamics
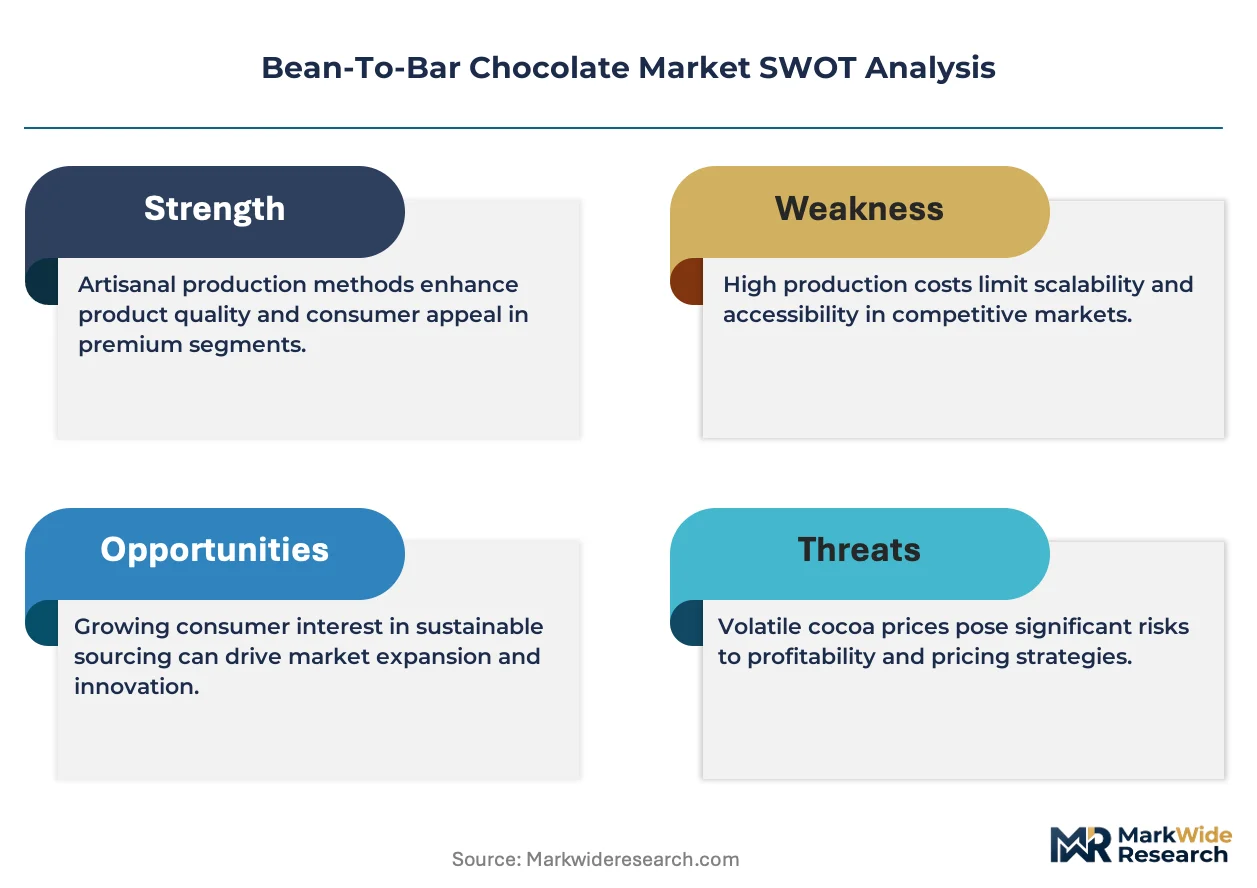
The EU Deforestation Regulation (EUDR) is forcing bean-to-bar makers to rebuild traceability infrastructure from farm to finished bar, compressing margins for small-batch producers while advantaging those with existing direct-trade relationships in verified origins.
Growth Catalysts
- Specialty café channel expansion:Independent coffee shops in Berlin, Melbourne, and Portland are dedicating retail space to single-origin chocolate pairings, creating dedicated shelf space for craft makers.
- EUDR traceability mandates:European regulatory pressure for farm-level GPS documentation is accelerating investment in blockchain-verified sourcing platforms among compliance-ready producers.
- Fermentation infrastructure:Controlled microbial inoculation protocols in Ecuador and Madagascar are enabling reproducible flavor profiles that secure long-term buyer contracts.
Market Restraints
- Cocoa butter price volatility:Weather-driven supply interruptions in West Africa inflate input costs for makers maintaining high cacao-content formulations.
- Heirloom varietal concentration:Nacional cacao availability depends on a narrow corridor of Ecuadorian highland cooperatives, creating single-source vulnerability.
- Small-batch equipment scarcity:Limited manufacturers of 50-200kg capacity roasters and conches extend lead times for capacity expansion.
Strategic Opportunities
- Japanese specialty retail penetration:Tokyo's depachika basement food halls present underexposed placement opportunities for origin-story-driven packaging.
- USDA Organic certification arbitrage:Dual-certified EU-US organic supply chains command placement premiums in American natural grocery channels.
- Direct-to-subscription channel development:Quarterly tasting clubs bypass wholesale margin compression while building predictable revenue streams.
Industry Challenges
- Conching technician scarcity:The specialized sensory judgment required for 72-hour flavor development cycles lacks formal training pipelines.
- Multi-certification timeline compression:Simultaneous pursuit of organic, fair trade, and deforestation-free credentials strains administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bean-To-Bar Chocolate Market |
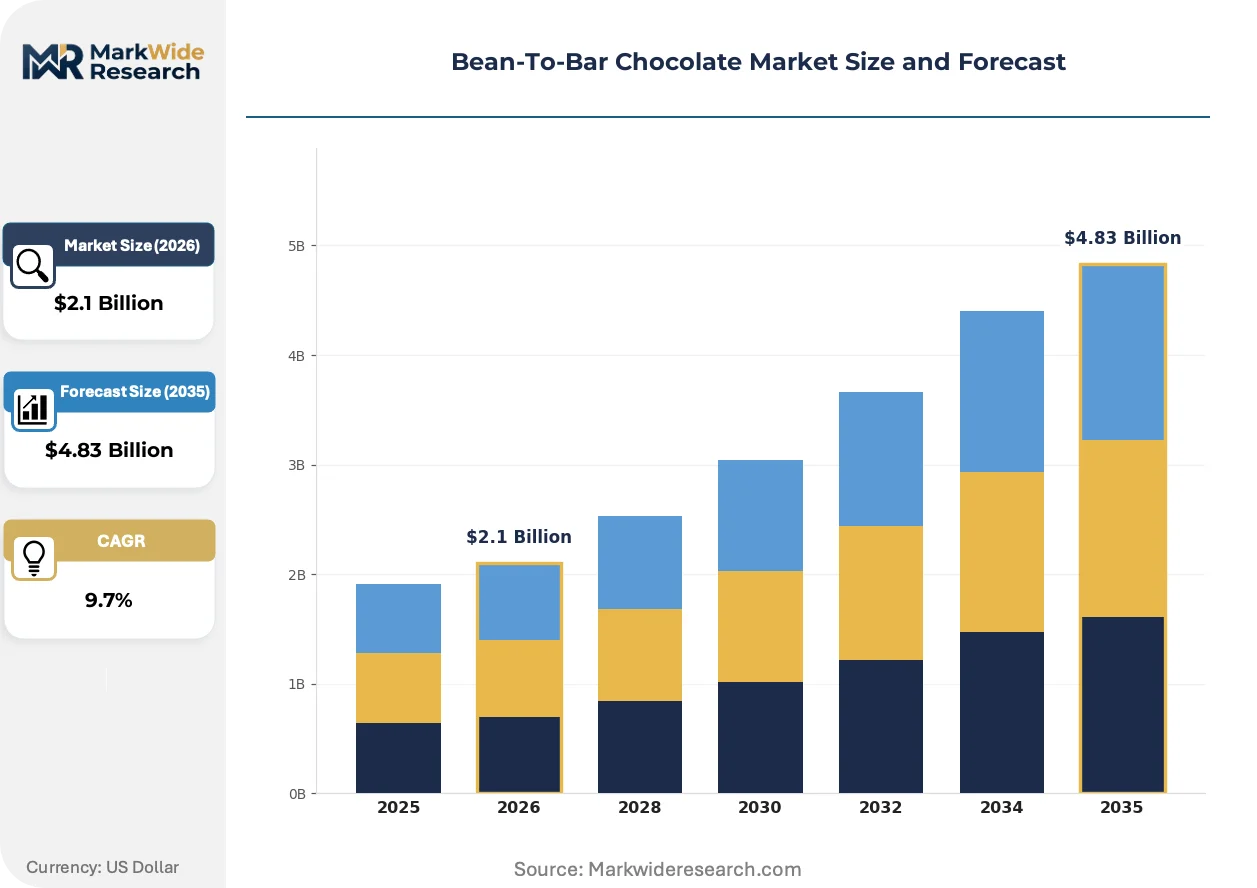
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.83 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Customers, Food Service, Bakeries, Confectioneries Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Flavor Profile: Fruity, Nutty, Spicy, Herbal |
| Companies Covered | Dandelion Chocolate, Askinosie Chocolate, Ritual Chocolate, Taza Chocolate, Amano Artisan Chocolate, Patric Chocolate, Goodnow Farms, Raaka Chocolate, Mast Brothers Chocolate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bean-To-Bar Chocolate Market Emerging Trajectories
Processing technology and sourcing verification methods are diverging sharply between industrial-scale efficiency optimization and craft-scale terroir preservation, with regulatory compliance costs accelerating this bifurcation.
Micro-lot roasting systems with programmable temperature curves and real-time humidity sensing are modularizing production workflows for makers operating below 500kg weekly throughput. Small-batch producers in Copenhagen and São Paulo are adopting these units to isolate fermentation-lot variables without dedicated engineering staff. This modularization is compressing the capital barrier between home-scale equipment and commercial viability, enabling faster market entry for new origin-focused brands.
The EU Deforestation Regulation's due diligence requirements are mandating geolocation tagging and supplier risk assessments for all cocoa imports into European customs territory. Bean-to-bar makers must now maintain satellite-verified farm boundary records and annual third-party audits to maintain market access. Dark chocolate SKUs with existing direct-trade documentation are capturing shelf space from traders reliant on aggregated commodity sourcing.
Subscription-based tasting clubs are displacing traditional specialty retail as the primary discovery channel for origin-differentiated bars among affluent urban consumers. These direct relationships capture full retail margin while generating batch-specific feedback that informs subsequent sourcing decisions. This channel rotation is most pronounced in North American and Australian metropolitan markets where courier infrastructure supports temperature-controlled delivery.
Bean-To-Bar Chocolate Market Segmentation
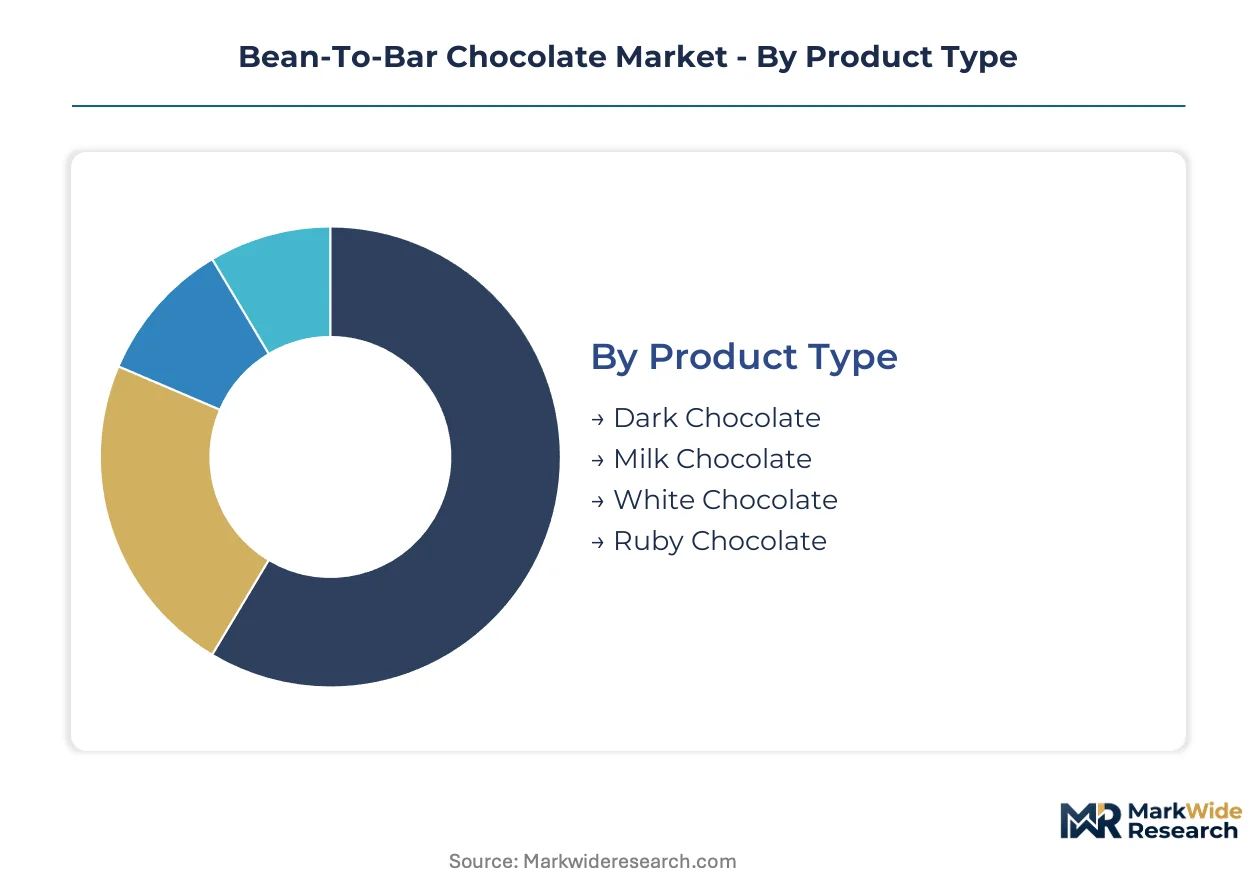
Bean-to-bar chocolate segmentation reveals how craft producers align product architecture with distinct buyer readiness levels and channel economics. Each dimension—product formulation, end-use application, route-to-market, and sensory positioning—carries different margin profiles and compliance burdens that reshape competitive strategy.
Product Type:
Upgrade cycles in craft chocolate track consumer sophistication trajectories, with buyers typically migrating from entry milk formats toward high-cacao expressions as palate education deepens.
- Dark Chocolate:Formulations maintaining 70% or higher cacao content dominate craft-grade positioning through minimal processing and antioxidant associations. Demand concentrates in specialty cafés across Berlin, Melbourne, and Portland where single-origin pairings command premium shelf placement; EUDR traceability mandates favor makers with existing direct-trade documentation in verified origins.
- Milk Chocolate:Lower cacao percentages with added dairy solids attract entry-level craft buyers transitioning from industrial confectionery. Bakeries in Copenhagen and São Paulo specify these formats for dessert applications where sweetness balance matters; cocoa butter price volatility in West African supply corridors squeezes margin on high-dairy formulations.
- White Chocolate:Cacao butter-based expressions without cocoa solids occupy niche gifting and pastry chef channels.
- Ruby Chocolate:Pink-hued varietals from specific cacao cultivars target novelty-seeking urban consumers in Tokyo depachika halls.
Volume placements concentrate in Dark Chocolate; the faster expansion belongs to Ruby Chocolate.
End User:
Cost tier stratification separates commodity-scale buyers from origin-story-driven procurement, with certification requirements widening the spend gap between mass food service and premium retail.
- Retail Customers:Direct purchasers seeking terroir transparency and supply chain narrative for personal consumption or gifting. Subscription tasting clubs in North American and Australian metropolitan markets capture full retail margin from this segment; temperature-controlled courier infrastructure enables batch-specific feedback loops that inform subsequent sourcing decisions.
- Food Service:Restaurants and hotels sourcing chocolate for plating and beverage applications. Independent coffee shops dedicate expanding retail space to single-origin pairings; specialty café channel growth in Berlin, Melbourne, and Portland creates dedicated shelf access for craft makers with documented provenance.
- Bakeries:Pastry operations requiring consistent tempering behavior and flavor stability at volume.
- Confectioneries:Artisan candy producers blending bean-to-bar inputs with in-house confections.
Margin capture peaks with Retail Customers; Food Service delivers the steepest expansion trajectory through café channel partnerships.
Distribution Channel:
Geographic reach constraints and cold-chain requirements segment channel viability, with direct models favoring urban density and retail placement demanding compliance certification depth.
- Online Retail:E-commerce platforms enabling temperature-controlled fulfillment to dispersed buyers. Quarterly subscription clubs bypass wholesale margin compression while building predictable revenue; blockchain-verified sourcing platforms satisfy EUDR documentation requirements for European customs clearance.
- Direct Sales:Producer-controlled channels including factory stores, farmers markets, and tasting events. Specialty stores and direct sales command the highest margin pools by eliminating wholesale intermediaries; GPS-tagged farm boundary records satisfy EU Deforestation Regulation due diligence for customs territory access.
- Supermarkets:Mass retail placement requiring scale consistency and promotional investment.
- Specialty Stores:Curated independent retailers prioritizing origin narrative and certification density.
Profitability concentrates in Direct Sales; Online Retail is climbing the fastest through subscription infrastructure.
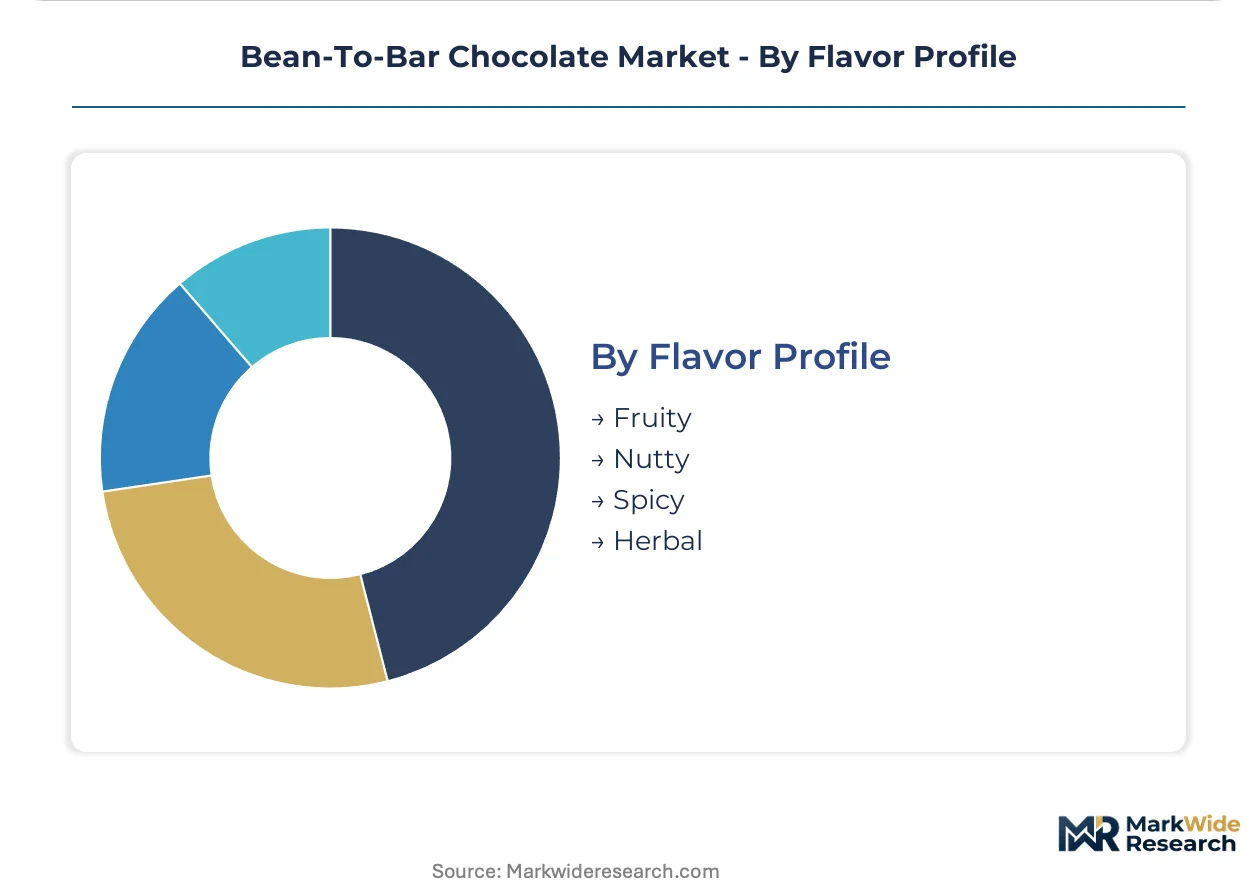
Flavor Profile:
Supply concentration in specific fermentation corridors creates flavor availability hierarchies, with microbial protocol reproducibility determining contract security for preferred taste directions.
- Fruity:Bright acidity and berry notes derived from short fermentation cycles in Ecuadorian and Peruvian highland cacao. Controlled microbial inoculation protocols in Ecuador and Madagascar enable reproducible profiles that secure long-term buyer contracts; origin-specific single-estate bars from these regions gain premium positioning in Japanese and Australian specialty retail.
- Nutty:Roasted, caramelized characteristics from extended Maillard development during processing. Palates in affluent urban markets shift toward origin-distinguished tasting experiences; flavor profiles centered on nutty notes expand alongside fruity expressions as craft education penetrates new buyer cohorts.
- Spicy:Pepper and warm spice notes from specific varietals and post-harvest handling.
- Herbal:Botanical, tea-like expressions from rare heirloom cultivars with limited availability.
Contract security runs strongest for Fruity; Nutty is gaining share fastest as roasting technique education spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecuadorian Nacional cacao anchors the raw-material foundation for premium bean-to-bar production, with highland cooperatives supplying heirloom varietals to craft makers worldwide. Madagascar and Peru follow as concentrated fermentation corridors, while consumption gravity shifts toward urban specialty retail clusters in North America, Europe, and East Asia.
United States
Independent coffee shops in Portland, Brooklyn, and Los Angeles dedicate expanding retail space to single-origin chocolate pairings. FDA food labeling requirements compel farm-level traceability documentation and allergen declarations for all cocoa imports. The Pacific Northwest hosts the densest concentration of small-batch roasters, where controlled fermentation partnerships with Ecuadorian cooperatives secure flavor reproducibility.
Germany
Berlin's specialty café channel drives demand for high-cacao dark formulations among transparency-focused consumers. The EU Deforestation Regulation mandates geolocation tagging and annual third-party audits for all cocoa entering European customs territory. Bavarian chocolate ateliers leverage direct-trade relationships to bypass aggregated commodity sourcing and maintain EUDR compliance.
Japan
Tokyo's depachika basement food halls present underexposed placement opportunities for origin-story-driven packaging and single-estate bars. METI standards for food import documentation align with EU traceability protocols, easing market entry for certified producers. The Kanto region concentrates specialty retail demand, with Osaka and Nagoya following as secondary craft chocolate adoption corridors.
Australia
Metropolitan tasting clubs in Sydney and Melbourne displace traditional specialty retail as the primary discovery channel for origin-differentiated bars. The country's national food regulator enforces strict import documentation for cocoa products, including allergen and origin verification. Temperature-controlled courier infrastructure enables subscription-based direct sales with full retail margin capture.
Switzerland
Geneva and Zurich specialty retailers prioritize certification density and supply chain narrative for affluent gifting segments. Swissmedic-aligned food safety protocols exceed baseline EU requirements, creating placement barriers for non-compliant imports. The Mittelland region hosts chocolate research institutions that advance fermentation science for craft producers.
Bean-To-Bar Chocolate Market Vendor Landscape
Global majors compete with regional champions across traceability infrastructure and direct-trade relationship depth. The vendor base organizes into three tiers: vertically integrated heritage makers with captive fermentation partnerships, mid-scale specialists operating modular small-batch equipment, and emerging origin-focused brands leveraging subscription channels. Consolidation pressure concentrates among EUDR-compliant producers with existing GPS-verified farm documentation. Dominant competitive moves include backward integration into Ecuadorian and Madagascar fermentation infrastructure and geographic expansion through Japanese and Australian specialty retail placement.
Within the vertically integrated heritage tier, Dandelion Chocolate and Askinosie Chocolate exemplify archetypes of supply chain control. Dandelion Chocolate represents the direct-trade partnership model, securing rare heirloom varietals through cooperative relationships in verified origins. Askinosie Chocolate anchors the in-house production archetype, maintaining competitive positioning through captive supply of every processing stage from bean sorting to finished bar wrapping.
| Leading Market Players |
|---|
| Dandelion Chocolate |
| Askinosie Chocolate |
| Ritual Chocolate |
| Taza Chocolate |
| Amano Artisan Chocolate |
| Patric Chocolate |
| Goodnow Farms |
| Raaka Chocolate |
| Mast Brothers Chocolate |
| Others |
Supply Flow & Price Mechanics
Cocoa butter costs from West African supply corridors cascade through three-tier pricing structures across premium, standard, and economy levels, with EUDR-compliant direct-trade bars commanding placement premiums over aggregated commodity sourcing in European specialty retail channels.
Pricing Analysis
Certification-bundled pricing separates EUDR-verified origin bars from uncertified alternatives, with organic and deforestation-free credentials unbundled as standard in premium tiers but charged as add-ons in economy positioning. Price differentiation rests on traceability documentation depth and fermentation-lot exclusivity. Pricing pressure stems from cocoa butter volatility in Ghana and Côte d'Ivoire squeezing high-cacao formulations. Food service buyers in specialty cafés exhibit lowest price sensitivity; entry-level milk chocolate retail purchasers show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Antwerp and Hamburg consolidate bean shipments from Ecuador, Madagascar, and Peru before final-mile dispatch to craft makers. Supply draws from heirloom Nacional cacao in Ecuadorian highlands, Trinitario varietals in Madagascar, and criollo-dominant lots in Peruvian Amazonas. Single-source vulnerability concentrates in Ecuadorian cooperative corridors. Distribution runs through direct-trade relationships bypassing commodity exchanges, with temperature-controlled logistics mandatory for finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Deforestation Regulation erects a compliance moat that advantages producers with existing GPS-verified farm documentation while marginalizing traders dependent on opaque commodity sourcing.
For Market Incumbents: To counter margin compression from EUDR audit costs, deepen backward integration into Ecuadorian and Madagascar fermentation infrastructure while locking multi-year offtake agreements with verified cooperatives. Channel control through proprietary subscription platforms captures full retail margin and builds predictable revenue insulation. For New Entrants and Emerging Players: Enter via Tokyo depachika placement and Australian metropolitan tasting clubs, the least penetrated high-value channels for origin-story-driven packaging. Target Japanese specialty retail through METI-aligned documentation and dual EU-Japan organic certification. Launch through quarterly subscription clubs to bypass wholesale margin compression while generating batch-specific consumer feedback. For Investors and Strategic Acquirers: EUDR compliance deadline acceleration is the leading indicator that GPS-verified direct-trade relationships will command acquisition premiums over commodity-dependent assets. Over the analysis window, vertically integrated makers with captive fermentation partnerships represent the most defensible acquisition archetype. Watch for blockchain-verified sourcing platform adoption rates as the signal of operational readiness for regulatory enforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive supply of controlled microbial protocols in Ecuador and Madagascar secures reproducible flavor profiles and long-term buyer contracts. |
| Blockchain-Verified Sourcing Platform Deployment | EUDR-mandated geolocation tagging and third-party audit trails satisfy EU customs due diligence requirements for market access. |
| Direct-to-Subscription Channel Development | Quarterly tasting clubs in North American and Australian metropolitan markets bypass wholesale intermediaries and capture full retail margin. |
| Dual Organic Certification Arbitrage | USDA-EU organic supply chains command placement premiums in American natural grocery and Japanese specialty retail channels. |
| Japanese Depachika Retail Penetration | Tokyo basement food halls present underexposed shelf space for origin-story-driven packaging and single-estate bar positioning. |
Methodological Framework
Trade databases, customs records, and cooperative export documentation formed the secondary backbone, cross-referenced with primary interviews involving bean-to-bar makers, specialty café procurement leads, fermentation facility operators, and organic certification auditors. Bottom-up and top-down triangulation validated volume estimates across origin countries and end-use channels.
Bottom-up modeling aggregated individual maker capacity and direct-trade offtake volumes, while top-down analysis calibrated against cocoa grind statistics and specialty chocolate import flows. Segmentation dimensions spanned product formulation, flavor profile, distribution channel, and end-user application. CAGRs derived from regression analysis of historical specialty chocolate premiumization trends and regulatory compliance cost trajectories, with inputs including EUDR implementation timelines and fermentation infrastructure investment cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under cocoa butter price spikes, EUDR enforcement delays, or heirloom varietal crop failures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Bangladesh Candy Market
Confectionery
South America Compound Chocolate Market
Confectionery
Low Calorie Treats Market
Confectionery
Europe Dark Chocolate Market
Confectionery
India Industrial Chocolate Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Europe Chocolate Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
UK Chocolate Market
Confectionery
Macarons Market
Confectionery
Confectionery Fillings Market
Confectionery
Gum Base Candy Market
Confectionery
Premium Chocolate Market
Confectionery
North America Confectionery Market
Confectionery
North America Sugar-Free Chewing Gum Market
Confectionery
Cocoa and Chocolate Market