
 Macarons Market | 2026-2036
Macarons Market Size, Share, and Industry Trends Forecast 2026-2036
Macarons Market Intelligence
EU Green Deal food sustainability targets are consolidating procurement standards across European luxury confectionery, forcing ingredient traceability and carbon footprint disclosure. Pierre Hermé Paris leverages its vertically integrated almond supply from Provence to sustain premium positioning. La Maison du Chocolat anchors its macaron line through controlled distribution in flagship boutiques across Paris, London, and Tokyo. TWG Tea Company differentiates by pairing macarons with its tea salon concept, occupying a niche at the intersection of patisserie and beverage retail.
A macaron is a meringue-based confection composed of almond flour, egg whites, and granulated sugar, with two shells sandwiching a flavored ganache, buttercream, or jam filling; the shells develop their characteristic smooth dome and ruffled "pied" foot through precise macaronage folding and controlled humidity drying before baking at 140-160°C. The product serves both direct consumption and premium gifting segments where visual presentation and shelf stability determine commercial viability. Premium product type commands the deepest margin pools due to ingredient provenance requirements and limited batch production, while vegan formulations represent the fastest-expanding category as plant-based meringue alternatives using aquafaba or potato protein achieve structural parity. Fruit flavor profile outpaces chocolate in seasonal rotation velocity, particularly in Asian markets where lighter palates dominate gifting occasions.
FDA food facility registration and EU REACH compliance on food contact materials shape cross-border macaron trade, with EFSA additive approvals determining colorant permissibility in European formulations. France's DGCCRF enforces strict appellation-style labeling on "macaron de Paris," creating market access barriers for non-compliant imports. Stakeholders must monitor evolving clean-label mandates and cold-chain energy regulations to secure shelf placement in premium retail channels.
Market Dynamics
The EU F-Gas Regulation phase-down is compressing cold-chain energy costs for almond-based confectionery, forcing operators toward natural refrigerants and rewiring distribution economics across temperature-sensitive luxury bakery segments.
Growth Catalysts
- EU Green Deal food sustainability targets:Procurement standards now mandate ingredient traceability and carbon footprint disclosure, consolidating supplier bases toward certified almond provenance.
- Gifting culture expansion:Premium bakery chains across the Middle East are broadening macaron assortments as boxed confectionery replaces traditional sweets in ceremonial exchange.
- Aquafaba meringue stabilization:Plant-based protein alternatives achieve structural parity with egg-white formulations, unlocking vegan category expansion without shell-texture compromise.
Market Restraints
- Almond supply concentration:California and Mediterranean growing regions dominate raw material sourcing, exposing margins to drought-driven price volatility and water-rights disputes.
- DGCCRF appellation enforcement:France's labeling authority restricts "macaron de Paris" designation to compliant domestic producers, creating non-tariff barriers for import competition.
- Colorant regulatory fragmentation:EFSA additive approvals diverge from FDA food facility standards, forcing dual-formulation runs for cross-border trade.
Strategic Opportunities
- Tea salon convergence:Beverage-retail hybrid concepts pair macarons with curated tea service, capturing occasion-based spending in underpenetrated Southeast Asian urban centers.
- Natural refrigerant retrofit incentives:EU cold-chain infrastructure grants subsidize ammonia and CO2 system upgrades, reducing long-term energy costs for frozen distribution networks.
- Seasonal fruit flavor rotation:Lighter palates in Asian gifting markets favor yuzu, lychee, and passionfruit profiles over chocolate, enabling premium pricing through limited-batch scarcity.
Industry Challenges
- Macaronage skill scarcity:The precise folding technique required for characteristic "pied" development demands trained patissiers, constraining production scale-up in new markets.
- Humidity-controlled facility capex:Controlled drying environments before baking require specialized HVAC investment, elevating break-even thresholds for regional entrants.
- Clean-label reformulation timelines:Removal of synthetic stabilizers and artificial colorants extends R&D cycles while EFSA evaluates novel natural alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macarons Market |
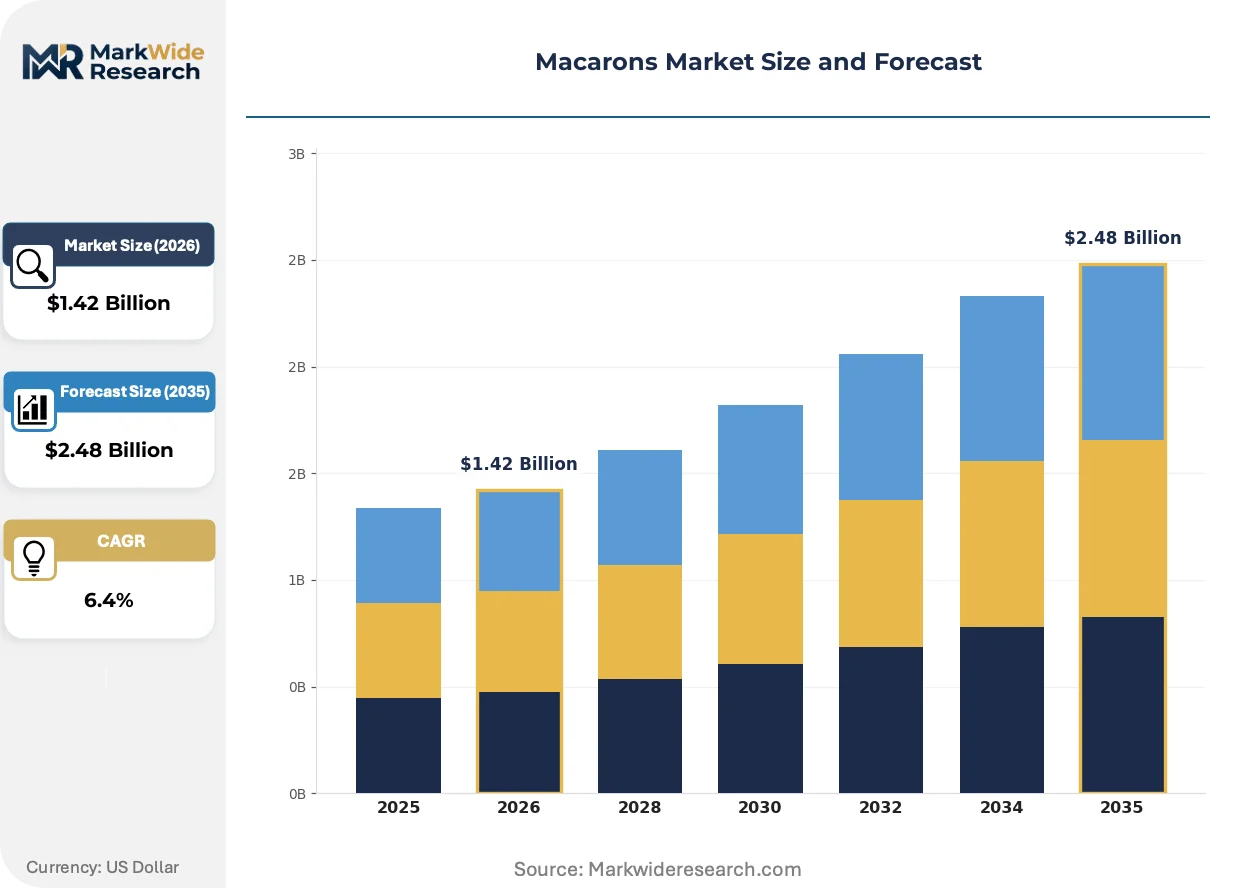
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Premium, Vegan, Sugar-Free Flavor Profile: Chocolate, Vanilla, Pistachio, Fruit Packaging Type: Boxes, Plastic Containers, Cartons, Tins Distribution Channel: Online, Supermarkets, Bakeries, Coffee Shops |
| Companies Covered | Pierre Marcolini Group, Jean-Paul Hevin, Pierre Hermé Paris, Smoor by Bliss Chocolates India, Jouer Hong Kong, Pâtisserie E. Ladurée, La Maison du Chocolat, TWG Tea Company, Fauchon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macarons Market Strategic Shifts & Innovations
Precision fermentation and plant-protein engineering are rewriting formulation possibilities, while regulatory pressure on cold-chain emissions and shifting ceremonial consumption patterns are redrawing competitive boundaries.
Controlled-atmosphere packaging technology is modularizing shelf-life extension for ambient-display macarons. Boutique hotel chains and airport retail operators are adopting nitrogen-flushed individual wrapping at accelerated procurement cycles. This modularizing approach compresses the traditional frozen-distribution dependency, enabling flagship-quality product placement in non-refrigerated premium channels previously inaccessible to meringue-based confectionery.
REACH compliance on food-contact materials is tightening migration limits for printing inks and laminate films used in luxury packaging. European converters must certify new substrate combinations, adding qualification lead time. High-end gifting assortments face the steepest compliance burden, with Parisian heritage houses accelerating in-house packaging production to control certification timelines.
Gifting-occasion compression is shortening purchase-to-consumption windows, with buyers prioritizing visual presentation over extended shelf stability. Corporate procurement teams are replacing annual contract orders with event-triggered spot purchasing through direct-to-recipient digital platforms. Japan's white-day and mid-autumn festival cycles demonstrate the pattern most acutely, where freshness guarantees override bulk-discount incentives.
Macarons Market Segmentation
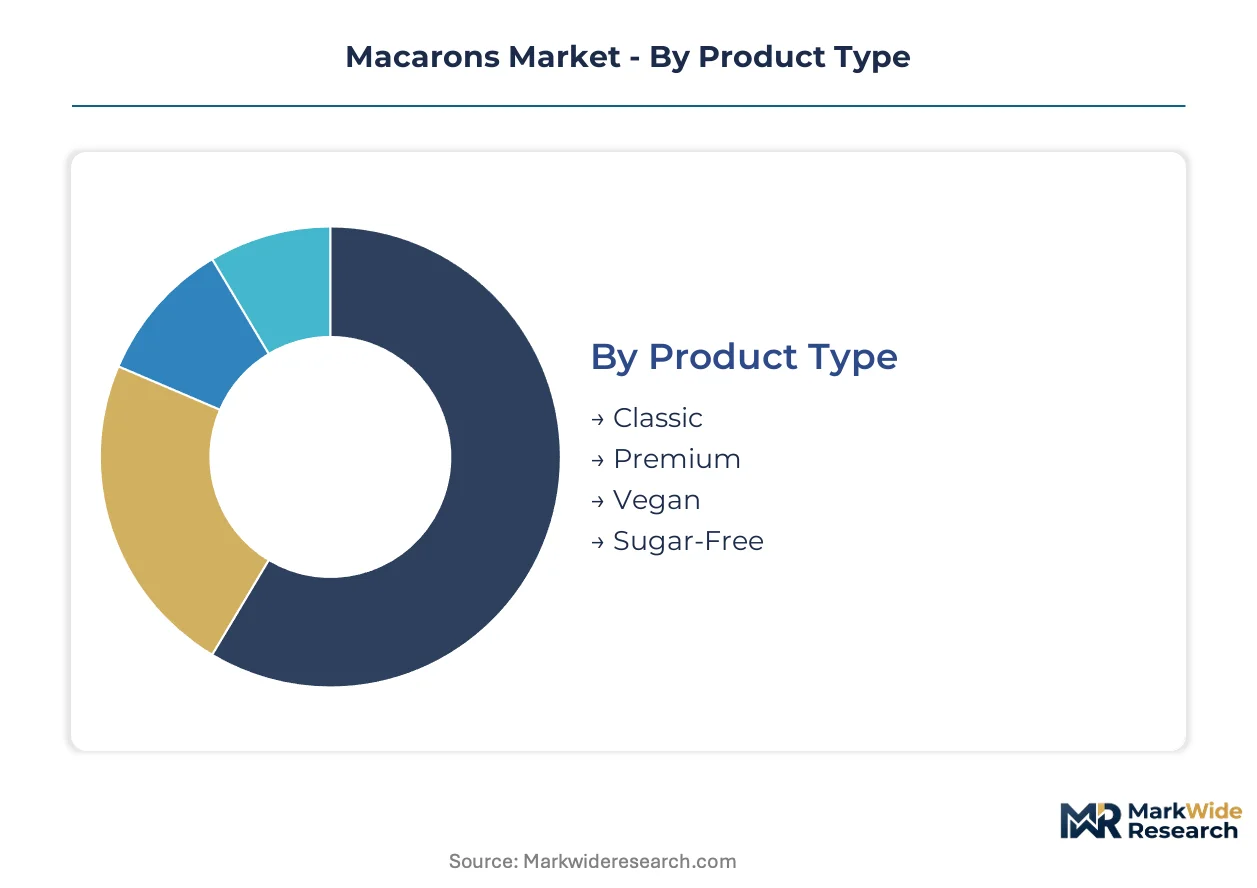
Macaron market segmentation reveals distinct capital requirements across production tiers. Facility investment, ingredient sourcing, and distribution infrastructure vary dramatically by segment, shaping competitive entry barriers and margin structures.
Product Type:
Premium and vegan formulations demand the heaviest upfront capital, requiring specialized equipment for controlled humidity environments and plant-protein engineering.
- Premium:Almond flour sourced from designated Provence orchards meets strict provenance standards. Parisian heritage houses and Dubai-based luxury chains anchor demand for limited-batch production with full ingredient traceability.
- Vegan:Aquafaba and potato protein meringue alternatives require precision fermentation infrastructure. European clean-label mandates and Middle Eastern gifting culture are accelerating category expansion fastest.
- Classic:Traditional egg-white formulations dominate volume production with standardized macaronage protocols.
- Sugar-Free:Alternative sweetener compatibility testing extends R&D cycles for diabetic and keto-positioned offerings.
Most installed capacity flows through Classic. Expansion is steepest in Vegan.
Flavor Profile:
Seasonal rotation velocity separates high-margin innovation from stable base demand, with fruit-forward profiles commanding premium positioning in Asian ceremonial markets.
- Fruit:Yuzu, lychee, and passionfruit limited releases target Japan's white-day and mid-autumn festival cycles. Lighter palates in Tokyo, Seoul, and Singapore favor these profiles over cocoa-based alternatives.
- Chocolate:Ganache-filled shells anchor year-round gifting assortments in European heritage retail. Paris and London flagship boutiques maintain highest per-square-meter revenue through dark and milk chocolate core SKUs.
- Vanilla:Madagascar and Tahitian bean sourcing supports consistent bakery channel placement.
- Pistachio:Iranian and Sicilian nut provenance requirements limit supplier pools to Mediterranean specialists.
Chocolate retains the largest revenue base. Fruit is climbing the fastest.
Packaging Type:
Compliance burden and shelf-life extension technology drive capital allocation, with nitrogen-flushed individual wrapping requiring specialized converter relationships.
- Boxes:Rigid presentation formats dominate corporate gifting procurement through direct-to-recipient digital platforms. EFSA migration limits on printing inks and laminate films force Parisian houses toward in-house production.
- Tins:Metal substrates support ambient-display placement in airport retail and boutique hotel chains. Controlled-atmosphere sealing technology enables non-refrigerated premium channel access.
- Plastic Containers:PET and PP formats balance visibility with cold-chain compatibility for supermarket distribution.
- Cartons:Folding board structures serve cost-optimized bakery takeaway and coffee shop impulse segments.
Boxes capture the highest value-per-unit. Tins are gaining share fastest in travel retail.
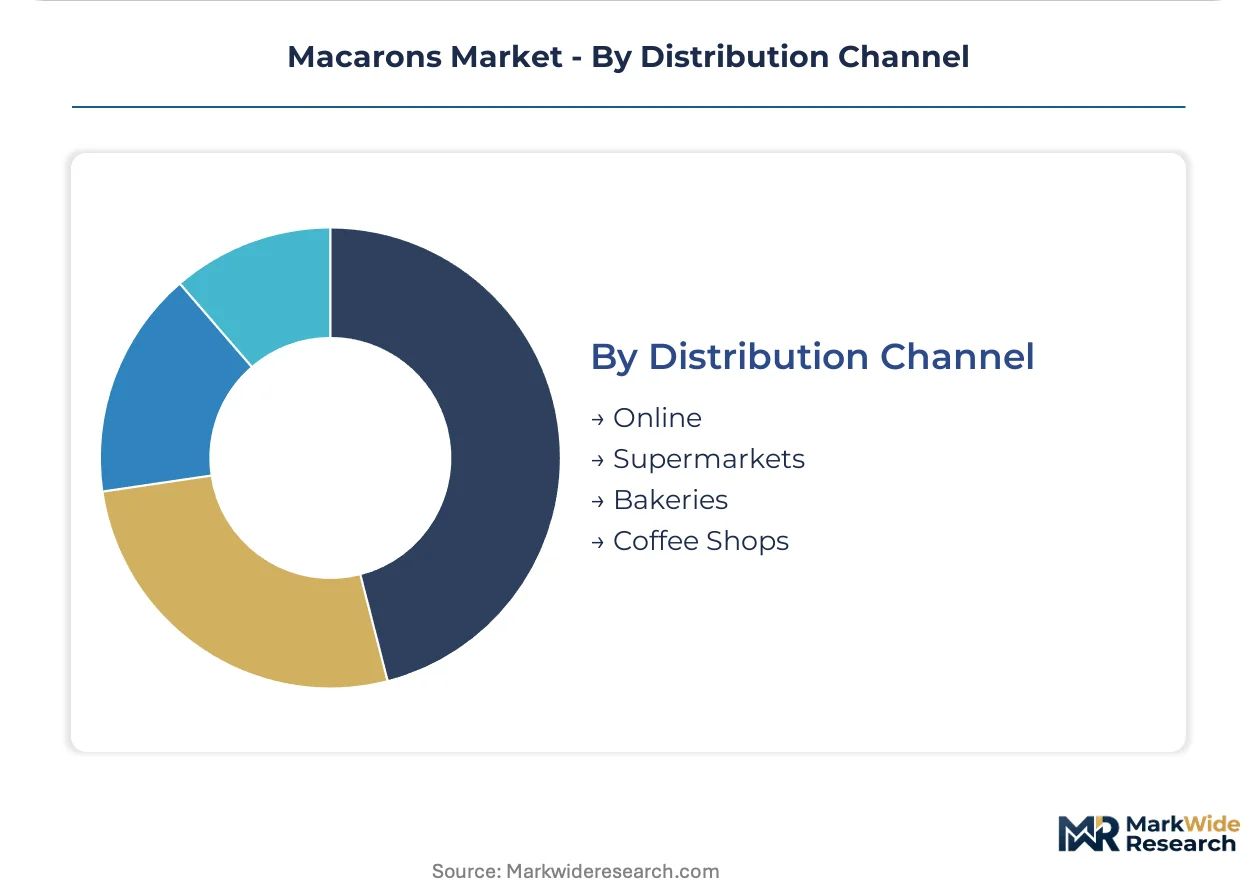
Distribution Channel:
Channel selection determines cold-chain infrastructure requirements and customer acquisition economics, with flagship boutiques demanding the steepest real estate investment.
- Bakeries:On-site macaronage production requires trained patissiers and humidity-controlled HVAC. Paris, Lyon, and Marseille anchor domestic French consumption while Dubai and Riyadh premium chains expand regional footprints.
- Online:Direct-to-recipient platforms compress purchase-to-consumption windows through event-triggered spot purchasing. Japan's festival-driven corporate procurement demonstrates the model's viability.
- Supermarkets:Frozen distribution networks and natural refrigerant retrofits shape EU market access under F-Gas Regulation phase-downs.
- Coffee Shops:Tea salon convergence concepts pair macarons with curated beverage service in underpenetrated Southeast Asian urban centers.
Bakeries hold the deepest established presence. Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parisian patisserie traditions established the technical foundations for modern macaron production, with French almond cultivation in Provence and Languedoc anchoring ingredient provenance standards that now shape global quality benchmarks.
France
Heritage houses in Paris, Lyon, and Bordeaux drive domestic consumption and export positioning through controlled flagship distribution. DGCCRF enforces strict appellation-style labeling on "macaron de Paris," creating regulatory barriers for non-compliant imports. The Île-de-France cluster concentrates premium production capacity, with Parisian boutiques generating highest per-square-meter revenue in chocolate and fruit-forward assortments.
United Arab Emirates
Dubai and Abu Dhabi premium bakery chains are expanding macaron offerings as boxed confectionery replaces traditional sweets in ceremonial exchange. MOHAP food safety standards govern import registration for almond-based products entering Gulf markets. Mall-based luxury retail in Dubai anchors regional gifting demand, with hotel chains adopting nitrogen-flushed packaging for ambient-display placement.
Japan
Tokyo, Osaka, and Yokohama consumers favor lighter fruit profiles—yuzu, lychee, passionfruit—over cocoa in white-day and mid-autumn festival cycles. METI oversees food contact material standards affecting luxury packaging compliance. Corporate procurement teams in Kanto region are replacing annual contracts with event-triggered spot purchasing through direct-to-recipient digital platforms.
United Kingdom
London flagship boutiques sustain year-round demand for ganache-filled chocolate assortments, with gifting culture concentrated in corporate and hospitality channels. FSA allergen labeling requirements shape formulation transparency for almond-based products. West End retail clusters and Heathrow airport travel retail are adopting controlled-atmosphere tin packaging to enable non-refrigerated premium channel access.
Saudi Arabia
Riyadh and Jeddah are emerging as high-volume gifting markets where visual presentation overrides extended shelf stability in purchase decisions. SFDA regulates food facility registration and additive approvals for imported confectionery. Premium bakery chains in the Eastern Province are broadening macaron assortments to capture ceremonial exchange occasions previously served by date-based traditional sweets.
Macarons Market Key Industry Players
Premium-margin players sit above commodity-margin players across ingredient provenance and controlled distribution dimensions, with heritage Parisian houses commanding pricing power through limited-batch production and full traceability. The vendor base stratifies into three tiers: vertically integrated specialists with captive almond supply, tea salon hybrid operators, and regional bakery chains licensing production protocols. Consolidation pressure is accelerating as natural refrigerant retrofits and clean-label reformulation raise break-even thresholds for new entrants.
Within the heritage Parisian tier, Pierre Hermé Paris and Pâtisserie E. Ladurée exemplify vertical integration into Provence almond sourcing and flagship boutique control. TWG Tea Company occupies a distinct position at the beverage-retail intersection, pairing macarons with curated tea service in underpenetrated Asian urban centers. Smoor by Bliss Chocolates India represents the regional chain archetype, adapting European production protocols to local gifting occasions while navigating FSSAI formulation standards.
| Leading Market Players |
|---|
| Pierre Marcolini Group |
| Jean-Paul Hevin |
| Pierre Hermé Paris |
| Smoor by Bliss Chocolates India |
| Jouer Hong Kong |
| Pâtisserie E. Ladurée |
| La Maison du Chocolat |
| TWG Tea Company |
| Fauchon |
| Others |
Cost & Logistics Intelligence
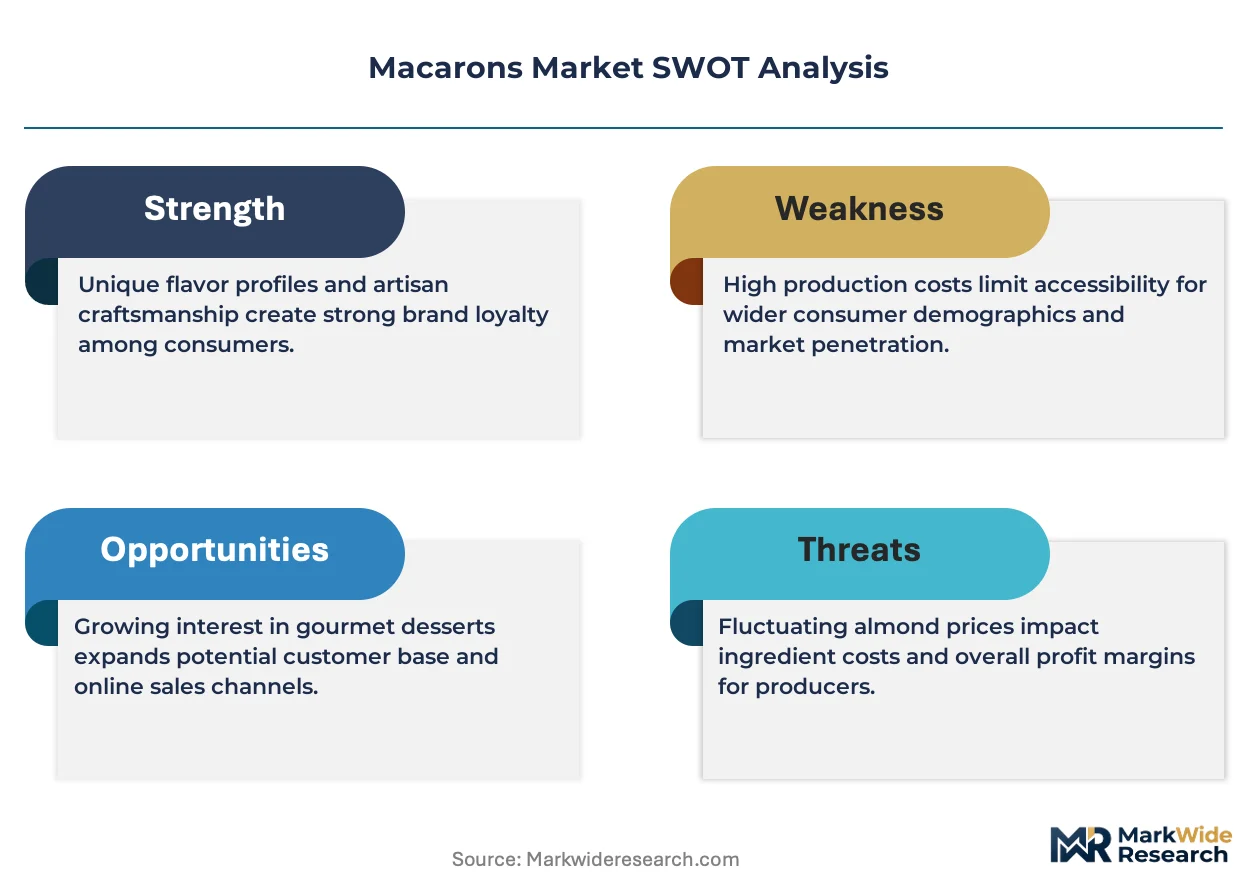
EU Green Deal procurement mandates for ingredient traceability and carbon footprint disclosure are forcing almond provenance certification upgrades across supplier bases, compressing margins for non-compliant operators while rewarding vertically integrated heritage houses with pricing power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Parisian heritage houses from regional bakery chains and mass-market supermarket SKUs. Price differentiation hinges on almond provenance certification and controlled humidity production infrastructure. Pricing pressure stems from California drought-driven almond cost volatility. Corporate gifting buyers show lowest price sensitivity; supermarket channel buyers exhibit highest.
Supply Chain Analysis
Patissier workforce scarcity in France and the UAE constrains macaronage skill replication across new market expansions. Almond supply concentrates in California, Spain, and Italy; egg white and aquafaba alternatives draw from diversified protein processing hubs. Single-source vulnerability runs through California water-rights disputes. Distribution runs through frozen networks with natural refrigerant retrofits accelerating under EU F-Gas phase-downs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium-tier positioning as clean-label reformulation costs amortize across higher price points and gifting-occasion buyers absorb provenance premiums.
For Market Incumbents: Acquire controlled humidity production facilities in Dubai and Riyadh to anchor Middle Eastern gifting expansion. Secure captive almond supply from Provence orchards before EU Green Deal traceability mandates consolidate supplier pools. Defend against aquafaba-based vegan entrants by accelerating clean-label certification timelines. For New Entrants and Emerging Players: Corporate procurement teams in Japan's Kanto region represent the most penetrable buyer archetype, shifting from annual contracts to event-triggered spot purchasing. Target tea salon convergence concepts in underpenetrated Southeast Asian urban centers. Lead with nitrogen-flushed individual wrapping technology to bypass frozen distribution infrastructure requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated heritage houses possessing captive Provence almond supply and flagship boutique networks. Long-term viability favors operators controlling both ingredient provenance and controlled distribution channels. Watch EFSA additive approval timelines for natural colorants as inflection indicator for clean-label reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Almond Orchards | Provence provenance certification secures EU Green Deal compliance and premium pricing tier access. |
| Natural Refrigerant Retrofit Program | Ammonia and CO2 system upgrades reduce F-Gas Regulation phase-down exposure across frozen distribution networks. |
| Tea Salon Concept Expansion | TWG Tea Company model captures occasion-based spending in Bangkok, Jakarta, and Kuala Lumpur premium retail. |
| Controlled-Atmosphere Packaging Deployment | Nitrogen-flushed individual wrapping enables airport and boutique hotel ambient-display placement without cold-chain dependency. |
| Aquafaba Meringue R&D Investment | Plant-based protein engineering unlocks vegan category expansion while maintaining structural parity with egg-white formulations. |
Research Approach
Bottom-up bakery channel modeling reconciled against top-down almond supply tracking forms the analytical core of this study. Primary interviews with Parisian heritage house operations directors, UAE mall-based luxury retail procurement managers, Japanese corporate gifting buyers, and EU cold-chain logistics providers combined with secondary validation from EFSA additive approval databases, DGCCRF labeling enforcement records, and customs trade flows. This approach triangulates production capacity estimates against import-export movements and retail audit data.
Historical trendline analysis of premium confectionery pricing and volume trajectories informed the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, flavor profile rotation velocity, packaging format compliance burden, and distribution channel cold-chain infrastructure requirements. CAGRs were derived from fitted growth curves incorporating almond price volatility indices and gifting-occasion calendar density by geography.
Underlying measurement precision varies by segment; premium and vegan product types carry tighter precision than classic formulations due to concentrated producer transparency. Forecasts reflect assumptions on EU F-Gas retrofit subsidy uptake and EFSA natural colorant approval timelines. Material deviation in California water-rights adjudication or DGCCRF appellation enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
South Africa Confectionery Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Mints Market
Confectionery
Sugarless Chocolate Market
Confectionery
Ice Cream Coating Market
Confectionery
United States and Europe Macarons Market
Confectionery
Vegan Chocolate Confectionery Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
Pralines Market
Confectionery
Dark Chocolate Market
Confectionery
South America Confectionery Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Gummy Market
Confectionery
Milk Chocolate Market