
 Edible Peanut Powder Market | 2026-2036
Edible Peanut Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Peanut Powder Market Insights
Ingredient licensing revenue from defatted peanut powder formulations is reconfiguring margin pools away from traditional peanut butter retail. Golden Peanut and Tree Nuts anchors supply through its integrated shelling and oil extraction network across the American Southeast. PB2 Foods differentiates through proprietary pressure processing that preserves protein content while stripping oil. ADM leverages its commodity risk management infrastructure to stabilize input costs for food manufacturers.
Edible peanut powder consists of roasted peanuts ground and partially or fully defatted to achieve fat contents ranging from 12% to 28%, yielding a shelf-stable protein concentrate with emulsifying properties for baked goods, beverages, and nutritional products. Roasted powder leads volume due to its flavor intensity and compatibility with confectionery and sauce applications, while organic powder captures premium positioning in clean-label nutritional supplements. Online retail channels are expanding fastest as direct-to-consumer protein brands bypass traditional grocery slotting fees.
FDA allergen labeling requirements under FALCPA and FSMA preventive controls mandate rigorous sanitation protocols and supplier verification for peanut powder facilities. USDA organic certification and Non-GMO Project verification create tiered market access thresholds that filter smaller processors from premium contract opportunities. Stakeholders must monitor evolving EPA air quality standards for roasting emissions and state-level peanut grading regulations that affect raw material qualification criteria.
Market Dynamics
The edible peanut powder market is experiencing a structural recalibration as protein fortification demands from sports nutrition pull volume away from traditional peanut butter retail, while FDA allergen labeling rules compress specification windows for defatted concentrates.
Growth Catalysts
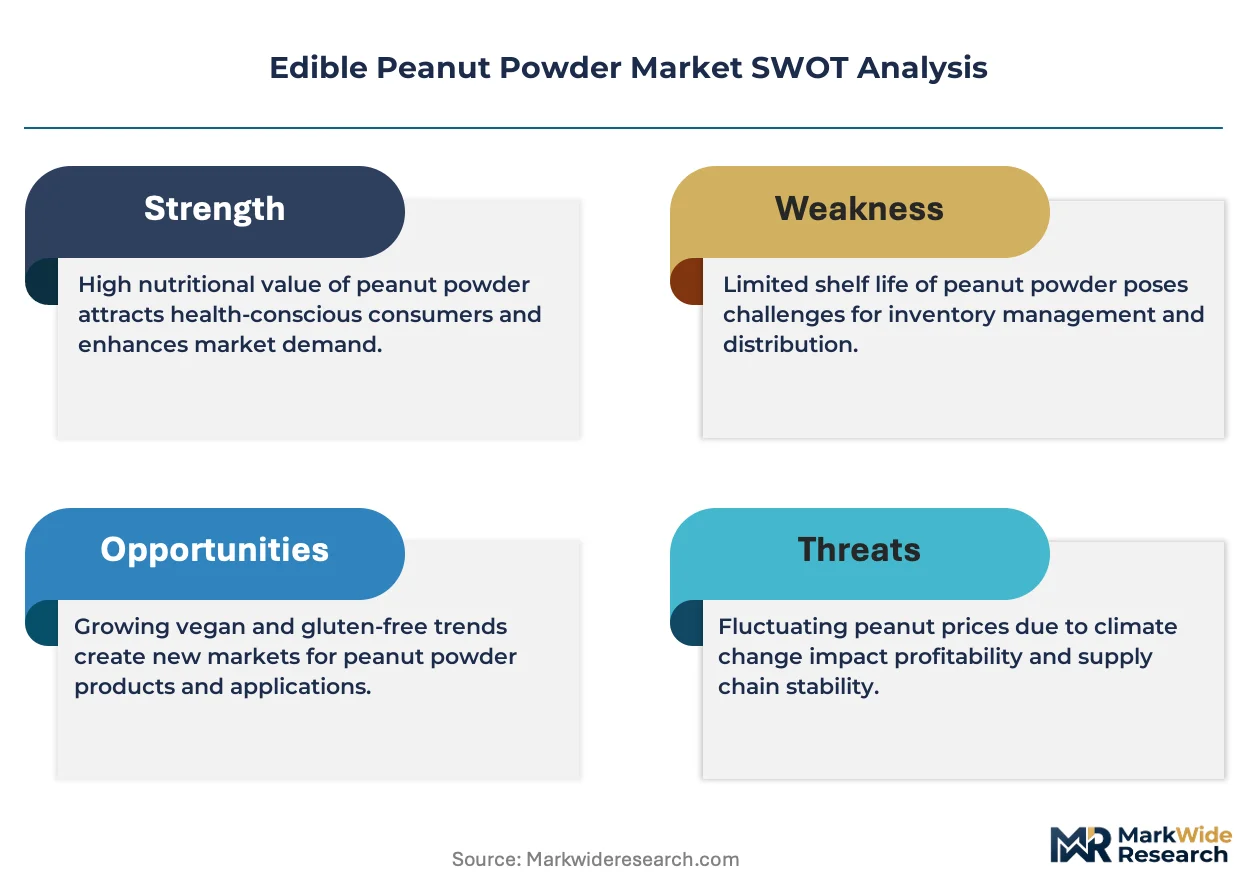
- Protein fortification mandates:Sports nutrition formulations require shelf-stable protein concentrates with emulsifying properties, driving demand for defatted peanut powders in ready-to-drink beverages and nutritional bars.
- FALCPA compliance infrastructure:FDA preventive controls under FSMA have forced facility upgrades that favor larger processors capable of rigorous sanitation protocols and supplier verification systems.
- Georgia-Alabama processing corridor:Concentrated peanut shelling and oil extraction infrastructure in the American Southeast creates captive supply advantages for regional ingredient manufacturers.
Market Restraints
- Raw material price volatility:Peanut commodity markets fluctuate with drought cycles in the Southeast and export demand shifts, squeezing margins for defatted powder processors locked into annual supply contracts.
- Allergen cross-contamination liability:FALCPA's strict labeling requirements create legal exposure throughout the supply chain, deterring multi-allergen facilities from adding peanut powder lines.
- Plant protein substitution:Pea and rice protein isolates achieve comparable emulsification in beverage applications at lower allergen risk profiles, threatening volume in premium nutritional segments.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail bypasses traditional grocery slotting fees, enabling protein-focused brands to build margin-rich subscription models for powdered peanut butter products.
- Organic certification tier:USDA organic and Non-GMO Project verification create price premiums that filter out commodity competitors, opening contract opportunities with clean-label supplement manufacturers.
- Pressure processing technology:Proprietary methods that preserve protein content while stripping oil enable functional differentiation in baked goods and confectionery applications beyond traditional nut butter replacement.
Industry Challenges
- Specialized equipment scarcity:Defatting and roasting systems require capital-intensive installations with long lead times, constraining capacity expansion for mid-scale processors seeking organic certification.
- Emissions compliance timelines:EPA air quality standards for roasting emissions impose retrofit deadlines that compress project schedules and strain engineering resources in the Southeast processing cluster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Peanut Powder Market |
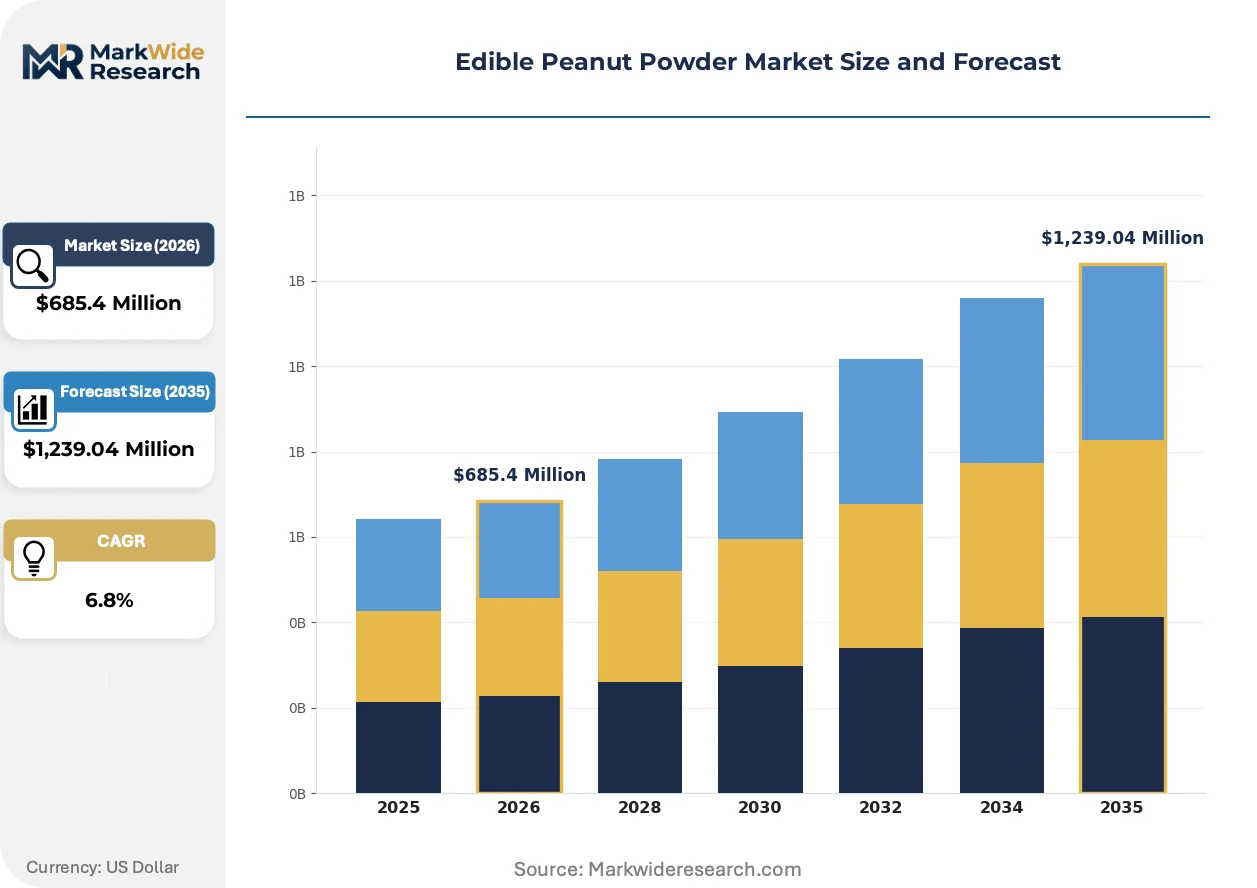
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Powder, Roasted Powder, Flavored Powder, Organic Powder Application: Food & Beverage, Bakery Products, Nutritional Supplements, Sauces Packaging Type: Bags, Jars, Sachets, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | The J.M. Smucker Company, Golden Peanut and Tree Nuts, PB2 Foods, BetterBody Foods, Santa Cruz Organic, Bell Plantation, ADM, PBfit, Crazy Richard's Peanut Butter Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Peanut Powder Market Trends and Innovations
Technology convergence and regulatory stringency are compressing traditional processing economics while opening premium tiers for certified clean-label products. These shifts favor operators with integrated supply chains and proprietary extraction capabilities.
Cold-press oil extraction is collapsing the traditional trade-off between fat reduction and protein retention in peanut powder manufacturing. Sports nutrition brands and clean-label bakeries are adopting these concentrates at accelerating rates, displacing older solvent-based defatting methods that degraded functional protein structures. The technology is collapsing premium pricing for high-protein concentrates as yield improvements democratize access.
FSMA preventive controls and FALCPA enforcement have tightened supplier verification requirements across the American Southeast processing corridor. Facilities must now document sanitation protocols and allergen segregation systems that previously operated on informal standards. Small and mid-scale processors without dedicated peanut-only lines are exiting premium contract pools rather than absorb compliance costs.
Clean-label certification has become a primary purchase filter for nutritional supplement buyers, with USDA organic and Non-GMO Project verification functioning as market access tickets. Procurement teams at branded protein companies now require dual certification for new supplier qualification, displacing conventional commodity sourcing. This behavioral shift concentrates contract volume among processors with captive organic peanut supply and in-house certification management.
Edible Peanut Powder Market Segmentation
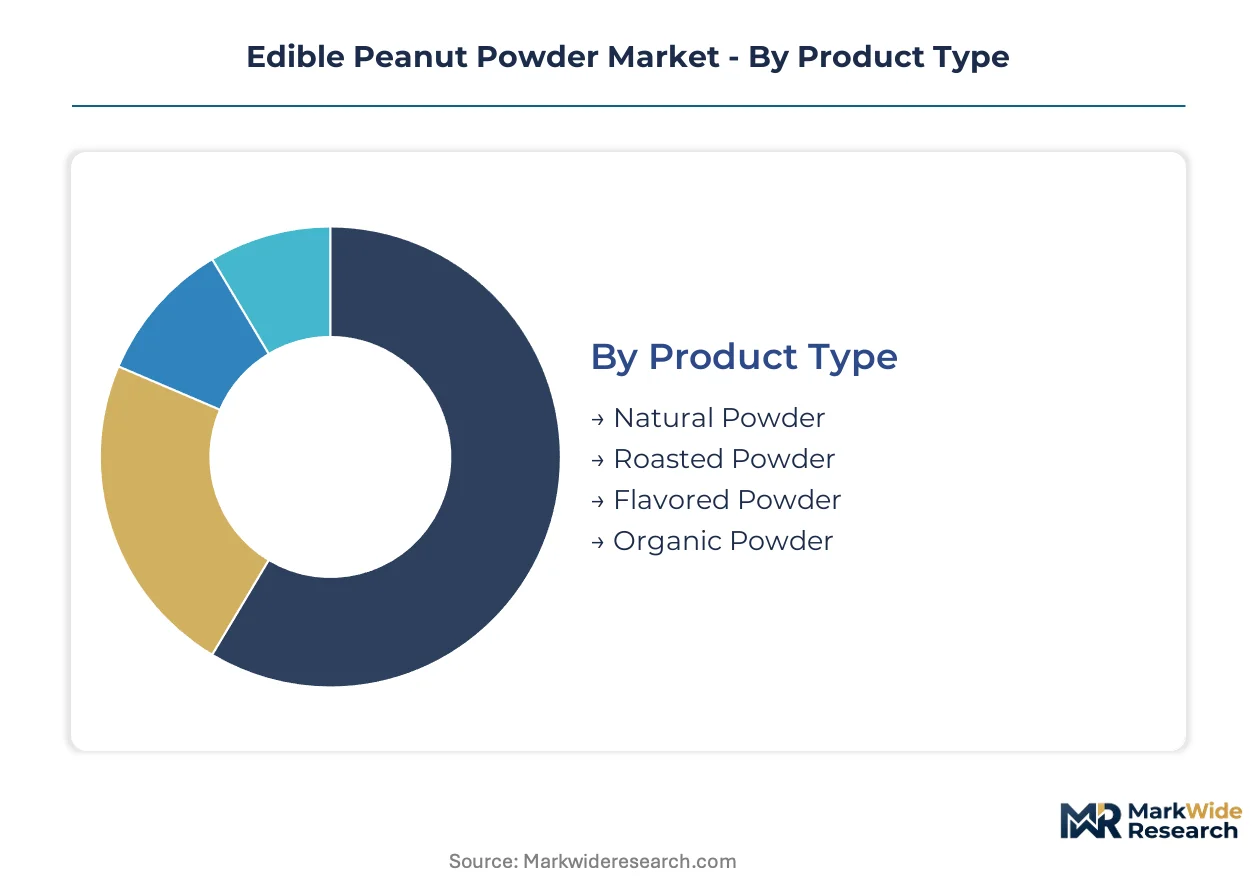
Segmentation in edible peanut powder reveals how protein fortification requirements, clean-label certification tiers, and channel economics reshape procurement priorities across food manufacturing and direct-to-consumer markets.
Product Type:
After-sales service intensity varies sharply by powder type—roasted and organic variants demand technical support for flavor consistency and certification documentation that natural commodity grades rarely require.
- Roasted Powder:Intense heat treatment develops Maillard reaction compounds that deliver concentrated nutty flavor profiles. Demand concentrates in confectionery and sauce manufacturing across Georgia and Alabama, where peanut processing infrastructure enables just-in-time roasted powder supply with tight moisture specifications.
- Organic Powder:USDA certification and Non-GMO Project verification mandate segregated supply chains from farm through defatting. Premium nutritional supplement brands in the American Southeast specify organic powder for clean-label positioning, though certification costs filter smaller processors from contract pools.
- Natural Powder:Minimally processed with raw or lightly roasted peanut base, serving commodity baking applications where cost efficiency outweighs flavor intensity requirements.
- Flavored Powder:Cocoa, vanilla, or spice-infused variants targeting direct-to-consumer protein brands seeking flavor differentiation without additional ingredient handling.
Roasted powder holds the largest share; momentum sits with organic powder.
Application:
Cost tier stratification separates premium nutritional formulations from commodity foodservice volumes, with certification requirements and protein content specifications driving price spreads.
- Food & Beverage:Ready-to-drink protein beverages and smoothie bases require defatted powders with emulsifying stability and neutral flavor profiles. Sports nutrition brands bypass traditional grocery channels, pulling volume toward direct procurement relationships with Southeast processors.
- Nutritional Supplements:Protein bars and meal replacement powders demand high-protein concentrates with documented amino acid profiles. FDA allergen labeling under FALCPA and FSMA preventive controls compress supplier qualification windows, favoring processors with dedicated peanut-only lines and verified sanitation protocols.
- Bakery Products:Muffins, cookies, and bread formulations utilize partially defatted powder for moisture retention and protein enrichment without excessive fat content.
- Sauces:Peanut-based dressings and marinades leverage roasted powder for flavor intensity and suspension stability in high-viscosity applications.
Nutritional supplements command premium pricing; bakery products represent the highest volume throughput.
Packaging Type:
Volume concentration in food manufacturing favors bulk formats, while customer type fragmentation—industrial buyers versus subscription direct-to-consumer brands—determines packaging specification priorities.
- Bulk Containers:Food manufacturers and co-packers receive powder in food-grade totes and drums with integrated nitrogen flushing for shelf-life extension. Georgia and Alabama ingredient hubs concentrate bulk demand from regional bakery and confectionery operations.
- Bags:Multi-layer laminated pouches with resealable closures serve mid-scale specialty food producers and foodservice distributors requiring portion control without industrial handling equipment.
- Jars:Glass or PET containers with wide-mouth designs target retail peanut butter alternatives and powdered peanut butter brands positioned as pantry staples.
- Sachets:Single-serve packets support travel-size protein supplements and sample distribution for emerging direct-to-consumer brands testing flavor variants.
Bulk containers dominate food manufacturing procurement; sachets are expanding most quickly in subscription protein services.
Distribution Channel:
Supply concentration in the American Southeast processing corridor shapes channel economics, with proximity to Georgia-Alabama shelling infrastructure determining landed cost competitiveness.
- Online Retail:Direct-to-consumer protein brands bypass grocery slotting fees through Shopify and Amazon storefronts, building margin-rich subscription models with customized flavor bundles and auto-replenishment.
- Supermarkets:Mass retail placement requires defatted peanut butter alternatives to compete for shelf space against established jarred peanut butter, with clean-label certification increasingly required for natural and organic set placement.
- Health Stores:GNC, Vitamin Shoppe, and regional natural food co-ops curate certified organic and Non-GMO Project verified powders for performance nutrition consumers.
- Specialty Stores:Gourmet food retailers and baking supply shops stock roasted and flavored powders for home confectionery enthusiasts and small-batch food entrepreneurs.
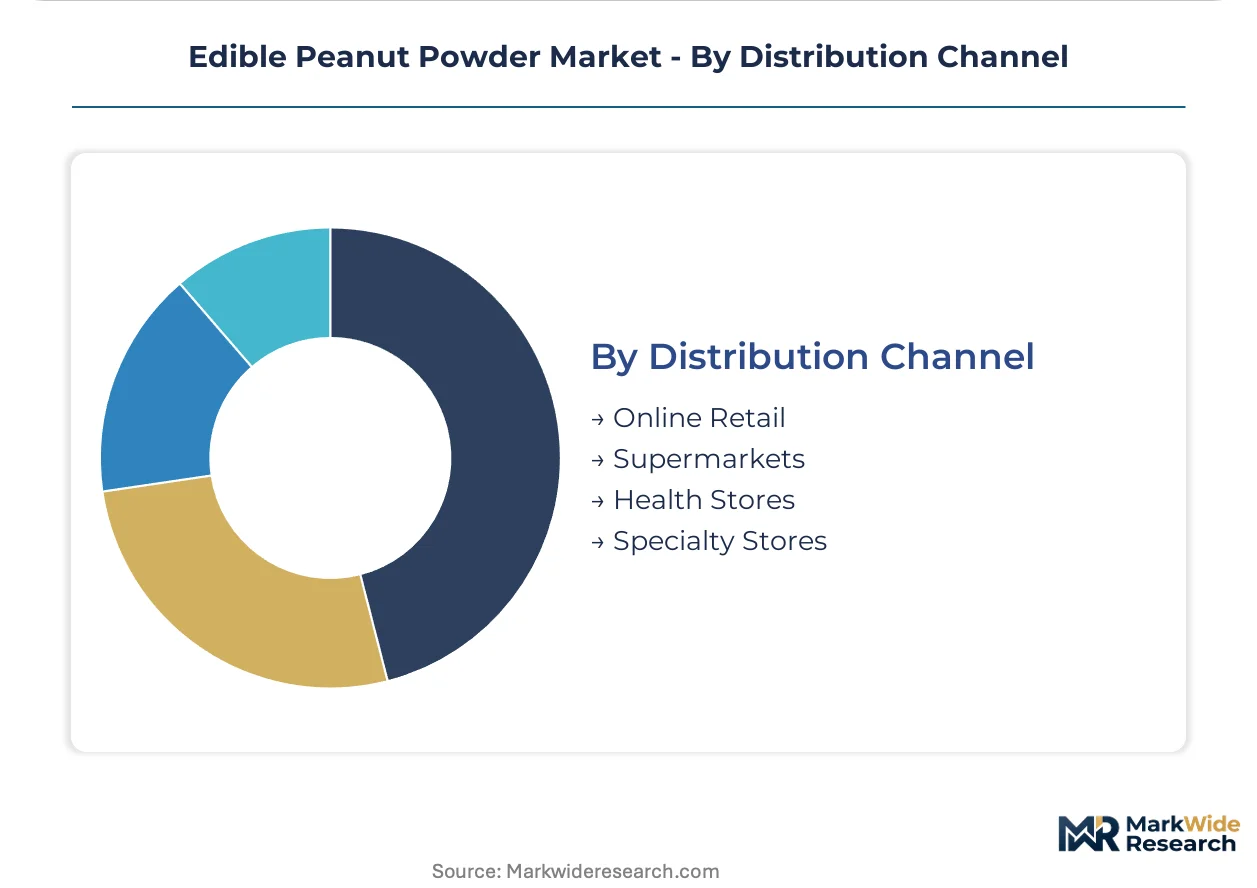
Supermarkets maintain the broadest reach; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peanut shelling infrastructure and oil extraction capacity cluster in the American Southeast, creating captive supply advantages for regional ingredient manufacturers while FDA allergen rules reshape facility investment patterns across producing regions.
United States
Sports nutrition brands and clean-label bakeries drive defatted powder procurement from Georgia and Alabama processing corridors. FDA preventive controls under FSMA mandate dedicated peanut-only lines and verified sanitation protocols that favor larger operators. The Georgia-Alabama corridor concentrates shelling, roasting, and oil extraction infrastructure within a 200-mile radius, enabling just-in-time supply chains for regional food manufacturers.
Canada
Health Canada labeling requirements for priority allergens align with FALCPA stringency, creating cross-border compliance economies for US-based processors. Canadian sports nutrition brands import defatted concentrates through Vancouver and Toronto distribution hubs. Ontario and Quebec food manufacturers source certified organic powder through direct procurement relationships with Southeast US processors holding dual USDA-Canada Organic certification.
Brazil
Peanut production in São Paulo and Minas Gerais states supplies domestic confectionery and emerging protein fortification sectors. ANVISA food allergen regulations are tightening labeling and facility segregation standards for peanut-derived ingredients. São Paulo's ingredient manufacturing cluster is developing defatting capacity to serve South American sports nutrition brands seeking regional supply alternatives to US imports.
Argentina
Córdoba and Buenos Aires provinces anchor peanut cultivation for export-oriented shelling operations. The national food safety regulator enforces Codex-aligned allergen management protocols for peanut processing facilities serving European Union export markets. Rosario's agro-industrial corridor houses emerging oil extraction capacity targeting defatted powder production for Mercosur nutritional supplement manufacturers.
India
Gujarat and Andhra Pradesh states dominate peanut cultivation for domestic oil extraction and emerging protein concentrate applications. FSSAI food safety standards for allergen labeling and manufacturing facility hygiene are converging with Codex Alimentarius frameworks. Gujarat's Anand and Rajkot processing clusters are upgrading roasting and defatting equipment to meet certification requirements for export-oriented nutritional ingredient supply.
Edible Peanut Powder Market Competitive Landscape
Integrated agricultural processors and specialized ingredient technology firms split the market between commodity-scale supply security and functional differentiation. The competitive structure tilts toward processors with captive peanut supply and in-house oil extraction capacity. Three archetypes dominate: vertically integrated shelling-to-powder operators, proprietary technology licensors, and commodity risk management platforms. Capacity expansion and clean-label certification acquisition represent the dominant competitive moves as specification windows narrow under FDA enforcement.
Within the integrated processor tier, Golden Peanut and Tree Nuts and ADM exemplify archetypes built on Southeast US infrastructure density and commodity hedging capabilities. PB2 Foods occupies a technology-differentiated position, representing the pressure-processing specialist archetype that preserves protein content through mechanical oil extraction. These three companies anchor the competitive landscape without exhausting its strategic variation.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Golden Peanut and Tree Nuts |
| PB2 Foods |
| BetterBody Foods |
| Santa Cruz Organic |
| Bell Plantation |
| ADM |
| PBfit |
| Crazy Richard's Peanut Butter Company |
| Others |
Pricing and Supply Chain Analysis
Georgia-Alabama shelling infrastructure concentration anchors margin capture downstream, with defatted powder processors extracting value through certification tiers that commodity peanut butter manufacturers cannot access. FDA allergen compliance costs filter smaller operators from premium contract pools, concentrating pricing power among integrated processors with dedicated peanut-only lines.
Pricing Analysis
FDA preventive controls under FSMA dictate the pricing tier structure by forcing facility segregation investments that smaller processors cannot amortize. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified powder from conventional defatted grades and commodity natural variants. Cost compression in the standard tier is intensifying because cold-press extraction technology democratizes high-protein concentrate production. Nutritional supplement brands exhibit lowest price sensitivity due to clean-label certification requirements, while commodity bakery manufacturers drive hard volume negotiations.
Supply Chain Analysis
Export-oriented peanut processing equipment faces dual-use technology scrutiny under US Commerce Department restrictions, constraining capacity expansion in emerging production regions. Raw material supply draws from the United States, Argentina, and India, with shelling and oil extraction infrastructure concentrated in Georgia, Córdoba province, and Gujarat state. Defatted powder production rests on roasted peanut inputs, specialized pressing equipment, and nitrogen-flushed packaging materials. Single-source vulnerability runs through the Georgia-Alabama corridor where roasting emissions compliance deadlines strain engineering resources. Distribution runs through bulk tote shipments to regional food manufacturers and direct-to-consumer subscription fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from pea and rice protein isolates that achieve comparable emulsification at lower allergen risk profiles, demanding defensive positioning around functional differentiation and certification moats.
For Market Incumbents: Entrench market position through captive organic peanut supply acquisition in the Southeast and in-house Non-GMO Project verification management that filters commodity competitors from premium contract pools. Pressure processing R&D investment preserves protein content differentiation against plant protein substitutes threatening beverage applications. FSMA compliance infrastructure serves as a barrier against mid-scale entrants lacking dedicated peanut-only line capital. For New Entrants and Emerging Players: Brazil's São Paulo ingredient manufacturing cluster offers underpenetrated white space as ANVISA allergen regulations tighten and regional sports nutrition brands seek Mercosur supply alternatives to US imports. Direct-to-consumer subscription models bypass grocery slotting fee barriers that entrench incumbent retail placement. Cold-press technology licensing from established equipment vendors enables rapid functional parity without solvent-based defatting legacy investments. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated shelling-to-powder operators with Georgia-Alabama infrastructure density and existing organic certification pipelines. Long-term viability hinges on defensible supply chain positioning as specification windows narrow under FDA enforcement. The signal to watch is EPA roasting emissions retrofit compliance timelines that may force distressed asset opportunities in the Southeast processing corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Peanut Supply | Captive sourcing from Georgia and Alabama farms secures Non-GMO Project verification pipeline for premium contract access. |
| Cold-Press Extraction Capacity Expansion | Mechanical oil removal preserves functional protein structures that solvent methods degrade in sports nutrition applications. |
| Direct-to-Consumer Channel Launch | Subscription models bypass supermarket slotting fees and build margin-rich customer relationships for powdered peanut butter brands. |
| FSMA Compliance Infrastructure Investment | Dedicated peanut-only lines and verified sanitation protocols unlock procurement relationships with FDA-regulated nutritional supplement manufacturers. |
| Dual Certification Acquisition Program | USDA organic and Non-GMO Project verification functions as market access ticket for clean-label supplement contract qualification. |
Research Methodology
Initial hypotheses were tested against primary input from peanut processing plant managers, sports nutrition brand procurement leads, ingredient distribution channel partners, and FDA regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined facility site assessments across the Georgia-Alabama corridor with structured interviews at Southeast shelling operations and defatting facilities. Secondary sources included FDA FSMA guidance documents, USDA peanut crop reports, EPA air quality standards for roasting emissions, and customs trade data on peanut product flows. Bottom-up volume estimates from processor capacity utilization triangulated against top-down demand segmentation from nutritional supplement and bakery manufacturer procurement patterns.
Demand-supply balance modeling across the analysis window incorporated protein fortification trend trajectories, allergen labeling regulatory stringency indices, and cold-press technology adoption curves. Segmentation dimensions modeled included product type tier, application end-use, certification status, packaging format, and distribution channel economics. CAGRs were derived from iterative reconciliation of historical volume trends with forward-looking procurement intention surveys and capacity expansion announcements. Industry-specific forecast inputs captured EPA emissions compliance retrofit schedules and organic peanut acreage conversion rates in the American Southeast.
Practitioners should monitor EPA roasting emissions standard revisions and organic peanut supply contract availability for early signals of margin compression or expansion. Forecasts reflect assumptions about FSMA enforcement continuity and plant protein substitute performance parity timelines. Material shifts in FDA allergen labeling stringency or Southeast drought frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Packaged Sunflower Seeds Market
Nuts and Seeds
Fox Nuts Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Hickory Nut Market
Nuts and Seeds
Carob Extract Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Almond Products Market
Nuts and Seeds
Japan Fox Nuts Market
Nuts and Seeds
Asia-Pacific Grape Seed Extract Market
Nuts and Seeds
Europe Dried Fruit and Edible Nuts Market
Nuts and Seeds
Low-Cal Nuts Market
Nuts and Seeds
Vietnam Cashew Market
Nuts and Seeds
Rubus Fructicosus (Blackberry) Seed Market
Nuts and Seeds
Seed Butter Market
Nuts and Seeds
Horse Chestnut Seed Extract Market