
 Natural Vitamins Market | 2026-2036
Natural Vitamins Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Vitamins Market Insights
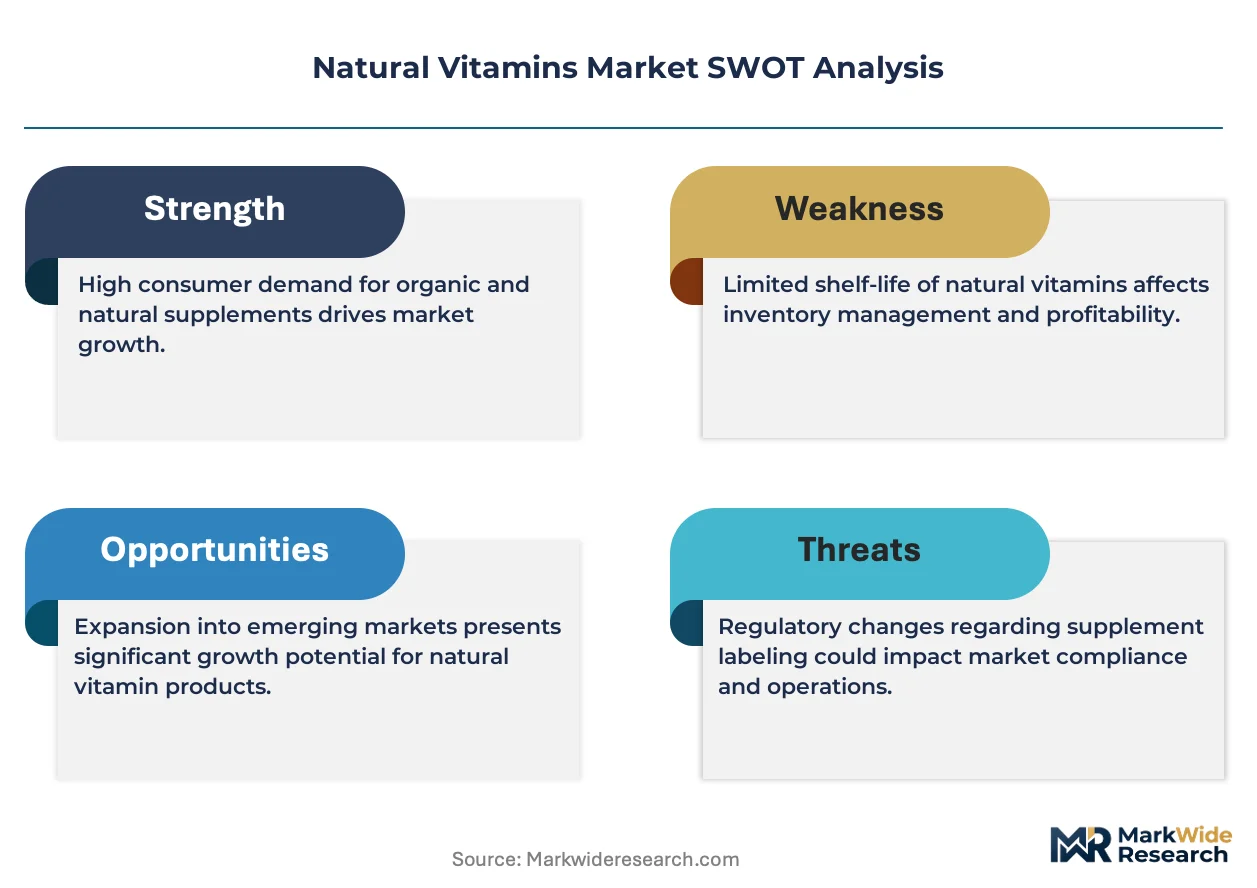
Single-ingredient unbundling is decoupling traditional multivitamin bundles into targeted, condition-specific offerings that let buyers customize regimens. Amway Corporation leverages its direct-selling infrastructure to control channel access across multiple geographies. DSM Nutritional Products anchors its position through backward integration into fermentation-derived vitamin precursors. NOW Foods specializes in transparent sourcing protocols that differentiate its catalog within the specialist retail tier.
Natural vitamins comprise bioactive compounds extracted or derived from plant, microbial, or animal sources, typically retaining cofactors and phytonutrients absent in synthetic analogs, with standardization markers including USP-verified potency and dissolution profiles. Their primary commercial purpose centers on correcting micronutrient deficiencies and supporting physiological functions in populations with dietary gaps or elevated metabolic demands. Dietary gummy vitamins command the fastest-expanding position within product type segmentation as palatability drives pediatric and adult compliance. Online retail channels capture disproportionate margin pools through subscription models and direct-to-consumer data capture. Liquid vitamins occupy a premium niche where bioavailability claims justify higher per-dose pricing relative to pill and powder alternatives.
The FDA's Current Good Manufacturing Practice regulations enforce identity, purity, and composition standards for dietary supplements sold in the United States, while EFSA health claims authorization in Europe constrains permissible marketing language and substantiation requirements. ISO 17025 accreditation for third-party testing laboratories has become a de facto market access threshold for brands seeking retail pharmacy placement. Stakeholders must monitor evolving substantiation requirements for structure-function claims as litigation risk and regulatory scrutiny intensify across major jurisdictions.
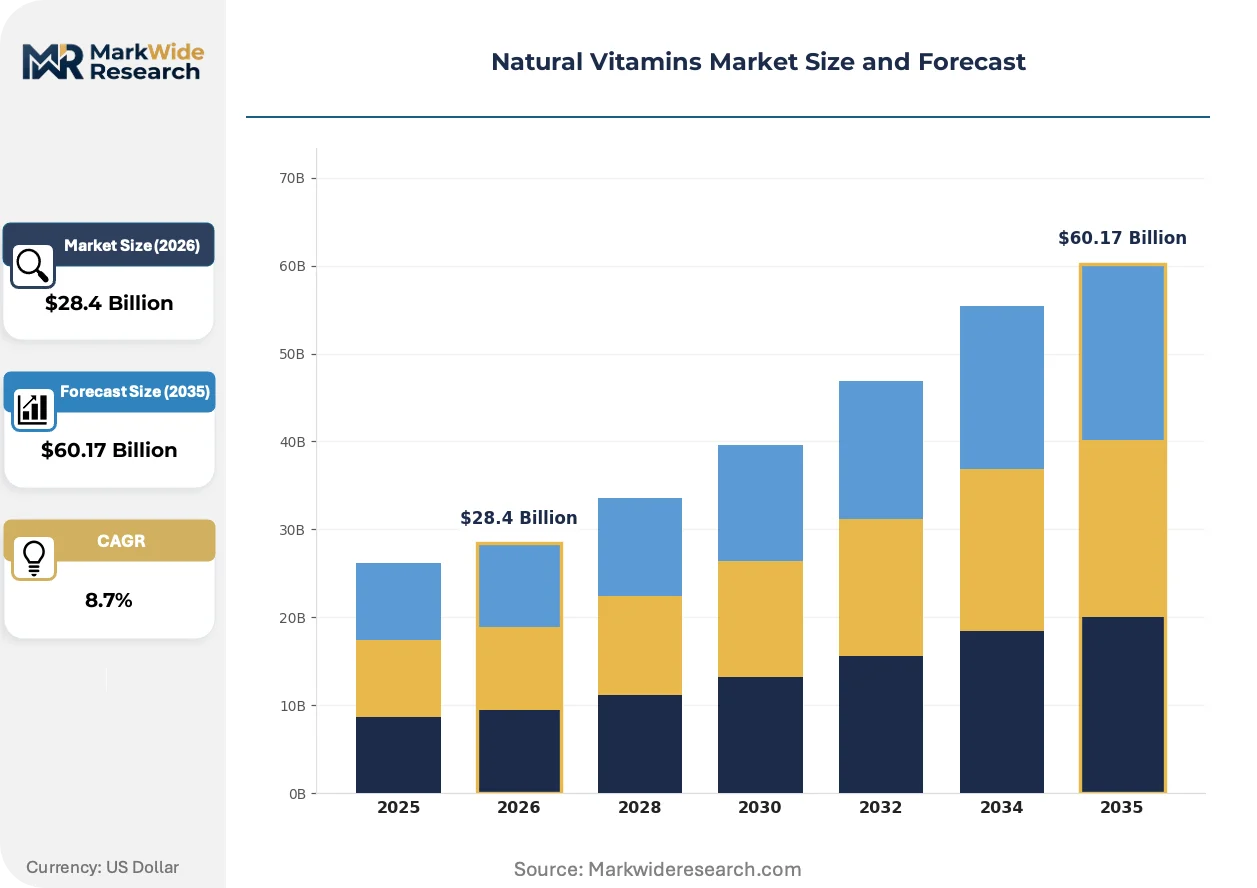
Market Dynamics
Clean-label certification mandates from FDA and EFSA are compressing formulation timelines and forcing manufacturers to rebuild supply chains around identity-verified botanical sources rather than synthetic precursors.
Growth Catalysts
- Fermentation-derived vitamin K2:Microbial production platforms bypass agricultural crop volatility while delivering trans-isomer purity that synthetic routes cannot match, attracting pharmaceutical-grade buyers.
- India's PLI scheme for nutraceuticals:Production-linked incentives for fermentation capacity are drawing contract manufacturing investment away from Chinese vitamin C dominance.
- Pediatric gummy compliance:Palatability engineering for iron and D3 formats is expanding addressable populations beyond traditional capsule-averse demographics into senior swallowing-difficulty segments.
Market Restraints
- Organic acerola concentrate shortages:Climate volatility in Brazilian growing regions is squeezing natural vitamin C feedstock availability and inflating raw material costs.
- EFSA health claims authorization backlog:Structure-function substantiation delays are freezing marketing language for botanical vitamin complexes across European markets.
- Synthetic vitamin price floors:Petrochemical-derived B12 and folic acid from Chinese bulk manufacturers undercut natural-source equivalents on unit economics.
Strategic Opportunities
- Personalized nutrition platforms:At-home micronutrient testing integration is creating subscription vitamin regimens tailored to individual metabolic profiles.
- Thailand's BOI incentive zone:Board of Investment tax holidays for herbal extraction facilities are positioning the country as ASEAN's natural vitamin manufacturing hub.
- Algae-derived vitamin D3:Lichen and microalgae sources are capturing vegan and halal certification premiums that lanolin-based competitors cannot access.
Industry Challenges
- ISO 17025 laboratory accreditation timelines:Third-party testing bottlenecks are delaying product launches by six to nine months for brands seeking retail pharmacy placement.
- Legacy ERP integration with batch genealogy systems:Traceability software for botanical supply chains is forcing mid-tier manufacturers into expensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Vitamins Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Mineral Supplements, Dietary Gummy Vitamins, Liquid Vitamins Customer Type: Health-Conscious Consumers, Dietary Supplement Users, Fitness Enthusiasts, Organic Product Consumers Distribution Channel: Online Retail, Health Food Stores, Supermarkets, Pharmacies Form: Pills, Powders, Gummies, Liquids |
| Companies Covered | Amway Corporation, Herbalife Nutrition Ltd., GNC Holdings Inc., Nature's Bounty Co., Nature’s Way Products LLC, Garden of Life, NOW Foods, Thorne, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Vitamins Market Trends and Innovations
Bioprocess engineering and regulatory data transparency are converging to compress the gap between natural-source purity claims and verified analytical standards, reshaping how manufacturers prove differentiation.
Liposomal encapsulation technology is electrifying bioavailability claims for fat-soluble vitamins A, D, E, and K. Functional beverage formulators are adopting phospholipid delivery systems at accelerating pace to justify premium positioning against standard oil-based softgels. This encapsulation advance is compressing the efficacy gap between high-dose synthetic formats and lower-dose natural equivalents in clinical positioning.
EFSA's updated guidance on botanical safety assessments is forcing reformulation of multivitamin complexes containing novel plant extracts. The regulation's tightened toxicological requirements are eliminating marginally substantiated SKUs from European shelves. Natural vitamin brands with pre-existing EFSA-approved health claims are capturing displaced shelf space from competitors facing retrospective safety reviews.
Subscription direct-to-consumer models are displacing traditional retail replenishment cycles for vitamin regimens. Millennial and Gen-Z buyers are abandoning pharmacy aisles for algorithm-driven personalized packs delivered on 30-day cycles. This channel shift concentrates most visibly in United States metropolitan markets where telehealth integration enables prescription-adjacent vitamin counseling.
Natural Vitamins Market Segmentation
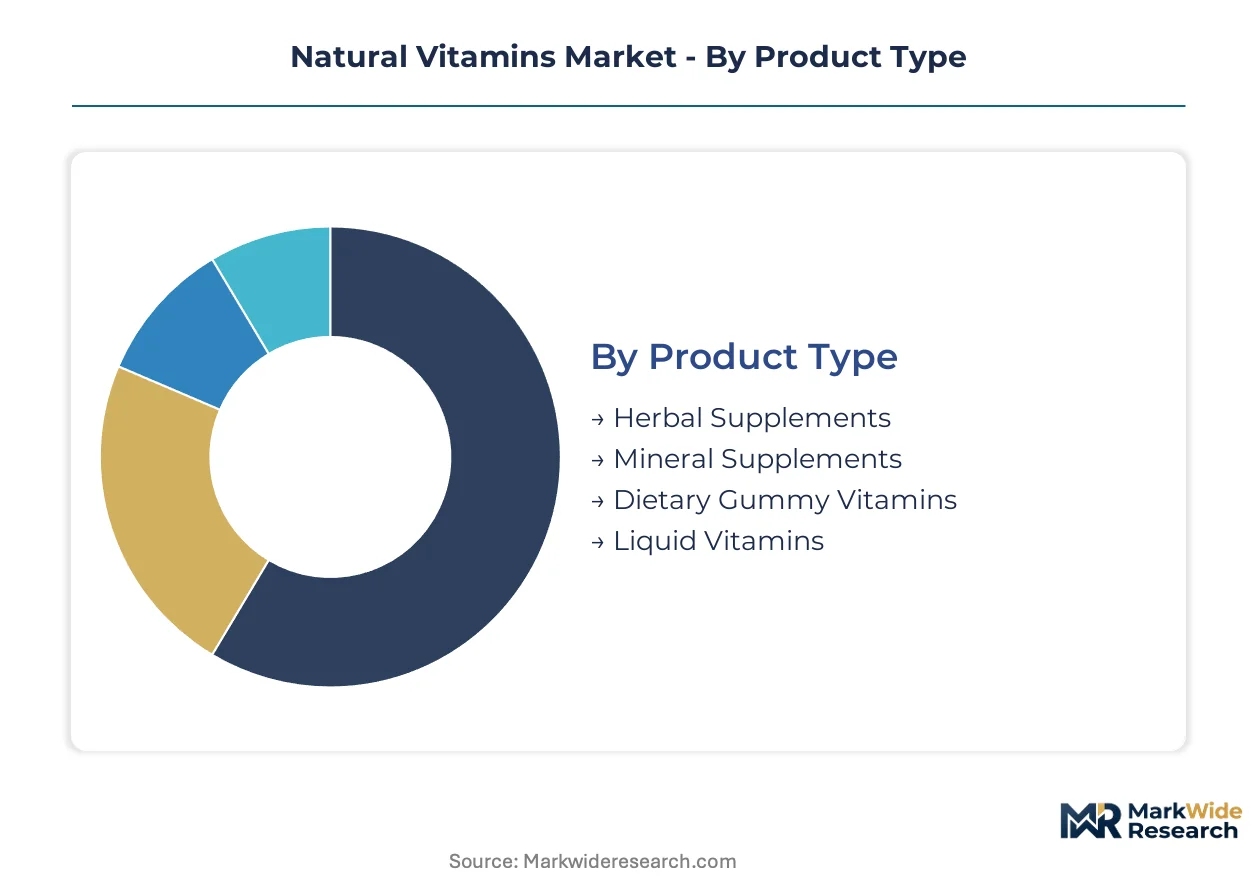
Natural vitamins fragment across multiple axes that determine formulation priorities, channel economics, and compliance burdens. Product type and form factor decisions cascade through manufacturing investments, while customer segmentation dictates pricing tolerance and subscription potential.
Product Type:
Upgrade cycles in natural vitamins are shortening as consumers replace legacy multivitamin bundles with condition-specific formats that target precise physiological needs rather than general wellness.
- Dietary Gummy Vitamins:Palatability-engineered matrices deliver iron, D3, and B-complex through chewable formats. Demand concentrates among pediatric populations and seniors with dysphagia, driven by compliance advantages over capsules in United States metropolitan markets.
- Liquid Vitamins:Aqueous suspensions and oil-based drops offer dose flexibility for metabolic disorders and infant nutrition. Premium positioning in functional beverage formulations justifies per-dose pricing multiples above pill alternatives, with bioavailability claims supporting shelf placement in specialist retail.
- Herbal Supplements:Botanical extracts standardized for marker compounds address stress, sleep, and immune modulation.
- Mineral Supplements:Chelated and colloidal mineral formats correct deficiency states in populations with malabsorption conditions.
Dietary gummy vitamins sit at the top of the volume ranking, with liquid vitamins climbing the fastest.
Customer Type:
Cost tier stratification separates premium subscription buyers from price-sensitive mass-market purchasers, with subscription economics favoring customers willing to commit to algorithm-curated regimens.
- Dietary Supplement Users:Core repeat purchasers with established micronutrient routines and above-average category knowledge. Concentration in United States direct-to-consumer channels, where telehealth integration enables prescription-adjacent counseling and 30-day replenishment cycles.
- Organic Product Consumers:Certification-driven buyers prioritizing USDA Organic or Non-GMO Project verification over unit economics. Willingness to absorb 40-60% price premiums creates margin pools for brands with transparent supply chains and batch-level traceability.
- Health-Conscious Consumers:Preventive wellness seekers responding to personalized nutrition marketing and at-home testing integration.
- Fitness Enthusiasts:Performance-oriented buyers targeting recovery, energy metabolism, and oxidative stress management.
Dietary supplement users command the deepest penetration, with organic product consumers gaining share fastest.
Distribution Channel:
Margin concentration follows channel control over customer data, with direct relationships enabling subscription pricing and inventory optimization that retail intermediaries cannot replicate.
- Online Retail:Algorithm-driven personalization and subscription lock-in capture lifetime value exceeding transactional pharmacy purchases. United States platforms dominate data-capture infrastructure, with millennial and Gen-Z cohorts abandoning physical replenishment cycles.
- Pharmacies:ISO 17025 accreditation requirements and pharmacist counseling create trust barriers that filter out unverified brands. Retail pharmacy placement demands six-to-nine-month third-party testing timelines, compressing launch velocity for new entrants.
- Health Food Stores:Specialist retail tier with educated staff and curated natural-product assortments.
- Supermarkets:Mass-market reach with limited shelf space and price-competitive positioning.
Online retail leads volume contribution, with pharmacies expanding most quickly.
Form:
Manufacturing maturity separates established pill and powder infrastructure from emerging gummy and liquid capabilities that require distinct equipment and stability expertise.
- Gummies:Hydrogel and pectin-based matrices require humidity-controlled production environments and shorter shelf-life management. Palatability engineering investments pay off in pediatric and geriatric compliance, with gelatin-free formats capturing vegan certification premiums.
- Liquids:Emulsion stability and preservative-free packaging demands constrain formulation flexibility. Liposomal encapsulation technology for fat-soluble vitamins justifies premium positioning through bioavailability claims that standard oil-based softgels cannot match.
- Pills:Compressed tablet and two-piece capsule formats dominate manufacturing scale and unit cost efficiency.
- Powders:Bulk flexibility for personalized dosing and functional food integration.
Pills retain volume leadership, with gummies showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The natural vitamins industry traces its modern commercial roots to early twentieth-century United States pharmaceutical innovation, where standardized vitamin extraction from food sources first achieved industrial scale before diffusing to European fermentation specialists and Asian botanical processors.
United States
Direct-to-consumer subscription platforms and telehealth-integrated personalized nutrition drive demand concentration in metropolitan markets. FDA Current Good Manufacturing Practice regulations enforce identity and purity standards that filter out unverified entrants. The greater New York and Los Angeles corridors host the densest clustering of algorithm-driven vitamin pack services and at-home micronutrient testing providers.
Germany
EFSA health claims authorization requirements constrain permissible marketing language for botanical vitamin complexes, creating compliance barriers for new entrants. REACH chemical safety protocols extend to novel extraction solvents used in plant-derived vitamin production. The Baden-Württemberg region concentrates fermentation-derived vitamin K2 manufacturing capacity serving pharmaceutical-grade buyers across Europe.
India
Production-linked incentive schemes for nutraceutical fermentation capacity are drawing contract manufacturing investment away from Chinese vitamin C dominance. FSSAI food safety standards govern dietary supplement labeling and health claim substantiation. The Hyderabad-Bengaluru corridor anchors expanding fermentation infrastructure for microbial vitamin production serving export markets.
China
Synthetic vitamin B12 and folic acid manufacturing from petrochemical feedstocks undercuts natural-source equivalents on unit economics, pressuring margin structures for botanical competitors. SAMR market regulation enforces dual carbon compliance for extraction facilities. The Zhejiang-Jiangsu industrial belt retains dominant positions in bulk vitamin intermediates despite shifting demand toward natural alternatives.
Thailand
Board of Investment tax holidays for herbal extraction facilities position the country as ASEAN's emerging natural vitamin manufacturing hub. The country's national pharmaceutical regulator aligns with ASEAN harmonized standards for dietary supplement safety assessment. The Bangkok metropolitan region and Eastern Economic Corridor attract contract manufacturing investment targeting halal and vegan certification premiums.
Natural Vitamins Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain traceability, with the market structure consolidating around three distinct tiers. Vertically integrated fermentation specialists control upstream vitamin precursor production, direct-selling networks capture recurring revenue through subscription lock-in, and specialist retailers differentiate through transparent sourcing protocols. Competitive moves concentrate on backward integration into botanical supply chains and algorithm-driven personalization platforms that displace traditional replenishment cycles.
Within the direct-selling network tier, Amway Corporation and Herbalife Nutrition Ltd. exemplify channel control strategies that bypass retail intermediaries. NOW Foods anchors the specialist retail tier through transparent sourcing differentiation. DSM Nutritional Products represents the fermentation-integrated archetype with captive supply of microbial-derived vitamin precursors.
| Leading Market Players |
|---|
| Amway Corporation |
| Herbalife Nutrition Ltd. |
| GNC Holdings Inc. |
| Nature's Bounty Co. |
| Nature's Way Products LLC |
| Garden of Life |
| NOW Foods |
| Thorne |
| DSM Nutritional Products |
| Others |
Pricing and Supply Chain Analysis
Fermentation-derived vitamin K2 production platforms are simultaneously compressing manufacturing costs and shifting supply concentration toward pharmaceutical-grade fermentation hubs in Germany and India. This technological transition rewards buyers demanding trans-isomer purity while penalizing brands tethered to agricultural crop volatility in Brazilian acerola regions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EFSA-authorized botanical complexes from ISO 17025-accredited pharmacy-tier products and unverified mass-market alternatives. Price differentiation rests on certification depth and batch-level traceability, with USDA Organic verification commanding 40-60% premiums over conventional equivalents. Cost compression in the standard tier is intensifying because Chinese synthetic B12 and folic acid manufacturers undercut natural-source unit economics. Mass-market supermarket buyers exhibit highest price sensitivity, while subscription direct-to-consumer purchasers show lowest elasticity due to algorithm-curated regimen lock-in.
Supply Chain Analysis
Direct-to-consumer subscription channels handle millennial and Gen-Z replenishment demand, while retail pharmacy distribution runs through ISO 17025-accredited third-party testing bottlenecks. Geographic supply concentrates in China for synthetic vitamin intermediates, India for fermentation capacity under PLI scheme incentives, and Brazil for organic acerola vitamin C feedstock. Raw material dependencies include trans-isomer vitamin K2 precursors, algae-derived D3 lichen extracts, and pectin-based gummy matrices. Single-source vulnerability in Brazilian growing regions creates structural exposure to climate-driven concentrate shortages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The natural vitamins market functions as a regulatory compounder where FDA Current Good Manufacturing Practice enforcement and EFSA health claims authorization create escalating compliance barriers that consolidate advantage among pre-certified incumbents.
For Market Incumbents: Deploy backward integration into fermentation-derived vitamin precursor production to secure supply independence from Chinese synthetic dominance. Capture subscription platform data infrastructure to algorithm-lock millennial and Gen-Z replenishment cycles before telehealth-integrated competitors consolidate metropolitan United States markets. Prioritize EFSA pre-authorization investments to capture shelf space from rivals facing retrospective botanical safety reviews. For New Entrants and Emerging Players: Begin with Thailand's Board of Investment tax holiday zones to establish ASEAN manufacturing footholds targeting halal and vegan certification premiums that European and United States incumbents cannot easily replicate. Target personalized nutrition white space where at-home micronutrient testing integration remains underdeveloped outside United States metropolitan corridors. Pursue direct-to-consumer algorithm-curated packs as the primary go-to-market angle to bypass retail pharmacy ISO 17025 accreditation timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier manufacturers lacking batch genealogy ERP integration, creating acquisition targets for private equity rollups. Long-term viability favors fermentation-integrated specialists with captive K2 and D3 precursor supply over botanical-dependent brands exposed to climate volatility. Watch EFSA health claims authorization backlog resolution as the critical inflection signal for European market access tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | DSM Nutritional Products anchors microbial vitamin K2 production, bypassing agricultural feedstock volatility. |
| Subscription Platform Algorithm Development | Amway Corporation leverages direct-selling infrastructure to data-capture recurring replenishment cycles. |
| EFSA Health Claims Pre-Authorization Investment | Pre-approved botanical complexes capture displaced shelf space from competitors facing safety reviews. |
| Thailand BOI Zone Manufacturing Establishment | Tax holidays position contract manufacturers to serve ASEAN halal and vegan certification demand. |
| At-Home Micronutrient Testing Integration | Telehealth-adjacent platforms enable prescription-counseling subscription models in United States metros. |
Research Methodology
Coverage spans United States, Germany, India, China, and Thailand, with primary inputs from each regional cluster combining executive interviews with dietary supplement brand managers, fermentation plant technical directors, retail pharmacy category buyers, and regulatory affairs specialists. Secondary validation draws from FDA Current Good Manufacturing Practice guidance documents, EFSA health claims authorization registers, FSSAI food safety standards, and SAMR dual carbon compliance disclosures. Bottom-up SKU-level demand modeling triangulates against top-down national nutraceutical consumption benchmarks.
Granularity-level modeling disaggregates volume and value across product type, customer archetype, distribution channel, and form factor dimensions throughout the forecast period. CAGRs derive from segment-specific adoption curves weighted by regulatory milestone timing and channel shift velocity. Industry-specific forecast inputs include PLI scheme capacity buildout timelines in India and EFSA botanical safety assessment backlog clearance rates.
Several conditions sit outside the modeled scope, including unforeseen climate shocks to Brazilian acerola harvests and abrupt EFSA guidance revisions. Forecasts reflect documented assumptions around subscription platform retention rates and telehealth integration penetration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Europe Vitamin a Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Food Grade Vitamin B1 Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Encapsulated Vitamin C Market