
 Middle East and Mediterranean Tahini Market | 2026-2036
Middle East and Mediterranean Tahini Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Mediterranean Tahini Market Foresight
Artisanal sesame roasting expertise is rotating toward industrial automation as heritage mills modernize, tightening the skilled labor pipeline across traditional production zones. Haitoglou Bros. S.A. leverages its Thessaloniki facility to sustain European export volumes with controlled-temperature grinding lines. Halwani Bros. Co. anchors Saudi Arabian retail shelves through dense supermarket distribution and long-standing brand recognition. Dipasa competes on organic certification depth, navigating North American and European import requirements with vertically managed sesame sourcing from Ethiopian and Sudanese origins.
Tahini is a sesame seed paste produced by hulling, roasting, and mechanically grinding sesame seeds into a smooth or coarse emulsion with typical oil content of 50-60% by weight; its primary commercial function spans hummus production, halva manufacturing, salad dressing formulation, and direct table consumption. Conventional tahini dominates volume due to lower raw material costs and established food service procurement patterns, while organic tahini captures expanding margin pools in European health stores and Gulf supermarket premium aisles. Food service end use leads absolute consumption across Levantine and Turkish restaurant chains, though food manufacturing demand for industrial-scale tahini in packaged hummus and confectionery is accelerating fastest.
Turkey's Ministry of Agriculture and Forestry enforces sesame purity and aflatoxin thresholds that shape export eligibility for tahini processors, while Saudi Arabia's SFDA applies Gulf-standard labeling and additive restrictions on imported sesame preparations. The EU's REACH framework and evolving EFSA guidance on sesame allergen declarations influence Mediterranean exporters seeking continental market access. Stakeholders must monitor how diverging national enforcement of sesame traceability rules affects cross-border supply fluidity and certification costs.
Market Dynamics
Turkey's Ministry of Agriculture and Forestry enforces sesame purity and aflatoxin thresholds that reshape export eligibility for tahini processors, compressing supply fluidity while heritage mills automate roasting lines to meet industrial scale demands.
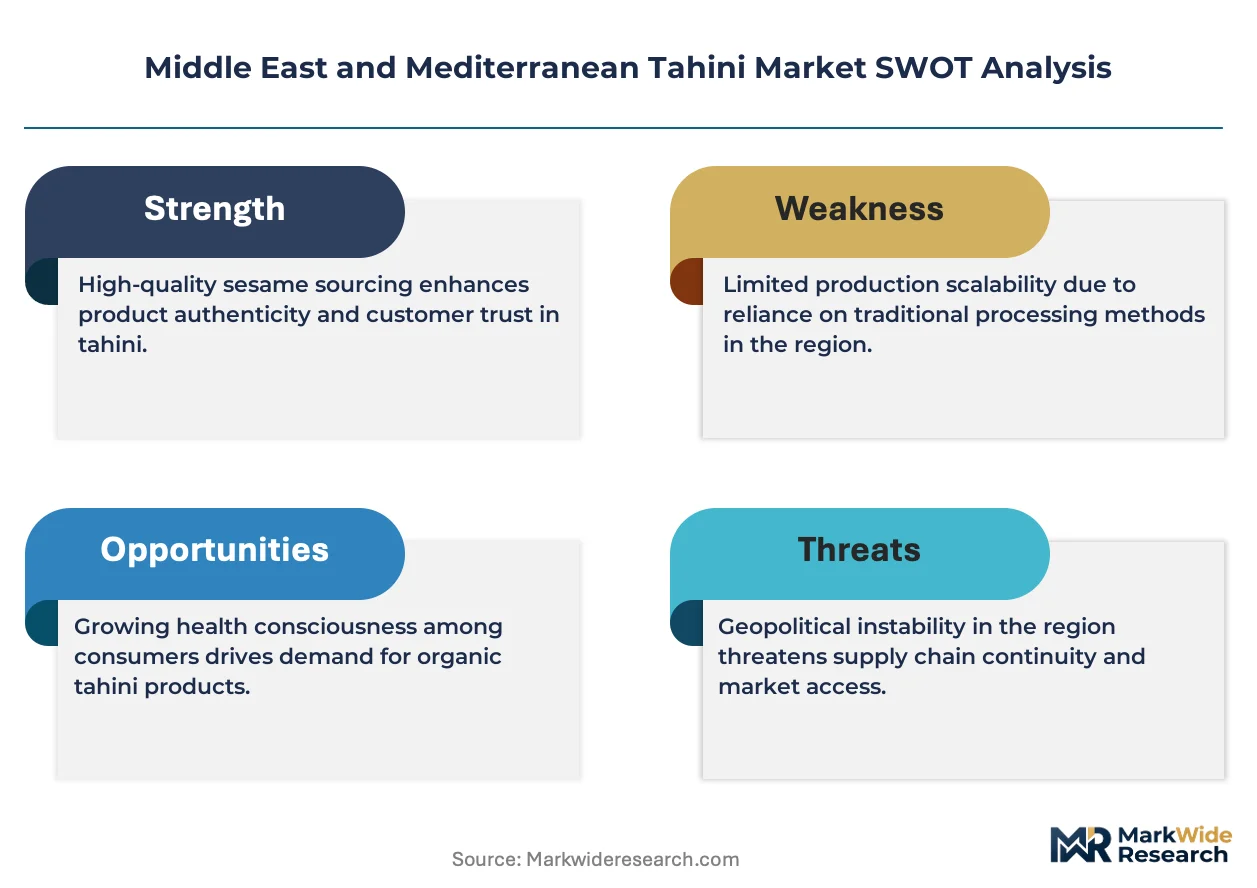
Growth Catalysts
- EU REACH-aligned protocols:Mediterranean exporters adapting to EFSA allergen declaration guidance gain continental market access, pulling investment into controlled-temperature grinding infrastructure.
- Food manufacturing procurement:Packaged hummus and confectionery lines across the Levant are expanding tahini incorporation, creating industrial-scale demand pools.
- Istanbul-Gaziantep processing clusters:Concentrated roasting and grinding capacity supplies both regional brands and European private-label programs, anchoring export volumes.
Market Restraints
- Sesame seed price volatility:Ethiopian and Sudanese origin dependence exposes processors to currency and harvest fluctuations, squeezing margin stability.
- Aflatoxin threshold enforcement:Turkey's Ministry of Agriculture and Forestry testing regimes disqualify non-compliant batches, creating batch-level supply risk.
- Heritage labor pipeline constriction:Artisanal roasting expertise rotation toward automation depletes traditional skill availability, raising training costs.
Strategic Opportunities
- Saudi Arabian retail premium aisles:Dense supermarket distribution networks reward brand recognition with shelf-space allocation for organic and conventional variants.
- North American organic certification depth:Vertically managed Ethiopian and Sudanese sesame sourcing navigates import requirements, opening margin pools in health stores.
- Food service chain standardization:Levantine and Turkish restaurant procurement consolidation favors suppliers with volume consistency and halal certification alignment.
Industry Challenges
- Automated roasting calibration:Temperature-controlled grinding line deployment demands capex and technical integration with legacy hulling equipment.
- Cross-border certification timelines:Diverging national enforcement of sesame traceability rules extends compliance documentation cycles for multi-destination exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Mediterranean Tahini Market |
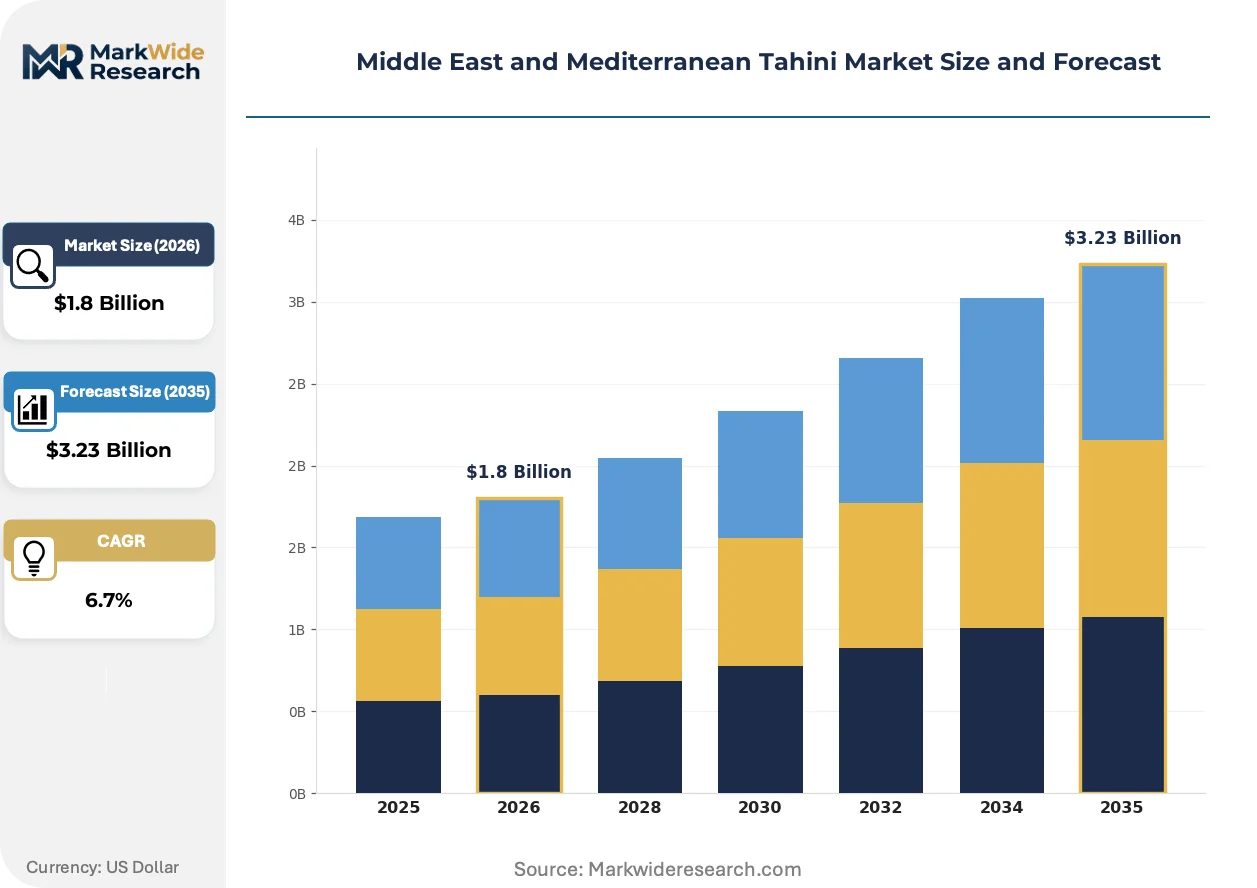
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Tahini, Conventional Tahini, Flavored Tahini, Light Tahini Packaging Type: Tubs, Bottles, Pouches, Jars Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Stores End Use: Food Service, Household, Food Manufacturing, Retail |
| Companies Covered | Haitoglou Bros. S.A., Dipasa, Halwani Bros. Co., Mounir Bissat, SESAJAL, Al Wadi Al Akhdar SAL, Prince Tahina Ltd, Al Kanater SAL, El Rashidi El Mizan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Mediterranean Tahini Market Shifts & Advancements
Automation is decomposing traditional production boundaries as heritage mills retrofit controlled-temperature systems, while regulatory divergence across Mediterranean trade zones forces processors into multi-standard compliance architectures.
Continuous-flow roasting technology is decomposing batch-dependent quality variation. Food manufacturing buyers in packaged hummus lines adopt these systems for consistency. The technology compresses artisanal-to-industrial transition timelines for Gaziantep and Thessaloniki processors.
EU REACH framework evolution on sesame allergen declarations is tightening label precision requirements. Mediterranean exporters seeking continental access must reformulate packaging and testing protocols. Organic tahini suppliers face the steepest compliance cost adjustment.
Food service procurement consolidation is concentrating buying power across Levantine restaurant chains. Volume-scale suppliers with halal certification and aflatoxin documentation are displacing fragmented local sources. Turkey's Istanbul processing hub captures the bulk of this contract migration.
Middle East and Mediterranean Tahini Market Segmentation
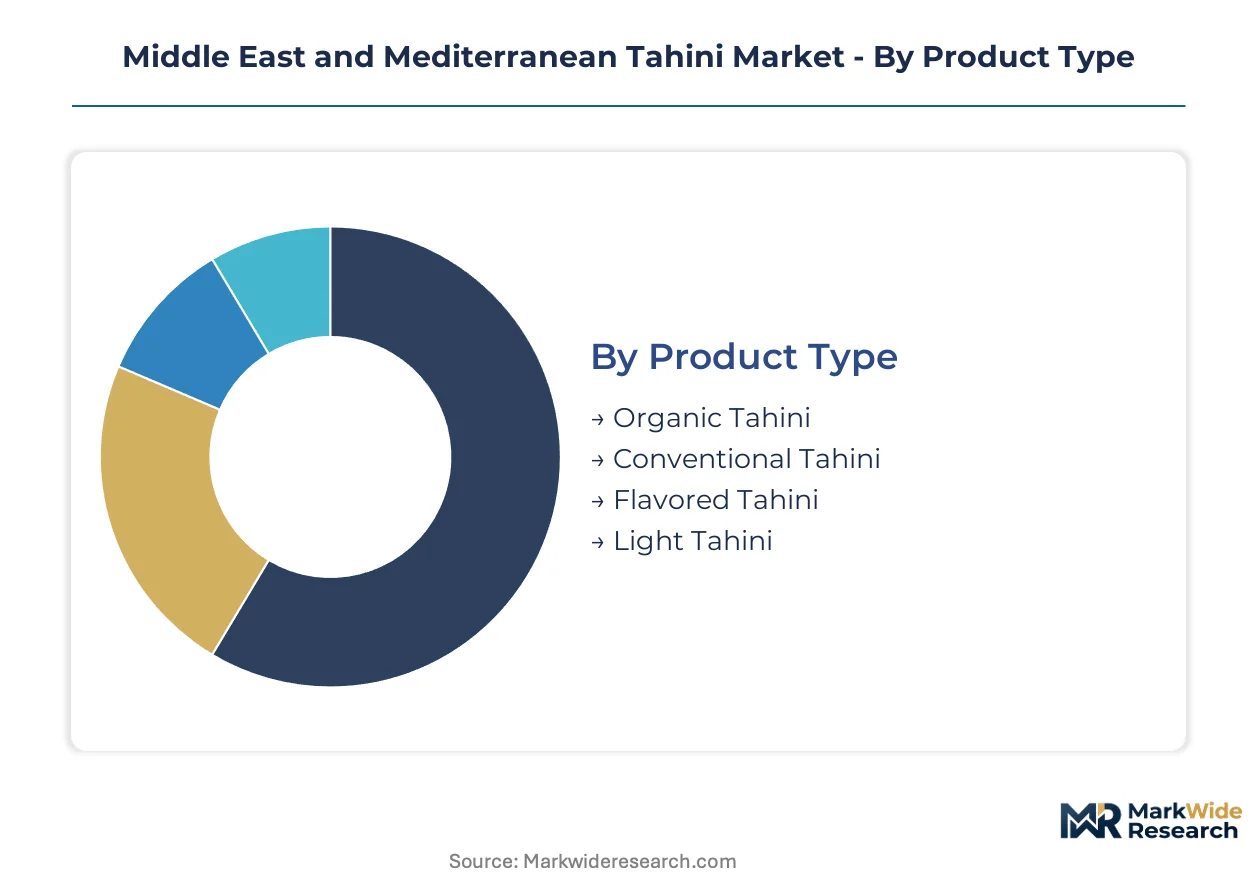
Tahini procurement patterns diverge sharply across product grades and channel structures, with margin pools concentrating in certified organic lines and industrial-scale food manufacturing contracts. Understanding where volume, premium pricing, and regulatory complexity intersect allows processors to prioritize capacity investments and certification spending.
Product Type:
Margin concentration sits in certified organic grades where European health stores and Gulf supermarket premium aisles absorb price premiums, while conventional volumes anchor food service profitability through scale economies.
- Organic Tahini:Produced from sesame cultivated without synthetic pesticides or fertilizers, meeting EU organic and equivalent Gulf standards. Demand concentrates in European health stores and Saudi Arabian retail premium aisles where EFSA-aligned allergen documentation and halal certification unlock shelf access. Certification depth navigates import requirements but squeezes working capital through extended traceability documentation cycles.
- Conventional Tahini:Standard-grade paste from conventionally farmed sesame with typical 50-60% oil content. Volume concentrates in Turkish food service chains and Levantine restaurant procurement where Istanbul-Gaziantep processing clusters compete on halal certification alignment and aflatoxin documentation consistency. Lower raw material costs sustain margin stability despite sesame price volatility from Ethiopian and Sudanese origin dependence.
- Flavored Tahini:Emulsions incorporating garlic, lemon, or spice infusions for direct table consumption. Niche positioning in specialty retail and Gulf supermarket deli sections.
- Light Tahini:Reduced-oil formulation targeting calorie-conscious household segments. Limited penetration outside health-focused urban centers.
The dominant share belongs to Conventional Tahini, while Organic Tahini is expanding most quickly in certified export channels.
Packaging Type:
Cost tier differentiation separates industrial bulk formats from retail-ready units, with food manufacturing procurement favoring tubs for operational efficiency while household demand drives bottle and jar innovation.
- Tubs:Bulk polyethylene or metal containers ranging from 5kg to 20kg for food manufacturing and high-volume food service. Preferred by packaged hummus lines across the Levant for pump-compatible viscosity and reduced unit cost per kilogram.
- Bottles:Squeeze or wide-mouth polyethylene terephthalate containers for household and food service table use. Turkish retail shelves and Saudi Arabian supermarket chains allocate prominent placement to branded bottle formats.
- Pouches:Flexible laminated film with spout or tear-notch closure. Gaining traction in online retail and single-serve food service portions where shipping weight reduction matters.
- Jars:Glass containers with metal lug caps for premium positioning. Dominates European health stores and organic specialty retail where visual transparency signals purity.
Tubs command the largest volume share through industrial procurement, though pouches are climbing the fastest in e-commerce channels.
Distribution Channel:
Customer type stratification creates distinct service requirements, with supermarkets demanding promotional support and health stores requiring certification depth while online retail compresses delivery timelines.
- Supermarkets:Dense network of hypermarkets and supermarkets across Turkey, Saudi Arabia, and Levantine markets. Halwani Bros. Co. anchors Saudi Arabian retail shelves through long-standing brand recognition and promotional slotting fees.
- Health Stores:Specialist organic and natural product retailers concentrated in European cities and Gulf urban centers. Dipasa competes here on organic certification depth with vertically managed Ethiopian and Sudanese sesame sourcing.
- Online Retail:Direct-to-consumer and marketplace platforms accelerating in Turkish and Gulf markets. Pouch formats and subscription models reduce last-mile cost.
- Specialty Stores:Ethnic grocers and Mediterranean food importers serving diaspora communities in Europe and North America. Niche volume with high brand loyalty.
Supermarkets retain the dominant position, yet online retail is gaining share fastest among urban household segments.
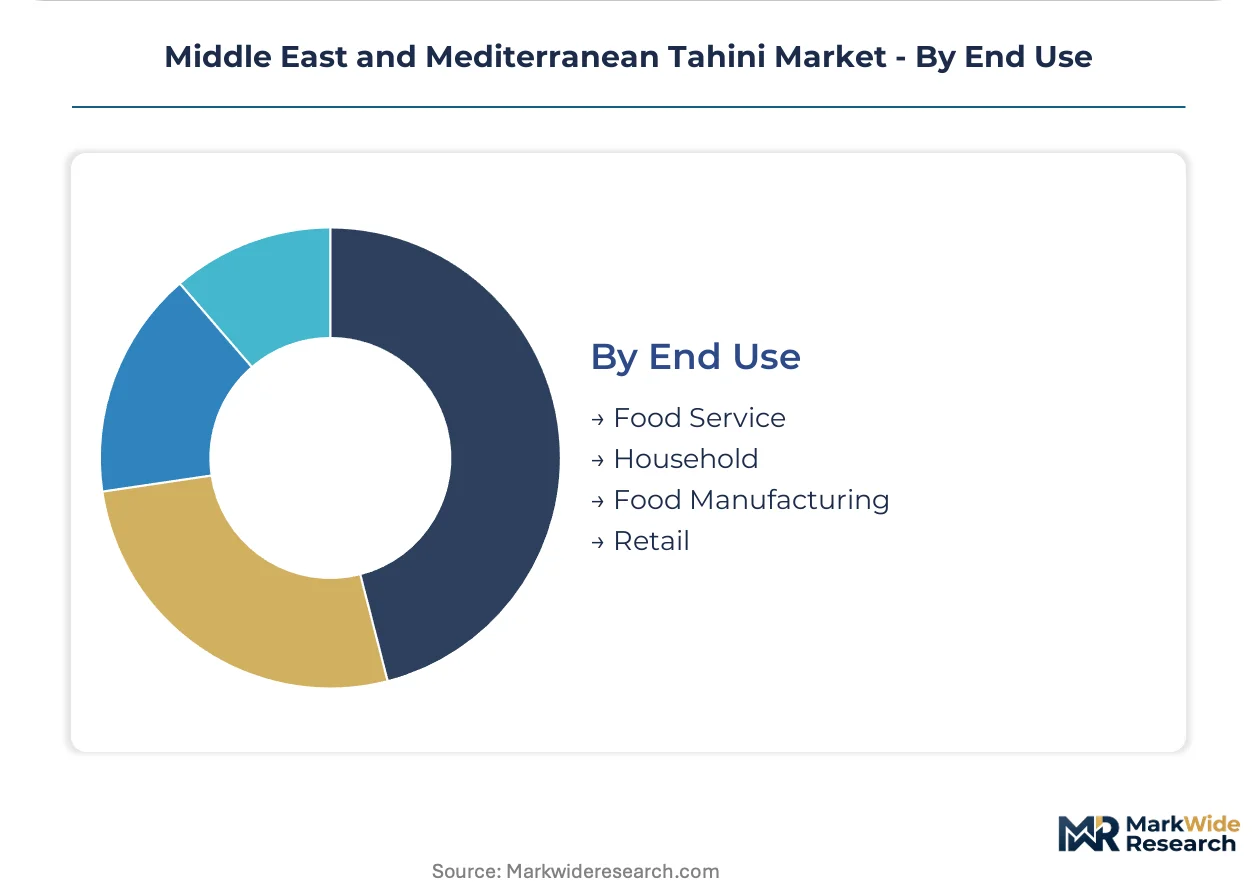
End Use:
Application maturity varies from heritage food service patterns to emerging industrial-scale incorporation, with volume concentration in restaurant chains and growth acceleration in packaged goods manufacturing.
- Food Service:Levantine and Turkish restaurant chains, hotels, and institutional catering. Procurement consolidation favors suppliers with volume consistency, halal certification, and aflatoxin documentation. Istanbul processing hub captures contract migration from fragmented local sources.
- Food Manufacturing:Industrial-scale tahini for packaged hummus, halva, and confectionery lines. Fastest expansion trajectory as heritage mills automate roasting lines to meet controlled-temperature grinding specifications for consistency.
- Household:Direct consumer purchase for table consumption and home recipe preparation. Stable demand anchored in traditional consumption patterns across the Levant and Turkey.
- Retail:Branded packaged goods for resale through third-party channels. Overlaps with other categories but captures private-label programs sourced from Gaziantep and Thessaloniki clusters.
Food Service holds the dominant volume position, while Food Manufacturing shows the steepest expansion trajectory through automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey absorbs tahini predominantly through food manufacturing channels for packaged hummus export, while Saudi Arabia and Levantine markets still route the majority through traditional food service procurement. This consumption-mix differential shapes where processors invest in automation versus brand-building.
Turkey
Istanbul and Gaziantep processing clusters supply European private-label programs and regional brands alike, with the Ministry of Agriculture and Forestry enforcing sesame purity and aflatoxin thresholds that reshape export eligibility. Food manufacturing buyers from packaged hummus lines drive the fastest capacity expansion, pulling heritage mills toward controlled-temperature grinding automation.
Saudi Arabia
Dense supermarket networks anchor household consumption in branded retail formats, with the Saudi Food and Drug Authority applying Gulf-standard labeling and additive restrictions on imported sesame preparations. Halwani Bros. Co. occupies shelf space through long-standing brand recognition, while organic variants capture expanding margin pools in premium aisles.
Lebanon
Beirut and Mount Lebanon host heritage mills with artisanal roasting expertise now rotating toward industrial-scale equipment, as EU REACH-aligned protocols tighten sesame allergen declaration requirements for continental market access. Food service procurement across Levantine restaurant chains still dominates absolute volume, though export-oriented processing is climbing.
Greece
Thessaloniki facilities sustain European export volumes with controlled-temperature grinding lines, with EFSA guidance on sesame allergen labeling influencing packaging reformulation for Mediterranean exporters. Haitoglou Bros. S.A. leverages this cluster for continental distribution, balancing heritage production methods against industrial consistency demands from northern European buyers.
Israel
Tel Aviv and central district processors serve both domestic food service dense with Levantine restaurant chains and export markets requiring halal-adjacent certification alignment. Local tahini culture supports direct table consumption volumes uncommon elsewhere, though industrial-scale supply to packaged goods manufacturing is accelerating fastest.
Middle East and Mediterranean Tahini Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven exporters controlling grinding infrastructure and heritage mill operators competing on authenticity positioning. The market structures around three archetypes: vertically integrated processors with captive sesame sourcing, automation-investing heritage mills, and brand-anchored retail specialists. Competitive moves concentrate on capacity expansion in Istanbul-Gaziantep corridors and certification depth for EU and North American organic channels.
Among Greek and Turkish integrated processors, Haitoglou Bros. S.A. and Halwani Bros. Co. exemplify the scale-tier archetype, with geographic naming signaling Thessaloniki and Saudi anchoring respectively. Dipasa occupies a position within the certification-specialist tier, with vertically managed Ethiopian and Sudanese sesame sourcing representing the backward integration pattern required for organic export eligibility. Mounir Bissat and SESAJAL sit within the heritage-to-industrial transition segment, their Levantine and Mexican naming conventions indicating regional production concentration without specifying strategic posture.
| Leading Market Players |
|---|
| Haitoglou Bros. S.A. |
| Dipasa |
| Halwani Bros. Co. |
| Mounir Bissat |
| SESAJAL |
| Al Wadi Al Akhdar SAL |
| Prince Tahina Ltd |
| Al Kanater SAL |
| El Rashidi El Mizan |
| Others |
Supply & Pricing Matrix
Controlled-temperature grinding capacity at Istanbul and Gaziantep facilities anchors margin structures across conventional and organic grades, compressing unit economics for heritage mills while elevating price floors for export-compliant batches. Scale concentration in Turkish processing clusters shapes procurement leverage for food manufacturing buyers and supermarket chains alike.
Pricing Analysis
Contract-based long-term offtake agreements dominate food manufacturing procurement, with packaged hummus lines locking in volume commitments against spot-market exposure for Ethiopian and Sudanese sesame. Price differentiation rests on EU organic certification depth and aflatoxin documentation consistency, with certified organic tiers commanding shelf-space premiums in European health stores. Cost compression in conventional grades is intensifying because sesame seed currency volatility squeezes processor margins. Food service chains exhibit highest price sensitivity due to procurement consolidation, while Gulf supermarket premium aisles absorb organic premiums with least resistance.
Supply Chain Analysis
Ethiopia, Sudan, and Turkey anchor global sesame sourcing for tahini production, with hulling and roasting capacity concentrated in Istanbul-Gaziantep corridors and Thessaloniki clusters. Raw material flows draw from East African origins, mechanical grinding equipment feeds from European and Asian suppliers, and halal certification documentation hinges on Gulf-standard audit protocols. Single-source vulnerability to Ethiopian harvest fluctuations creates batch-level supply risk for processors lacking multi-origin sourcing. Distribution runs through industrial bulk tubs to food manufacturing lines, with retail bottles and jars penetrating supermarket and health store channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service layers are expanding faster than commodity tahini production, with organic traceability documentation and halal audit protocols generating recurring revenue streams for vertically managed processors.
For Market Incumbents: Secure aflatoxin-testing infrastructure and controlled-temperature grinding automation to defend against heritage mill modernization eroding export eligibility. Anchor capacity expansion in Gaziantep processing corridors where Ministry of Agriculture and Forestry enforcement creates compliance barriers for smaller competitors. Certification investment represents the priority lever for sustaining European private-label contracts against Thessaloniki-based rivals. For New Entrants and Emerging Players: Differentiate on vertically managed Ethiopian and Sudanese sesame sourcing to penetrate North American organic certification channels where Dipasa has established precedent. Target Saudi Arabian retail premium aisles for organic variant introduction, exploiting dense supermarket network shelf-space allocation dynamics. A direct-to-food-service model with halal certification alignment offers the most penetrable entry vector against consolidated Istanbul procurement hubs. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation-investing heritage mills with retrofit grinding infrastructure and captive sesame sourcing relationships. Long-term viability over the coming decade rests on processors bridging artisanal roasting expertise with industrial-scale consistency demands. The signal to watch is EU REACH framework evolution on sesame allergen declarations, which would accelerate compliance cost divergence between certified and conventional tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethiopian and Sudanese Sesame Sourcing | Captive supply of organic-certified raw material secures EU and North American export eligibility against origin volatility. |
| Controlled-Temperature Grinding Automation Deployment | Istanbul and Gaziantep facilities meet food manufacturing consistency specifications for packaged hummus lines. |
| Multi-Standard Certification Architecture Investment | Dual EU REACH and Gulf halal compliance unlocks continental European and Saudi Arabian supermarket access simultaneously. |
| Food Service Chain Procurement Consolidation | Volume contracts with Levantine and Turkish restaurant networks displace fragmented local suppliers through aflatoxin documentation. |
| Organic Traceability Documentation Service Layer | Extended certification cycles generate recurring revenue from European health stores requiring EFSA-aligned allergen declarations. |
Research Methodology
Operator-level perspectives from tahini processing plant managers, sesame procurement leads at integrated processors, supermarket category buyers in Turkey and Saudi Arabia, and food manufacturing R&D directors anchored the qualitative base. Primary fieldwork combined with secondary validation from Turkish Ministry of Agriculture and Forestry enforcement bulletins, EU EFSA allergen guidance updates, Saudi SFDA labeling regulations, and customs trade data on sesame seed flows. Bottom-up capacity assessments at Istanbul-Gaziantep and Thessaloniki clusters triangulated against top-down demand modeling from packaged hummus production lines.
Sensitivity analysis tested forecast outputs against sesame price volatility bands, aflatoxin threshold enforcement scenarios, and automation adoption timelines across heritage mills. Segmentation dimensions modeled include product grade tier, packaging format, distribution channel structure, and end-use application maturity. CAGRs were derived from installed grinding capacity expansion rates correlated with food manufacturing procurement growth trajectories. Industry-specific inputs incorporated Ethiopian and Sudanese harvest yield patterns and EU REACH framework evolution timelines.
The analysis sits within stated boundaries; outcomes outside sustained Turkish processing cluster investment and stable East African sesame flows would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement consistency and heritage mill automation adoption curves. Recalibration cycles align with material shifts in EU allergen declaration protocols and Ministry of Agriculture and Forestry testing regime intensification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Condiments
Acacia Concinna Extracts Market
Spices and Condiments
Garlic Extract Market
Spices and Condiments
Paprika Market
Spices and Condiments
Peeled Garlic Market
Spices and Condiments
Global Dehydrated Onion Market
Spices and Condiments
Rosemary Extracts Market
Spices and Condiments
Middle East and Africa Vanilla Beans and Extract Market
Spices and Condiments
Geranium Oil Market
Spices and Condiments
Dry Chilies Market
Spices and Condiments
Savory Flavor Blends Market
Spices and Condiments
Fermented Mediterranean Pepper and Tomato Complexes Market
Spices and Condiments
Mustard Brown Extract Market
Spices and Condiments
Europe Dehydrated Onion Market
Spices and Condiments
Frangipani Extract Market
Spices and Condiments
Cayenne Pepper Market
Spices and Condiments
Middle East and Africa Dehydrated Onion Market