
 Caramel Chocolate Market | 2026-2036
Caramel Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Caramel Chocolate Market Intelligence
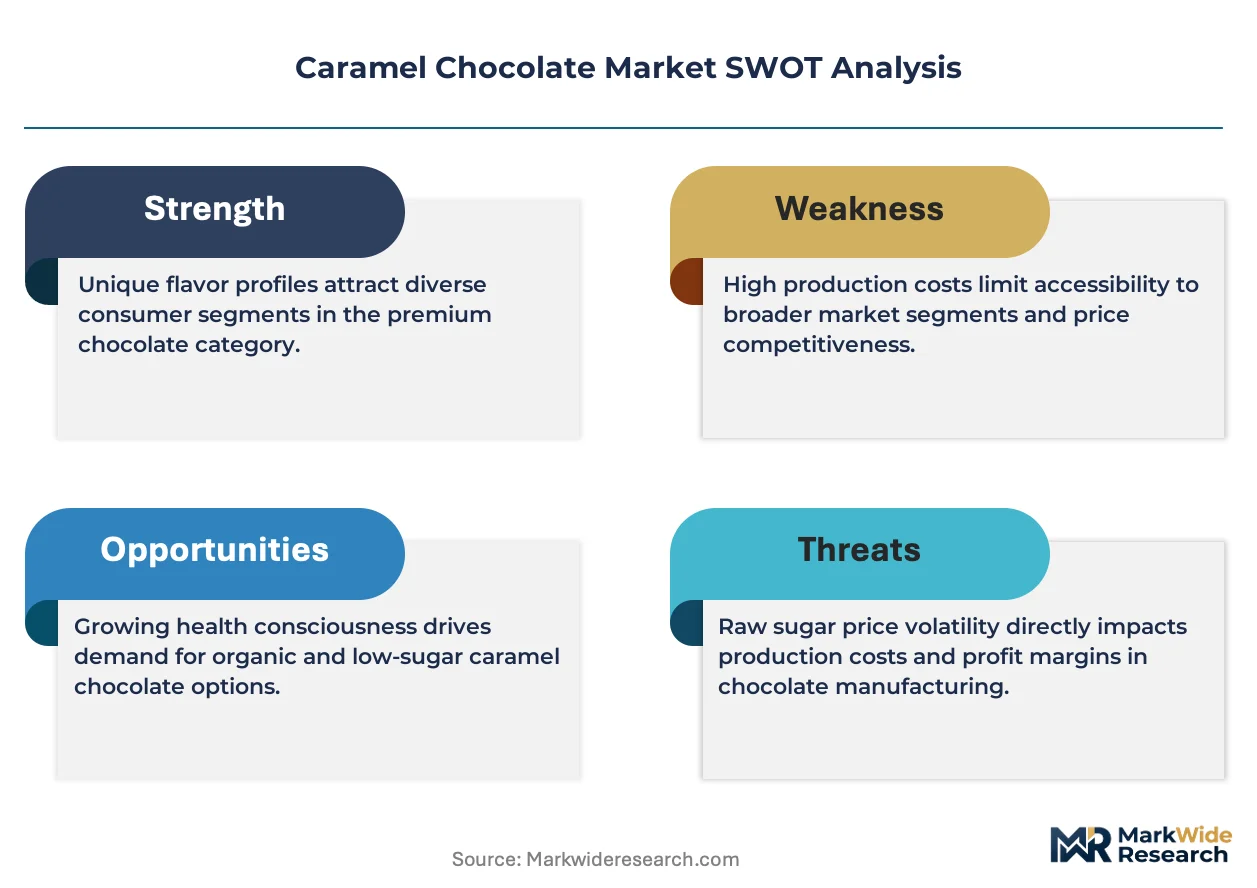
ISO 22000 certification is bifurcating the competitive landscape into qualified mass producers and uncertified regional artisans. Mars, Inc. leverages its integrated cocoa supply chain to sustain cost advantages across milk and dark caramel chocolate lines. Lindt & Sprüngli anchors its premium positioning through controlled-origin cacao sourcing and Swiss manufacturing heritage. Ferrero Group differentiates via hazelnut-caramel fusion products that occupy a distinct texture niche in European and Asian markets.
Caramel chocolate denotes confectionery wherein sugar syrup heated to specific Maillard-reactive temperatures is emulsified into cocoa butter-based matrices, typically containing 20-40% caramel by weight and requiring precise moisture control below 2% to prevent fat bloom. The product serves both impulse retail segments and premium gift occasions where texture contrast drives repeat purchase. Milk chocolate variants dominate volume through supermarket and convenience store channels, while specialty shops concentrate margin pools in single-origin and sea-salt-caramel formulations. Online retail is expanding fastest among distribution channels, particularly for gift pack packaging formats targeting seasonal purchasing.
EU REACH and EFSA govern additive permissions and contaminant thresholds for caramel colorants and flavor precursors in European markets, while FDA GRAS determinations and FSMA preventive controls shape U.S. import and domestic production standards. BIS food safety certifications create compliance thresholds for brands entering India's organized retail sector. Stakeholders must monitor evolving sugar taxation frameworks and front-of-pack labeling mandates that threaten to reclassify caramel chocolate into restricted-advertising categories in multiple jurisdictions.
Market Dynamics
Clean-label ingredient mandates under EU REACH and evolving FDA food labeling standards are compressing formulation flexibility while bifurcating production capabilities between certified mass producers and artisanal operators lacking ISO 22000 qualification.
Growth Catalysts
- EU REACH additive permissions:EFSA-regulated natural caramel colorant approvals enable premium European chocolatiers to reformulate without synthetic alternatives, opening protected-origin designation pathways in France, Belgium, and Switzerland.
- Online retail channel expansion:Gift pack packaging formats targeting seasonal purchasing are capturing repeat buyers through direct-to-consumer platforms, particularly for sea-salt-caramel formulations.
- Maillard-reactive temperature precision:Advanced emulsification equipment achieving sub-2% moisture control is eliminating fat bloom defects and extending shelf stability for export-grade production.
Market Restraints
- Cocoa butter input volatility:Concentrated West African supply exposes margins to weather-driven harvest fluctuations and port logistics disruptions.
- EU sugar taxation frameworks:Front-of-pack labeling mandates in multiple member states threaten reclassification into restricted-advertising categories, compressing impulse retail placement.
- Technical moisture threshold:The 2% ceiling for fat bloom prevention requires capital-intensive climate-controlled facilities inaccessible to uncertified regional artisans.
Strategic Opportunities
- India organized retail penetration:BIS food safety certification thresholds create first-mover advantages for compliant brands entering modern trade channels.
- Hazelnut-caramel fusion textures:Converging nut-processing and confectionery emulsification technologies enable distinct mouthfeel positioning in Asian markets.
- Single-origin cacao sourcing:Controlled-origin supply chain investments unlock Swiss manufacturing heritage premiums for specialty shop channels.
Industry Challenges
- ISO 22000 certification timelines:Eighteen-month audit cycles delay market entry for mid-scale producers targeting EU and US export qualification.
- Legacy equipment integration:Retrofitting existing lines for precise Maillard temperature control requires downtime that seasonal demand windows cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caramel Chocolate Market |
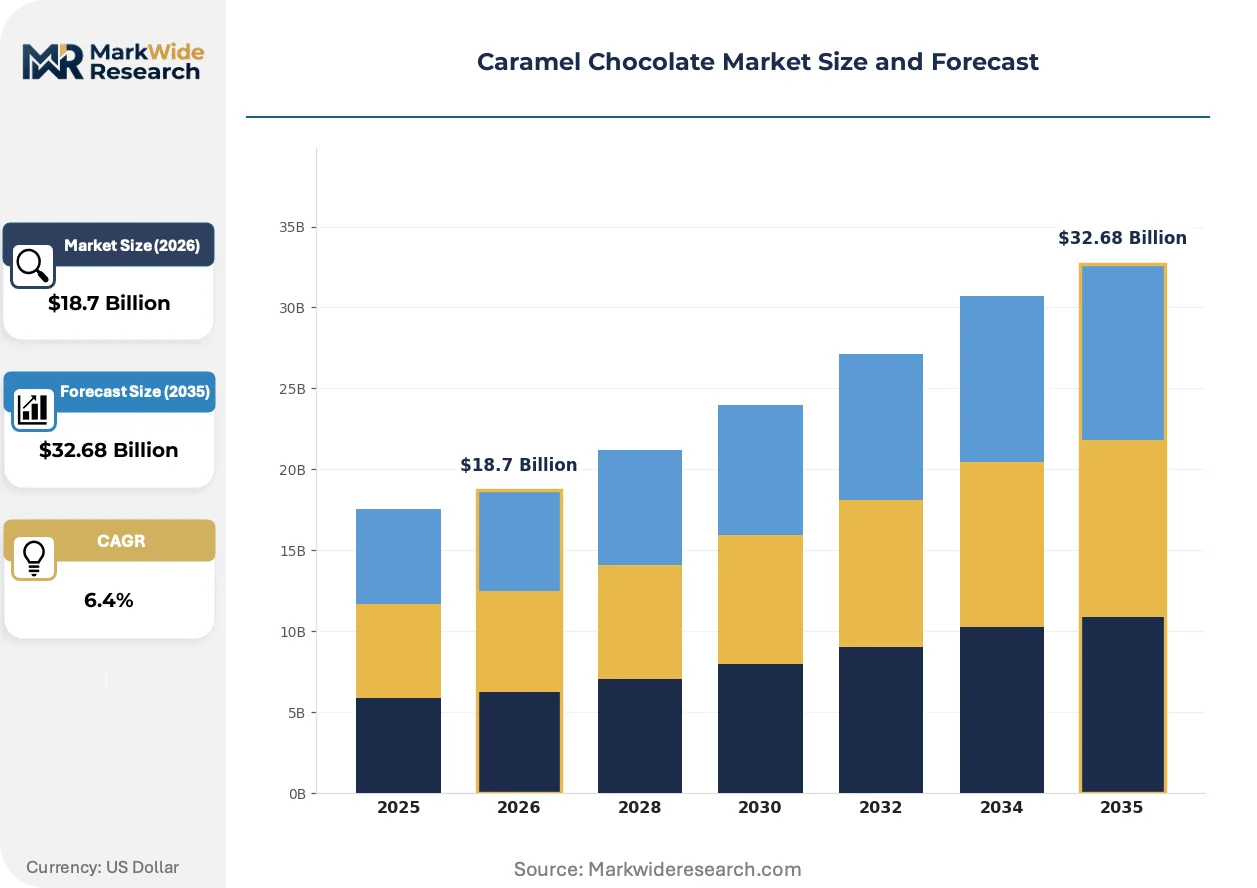
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Assorted Chocolate Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Customer Type: Retail Consumers, Food Service, Manufacturers, Exporters Packaging Type: Bar, Box, Bulk, Gift Pack |
| Companies Covered | Nestlé SA, Lindt & Sprüngli, Mars, Inc., Pladis, Haribo GmbH & Co. KG, Mondelēz International, Inc., The Hershey Company, Storck, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caramel Chocolate Market Strategic Shifts & Innovations
Precision emulsification and controlled-origin supply chains are restructuring competitive advantage around traceability credentials and texture engineering capabilities rather than scale economics alone.
Low-temperature Maillard reaction chambers are decomposing the traditional trade-off between caramel depth and cocoa butter stability. Premium confectionery brands in Switzerland and Belgium are retrofitting production lines with these systems to achieve 40% caramel inclusion without fat bloom defects. The technology is decomposing artisanal production advantages by enabling mass manufacturers to replicate small-batch texture profiles at scale.
EU front-of-pack nutrition labeling mandates under the Nutri-Score framework are forcing reformulation of high-sugar caramel inclusions. Manufacturers are responding with fiber-enhanced and reduced-sugar caramel matrices that maintain Maillard flavor development. Milk chocolate variants targeting supermarket channels face the steepest compliance costs, accelerating investment in clean-label ingredient R&D.
Direct-to-consumer subscription models are displacing seasonal gift purchasing with recurring delivery structures. Specialty chocolatiers in France and Switzerland are capturing lifetime value through curated single-origin assortments rather than impulse retail. This shift concentrates margin pools with brands possessing controlled-origin cacao sourcing and Swiss manufacturing heritage credentials.
Caramel Chocolate Market Segmentation
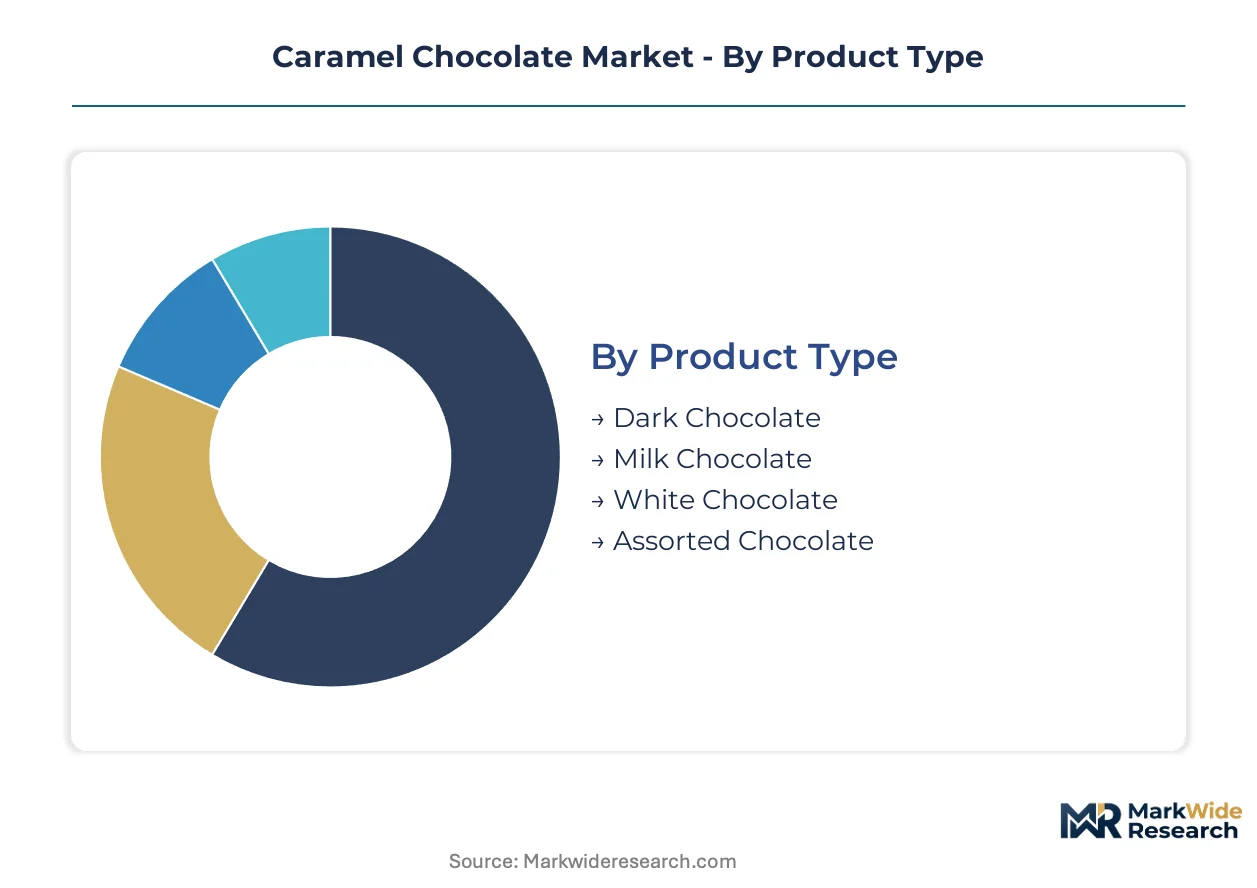
Caramel chocolate segmentation reveals how formulation chemistry, channel economics, and occasion-based purchasing fragment addressable demand. Distinct margin pools attach to each axis, with moisture-control capabilities and origin credentials determining which producers capture premium positioning versus commodity volume.
Product Type:
Channel-mix dynamics concentrate dark and milk variants in impulse retail, while white and assorted formats dominate gift and food service channels where texture differentiation commands price premiums.
- Dark Chocolate:High-cacao formulations with reduced sugar matrices align with EU front-of-pack labeling mandates under Nutri-Score frameworks. Demand concentrates in French and Belgian specialty shops where protected-origin designations validate premium positioning against clean-label regulatory pressure.
- Milk Chocolate:Standard 20-40% caramel emulsification dominates supermarket and convenience store volumes through Mars and Ferrero distribution networks. This segment captures the largest revenue pool but faces steepest reformulation costs from sugar taxation frameworks across EU member states.
- White Chocolate:Cocoa butter-based matrices without cocoa solids serve confectionery fusion applications in Asian markets.
- Assorted Chocolate:Multi-texture formats target seasonal gift purchasing through direct-to-consumer platforms.
Milk chocolate dominates installed base. Dark chocolate is where expansion concentrates.
Distribution Channel:
Cost-tier stratification separates capital-intensive climate-controlled supply chains serving export-grade production from ambient-distribution channels accessible to uncertified regional operators.
- Supermarkets:High-velocity shelf placement requires ISO 22000 certification and front-of-pack compliance with evolving FDA labeling standards. Volume concentrates in Western European chains where private-label expansion compresses branded margins.
- Online Retail:Gift pack packaging formats with sub-2% moisture specifications enable direct-to-consumer subscription models. This channel gains share fastest in Swiss and French markets where single-origin curation justifies recurring delivery premiums.
- Convenience Stores:Impulse placement depends on fat bloom stability through ambient temperature fluctuations.
- Specialty Shops:Controlled-origin cacao sourcing and Swiss manufacturing heritage credentials unlock margin pools inaccessible to mass channels.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Customer Type:
Application-specific formulation requirements separate commodity emulsification for manufacturing inputs from precision-controlled production for retail and export qualification.
- Retail Consumers:Occasion-based purchasing splits between impulse self-consumption and premium gift occasions where texture contrast drives repeat purchase. Demand clusters in EU markets with protected-origin designations.
- Food Service:Dessert and pastry applications require precise Maillard-reactive temperature control for plating stability. This segment concentrates margin in Belgian and Swiss food service channels where artisanal positioning validates ingredient premiums.
- Manufacturers:Bulk caramel inclusions for confectionery and bakery applications prioritize cost over origin credentials.
- Exporters:BIS food safety certification thresholds gate entry into India's organized retail sector for compliant brands.
Retail consumers dominate installed base. Food service is where expansion concentrates.
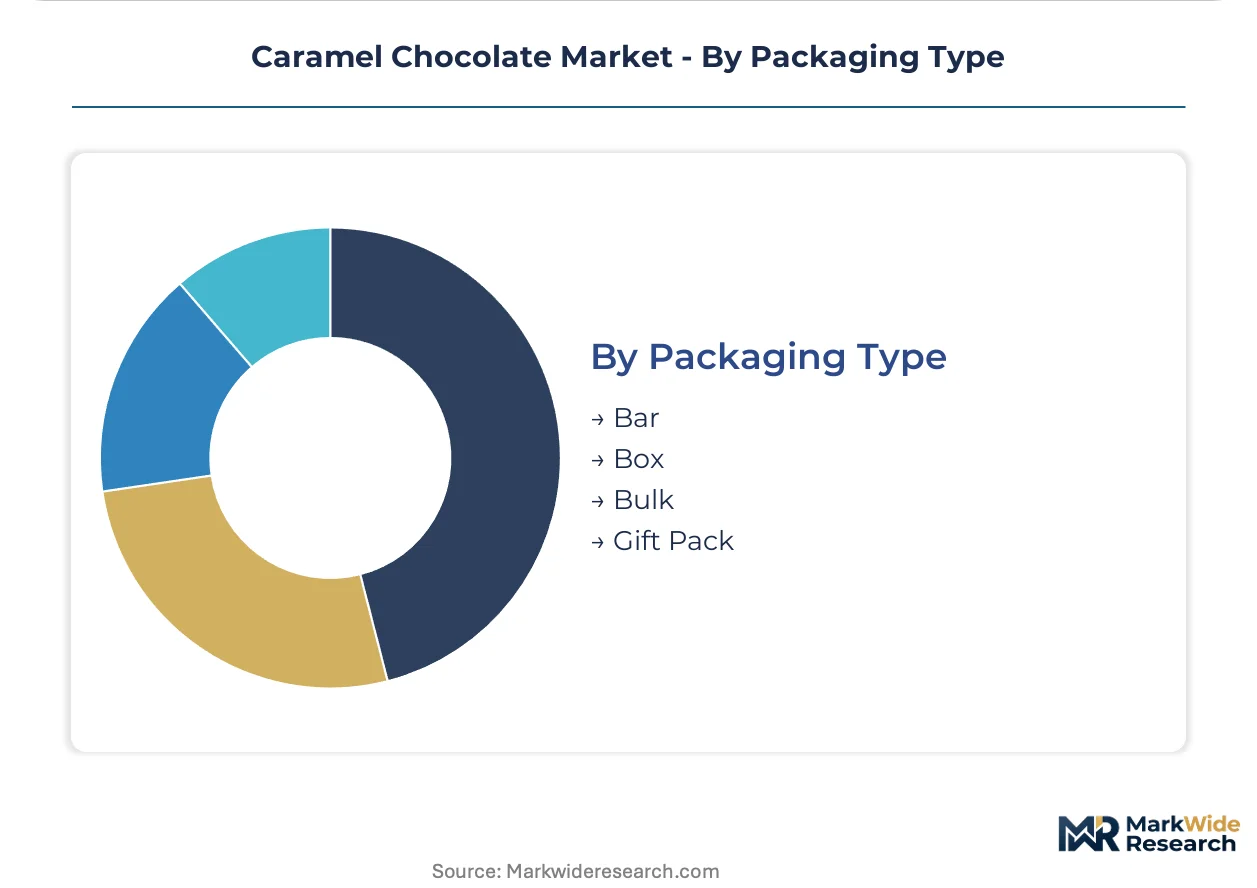
Packaging Type:
Volume-to-margin ratios stratify across formats, with bulk and bar formats capturing scale economics while box and gift pack configurations concentrate premium positioning through seasonal purchasing concentration.
- Bar:Single-serve formats with moisture barriers below 2% target convenience store and supermarket impulse placement. This format captures the highest unit velocity but faces front-of-pack labeling reclassification risks in multiple jurisdictions.
- Gift Pack:Assortment curation with controlled-origin credentials enables direct-to-consumer subscription models. Demand concentrates in Swiss and French markets where Swiss manufacturing heritage validates premium pricing.
- Box:Multi-piece formats serve seasonal occasion purchasing through specialty retail channels.
- Bulk:Food service and manufacturing inputs prioritize unit cost over origin traceability.
Bar formats dominate installed base. Gift pack is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Antwerp-Bruges processes the majority of European cocoa bean imports, underwriting Belgium's central role in caramel chocolate processing and re-export logistics across the continent.
Belgium
Protected-origin praline traditions and concentrated artisanal chocolatier clusters in Brussels and Bruges drive premium demand. EFSA-regulated natural caramel colorant approvals enable reformulation without synthetic alternatives. The Port of Antwerp-Bruges anchors import logistics for cocoa butter destined to Walloon processing facilities.
Switzerland
Swiss manufacturing heritage credentials and controlled-origin cacao sourcing justify recurring delivery premiums in direct-to-consumer channels. Swissmedic food safety standards exceed baseline EU requirements, creating export qualification advantages. The Zurich-Geneva corridor concentrates Lindt & Sprüngli production and specialty retail distribution.
France
Sea-salt-caramel formulations and single-origin curation capture lifetime value through subscription models in Paris and Lyon markets. EU REACH clean-label mandates reshape formulation requirements for mass retail placement. The Île-de-France region hosts premium confectionery R&D and protected-origin designation lobbying.
Germany
Haribo GmbH & Co. KG and Storck anchor mass-market caramel inclusion production for European supermarket channels. Germany's national food safety regulator enforces strict contaminant thresholds for caramel flavor precursors. The Cologne-Bonn industrial corridor concentrates confectionery machinery manufacturing and export-grade packaging.
United States
Impulse retail placement in convenience stores and supermarket chains depends on FDA GRAS determinations for caramel colorants. The Hershey Company and Mars, Inc. leverage integrated distribution networks across Eastern Seaboard ports. FSMA preventive controls shape domestic production standards and import inspection protocols at Port Newark-Elizabeth.
Caramel Chocolate Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with ISO 22000 qualification bifurcating mass producers from uncertified artisans. The vendor base stratifies into three archetypes: integrated cocoa processors with captive supply chains, heritage-positioned premium chocolatiers, and nut-confectionery fusion specialists. Dominant competitive moves include backward integration into cacao sourcing and retrofitting production lines for precision emulsification.
Within the heritage-premium tier, Lindt & Sprüngli AG exemplifies Swiss manufacturing credential positioning, while Mars, Inc. represents scale-driven integrated supply chain control. Ferrero Group occupies the fusion-specialist position, leveraging hazelnut-processing capabilities for distinct texture formulations.
| Leading Market Players |
|---|
| Nestlé SA |
| Lindt & Sprüngli |
| Mars, Inc. |
| Pladis |
| Haribo GmbH & Co. KG |
| Mondelēz International, Inc. |
| The Hershey Company |
| Storck |
| Ferrero Group |
| Others |
Cost & Logistics Intelligence
Scale economies in cocoa butter processing and Maillard-reactive emulsification equipment anchor cost structures across the caramel chocolate value chain, concentrating pricing power with ISO 22000-certified mass producers while compressing margins for uncertified regional artisans lacking climate-controlled facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the caramel chocolate market by certification grade and origin credentials. Premium tiers command valuation multiples through Swiss manufacturing heritage and controlled-origin cacao sourcing, while standard supermarket channels face cost compression from private-label expansion and EU sugar taxation frameworks. Price erosion runs through milk chocolate variants where reformulation costs for Nutri-Score compliance intensify margin pressure. Food service buyers exhibit lowest price sensitivity due to plating stability requirements and artisanal positioning premiums, whereas convenience store channels demonstrate highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Inventory cycles for cocoa butter extend twelve to eighteen months from West African harvest through European processing, tethering production scheduling to weather-driven supply volatility and port logistics disruptions at Abidjan and San Pedro. Côte d'Ivoire, Ghana, and Ecuador concentrate raw bean supply, while Belgium and Switzerland anchor downstream processing and premium formulation. Cocoa butter, natural caramel colorants, and sea salt inputs draw from geographically dispersed suppliers with single-source vulnerability in West African bean origins. Distribution runs through Antwerp-Bruges port logistics for European re-export and Eastern Seaboard customs clearance for U.S. market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision emulsification technology and EU front-of-pack labeling mandates constitute simultaneous disruption vectors, rewarding capital deployment into low-temperature Maillard systems while penalizing legacy formulation portfolios.
For Market Incumbents: Shield premium positioning by retrofitting production lines for sub-2% moisture control before seasonal demand windows close, and secure backward integration into controlled-origin cacao sourcing to validate Swiss manufacturing heritage claims against emerging fusion specialists. ISO 22000 certification gaps among mid-scale competitors create defensive moats if audit timelines are accelerated. For New Entrants and Emerging Players: Direct-to-consumer subscription curation represents the most penetrable service-layer gap, as incumbents under-invest in recurring delivery infrastructure outside Swiss and French core markets. Target India's organized retail sector through BIS food safety certification, leveraging first-mover advantages before compliance thresholds harden. Lead with single-origin storytelling and gift pack packaging formats to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage-positioned premium chocolatiers with controlled-origin supply chains and direct-to-consumer platform infrastructure. Five-to-ten year viability favors acquisition targets possessing both Swiss manufacturing credentials and retrofit-ready precision emulsification capacity. Monitor EU sugar taxation framework expansion as the critical inflection signal for portfolio reclassification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Emulsification Retrofit | Low-temperature Maillard chambers enable 40% caramel inclusion without fat bloom defects, replicating artisanal textures at mass scale. |
| Controlled-Origin Cacao Integration | Backward integration into Ecuadorian and Venezuelan single-origin supply validates premium positioning against commodity competitors. |
| Direct-to-Consumer Platform Buildout | Subscription models displace seasonal gift purchasing with recurring revenue structures in Swiss and French markets. |
| BIS Certification Pre-Positioning | Early compliance creates gated access to India's modern trade channels before threshold enforcement intensifies. |
| Clean-Label Reformulation R&D | Fiber-enhanced caramel matrices maintain Maillard depth under EU Nutri-Score sugar reduction mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with premium chocolatier R&D directors, supermarket category buyers, food service procurement managers, and cocoa supply chain coordinators. Secondary validation drew from EFSA additive permission databases, FDA GRAS determination filings, EU REACH regulatory updates, and customs trade records for cocoa butter imports. Bottom-up volume modeling triangulated against top-down value estimates derived from channel-specific margin structures.
Across the analysis window, forecasts incorporated product type segmentation by cacao content and caramel inclusion rate, distribution channel stratification by certification requirements, and customer type differentiation between impulse retail and premium gift occasions. CAGRs were derived from trend extrapolation of clean-label reformulation adoption curves and online retail channel penetration rates. Model inputs included EU sugar taxation framework expansion scenarios and precision emulsification equipment deployment timelines.
Underlying assumptions cover sustained EU REACH enforcement continuity and stable West African cocoa supply, with deviation risk concentrated in weather-driven harvest fluctuations and front-of-pack labeling reclassification mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
North America Gummy Market
Confectionery
North America Confectionery Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Global Non-Cocoa Confectionery Market
Confectionery
Sugar Free Candy Market
Confectionery
Canada Chocolate Market
Confectionery
Europe Chocolate Market
Confectionery
Licorice Candy Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Low Calorie Nutella Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Confectionery Fats Market
Confectionery
United States and Europe Macarons Market
Confectionery
Brazil Chocolate Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
Salted Caramel Products Market