
 Middle East and Africa Chocolate Market | 2026-2036
Middle East and Africa Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Chocolate Market Foresight
Market Context
Skilled cocoa-bean sourcing expertise is collapsing across West African cooperatives, forcing manufacturers to rebuild traceability networks from farm to processor. Nestle S.A. leverages its existing dairy logistics infrastructure to secure milk powder supply chains across Egypt and Morocco. Mondelez International anchors its regional competitiveness through large-scale manufacturing partnerships in Ghana and Côte d'Ivoire. Patchi differentiates via premium positioning in Gulf luxury retail corridors where gifting occasions drive basket values.
Technical Definition and Segments
Chocolate comprises a suspension of cocoa solids and sugar within a continuous fat phase of cocoa butter, typically refined to particle sizes below 30 microns for mouthfeel and tempered to stabilize polymorphic crystal forms V and VI. Its primary commercial purpose spans direct consumption, confectionery ingredient applications, and artisanal bakery formulations where fat bloom resistance and snap quality determine shelf appeal. Milk Chocolate occupies the dominant volume position across supermarkets and convenience stores due to price accessibility and childhood brand loyalty. Dark Chocolate registers the fastest structural expansion among specialty shops and online retail channels as Gulf consumers associate higher cocoa percentages with wellness positioning. Coated Snacks within the Form dimension concentrate margin pools through industrial foodservice contracts and cinema-channel exclusivity.
Regulatory Outlook
South Africa's Department of Health enforces strict cadmium limits on cocoa imports, while Saudi Food and Drug Authority and UAE's Ministry of Climate Change and Environment mandate bilingual labeling and halal certification for all chocolate distributed through domestic channels. These frameworks elevate compliance costs for European exporters but create protected terrain for regional producers like Al Nassma Chocolate LLC that already navigate Gulf regulatory requirements. Stakeholders must monitor how Egypt's food safety authority harmonizes its standards with Gulf Cooperation Technical Regulation streams to avoid fragmented approval bottlenecks.
Market Dynamics
FSSAI-equivalent food safety protocols across South Africa and Nigeria are tightening cadmium and lead thresholds, forcing manufacturers to rebuild traceability networks from West African cooperatives through Gulf retail channels.
Growth Catalysts
- Halal Certification Mandates:Saudi Food and Drug Authority and UAE's Ministry of Climate Change and Environment require bilingual labeling and halal certification for all domestic chocolate distribution, creating protected terrain for compliant regional producers.
- Premium Gifting Traditions:Mall-based specialty shops and airport duty-free channels in Saudi Arabia are expanding rapidly, intensifying cocoa butter demand across the Gulf as basket values rise on ceremonial occasions.
- Dark Chocolate Wellness Positioning:Gulf consumers increasingly associate higher cocoa percentages with health benefits, accelerating structural expansion through specialty shops and online retail channels.
Market Restraints
- Cocoa Butter Input Volatility:Skilled cocoa-bean sourcing expertise is collapsing across West African cooperatives, forcing manufacturers to absorb reconstruction costs for farm-to-processor traceability networks.
- Heavy Metal Compliance Costs:South Africa's Department of Health enforces strict cadmium limits on cocoa imports, elevating testing and rejection expenses for European exporters unfamiliar with regional thresholds.
- Milk Powder Supply Concentration:Egypt and Morocco depend on limited dairy logistics infrastructure for milk chocolate production, exposing formulations to powder availability disruptions.
Strategic Opportunities
- Underpenetrated Nigerian Retail:FSSAI-equivalent protocols in Nigeria are tightening but enforcement capacity remains uneven, creating first-mover advantage for compliant manufacturers establishing direct distribution.
- Coated Snack Industrial Contracts:Cinema-channel exclusivity and foodservice agreements for coated chocolate snacks concentrate margin pools beyond traditional retail.
- Egypt-GCC Regulatory Harmonization:Egypt's food safety authority is aligning standards with Gulf Cooperation Technical Regulation streams, promising streamlined approval bottlenecks for cross-border operators.
Industry Challenges
- Crystallization Expertise Shortage:Tempering operations requiring polymorphic crystal form stabilization face talent gaps as experienced technicians retire without structured apprenticeship pipelines.
- Particle Refinement Capex:Achieving sub-30 micron particle sizes for premium mouthfeel demands continuous conching equipment investments that mid-scale processors struggle to finance.
- Dual Certification Timelines:Simultaneous halal and heavy metal compliance verification creates elongated product launch cycles, compressing seasonal gifting windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Chocolate Market |
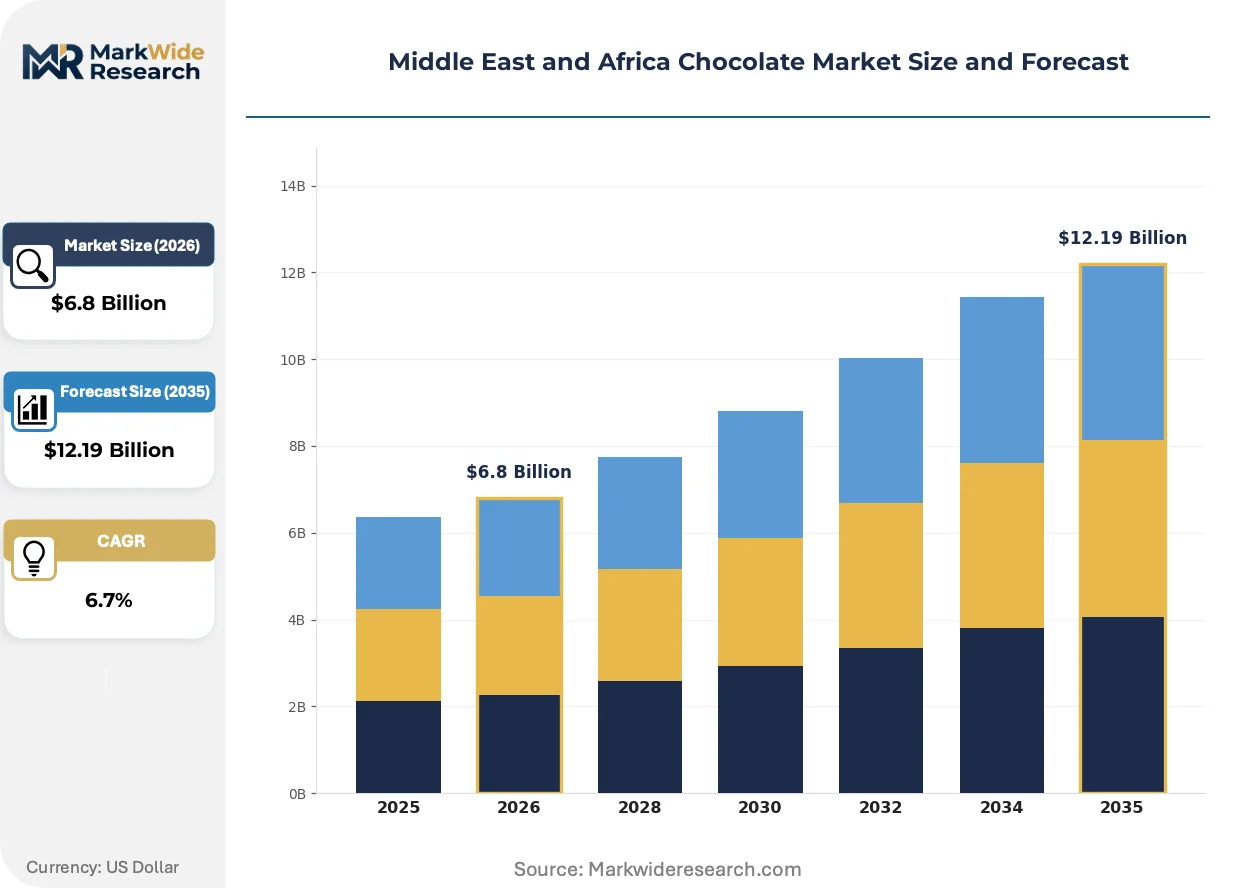
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Foodservice, Bakeries, Confectionery Form: Bars, Pralines, Truffles, Coated Snacks Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops |
| Companies Covered | Ferrero Group, Patchi, Nestle S.A., Tiger Brands Limited, Al Nassma Chocolate LLC, Mondelez International Inc., Barry Callebaut, Chocoladefabriken Lindt & Sprüngli AG, Mars Incorporated, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Chocolate Market Shifts & Advancements
Traceability technologies and wellness-positioned formulations are restructuring competitive advantage across Middle East and Africa chocolate markets, while regulatory convergence between North Africa and Gulf states reshapes cross-border operations.
Blockchain-enabled farm-to-bar verification is fragmenting traditional commodity sourcing relationships. Artisanal producers and premium brands in Saudi Arabia and UAE are adopting distributed ledger systems to document cooperative provenance. This technology is fragmenting established supplier hierarchies by enabling direct farmer-processor contracts that bypass conventional trading structures.
South Africa's Department of Health cadmium enforcement and Saudi Food and Drug Authority halal mandates are tightening in parallel. These frameworks are diverging from European standards, forcing exporters to maintain separate formulation and documentation streams. Dark chocolate imports face the strictest scrutiny as higher cocoa solids concentrate heavy metal content.
Airport duty-free and mall-based specialty shops are displacing supermarket dominance in Gulf gifting segments. Saudi consumers now prioritize origin stories and certification transparency over price accessibility for ceremonial purchases. This rotation is most visible in Jeddah and Riyadh retail corridors where Patchi and comparable premium operators command premium positioning.
Middle East and Africa Chocolate Market Segmentation
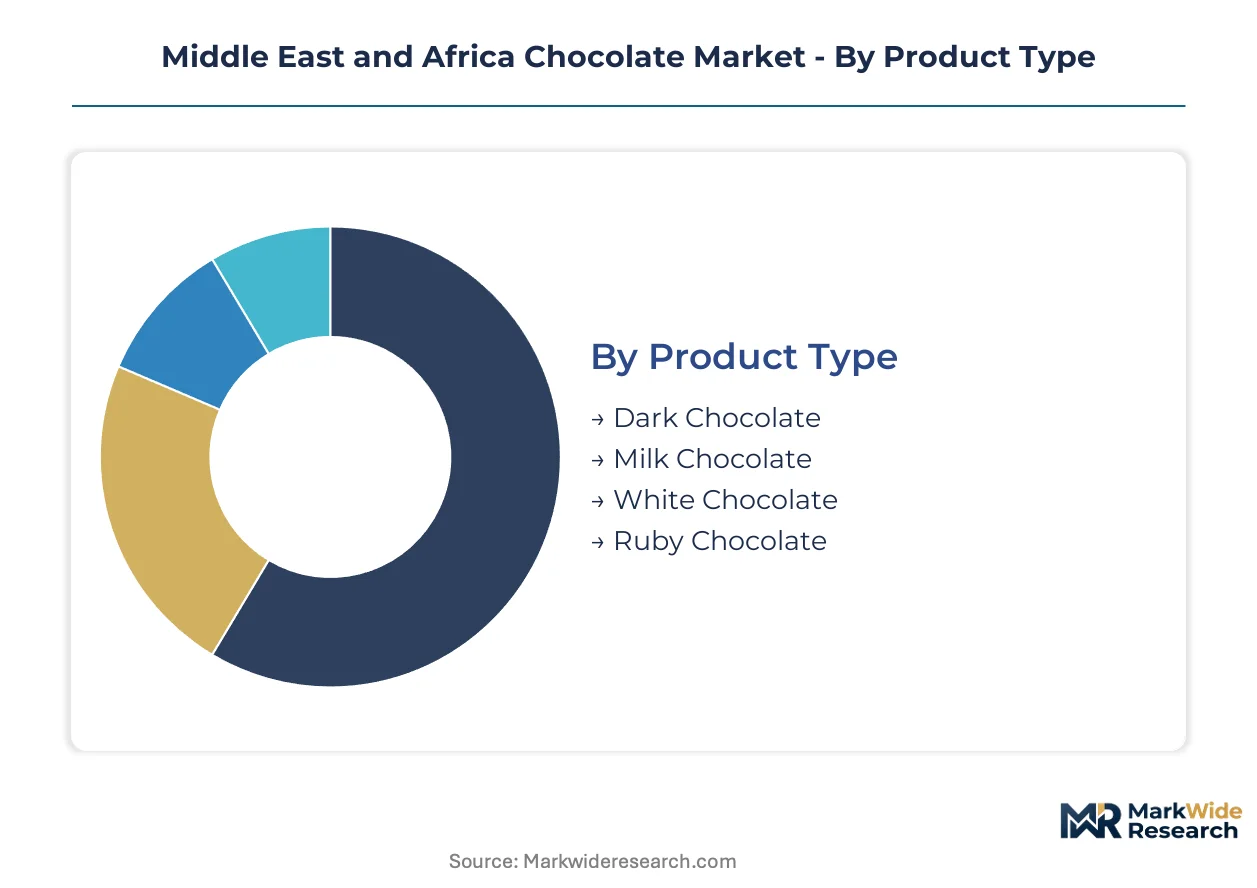
Segmentation across the Middle East and Africa Chocolate Market reveals divergent growth mechanics between Gulf premium corridors and West African volume basins. Each dimension exposes distinct procurement patterns, regulatory exposures, and margin architectures that reshape manufacturer resource allocation.
Product Type:
Domestic production concentrates on milk chocolate formulations for mass-market penetration across Egypt and Morocco, while dark chocolate demand flows disproportionately through Saudi Arabia and UAE import channels.
- Milk Chocolate:Formulations combine cocoa solids with milk powder within a continuous cocoa butter fat phase, typically carrying 10-20% cocoa content. Egyptian and Moroccan manufacturers anchor regional supply through Nestle's dairy logistics infrastructure, though powder availability disruptions expose formulation continuity risks.
- Dark Chocolate:Higher cocoa percentages (70% and above) concentrate heavy metal content, triggering strict cadmium enforcement by South Africa's Department of Health. Gulf specialty shops and online retail channels absorb premium-priced imports as wellness positioning accelerates ceremonial gifting demand.
- White Chocolate:Cocoa butter dominates the fat phase without cocoa solids, requiring precise tempering to stabilize polymorphic crystal forms for snap quality.
- Ruby Chocolate:Ruby cocoa bean varieties deliver natural pink coloration without artificial additives, appealing to Instagram-driven retail aesthetics in Dubai and Riyadh mall corridors.
Milk chocolate holds the largest share; momentum sits with dark chocolate.
End User:
Cost tier stratification separates commodity-scale foodservice contracts from premium retail ceremonial purchases, with bakeries occupying a mid-tier equipment-dependent position.
- Retail Consumers:Direct consumption spans supermarket impulse purchases and airport duty-free gifting corridors. Saudi Arabia's mall-based specialty shops concentrate basket value elevation during Ramadan and Eid occasions.
- Foodservice:Industrial-scale procurement for hotels and catering operations demands fat bloom resistance and extended shelf stability under ambient Gulf temperatures.
- Bakeries:Artisanal formulations require tempered chocolate with precise viscosity control for enrobing and decoration applications.
- Confectionery:Ingredient supply to regional manufacturers depends on particle refinement below 30 microns for seamless integration into compound coatings.
Retail consumers command volume leadership; foodservice contracts concentrate margin pools through exclusivity arrangements.
Form:
Volume concentration favors bar formats for manufacturing efficiency, while praline and truffle production demands skilled labor pools that contract across Gulf states.
- Bars:Standardized molding enables mass production with minimal labor input, dominating supermarket and convenience store distribution across Nigeria and South Africa.
- Coated Snacks:Cinema-channel exclusivity and industrial foodservice agreements generate contracted revenue streams. Saudi multiplex operators and UAE entertainment venues lock in supply through annual procurement cycles.
- Pralines:Molded shells with soft ganache centers require tempering expertise scarce across regional processing facilities.
- Truffles:Hand-rolled formats with cocoa powder dusting occupy premium positioning in duty-free and specialty retail.
Bars maintain production dominance; coated snacks climb fastest through channel exclusivity.
Distribution Channel:
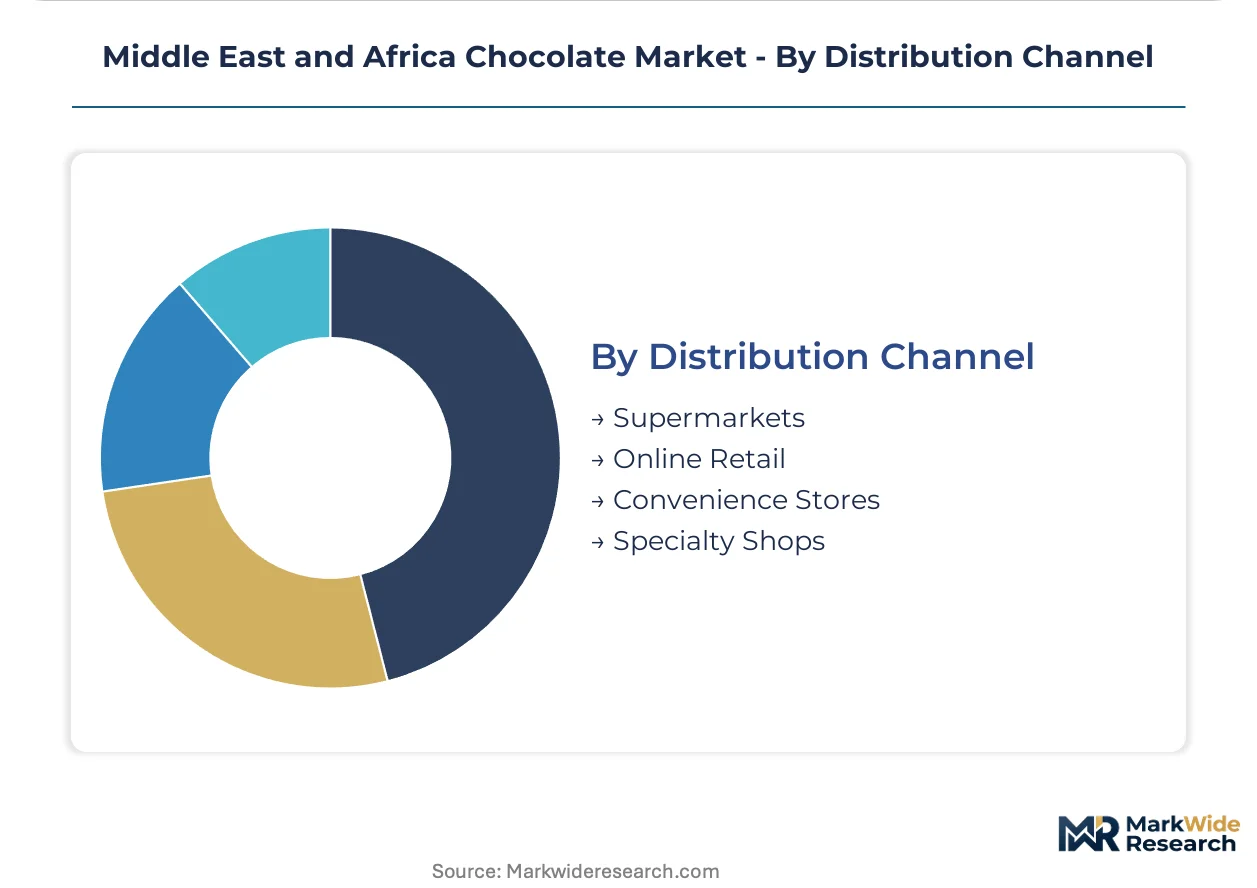
Supply concentration in Saudi Arabia and UAE retail corridors contrasts with fragmented Nigerian and Egyptian wholesale networks.
- Specialty Shops:Patchi and comparable premium operators command ceremonial gifting positioning in Jeddah and Riyadh, where origin stories and halal certification transparency override price sensitivity.
- Online Retail:Direct-to-consumer platforms bypass traditional import bottlenecks, accelerating dark chocolate access for wellness-seeking demographics across Gulf Cooperation Council states.
- Supermarkets:Price-accessible milk chocolate formats dominate childhood brand loyalty capture in South African and Nigerian mass retail.
- Convenience Stores:Impulse-oriented single-serve packaging targets transit corridors and petrol station networks.
Supermarkets retain volume foundation; online retail gains share fastest through regulatory streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA mandates in Saudi Arabia anchor the Middle East and Africa chocolate market's regulatory framework, with halal certification and bilingual labeling requirements cascading across Gulf Cooperation Council states and reshaping cross-border trade corridors.
Saudi Arabia
Mall-based specialty shops in Jeddah and Riyadh drive ceremonial gifting demand during Ramadan and Eid, elevating cocoa butter consumption per transaction. SFDA enforces strict halal certification and bilingual Arabic-English labeling for all domestic chocolate distribution. Airport duty-free channels at King Abdulaziz International and King Khalid International concentrate premium import flows.
United Arab Emirates
Dubai's retail corridors and Abu Dhabi's luxury hospitality sector absorb high-margin dark chocolate imports positioned for wellness-conscious consumers. MOCCAE mandates align with Saudi halal frameworks, creating regulatory continuity across Emirates. Mall operators in Dubai Festival City and Yas Island anchor premium brand flagship presence.
South Africa
Supermarket chains in Gauteng and Western Cape provinces maintain milk chocolate volume leadership through childhood brand loyalty capture. The Department of Health enforces cadmium limits on cocoa imports that exceed European thresholds, elevating testing costs for European exporters. Industrial processing clusters around Johannesburg concentrate compound chocolate production for regional foodservice.
Egypt
Domestic manufacturers leverage Nestle's dairy logistics infrastructure to secure milk powder supply chains for mass-market formulations. The national food safety authority is harmonizing standards with Gulf Cooperation Technical Regulation streams to streamline cross-border approvals. Cairo-Alexandria corridor production facilities supply both domestic retail and Libyan re-export channels.
Nigeria
FSSAI-equivalent protocols are tightening cadmium and lead thresholds, though enforcement capacity remains uneven across Lagos and Kano distribution networks. First-mover advantage accrues to compliant manufacturers establishing direct distribution before regulatory maturation. Ikeja industrial zones concentrate local confectionery ingredient processing for West African re-export.
Middle East and Africa Chocolate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa chocolate market. Multinational confectionery conglomerates with integrated cocoa processing capabilities occupy scale-driven positions, while regional specialists command premium gifting segments through certification proximity and cultural positioning. Three archetypes dominate: Gulf-based halal-certified premium operators, West African manufacturing-anchored volume players, and European import-dependent dark chocolate specialists. Competitive moves concentrate on regulatory compliance pre-emption and duty-free channel exclusivity arrangements.
Among regional premium operators, Patchi and Al Nassma Chocolate LLC exemplify archetypes that leverage Gulf regulatory familiarity to capture ceremonial gifting margins. Nestle S.A. and Mondelez International occupy positions anchored by dairy logistics infrastructure and large-scale manufacturing partnerships across North and West Africa. These four entities represent distinct strategic postures: certification-proximate regional premium, multinational volume-scale, and import-dependent specialty positioning.
| Leading Market Players |
|---|
| Ferrero Group |
| Patchi |
| Nestle S.A. |
| Tiger Brands Limited |
| Al Nassma Chocolate LLC |
| Mondelez International Inc. |
| Barry Callebaut |
| Chocoladefabriken Lindt & Sprüngli AG |
| Mars Incorporated |
| Others |
Supply & Pricing Matrix
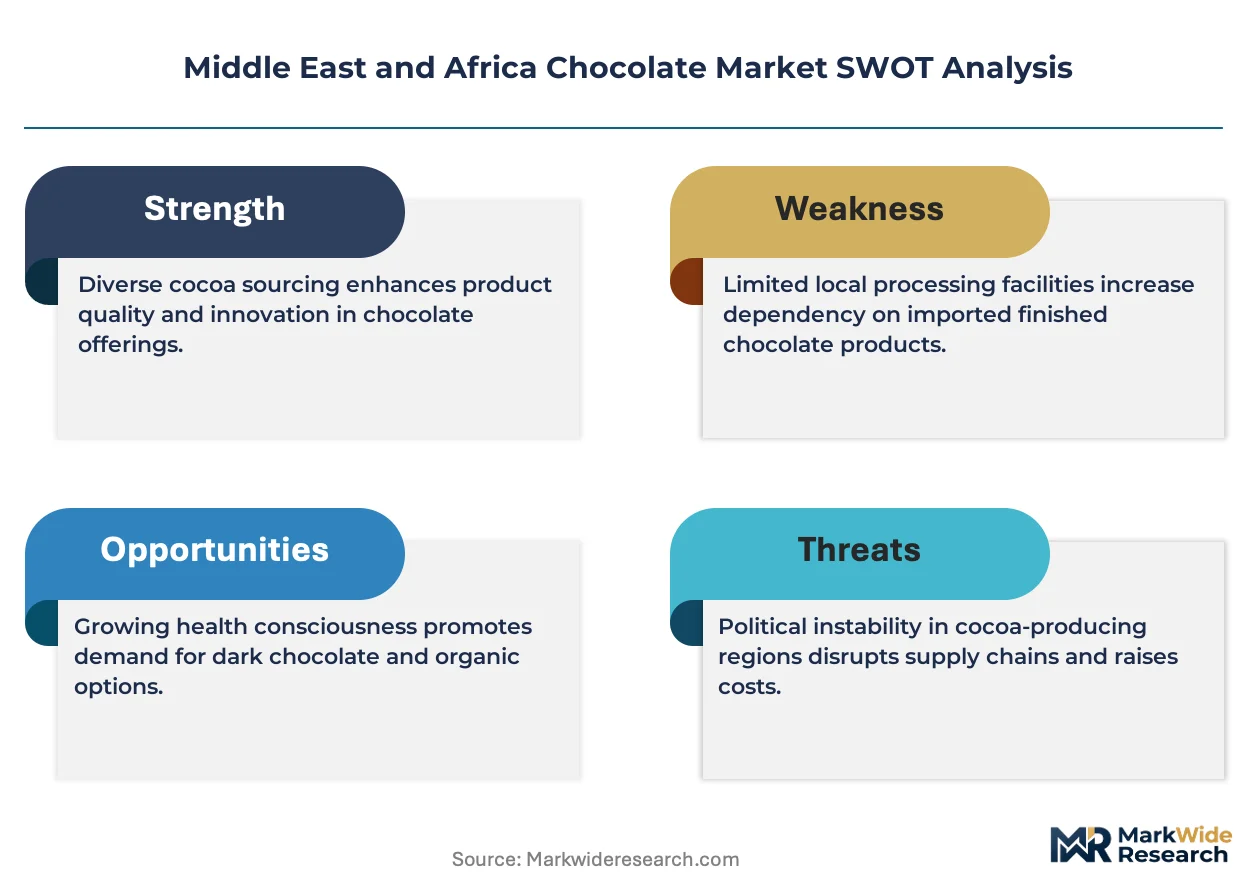
Long-term offtake contracts between West African cooperatives and Gulf processors lock in cocoa butter supply access while fixing price visibility against London futures volatility. These arrangements concentrate procurement power among manufacturers with established traceability networks, leaving spot-market buyers exposed to premium spreads during Ramadan demand spikes.
Pricing Analysis
Saudi Arabia commands a 15-25% premium over Egyptian retail shelves for equivalent milk chocolate formulations, reflecting halal certification compliance costs and duty-free channel positioning. Three-tier pricing structure across premium, standard, and economy levels separates Patchi-tier ceremonial gifting from mass-market Nestle placements and private-label economy bars. Price differentiation hinges on cocoa percentage certification and bilingual labeling compliance, with SFDA-mandated documentation adding 8-12% to landed costs for European exporters. Cost compression in the standard tier is intensifying because Egyptian manufacturers are expanding capacity for Libyan re-export, squeezing margin buffers for import-dependent players.
Supply Chain Analysis
Port congestion at Lagos Apapa and Jebel Ali container availability constraints are elevating inbound logistics costs for cocoa butter shipments originating from Côte d'Ivoire and Ghana. Supply concentrates in Côte d'Ivoire, Ghana, and Nigeria for bean sourcing, with Egyptian and Moroccan facilities dependent on Nestle's dairy logistics infrastructure for milk powder. Raw material dependencies span cocoa butter, milk powder, and lecithin emulsifiers. Single-source vulnerability runs through West African cooperative traceability networks as skilled sourcing expertise collapses. Distribution runs through mall-based specialty shops in Jeddah and Riyadh for premium tiers, with supermarket chains anchoring volume across South Africa and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa chocolate market sits in early-cycle expansion as Gulf gifting traditions professionalize and Nigerian regulatory enforcement matures, creating penetrable white space for compliant operators ahead of threshold tightening.
For Market Incumbents: Consolidate backward integration into West African cooperative networks before traceability expertise scarcity hardens into permanent bottleneck. Lock in annual capacity reservation agreements with Saudi multiplex operators and UAE entertainment venues to defend margin pools against emerging coated-snack competitors. Prioritize halal certification pre-emption as Egypt-GCC regulatory harmonization accelerates cross-border approval timelines.
For New Entrants and Emerging Players: Anchor in Nigerian direct distribution infrastructure before FSSAI-equivalent enforcement capacity matures, capturing first-mover positioning in Africa's most populous market. Target online retail channels across Gulf Cooperation Council states where regulatory streamlining accelerates dark chocolate access for wellness demographics. Pursue blockchain-enabled farm-to-bar verification as the go-to-market angle to bypass established commodity trading hierarchies.
For Investors and Strategic Acquirers: Capital is best deployed toward Gulf-based halal-certified premium operators with established duty-free channel relationships and cultural positioning leverage. The 5-10 year viability window favors acquisition targets with captive cooperative sourcing networks rather than import-dependent European specialty brands. Monitor Egypt's food safety authority harmonization pace with Gulf Cooperation Technical Regulation streams as the inflection signal for cross-border operational scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Pre-emption | SFDA and MOCCAE mandates create protected terrain for compliant regional producers against European exporters. |
| Blockchain Traceability Deployment | Farm-to-bar verification enables direct farmer-processor contracts that fragment conventional trading structures. |
| Coated Snack Channel Exclusivity | Cinema-channel and foodservice agreements concentrate margin pools beyond traditional retail in Saudi multiplexes. |
| West African Cooperative Integration | Traceability network reconstruction absorbs collapsing sourcing expertise across Côte d'Ivoire and Ghana. |
| Egypt-GCC Regulatory Harmonization | Standards alignment streamlines approval bottlenecks for cross-border operators targeting Libyan re-export channels. |
Research Methodology
A spread of perspectives from cocoa procurement managers, halal certification auditors, retail category buyers at Gulf mall operators, and SFDA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against customs records, Nielsen retail audit data, and food safety authority filing databases. Bottom-up volume modeling across product types and distribution channels triangulated with top-down macroeconomic indicators.
Segmentation dimensions modeled span product type, end user, form, and distribution channel across the analysis window. CAGRs were derived from growth rate convergence analysis applied to historical consumption patterns and projected regulatory enforcement trajectories. Forecast inputs incorporated cocoa butter price volatility assumptions and halal certification adoption curves specific to Gulf Cooperation Council states.
Material uncertainties — cadmium threshold enforcement intensity in South Africa, Egyptian regulatory harmonization pace, and West African cooperative traceability network reconstruction success — sit outside the modeled envelope. Forecasts reflect documented assumptions about these variables. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Bangladesh Candy Market
Confectionery
Chocolate Inclusions and Decorations Market
Confectionery
North America Sugar Confectionery Market
Confectionery
North America Chocolate Market
Confectionery
Low-Fat Sweets Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Ruby Chocolate Market
Confectionery
Crunchy Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Real and Compound Chocolate Market
Confectionery
Mooncake Market
Confectionery
South America Chocolate Market
Confectionery
United States Chocolate Market
Confectionery
North America Marshmallow Market
Confectionery
Chocolate Couverture Market
Confectionery
United States Caramel Chocolate Market