
 Middle-East and Africa Compound Chocolate Market | 2026-2036
Middle-East and Africa Compound Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Compound Chocolate Market Foresight
Asset-light leasing arrangements for cocoa butter equivalent processing lines is reconfiguring competitive entry barriers across the Middle-East and Africa. Barry Callebaut leverages its regional grinding infrastructure to supply industrial bakeries with consistent couverture alternatives. Cargill, Incorporated anchors West African procurement networks through direct sourcing partnerships with Ghanaian and Ivorian processors. Mars Incorporated competes via brand recognition in the premium snacking segment, channeling compound formulations into its regional confectionery portfolio.
Compound chocolate substitutes cocoa butter with vegetable fats such as palm kernel oil or shea butter, achieving melting profiles between 34°C and 38°C while reducing raw material costs by roughly half compared to true chocolate. Manufacturers deploy it primarily for coating biscuits, molding bars, and enrobing confectionery where precise tempering is secondary to cost stability. Milk compound leads volume across the Middle-East and Africa due to its mild flavor alignment with regional palates and widespread use in bakery applications. Dark compound occupies the fastest-expanding niche as health-conscious formulations gain traction in Gulf state retail channels. White compound sustains steady demand from ice cream and dessert manufacturers seeking neutral base colors for flavor layering.
Saudi Arabia's SFDA enforces strict vegetable fat labeling requirements that compel manufacturers to distinguish compound chocolate from chocolate proper on packaging. South Africa's Department of Health applies Codex-aligned standards through the National Regulator for Compulsory Specifications, governing melting point thresholds and fat composition ratios. The UAE's Ministry of Industry and Advanced Technology coordinates with Gulf Standardization Organization protocols for imported confectionery inputs. Stakeholders must monitor evolving halal certification requirements for emulsifiers and flavor additives as Gulf markets tighten supply chain traceability demands.
Market Dynamics
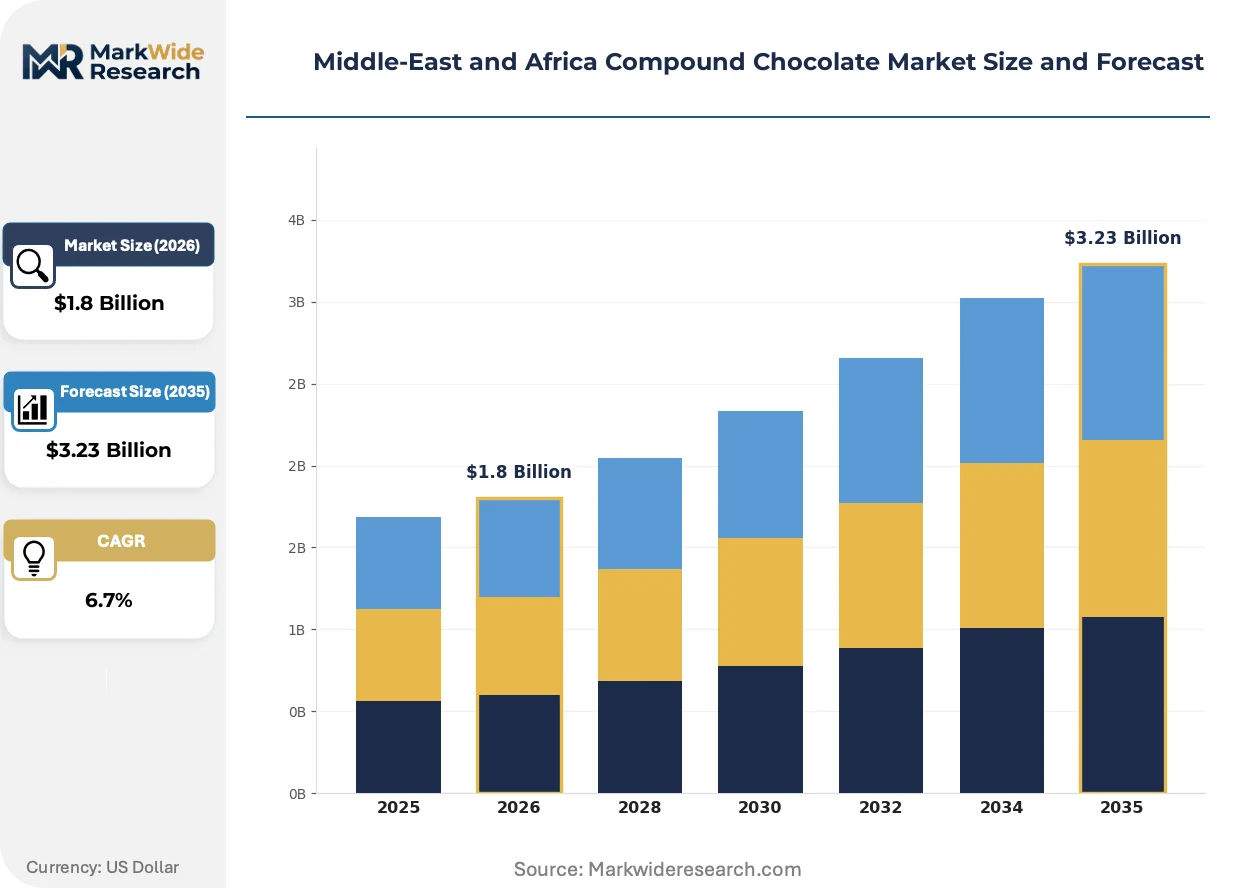
Asset-light leasing of cocoa butter equivalent processing lines is compressing capital barriers for new entrants across the Middle-East and Africa, while Saudi Arabia's SFDA labeling mandates force rapid packaging reformulation across regional portfolios.
Growth Catalysts
- SFDA Mandate Enforcement:Saudi Arabia's tightened vegetable fat disclosure rules compel manufacturers to reformulate and relabel, accelerating demand for compliant compound chocolate formulations in Gulf markets.
- Urban Bakery Expansion:Nigerian and Egyptian industrial bakeries are scaling procurement for croissants, cakes, and patisserie, pulling volume through regional distribution networks.
- Shea Butter Sourcing:West African processors are commercializing local shea butter as a cocoa butter equivalent, shortening supply chains and reducing import dependency for regional manufacturers.
Market Restraints
- Palm Kernel Oil Volatility:Malaysian and Indonesian export policy fluctuations create input cost instability for manufacturers dependent on Southeast Asian vegetable fat supplies.
- Grinding Infrastructure Concentration:Côte d'Ivoire and Ghana control the majority of regional cocoa processing capacity, creating geographic supply risk for compound chocolate producers.
- True Chocolate Substitution Threat:Premium positioning by bean-to-bar artisans in South African and UAE retail channels limits compound chocolate penetration in gift and specialty segments.
Strategic Opportunities
- Halal Certification Integration:Gulf Standardization Organization protocols for emulsifier traceability create first-mover advantage for manufacturers building certified supply chains from origin.
- Dark Compound Health Positioning:Reduced-sugar, high-cocoa formulations are capturing shelf space in UAE and Saudi retail as wellness-oriented snacking expands.
- Direct-to-Industrial Digital Platforms:B2B e-procurement channels are emerging for Egyptian and Moroccan bakeries, bypassing traditional distributor markups.
Industry Challenges
- Tempering Technician Scarcity:Industrial bakeries across Nigeria and Kenya face shortages of skilled operators capable of managing compound chocolate viscosity in high-throughput coating lines.
- Multi-Jurisdiction Labeling Complexity:Manufacturers must maintain parallel packaging variants to satisfy divergent South African NRCS, Saudi SFDA, and UAE MOIAT requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Compound Chocolate Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Compound, Milk Compound, White Compound, Ruby Compound End User: Bakeries, Confectioneries, Snacks Manufacturers, Food Service Distribution Channel: Modern Trade, Online Retail, Specialty Stores, Traditional Retail Application: Baking, Coating, Confectionery, Filling |
| Companies Covered | Puratos, Ferrero International SA, Barry Callebaut, Kerry Group, Cargill, Incorporated, Mondelez International, Mars Incorporated, Bühler Holding AG, Fuji Oil Holdings Inc, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Compound Chocolate Market Shifts & Advancements
Processing technology and regulatory alignment are converging to reshape competitive positioning across Middle-East and Africa compound chocolate manufacturing, with sustainability verification and digital procurement emerging as decisive differentiators.
Enzymatic interesterification of palm kernel and shea fractions is rendering obsolete traditional hydrogenation for melting point control in compound chocolate production. Industrial bakeries in Egypt and Morocco are adopting these enzymatic lines at accelerated replacement cycles. The technology is compressing capital recovery timelines while eliminating trans-fat labeling liabilities across Gulf export markets.
Saudi Arabia's SFDA has mandated blockchain-traceable halal certification for emulsifiers and flavor additives entering the kingdom. This regulatory pivot forces regional manufacturers to requalify entire supplier bases or risk customs detention. UAE-based confectionery exporters are responding by pre-certifying production batches through accredited Gulf laboratories.
Consolidated procurement by pan-African bakery chains is compressing supplier negotiation cycles and demanding just-in-time delivery guarantees. Traditional distributor networks in Nigeria and Kenya are losing share to direct manufacturer relationships with industrial end-users. This channel restructuring is most visible in Lagos and Nairobi, where multinational quick-service bakery brands are centralizing ingredient sourcing at headquarters level.
Middle-East and Africa Compound Chocolate Market Segmentation
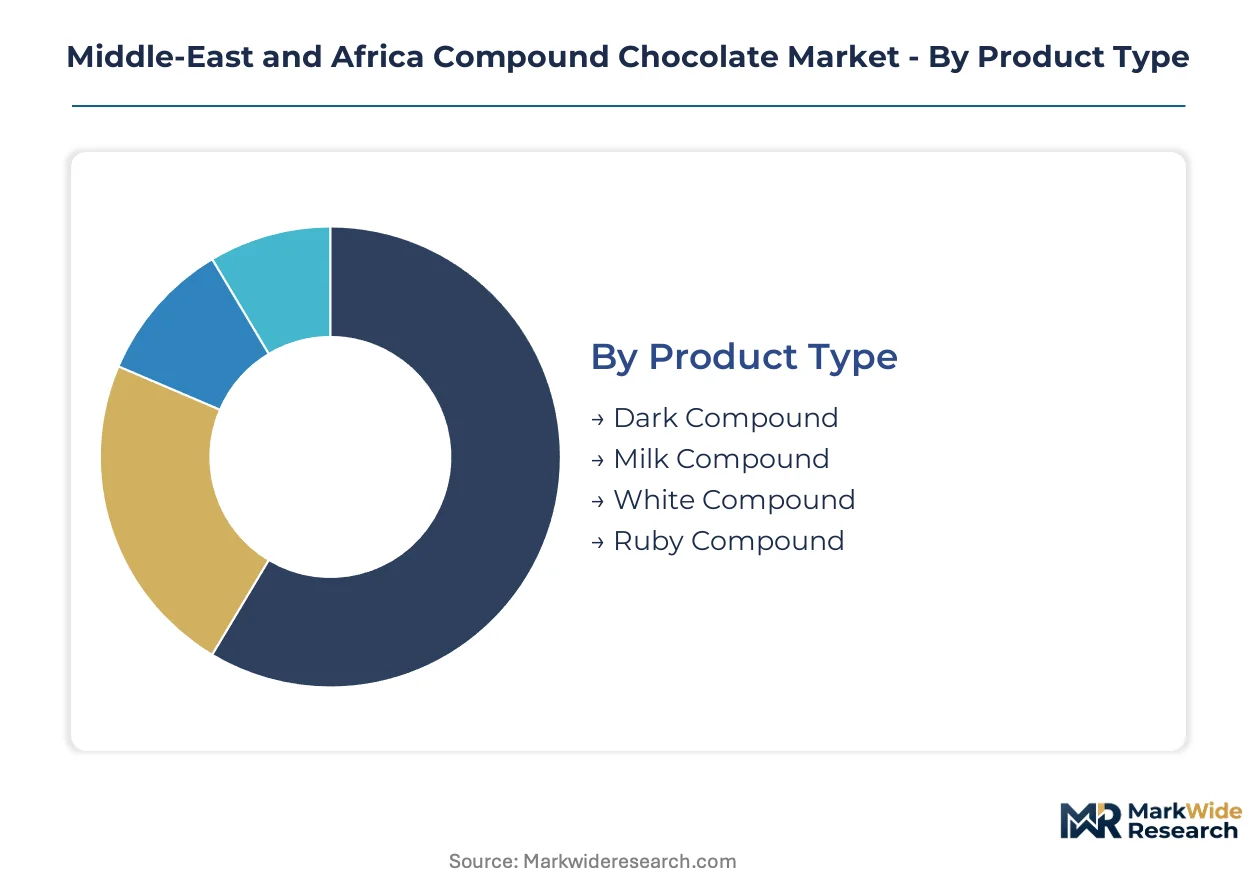
Compound chocolate formulations across the Middle-East and Africa exhibit distinct performance profiles across product chemistry, end-use thermal requirements, and channel logistics. Manufacturers configure production lines around these segment boundaries to optimize melting point control and fat stability for regional climate conditions.
Product Type:
The use-case spectrum spans from high-temperature stability coatings to delicate flavor-base applications requiring precise viscosity management.
- Milk Compound:Formulated with milk solids and vegetable fat blends achieving 34°C to 36°C melting profiles, this segment dominates procurement by Nigerian and Egyptian industrial bakeries producing croissants and layered pastries. Regional palates favor its mild sweetness profile, anchoring volume in mass-market bakery applications where cost stability outweighs cocoa intensity.
- Dark Compound:Higher cocoa powder content (typically 15-25%) delivers bitter notes and antioxidant positioning for wellness-oriented Gulf retail channels. UAE and Saudi Arabian health-conscious snacking segments are pulling this formulation fastest as reduced-sugar variants gain shelf space in premium convenience stores.
- White Compound:Cocoa butter-free composition relies on milk solids and deodorized vegetable fats for neutral color bases, serving ice cream manufacturers and dessert decorators seeking flavor layering flexibility without cocoa interference.
- Ruby Compound:Pink-hued formulation utilizing specific cocoa bean processing retains berry notes without artificial coloring, targeting gift confectionery and premium bakery decoration segments in South African and UAE urban markets.
The dominant share belongs to Milk Compound, while Dark Compound is closing the gap fastest.
End User:
Customer scale and technical capability create divergent procurement patterns across the value chain.
- Bakeries:Industrial-scale operators in Lagos and Cairo demand consistent viscosity for automated enrobing lines, with procurement centralized at headquarters level for pan-African chains. Temperature-controlled logistics requirements shape supplier selection.
- Confectioneries:Bar molding and praline specialists require precise tempering tolerance in compound formulations, with Gulf manufacturers prioritizing SFDA-compliant labeling for export eligibility.
- Snacks Manufacturers:Biscuit coating and cereal inclusion applications prioritize fat bloom resistance and snap characteristics for hot-climate distribution.
- Food Service:Hotel and restaurant dessert kitchens favor portion-controlled formats with extended holding stability for buffet and plating applications.
Bakeries command the largest volume allocation, though Snacks Manufacturers are expanding procurement most aggressively.
Distribution Channel:
Channel structure reflects the tension between traceability mandates and cost minimization for price-sensitive segments.
- Modern Trade:Hypermarket and supermarket chains in Saudi Arabia and UAE enforce supplier certification requirements including halal emulsifier documentation, consolidating procurement around accredited distributors.
- Traditional Retail:Open-market and independent grocer networks across Nigeria and Kenya rely on cash-based transactions with limited cold-chain integrity, favoring shelf-stable compound formulations.
- Online Retail:B2B platforms are emerging for Egyptian and Moroccan bakery procurement, though penetration remains constrained by payment infrastructure and delivery reliability.
- Specialty Stores:Professional bakery supply outlets in Johannesburg and Dubai stock technical-grade compounds with viscosity specifications for artisan chocolatiers.
Modern Trade captures the value concentration, yet Traditional Retail still handles the physical volume majority.
Application:
Processing temperature and shear requirements segment demand by equipment compatibility and finished product aesthetics.
- Coating:Thin-film enrobing for biscuits and ice cream bars demands precise viscosity control across 40°C to 45°C application temperatures, with shea butter-based formulations gaining traction for local sourcing alignment.
- Confectionery:Bar molding and praline shell applications require snap and gloss performance comparable to true chocolate, driving enzymatic interesterification adoption for trans-fat elimination.
- Baking:Chip and chunk inclusions for cookies and muffins prioritize fat stability through oven exposure, with milk compound variants preferred for Maillard reaction compatibility.
- Filling:Cream and ganache centers for pastries and boxed chocolates require pumpable viscosity at ambient temperatures, with white compound serving as neutral bases for flavor customization.
Coating applications anchor volume demand, while Confectionery is climbing the fastest as premium positioning expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakeries and confectionery manufacturers across the Middle-East and Africa concentrate procurement decisions in Riyadh, Lagos, and Dubai, where headquarters-level sourcing teams negotiate volume contracts with compound chocolate suppliers.
Saudi Arabia
Pan-Arabian bakery chains headquartered in Riyadh and Jeddah drive bulk procurement for croissant and pastry applications. The SFDA enforces strict vegetable fat labeling requirements that distinguish compound chocolate from true chocolate on all packaging. Eastern Province industrial zones host coating line installations serving regional biscuit manufacturers.
United Arab Emirates
Dubai's hotel and food service sector demands premium compound formulations for dessert plating and buffet applications. The Ministry of Industry and Advanced Technology coordinates with Gulf Standardization Organization protocols for imported confectionery inputs. Jebel Ali free zone concentration supports re-export logistics to African markets.
Nigeria
Lagos-based industrial bakeries scale procurement for mass-market bread and snack applications as urban consumption rises. The National Agency for Food and Drug Administration and Control governs food additive approvals for vegetable fat-based coatings. Kano and Onitsha manufacturing clusters expand local snack production capacity.
South Africa
Johannesburg and Cape Town confectionery specialists require precise tempering tolerance for praline and molded bar applications. The Department of Health applies Codex-aligned standards through the National Regulator for Compulsory Specifications governing melting point thresholds. Gauteng province hosts technical-grade compound distribution for artisan chocolatiers.
Egypt
Cairo industrial bakeries deploy milk compound variants for traditional pastry and biscuit applications at scale. The Egyptian Organization for Standardization and Quality regulates fat composition ratios in chocolate analogs. Alexandria port infrastructure facilitates shea butter imports from West African origins.
Middle-East and Africa Compound Chocolate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Regional grinding infrastructure concentrates in Côte d'Ivoire and Ghana, while Gulf-based distributors capture margin through certification and logistics services. Three archetypes dominate: cocoa processors with backward integration into West African origins, European-headquartered ingredient suppliers with regional compounding facilities, and local distributors with halal certification capabilities. Competitive moves center on direct sourcing partnerships with Ghanaian and Ivorian processors, and rapid packaging reformulation to satisfy divergent national labeling mandates.
Among European-headquartered ingredient specialists, Puratos and Barry Callebaut occupy positions anchored by regional grinding infrastructure and industrial bakery supply relationships. Cargill, Incorporated exemplifies the processor archetype with West African procurement networks. These three represent distinct competitive vectors: Puratos through bakery-focused formulation expertise, Barry Callebaut through couverture alternative consistency, and Cargill through direct origin sourcing control.
| Leading Market Players |
|---|
| Puratos |
| Ferrero International SA |
| Barry Callebaut |
| Kerry Group |
| Cargill, Incorporated |
| Mondelez International |
| Mars Incorporated |
| Bühler Holding AG |
| Fuji Oil Holdings Inc |
| Others |
Supply & Pricing Matrix
West African grinding infrastructure in Côte d'Ivoire and Ghana concentrates cocoa butter equivalent supply, anchoring margin capture with Gulf-based distributors who layer certification and logistics premiums onto base material costs. This upstream consolidation forces compound chocolate manufacturers to absorb volatility or push price adjustments through to Nigerian and Egyptian industrial bakeries.
Pricing Analysis
Halal certification grade creates the primary spread between Gulf-exportable formulations and domestic-grade alternatives, with SFDA-compliant labeling commanding substantial premia over standard variants. Three-tier pricing structure across premium certified, standard industrial, and economy bulk tiers reflects this certification hierarchy. Pricing pressure stems from Malaysian palm kernel oil export policy fluctuations, which compress margins for non-integrated processors. Pan-African bakery chains exhibit highest price sensitivity due to centralized procurement leverage, while Dubai hotel food service shows lowest sensitivity given premium positioning requirements.
Supply Chain Analysis
Malaysian and Indonesian export licensing regimes for refined palm oil derivatives constrain raw material flows into Middle-East and Africa compound chocolate production. Supply concentrates in Côte d'Ivoire and Ghana for cocoa processing, Malaysia and Indonesia for palm kernel oil fractions, and Nigeria for shea butter commercialization. Raw material dependencies span vegetable fat blends, milk solids powders, and emulsifier packages. Single-source vulnerability runs through Southeast Asian palm oil supply channels, where policy shifts disrupt input availability without short-term alternatives. Distribution runs through Jebel Ali free zone consolidation for Gulf markets and Lagos port clearance for West African industrial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound chocolate demand cycles with Gulf construction and hospitality investment waves, with the current upswing tied to Saudi Vision 2030 food service expansion and Nigerian urban bakery modernization.
For Market Incumbents: Insulate margin structures through backward integration into Ghanaian and Ivorian grinding assets, capturing cocoa butter equivalent supply before distributor markups accumulate. Prioritize rapid packaging reformulation capabilities to satisfy divergent SFDA, NRCS, and MOIAT labeling mandates without parallel inventory strains. Lock in multi-year offtake agreements with Nigerian industrial bakeries before asset-light leasing arrangements democratize competitor processing access. For New Entrants and Emerging Players: Pursue enzymatic interesterification technology deployment for trans-fat-free compound formulations, targeting Egyptian and Moroccan bakeries facing Gulf export compliance requirements. White space concentrates in direct-to-industrial digital procurement platforms bypassing traditional Lagos and Nairobi distributor networks. Entry through halal-certified emulsifier supply partnerships offers lowest friction path to Saudi market access. For Investors and Strategic Acquirers: Capital is best deployed toward regional grinding infrastructure with backward integration into West African origins, capturing structural margin pools currently harvested by European-headquartered intermediaries. Long-term viability hinges on sustainability verification capabilities and blockchain-traceable certification infrastructure. The signal to watch is SFDA enforcement intensity on emulsifier documentation, which would accelerate supplier base consolidation and reward pre-qualified asset owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Grinding | Cocoa butter equivalent supply control eliminates distributor margin extraction for Gulf manufacturers. |
| Halal Certification Infrastructure Investment | SFDA blockchain-traceable requirements create compliance moats for early-mover regional producers. |
| Enzymatic Interesterification Technology Deployment | Trans-fat elimination aligns with Gulf health labeling trends while compressing capital recovery timelines. |
| Direct-to-Industrial Digital Platform Launch | B2B e-procurement bypasses traditional Lagos and Nairobi distributor markups for Egyptian bakery chains. |
| Shea Butter Commercialization Partnerships | West African origin sourcing shortens supply chains and reduces Malaysian palm oil dependency for regional formulators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with compound chocolate procurement managers at Nigerian and Egyptian industrial bakeries, Gulf-based distributor certification specialists, and West African grinding facility technical directors providing operational perspective. Secondary validation drew from SFDA regulatory filings, Ghana Cocoa Board export statistics, UAE Ministry of Industry import clearance records, and Codex Alimentarius fat composition standards. Bottom-up volume modeling across bakery, confectionery, and snack manufacturing end uses triangulated with top-down macroeconomic consumption projections.
Calibration anchored historical volume trajectories against grinding capacity utilization rates and vegetable fat price series across the analysis window. Segmentation dimensions spanned product chemistry tier, thermal stability requirements, end-use equipment compatibility, and regional regulatory cluster. CAGRs derived from slope analysis of fitted trend lines, with cross-validation against industrial bakery expansion pipelines and hotel food service investment cycles in Saudi Arabia and UAE.
Macroeconomic conditions sit as an overlay; deviation in Gulf hospitality construction spend or Nigerian naira exchange rate stability would shift the trajectory. Forecasts reflect documented assumptions on SFDA enforcement continuity and Malaysian palm oil export policy. Material shifts in shea butter commercialization scale or enzymatic processing technology adoption curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Canada Chocolate Market
Confectionery
Low Calorie Hard Candy Market
Confectionery
Low-Calorie Chocolate Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Fruit Jellies Market
Confectionery
Europe Confectionery Market
Confectionery
Carob Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
United States and Europe Macarons Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Global Confectionery Market
Confectionery
Global Mochi Market
Confectionery
Low-Fat Sweets Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Low Calorie Sweets Market