
 Global Coronary Stent Market | 2026-2036
Global Coronary Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coronary Stent Market Analysis
Software-defined stent performance monitoring is hardening as a recurring revenue layer that manufacturers bundle with device contracts. Abbott leverages its cardiac rhythm management infrastructure to anchor subscription-based patient monitoring services. Medtronic sustains R&D intensity across drug-eluting polymer platforms. Boston Scientific Corporation competes through geographic dominance in European interventional cardiology centers.
A coronary stent is a tubular mesh scaffold, typically fabricated from cobalt-chromium, platinum-iridium, or polymeric matrices, that is deployed via catheter-based delivery to restore and maintain arterial lumen patency following percutaneous coronary intervention. Drug-eluting stents command the largest revenue pool through antiproliferative agent coatings that reduce restenosis rates. Bioresorbable stents represent the fastest-growing product category as magnesium and poly-L-lactic acid formulations advance through clinical validation. Bare-metal stents retain utility in specific patient populations where dual antiplatelet therapy poses contraindications.
FDA premarket approval pathways, EMA Medical Device Regulation conformity assessments, and Japan's PMDA stent-specific guidance shape market access timelines and clinical evidence requirements across major jurisdictions. The EU MDR transition has extended notified body review cycles, compressing launch windows for novel platforms. Stakeholders must monitor reimbursement parity between bioresorbable and metallic platforms as health technology assessment bodies refine value frameworks.
Market Dynamics
Bioresorbable scaffold technology is forcing a recalibration of clinical evidence requirements and manufacturing scale-up timelines across coronary stent portfolios. The transition from permanent metallic implants to magnesium and poly-L-lactic acid platforms demands new polymer processing capabilities and extended follow-up protocols.
Growth Catalysts
- Drug-eluting polymer refinements:Third-generation limus-analog coatings demonstrate superior endothelialization profiles in complex lesion subsets. Cardiac catheterization laboratories in Germany and Japan are prioritizing these platforms for diabetic patient cohorts.
- FDA breakthrough device designation pathways:Expedited review timelines for bioresorbable stents compress development-to-commercialization cycles. Manufacturers are restructuring clinical trial designs to align with premarket approval efficiency incentives.
- Interventional cardiology center expansion:Ambulatory surgical centers in the United States are adding PCI capabilities. This facility type is absorbing volume from traditional hospital-based catheterization laboratories.
Market Restraints
- Platinum-iridium alloy supply concentration:Primary refining operations cluster in South African and Russian mining jurisdictions. Geopolitical friction elevates raw material cost volatility for high-performance stent platforms.
- EU MDR notified body capacity constraints:Extended conformity assessment timelines delay European market entry for novel bioresorbable devices. Manufacturers face compressed revenue windows relative to prior CE marking cycles.
- Dual antiplatelet therapy duration requirements:Extended DAPT protocols following drug-eluting stent implantation create bleeding risk management burdens. Bare-metal stent alternatives retain niche utility in surgical candidates requiring shorter anticoagulation windows.
Strategic Opportunities
- India's underserved interventional infrastructure:Coronary artery disease prevalence outpaces PCI penetration rates in tier-2 and tier-3 cities. CDSCO regulatory harmonization initiatives are streamlining import substitution pathways for domestic manufacturing.
- Software-defined performance monitoring:Real-time stent patency tracking via implantable sensor integration creates recurring revenue attach rates. Abbott's cardiac rhythm management infrastructure demonstrates service bundling feasibility.
- Japan PMDA stent-specific guidance alignment:Accelerated approval frameworks for bioabsorbable scaffolds reward localized clinical development. Domestic trial data requirements favor partnerships with Japanese academic medical centers.
Industry Challenges
- Polymer processing specialist scarcity:Bioresorbable stent manufacturing demands precision extrusion and controlled degradation expertise. Talent competition with pharmaceutical packaging and orthopedic implant sectors elevates compensation costs.
- Legacy electronic health record integration:Post-market surveillance data capture requires API development across heterogeneous hospital IT systems. Device registries face incomplete longitudinal follow-up due to interoperability friction.
- Clinical evidence generation capex intensity:Five-year follow-up requirements for bioresorbable platforms demand sustained trial infrastructure investment. Smaller manufacturers face capital access constraints relative to diversified cardiovascular portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coronary Stent Market |
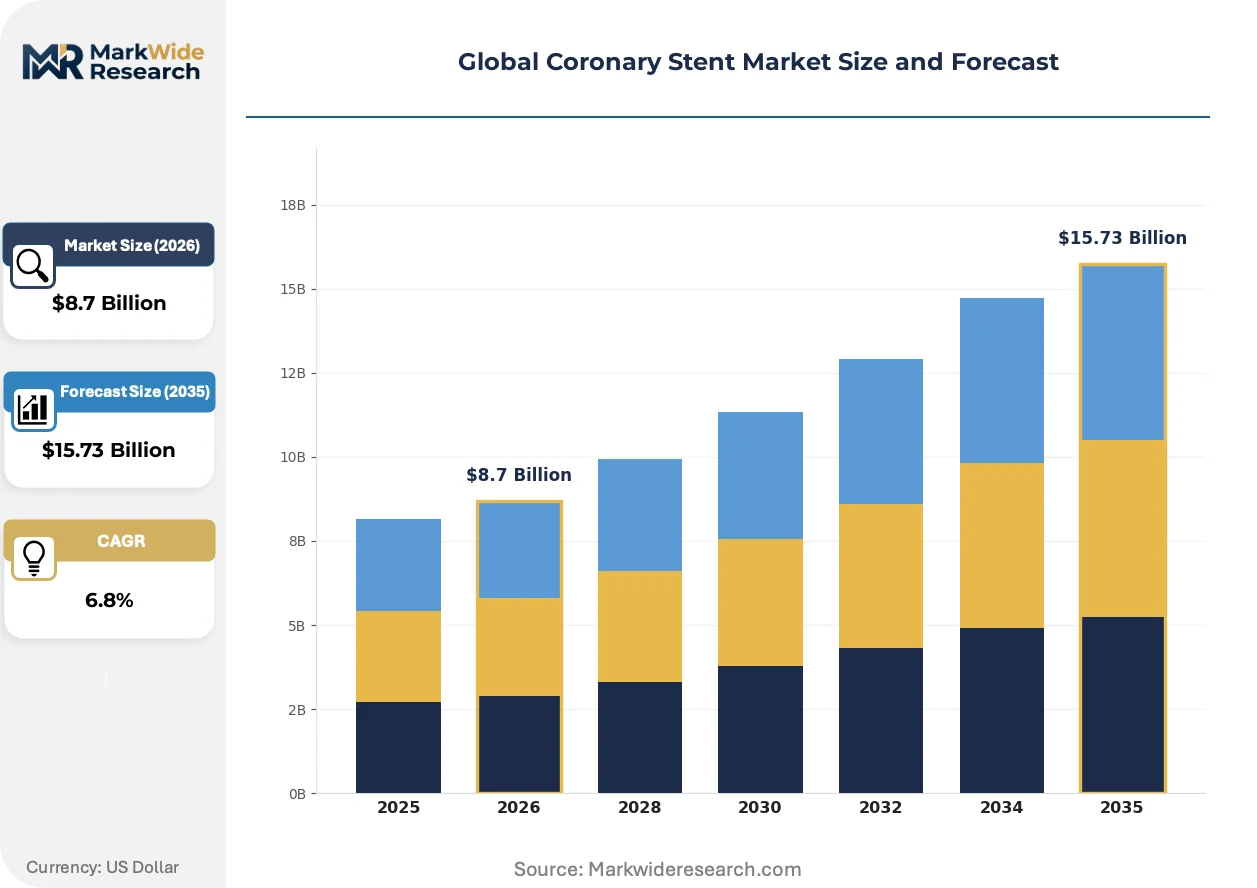
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug-Eluting Stents, Bare-Metal Stents, Bioresorbable Stents, Self-Expanding Stents Delivery Mode: Transluminal, Intracoronary, Endovenous, Surgical Application: Coronary Artery Disease, Angioplasty, Vascular Surgery, Peripheral Vascular Disease End User: Hospitals, Ambulatory Surgical Centers, Cardiac Clinics, Research Institutions |
| Companies Covered | Abbott, Boston Scientific Corporation, Medtronic, Terumo Corporation, B. Braun Melsungen AG, Biotronik SE & Co. KG, MicroPort Scientific Corporation, Cook Medical, Stentys S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coronary Stent Market Emerging Trajectories
Coronary stent architecture is fragmenting into application-specific platforms rather than universal lesion solutions. Manufacturers are optimizing deliverability, radial strength, and drug kinetics for distinct anatomical challenges.
Magnesium-based bioresorbable scaffolds is modularizing coronary stent product development into discrete functional components. Cardiac clinics in Germany and Japan are piloting these platforms for simple de novo lesions ahead of complex indication expansion. The technology is modularizing supply chain relationships between alloy processors, coating specialists, and finished device assemblers into interchangeable partnerships rather than captive vertical structures.
EU MDR Article 117 clinical evidence requirements are elevating post-market clinical follow-up obligations for legacy drug-eluting stent platforms. Manufacturers must generate real-world performance data or face certificate suspension. High-volume stent programs in Italian and Spanish interventional centers are restructuring registry participation to satisfy notified body expectations.
Hospital procurement committees are consolidating vendor relationships around full cardiovascular portfolio breadth rather than discrete stent line negotiations. Integrated delivery networks in the United States are awarding sole-source contracts spanning coronary, peripheral, and structural heart devices. This concentration is most visible in Texas and Florida health systems where physician employment models align purchasing authority with administrative decision-making.
Global Coronary Stent Market Segmentation
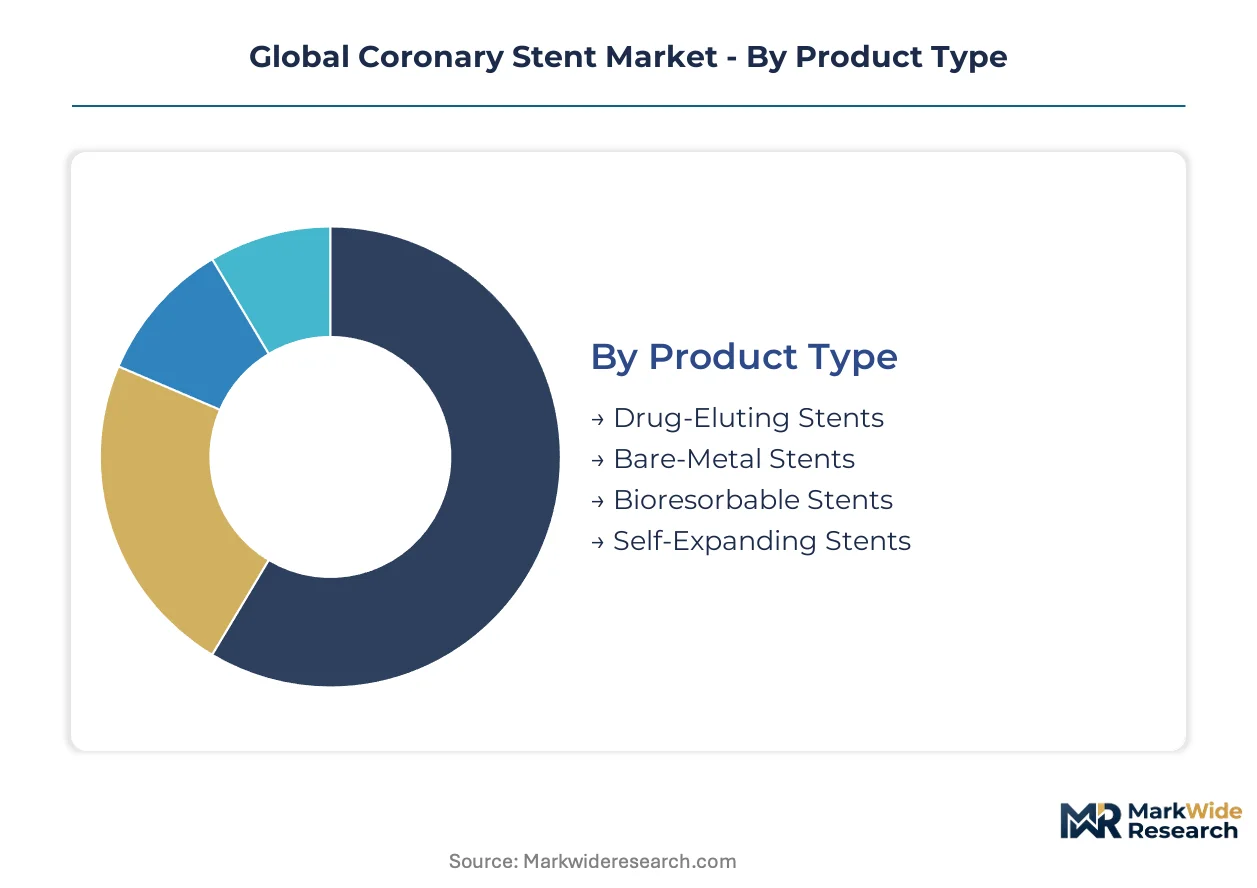
Coronary stent purchasing decisions fragment across clinical workflow requirements, lesion complexity profiles, and facility reimbursement structures. Manufacturers configure product portfolios around these intersecting demands rather than universal device platforms.
Product Type:
Capital intensity varies sharply across stent platforms, with polymer coating infrastructure and bioresorbable manufacturing lines demanding the heaviest upfront investment.
- Drug-Eluting Stents:Cobalt-chromium scaffolds carry antiproliferative limus-analog coatings that suppress neointimal hyperplasia. German and Japanese cardiac catheterization laboratories prioritize these platforms for diabetic patient cohorts with complex lesion anatomy.
- Bioresorbable Stents:Magnesium and poly-L-lactic acid formulations degrade completely after arterial remodeling. FDA breakthrough device designation pathways compress development timelines for manufacturers with polymer processing capabilities.
- Bare-Metal Stents:Platinum-iridium alloys serve surgical candidates requiring shorter dual antiplatelet therapy windows.
- Self-Expanding Stents:Nitinol superelasticity accommodates vessel tapering in peripheral anatomies.
Drug-eluting stents absorb the bulk of installed capacity; bioresorbable stents are expanding most quickly.
Delivery Mode:
Procedure volume distribution across delivery modalities reflects the geographic concentration of interventional cardiology training programs.
- Transluminal:Percutaneous femoral or radial access dominates elective PCI workflows in United States ambulatory surgical centers.
- Intracoronary:Direct coronary ostium engagement enables precise scaffold positioning in left main bifurcation cases.
- Endovenous:Venous delivery corridors support hybrid coronary-saphenous interventions.
- Surgical:Open sternotomy access reserves stent deployment for concomitant CABG procedures.
Transluminal delivery handles the majority of annual procedures; intracoronary techniques are gaining share in complex lesion subsets.
Application:
Reimbursement parity between coronary and peripheral indications shapes manufacturer portfolio prioritization decisions.
- Coronary Artery Disease:Atherosclerotic plaque burden in epicardial vessels generates the core revenue base for stent manufacturers.
- Angioplasty:Balloon predilation requirements influence stent sizing and delivery system compliance specifications.
- Vascular Surgery:Hybrid operating rooms in Texas and Florida health systems combine surgical access with catheter-based deployment.
- Peripheral Vascular Disease:Femoropopliteal and infrapopliteal lesions command specialized scaffold flexibility and fracture resistance.
Coronary artery disease applications anchor manufacturer revenue; peripheral vascular disease is climbing the fastest as limb salvage protocols expand.
End User:
Procurement authority concentration varies by facility type, with integrated delivery networks consolidating vendor relationships differently than independent cardiac clinics.
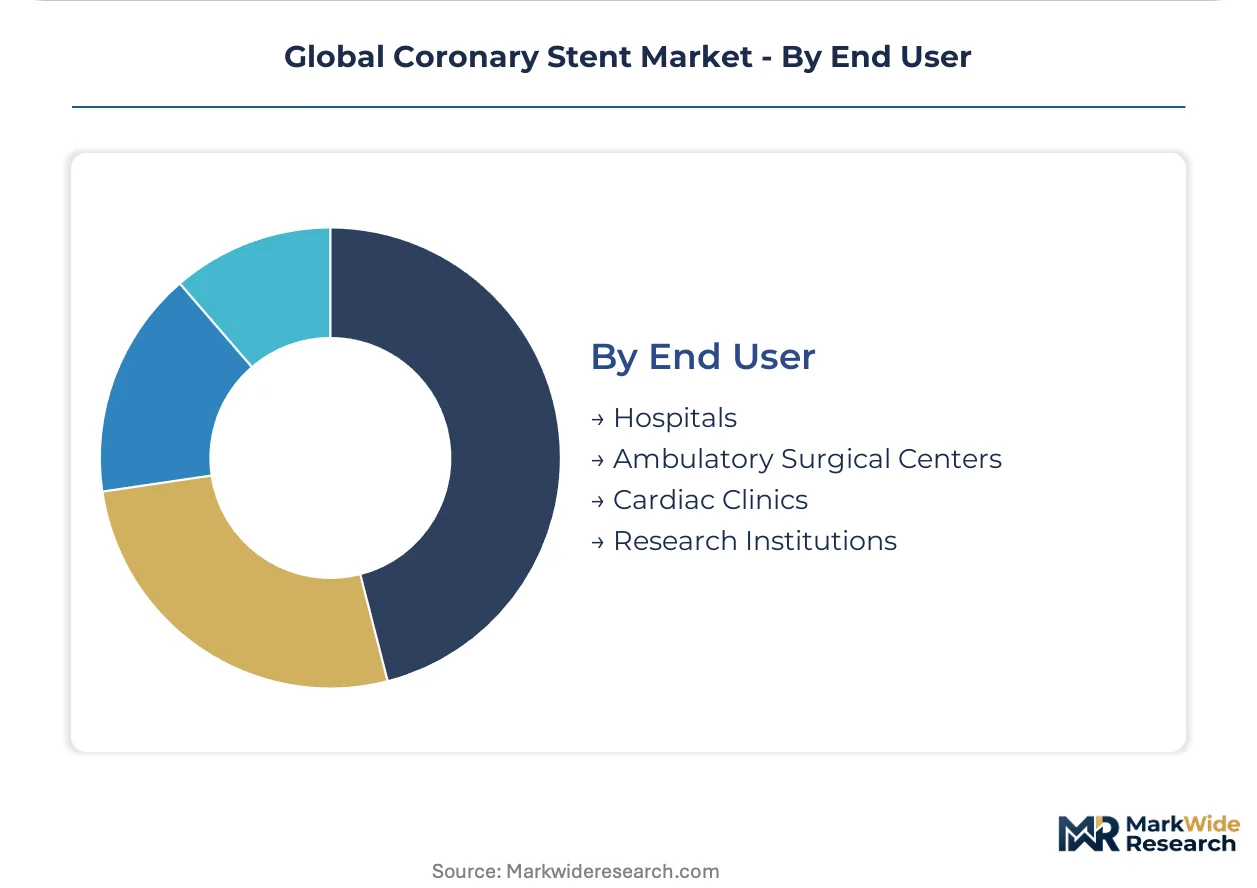
- Hospitals:Traditional catheterization laboratories in Germany and Japan maintain comprehensive device inventories across all stent platforms.
- Ambulatory Surgical Centers:United States freestanding PCI facilities prioritize rapid inventory turnover and standardized device protocols.
- Cardiac Clinics:Specialist interventional practices in tier-2 Indian cities are expanding PCI capabilities ahead of infrastructure maturation.
- Research Institutions:Academic medical centers in Japan generate the localized clinical data required for PMDA accelerated approval frameworks.
Hospitals retain the largest installed base of interventional infrastructure; ambulatory surgical centers are scaling fastest as United States reimbursement shifts toward site-neutral payment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American interventional cardiology infrastructure through Abbott's cardiac rhythm management headquarters and Medtronic's operational base, concentrating device development, clinical training, and procurement decision-making in this single metropolitan corridor.
United States
Ambulatory surgical centers in Texas and Florida health systems are absorbing PCI volume from traditional hospital laboratories as site-neutral reimbursement expands. FDA breakthrough device designation pathways compress premarket approval timelines for bioresorbable platforms. The Minneapolis-Saint Paul corridor concentrates manufacturer headquarters and interventional cardiology training programs.
Germany
Cardiac catheterization laboratories in Munich and Heidelberg prioritize third-generation limus-analog drug-eluting stents for diabetic patient cohorts with complex lesion anatomy. EMA Medical Device Regulation conformity assessments extend notified body review cycles, compressing launch windows. The Baden-Württemberg industrial cluster hosts precision polymer processing capabilities for bioresorbable scaffold manufacturing.
Japan
Academic medical centers in Tokyo and Osaka generate localized clinical data required for PMDA accelerated approval frameworks for bioabsorbable scaffolds. Japan's stent-specific guidance rewards domestic trial infrastructure investment. The Kanto region concentrates interventional cardiology excellence centers and manufacturer partnerships with university hospitals.
India
Coronary artery disease prevalence in tier-2 and tier-3 cities outpaces PCI penetration rates, creating infrastructure expansion opportunities. CDSCO regulatory harmonization initiatives streamline import substitution pathways for domestic manufacturing. Maharashtra and Gujarat industrial corridors are developing catheter-based device assembly capabilities.
Switzerland
Swissmedic maintains stringent conformity assessment protocols for high-performance platinum-iridium alloy stent platforms. The Basel-Zurich corridor concentrates precision metalworking expertise and coating specialist operations. Geneva-based health technology assessment bodies refine value frameworks for bioresorbable versus metallic platform reimbursement parity.
Global Coronary Stent Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the coronary stent landscape, with integrated cardiovascular portfolios sustaining R&D intensity against specialized scaffold developers. The market structure consolidates around diversified medical technology conglomerates with cardiac rhythm management infrastructure, tiered specialist manufacturers with polymer processing capabilities, and regional assemblers serving price-sensitive procurement committees. Dominant competitive moves include strategic partnerships with academic medical centers for localized clinical data generation and backward integration into cobalt-chromium alloy supply chains.
Among diversified cardiovascular conglomerates, Abbott and Medtronic occupy positions anchored by cardiac rhythm management infrastructure that enables subscription-based patient monitoring service bundling. Boston Scientific Corporation exemplifies geographic dominance archetypes through European interventional cardiology center concentration. These three entities represent distinct strategic postures: service integration, R&D intensity, and regional channel control respectively.
| Leading Market Players |
|---|
| Abbott |
| Boston Scientific Corporation |
| Medtronic |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Biotronik SE & Co. KG |
| MicroPort Scientific Corporation |
| Cook Medical |
| Stentys S.A. |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 117 clinical evidence mandates gate qualified supply access and premium-tier pricing power for coronary stent manufacturers, forcing notified body certification investments that stratify market participation. Device makers without polymer processing capabilities face exclusion from bioresorbable scaffold segments where reimbursement parity with metallic platforms remains contested.
Pricing Analysis
Value-based pricing anchors on dual antiplatelet therapy reduction outcomes, with drug-eluting stent premiums justified by restenosis rate differentials in diabetic cohorts. Three-tier pricing structure across premium, standard, and economy levels reflects FDA breakthrough designation status, cobalt-chromium alloy grade, and bundled monitoring service inclusion. Cost compression in bare-metal tiers intensifies because South African platinum-iridium supply friction elevates raw material volatility. Ambulatory surgical centers in the United States exhibit highest price sensitivity, while Japanese academic medical centers prioritize clinical performance over procurement cost.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian platinum-iridium refining jurisdictions, exposing high-performance stent platforms to geopolitical disruption. Precision polymer processing concentrates in Germany, Switzerland, and the United States, with magnesium alloy drawing from specialized European metallurgical suppliers. Supply chain risk centers on EU MDR notified body capacity constraints that extend conformity assessment timelines. Distribution runs through integrated delivery networks in Texas and Florida, hospital procurement committees in Germany and Japan, and emerging cardiac clinics in tier-2 Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer processing specialist scarcity props pricing power for qualified bioresorbable scaffold manufacturers, creating supply-constrained market dynamics that favor incumbents with captive extrusion capabilities.
For Market Incumbents: Anticipate magnesium alloy supply competition from orthopedic implant sectors by securing long-term offtake agreements with European metallurgical suppliers. Backward integration into cobalt-chromium refining buffers against South African mining jurisdiction volatility. Prioritize FDA breakthrough device designation maintenance to preserve premium pricing tiers against emerging polymer platform entrants. For New Entrants and Emerging Players: Begin with India's tier-2 cardiac clinic expansion, where CDSCO regulatory harmonization streamlines import substitution pathways and PCI penetration lags disease prevalence. Target domestic assembly partnerships in Maharashtra and Gujarat industrial corridors to bypass landed cost disadvantages. Lead with bare-metal stent offerings for surgical candidates requiring shorter antiplatelet windows, then migrate toward drug-eluting platforms. For Investors and Strategic Acquirers: FDA breakthrough device designation announcements for magnesium-based bioresorbable scaffolds are the leading indicator that polymer processing capabilities command acquisition premiums. Long-term viability rests on cardiac rhythm management infrastructure enabling subscription-based monitoring service bundling. Target specialized manufacturers with precision extrusion expertise and Japanese PMDA trial partnerships rather than diversified cardiovascular conglomerates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review timelines compress development-to-commercialization cycles for bioresorbable platforms. |
| Polymer Processing Backward Integration | In-house extrusion capabilities reduce dependency on pharmaceutical packaging sector talent competition. |
| Japanese Academic Medical Center Partnership | Localized clinical data generation satisfies PMDA accelerated approval frameworks for bioabsorbable scaffolds. |
| Software-Defined Performance Monitoring | Implantable sensor integration creates recurring revenue attach rates bundled with device contracts. |
| EU MDR Notified Body Certification | Article 117 compliance preserves market access as certificate suspension threatens legacy platforms. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with interventional cardiologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. FDA premarket approval databases, EMA Medical Device Regulation submissions, Japan PMDA stent-specific guidance documents, and CDSCO import registration records provided validation layers. Bottom-up stent shipment triangulation against top-down cardiac catheterization laboratory capacity estimates ensured cross-verification.
Data-stream reconciliation across product type, delivery mode, application, and end user segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs derived from procedure volume elasticity to coronary artery disease prevalence, reimbursement rate trajectories, and interventional cardiology center expansion pipelines. Magnesium alloy supply forecasts and polymer processing capacity buildouts informed bioresorbable scaffold growth assumptions.
Regulatory timeline delays, raw material supply disruptions, and reimbursement parity decisions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about notified body capacity normalization and health technology assessment body value framework evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
South Korea Cardiovascular Devices Market
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Venous Reservoirs Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
LAMEA Cardiac Surgical Devices Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Stent-Assisted Coiling Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Global Coil Wound Devices Market