
 Arterial Blood Sampling Systems Market | 2026-2036
Arterial Blood Sampling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Arterial Blood Sampling Systems Market Analysis
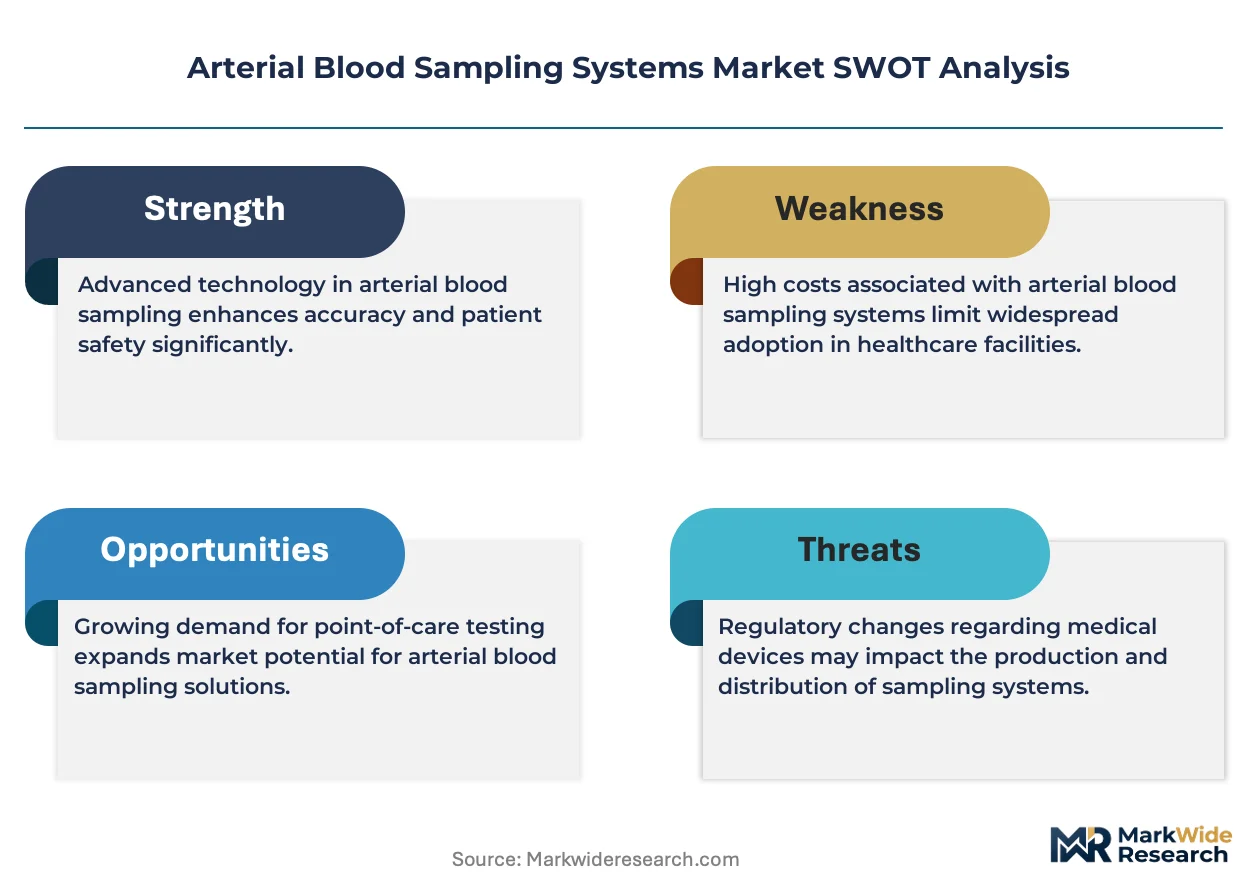
Hospital procurement consortiums is reshaping how arterial blood sampling systems reach end users, shifting volume toward centralized tenders and long-term supply agreements. Abbott Laboratories leverages its diagnostics portfolio to anchor critical care placements in integrated health networks. Siemens Healthineers competes through automation-heavy blood gas platforms that reduce manual sampling errors. Radiometer Medical specializes in point-of-care arterial line solutions that sustain premium positioning in emergency departments.
Arterial blood sampling systems comprise closed-collection devices, syringes, and safety-engineered needles designed to aspirate blood from peripheral or central arterial catheters for gas analysis, pH measurement, and electrolyte profiling. These systems typically integrate self-venting mechanisms and dry lithium heparin anticoagulant coatings to prevent clot formation and air bubble introduction during transfer. Automated systems lead the product type landscape as laboratories prioritize throughput and operator standardization, while safety devices capture expanding margin pools driven by OSHA needlestick regulations. Hospitals dominate end-user demand due to continuous arterial monitoring in ICUs and operating rooms, whereas diagnostic laboratories represent the fastest-growing usage frequency segment as decentralized testing expands.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens Standard govern device safety and clinician protection requirements in the United States, while EMA Medical Device Regulation and EU AI Act increasingly shape automated analyzer software validation across Europe. Japan's PMDA enforces JIS-standard material biocompatibility for silicone and stainless steel components used in repeated-use arterial lines. Stakeholders must monitor evolving harmonization between FDA digital health guidance and EU MDR software classification to anticipate compliance costs for next-generation integrated sampling-to-analysis platforms.
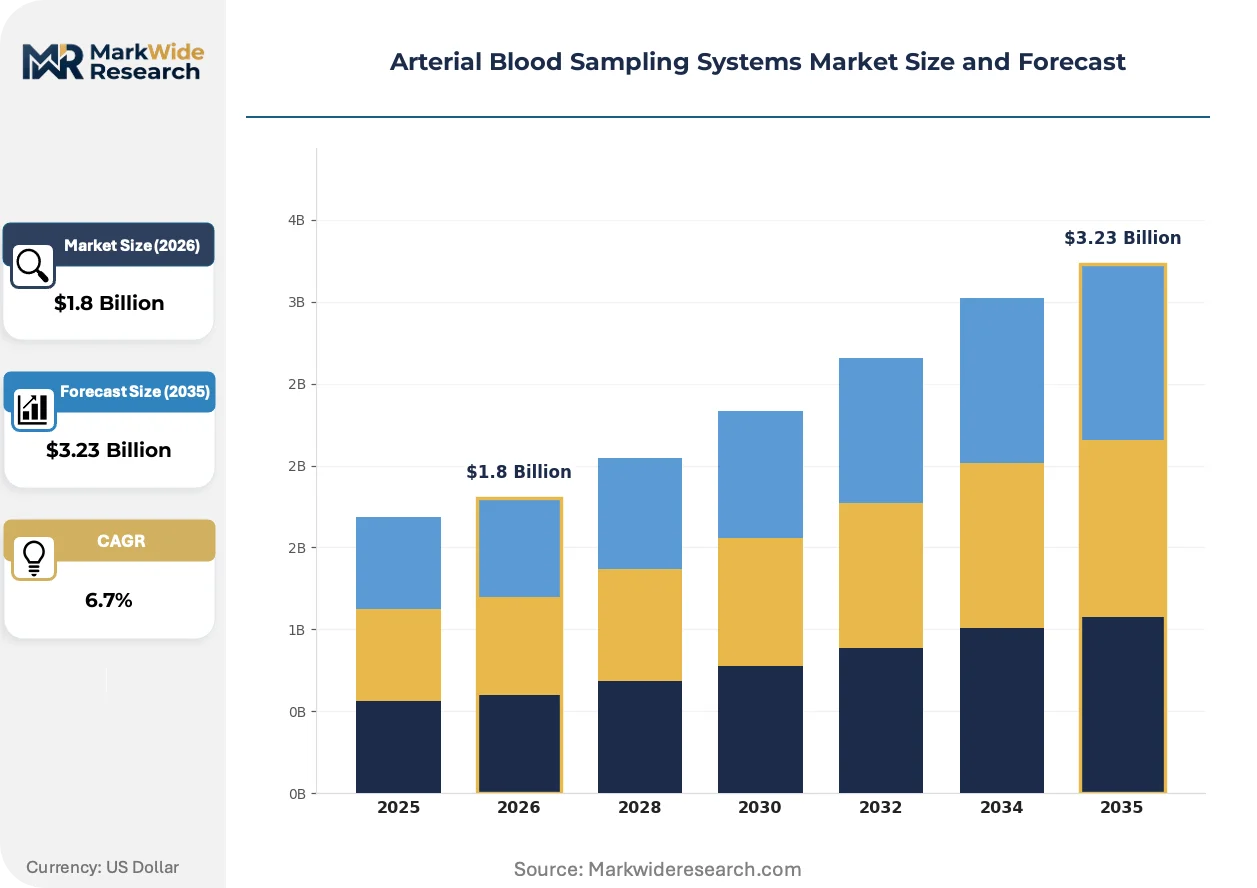
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing arterial blood sampling system vendors to restructure pricing and service models around multi-year enterprise agreements rather than transactional sales.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandatory needlestick prevention requirements in US acute care facilities are accelerating replacement cycles for legacy open-collection devices with safety-engineered alternatives.
- Point-of-care testing expansion:Emergency departments and surgical suites are deploying arterial line-integrated sampling systems to eliminate transport delays and reduce pre-analytical variables in critical care settings.
- Critical care infrastructure buildouts:China, Germany, and the United States are expanding ICU bed capacity and blood gas analyzer installations, creating sustained demand for compatible sampling consumables.
Market Restraints
- Silicone and specialty polymer supply concentration:Medical-grade tubing and catheter materials depend on a limited supplier base concentrated in East Asian manufacturing clusters, exposing device makers to input volatility and qualification delays.
- EU MDR software classification complexity:Automated sampling-to-analysis platforms with embedded algorithms face extended conformity assessment timelines and notified body bottlenecks, compressing product launch windows.
- Capillary microsampling substitution:Minimally invasive finger-stick alternatives for select blood gas and electrolyte panels are displacing arterial puncture in ambulatory and lower-acuity settings.
Strategic Opportunities
- Decentralized diagnostic laboratories:Standalone labs and outpatient surgery centers in the United States and Germany represent underpenetrated volume for closed-collection arterial sampling systems as testing migrates from hospital core labs.
- FDA 510(k) dual submission pathways:Concurrent hardware and software clearance strategies for integrated sampling-analyzer platforms can compress time-to-market versus sequential filings.
- Closed-loop automation convergence:Integration of robotic sample handling with AI-enabled quality control is digitizing pre-analytical workflows and creating premium positioning for vendors with full-stack capabilities.
Industry Challenges
- Specialized clinical engineering talent scarcity:Deployment and validation of automated arterial sampling systems requires hybrid competencies in perfusion technology, laboratory informatics, and point-of-care device management that outpace current training pipeline output.
- Legacy analyzer interoperability friction:Hospital IT environments with heterogeneous blood gas instrument fleets create integration complexity for next-generation sampling systems requiring bidirectional data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arterial Blood Sampling Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Safety Devices, Blood Collection Kits End User: Hospitals, Diagnostic Laboratories, Research Institutions, Blood Banks Usage Frequency: Routine Testing, Emergency Use, Surgical Procedures, Clinical Trials Material: Plastic, Glass, Silicone, Stainless Steel |
| Companies Covered | Abbott Laboratories, Nova Biomedical, Radiometer Medical, OPTI Medical Systems, Medica Corporation, Siemens Healthineers, Instrumentation Laboratory, Techno Medica, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arterial Blood Sampling Systems Market Emerging Trajectories
Arterial blood sampling systems are transitioning from passive consumables to intelligent workflow components, with embedded sensors, automated quality checks, and seamless analyzer connectivity redefining value capture in critical care diagnostics.
Closed-loop arterial line sampling systems with integrated clot detection and bubble elimination are digitizing pre-analytical error reduction. ICUs and operating rooms in the United States and Germany are adopting these platforms to minimize hemolysis and air contamination during specimen acquisition. This digitization is compressing the market for manual syringe-based collection methods and elevating service-contract pricing for integrated system vendors.
The EU Medical Device Regulation's software classification requirements are reshaping validation protocols for automated sampling platforms with embedded algorithms. Manufacturers must now demonstrate clinical evidence for decision-support functions previously treated as ancillary, extending development timelines and increasing regulatory affairs headcount. Blood gas analyzer vendors with European installations are responding by segregating software modules to isolate high-risk algorithmic components from core hardware submissions.
Hospital supply chain rationalization is consolidating arterial blood sampling procurement under diagnostic platform enterprise agreements. Integrated delivery networks in the United States are bundling sampling consumables with analyzer placement contracts, displacing independent distributor relationships and compressing standalone device margins. This concentration is most visible in multi-hospital systems pursuing vendor reduction initiatives to simplify accounts payable and standardize clinician training across facilities.
Arterial Blood Sampling Systems Market Segmentation
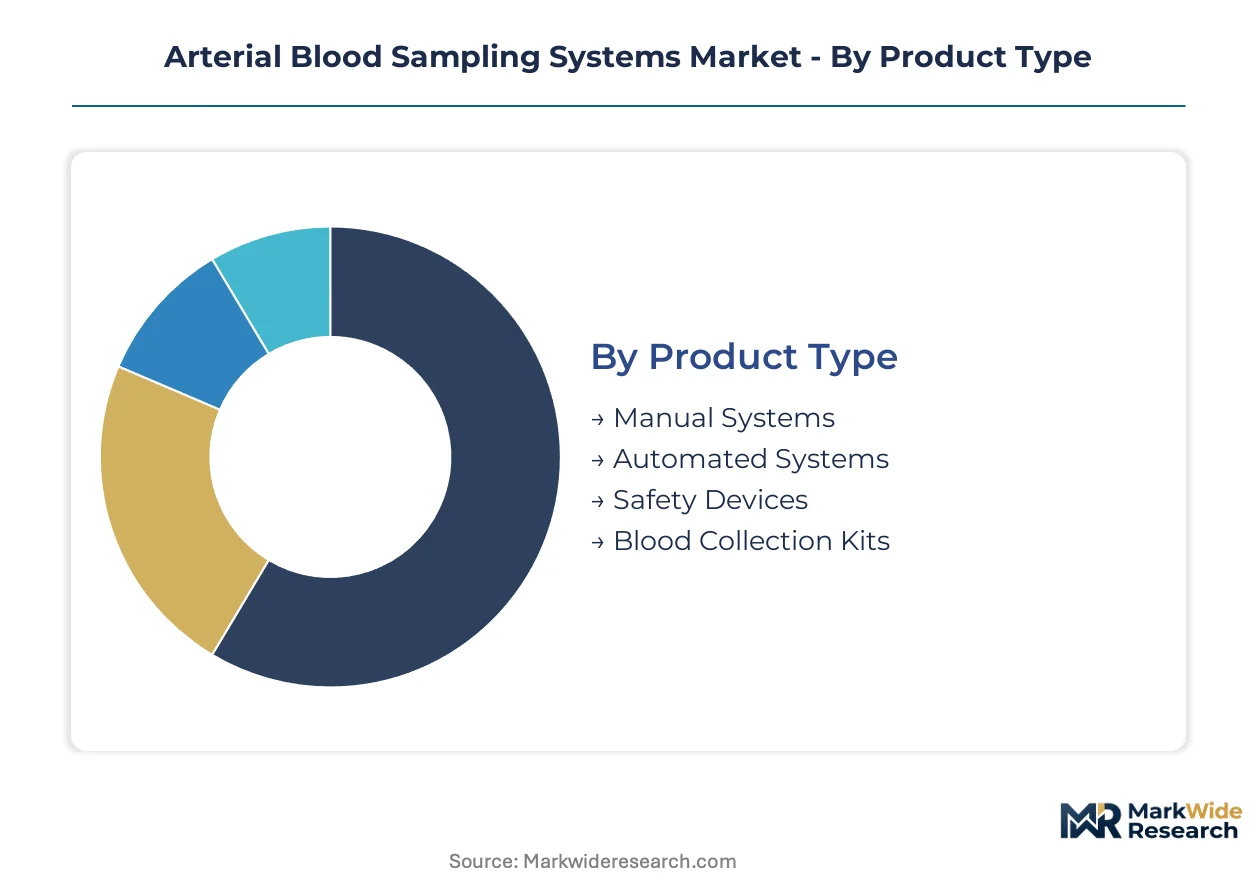
Arterial blood sampling systems fragment across four distinct dimensions, each shaping procurement patterns and vendor service obligations differently. Product type and end-user concentration drive the bulk of aftermarket support intensity, while material selection and usage frequency determine replacement cycles and inventory management complexity.
Product Type:
After-sales service intensity varies sharply across product categories, with automated platforms demanding continuous calibration support and safety devices requiring training-intensive deployment programs.
- Automated Systems:These platforms integrate robotic sample handling with embedded quality control sensors that detect clot formation and air bubbles during arterial line aspiration. Demand concentrates in United States and German ICUs where labor cost pressures and error reduction mandates justify premium capital outlays. Vendors capture recurring revenue through multi-year service contracts covering software updates and preventive maintenance schedules.
- Safety Devices:Needlestick prevention engineering dominates this segment, encompassing self-blunting needles and closed-collection chambers that eliminate clinician exposure to bloodborne pathogens. OSHA compliance deadlines in United States acute care facilities are accelerating replacement cycles for legacy open-collection equipment. Procurement runs through group purchasing organizations that negotiate enterprise pricing across integrated delivery networks.
- Manual Systems:Conventional syringe-based collection methods with basic anticoagulant coatings retain share in cost-constrained settings and developing markets with limited automation infrastructure.
- Blood Collection Kits:Pre-assembled disposable sets bundle syringes, needles, and transfer containers for standardized arterial sampling workflows in high-throughput environments.
Automated systems hold the largest share; momentum sits with safety devices as regulatory mandates tighten across major markets.
End User:
Customer type determines contract structure, with hospital procurement consortiums extracting volume discounts that standalone laboratories cannot match.
- Hospitals:Continuous arterial monitoring in ICUs and operating rooms sustains the highest per-bed consumption rates globally. United States multi-hospital systems are bundling sampling consumables with blood gas analyzer placements, compressing standalone device margins while locking in multi-year supply commitments.
- Diagnostic Laboratories:Decentralized testing expansion is driving the steepest expansion trajectory as outpatient surgery centers and standalone labs in Germany and the United States adopt closed-collection arterial sampling for point-of-care blood gas analysis.
- Research Institutions:Academic medical centers and contract research organizations utilize specialized arterial sampling protocols for pharmacokinetic studies and device validation trials.
- Blood Banks:Transfusion medicine applications require arterial sampling for donor screening and component quality verification in specialized collection facilities.
Hospitals dominate absolute volume; diagnostic laboratories are climbing the fastest as testing decentralizes from hospital core labs.
Usage Frequency:
Application cadence dictates inventory turnover and shelf-life management, with emergency use requiring immediate availability and surgical procedures demanding sterile lot tracking.
- Emergency Use:Arterial blood gas analysis in trauma bays and resuscitation suites demands immediate specimen acquisition without transport delays. Point-of-care integrated sampling systems in United States emergency departments eliminate pre-analytical variables by connecting directly to bedside analyzers.
- Surgical Procedures:Perioperative monitoring of acid-base status and oxygenation requires sterile, single-use collection sets with documented chain-of-custody for cardiac and major vascular surgeries.
- Routine Testing:Scheduled arterial sampling in chronic respiratory and metabolic monitoring programs follows standardized protocols with predictable consumption patterns.
- Clinical Trials:Protocol-specified arterial sampling for investigational drug studies demands specialized documentation and regulatory-grade specimen integrity controls.
Emergency use commands premium positioning; surgical procedures are gaining share fastest as operative complexity rises in aging populations.
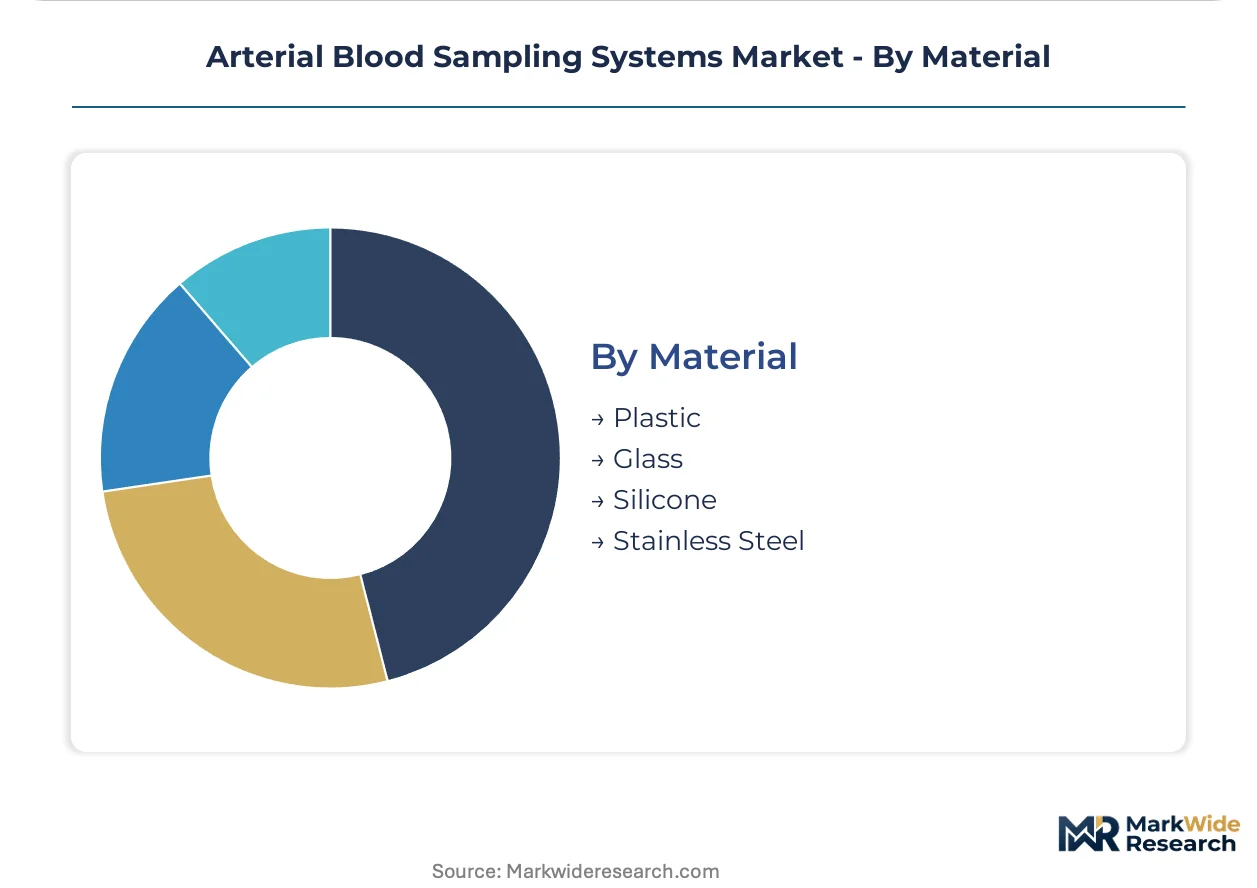
Material:
Supply concentration and biocompatibility certification requirements fragment sourcing strategies across material categories.
- Silicone:Medical-grade tubing and catheter components offer superior flexibility and thromboresistance for repeated-use arterial lines. Japanese PMDA enforces JIS-standard biocompatibility validation that extends qualification timelines for new silicone formulations.
- Plastic:Polypropylene and polycarbonate disposable components dominate high-volume manual collection sets due to cost efficiency and moldability.
- Stainless Steel:Precision-engineered needles and cannula components require passivation and surface treatment to prevent corrosion and ensure smooth vascular entry.
- Glass:Borosilicate syringe barrels retain niche applications where chemical inertness and optical clarity outweigh fragility concerns.
Silicone holds the largest share; plastic is expanding most quickly as disposable volume scales in cost-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA safety mandates in the United States are tightening needlestick prevention standards while EMA software classification rules reshape European automated platform launches. Critical care infrastructure expansion in China and Germany sustains arterial line consumable demand across these high-volume markets.
United States
OSHA Bloodborne Pathogens Standard enforcement accelerates safety-engineered device replacement in acute care facilities. Hospital procurement consortiums bundle sampling consumables with blood gas analyzer placements under multi-year enterprise agreements. The Boston-Cambridge medical technology cluster anchors automated sampling system development for integrated delivery networks.
Germany
ICU bed capacity expansion and decentralized testing migration drive closed-collection system demand in hospital and outpatient settings. EU MDR software classification requirements extend conformity assessment timelines for automated sampling-to-analysis platforms. The Baden-Württemberg industrial corridor concentrates blood gas analyzer manufacturing and compatible consumable supply chains.
China
Critical care infrastructure buildouts and blood gas analysis capability investments sustain arterial sampling consumable volume. National medical device registration pathways govern safety-engineered needle approvals for hospital procurement. Shanghai and Beijing medical device clusters scale domestic production of closed-collection arterial sampling systems for regional hospital networks.
Japan
PMDA JIS-standard biocompatibility requirements extend silicone and stainless steel component qualification timelines for repeated-use arterial lines. Aging population demographics expand chronic respiratory monitoring programs requiring scheduled arterial sampling. The Kanto region's precision manufacturing base supplies medical-grade tubing for domestic and export device markets.
United Kingdom
NHS supply chain rationalization consolidates arterial blood sampling procurement under diagnostic platform framework agreements. Post-Brexit UKCA marking transitions create parallel conformity assessment obligations for automated sampling systems. The Oxford-Cambridge-London life sciences corridor hosts point-of-care testing innovation targeting emergency department deployment.
Arterial Blood Sampling Systems Market Vendor Landscape
Diversified diagnostics conglomerates and specialized point-of-care technology developers split the market based on integrated platform versus standalone consumable positioning. The vendor landscape exhibits tiered concentration around blood gas analyzer bundling power and safety device regulatory compliance depth. Strategic archetypes span full-stack critical care platform vendors, safety-engineered consumable specialists, and regional automation technology providers. Competitive moves center on multi-year hospital enterprise agreements and FDA-EU dual submission pathways for integrated hardware-software platforms.
Among diversified diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions anchoring critical care placements through analyzer ecosystem control. Radiometer Medical exemplifies the point-of-care specialization archetype with emergency department-focused arterial line solutions. These three companies represent distinct competitive vectors: platform breadth, automation integration, and clinical workflow specificity.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Nova Biomedical |
| Radiometer Medical |
| OPTI Medical Systems |
| Medica Corporation |
| Siemens Healthineers |
| Instrumentation Laboratory |
| Techno Medica |
| Roche Diagnostics |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese medical-grade polymer production is compressing input costs for arterial line tubing while simultaneously eroding supplier pricing power across Asian manufacturing clusters. This utilization dynamic forces device makers to choose between absorbing margin compression or accelerating qualification of alternative silicone sources in Germany and Japan.
Pricing Analysis
Price spreads between United States and Chinese arterial sampling systems exceed thirty percent at equivalent safety-engineered specifications. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with FDA 510(k) certification tier and analyzer compatibility bundling as the primary differentiation drivers. Cost compression in standard-tier manual systems is intensifying because hospital procurement consortiums extract volume discounts through multi-year enterprise agreements. Diagnostic laboratories exhibit the highest price sensitivity due to capital constraints, while integrated delivery networks in the United States demonstrate the lowest sensitivity when bundling consumables with analyzer placements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for medical-grade silicone tubing and lithium heparin anticoagulant coatings. Manufacturing concentrates in China, Germany, and Japan for precision-engineered arterial line components. Raw material sourcing draws from East Asian petrochemical complexes for specialty polymers and European pharmaceutical suppliers for anticoagulant formulations. Single-source vulnerability persists for JIS-standard biocompatibility-certified silicone grades required by Japanese PMDA. Distribution runs through group purchasing organizations and direct hospital procurement consortiums rather than independent medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arterial blood sampling systems market rewards vendors who control hybrid competencies spanning perfusion technology, laboratory informatics, and point-of-care device management that currently outpace university training pipeline output.
For Market Incumbents: Harden analyzer ecosystem lock-in by embedding proprietary sampling-to-analysis protocols that resist third-party consumable substitution. Expand backward integration into medical-grade silicone compounding to insulate margin structures from East Asian petrochemical volatility. Prioritize FDA-EU dual submission pathways for automated platforms to compress competitive response windows.
For New Entrants and Emerging Players: Build out point-of-care testing capabilities for outpatient surgery centers and standalone diagnostic laboratories in Germany and the United States where incumbent bundling power remains weakest. Target emergency department workflow integration as the most penetrable application segment. Pursue software companion development for existing blood gas analyzer installed bases rather than competing on hardware replacement cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a consumable-annuity play because arterial line monitoring sustains recurring revenue through predictable replacement cycles in expanding critical care infrastructure. Acquisition candidates should demonstrate regulatory affairs depth across FDA 510(k) and EU MDR pathways alongside established GPO contract relationships. Monitor hospital procurement consortium vendor reduction initiatives as the critical signal for margin compression inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise agreements with integrated delivery networks lock in consumable volume against competitor displacement. |
| FDA Submission | Dual hardware-software clearance pathways compress time-to-market versus sequential regulatory filings for automated platforms. |
| CE Marking Pathway | EU MDR software classification compliance extends addressable market access for algorithm-enabled sampling systems. |
| Software Companion Development | Analyzer-agnostic quality control modules penetrate installed bases without requiring capital equipment replacement. |
| Reimbursement Strategy | Point-of-care testing coding alignment with CMS and German DRG frameworks accelerates hospital adoption economics. |
Methodological Framework
Initial hypotheses were tested against primary input from critical care physicians, hospital procurement committee members, biomedical engineering directors, and group purchasing organization contract managers and refined through secondary validation against FDA 510(k) clearance databases, EMA Medical Device Regulation submissions, hospital procurement consortium contract disclosures, and blood gas analyzer installed base records. Bottom-up demand modeling triangulated against top-down market sizing across product type, end user, usage frequency, and material segmentation dimensions.
Demand-supply-balance dynamics anchored the analytical framework across the analysis window, with segmentation modeling spanning automated systems, safety devices, manual systems, and collection kits by product type; hospitals, diagnostic laboratories, research institutions, and blood banks by end user; and silicone, plastic, stainless steel, and glass by material. CAGRs were derived from regression analysis of historical procurement volume against ICU bed expansion trajectories and blood gas analyzer placement rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified diagnostics conglomerates or point-of-care specialization entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Vascular Plugs Market
Cardiovascular Devices
US Ventricular Assist Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Netherlands Cardiovascular Devices Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Prosthetic Devices Market
Cardiovascular Devices
Global Pediatric Interventional Cardiology Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Cardiovascular Surgical Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Global Peripheral Stent Market