
 Global Artificial Intelligence in Ultrasound Imaging Market | 2026-2036
Global Artificial Intelligence in Ultrasound Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence in Ultrasound Imaging Market Foresight
Software-defined diagnostic layers is broadening what ultrasound OEMs monetize beyond hardware shipments. GE Healthcare leverages its Edison platform to anchor AI algorithm deployment across hospital networks. Koninklijke Philips N.V. competes through integrated workflow tools that connect acquisition to structured reporting. Siemens Healthineers specializes in real-time inference at the point of care, differentiating its portfolio from conventional cart-based systems.
Artificial intelligence in ultrasound imaging encompasses algorithmic systems that analyze acoustic signal data to automate anatomical recognition, quantify physiological parameters, and flag pathological findings in real time. These systems typically process raw radiofrequency data or reconstructed B-mode images through trained neural networks, delivering measurements such as ejection fraction or fetal biometry without manual caliper placement. Deep learning architectures now dominate algorithm development for cardiac and obstetric applications, where pattern complexity rewards multi-layered feature extraction. Cloud-based deployment is gaining traction fastest among imaging clinics seeking scalable infrastructure without capital-intensive on-premise servers. Edge computing configurations serve emergency departments and mobile screening units where latency constraints override bandwidth economics.
The FDA's software-as-a-medical-device framework shapes how developers validate algorithm performance across diverse patient populations and scanner models. The European Medicines Agency and Medical Device Regulation impose clinical evidence requirements that filter out lower-validity algorithms from the EU market. Japan's Ministry of Economy, Trade and Industry coordinates standards alignment through JIS frameworks for AI-enabled diagnostic equipment. Stakeholders must monitor how divergent evidentiary standards across these jurisdictions fragment product development roadmaps and delay synchronized launches.
Market Dynamics
Software-as-a-medical-device frameworks are compressing validation timelines for algorithmic ultrasound tools, pulling deployment decisions away from capital committees and toward IT procurement functions in integrated health networks.
Growth Catalysts
- FDA's SaMD Pathway:The framework accelerates 510(k) clearances for AI-enabled diagnostic algorithms, reducing time-to-market for developers targeting US hospital systems.
- Cardiology Workflow Integration:Health systems are embedding automated ejection fraction measurements into standard echocardiography protocols, eliminating manual caliper placement bottlenecks.
- Cloud Infrastructure:Imaging clinics are adopting scalable cloud deployments to bypass capital-intensive on-premise server requirements for deep learning inference.
Market Restraints
- Scanner Model Fragmentation:Algorithm training across heterogeneous radiofrequency data formats from multiple OEMs inflates validation costs and limits cross-platform portability.
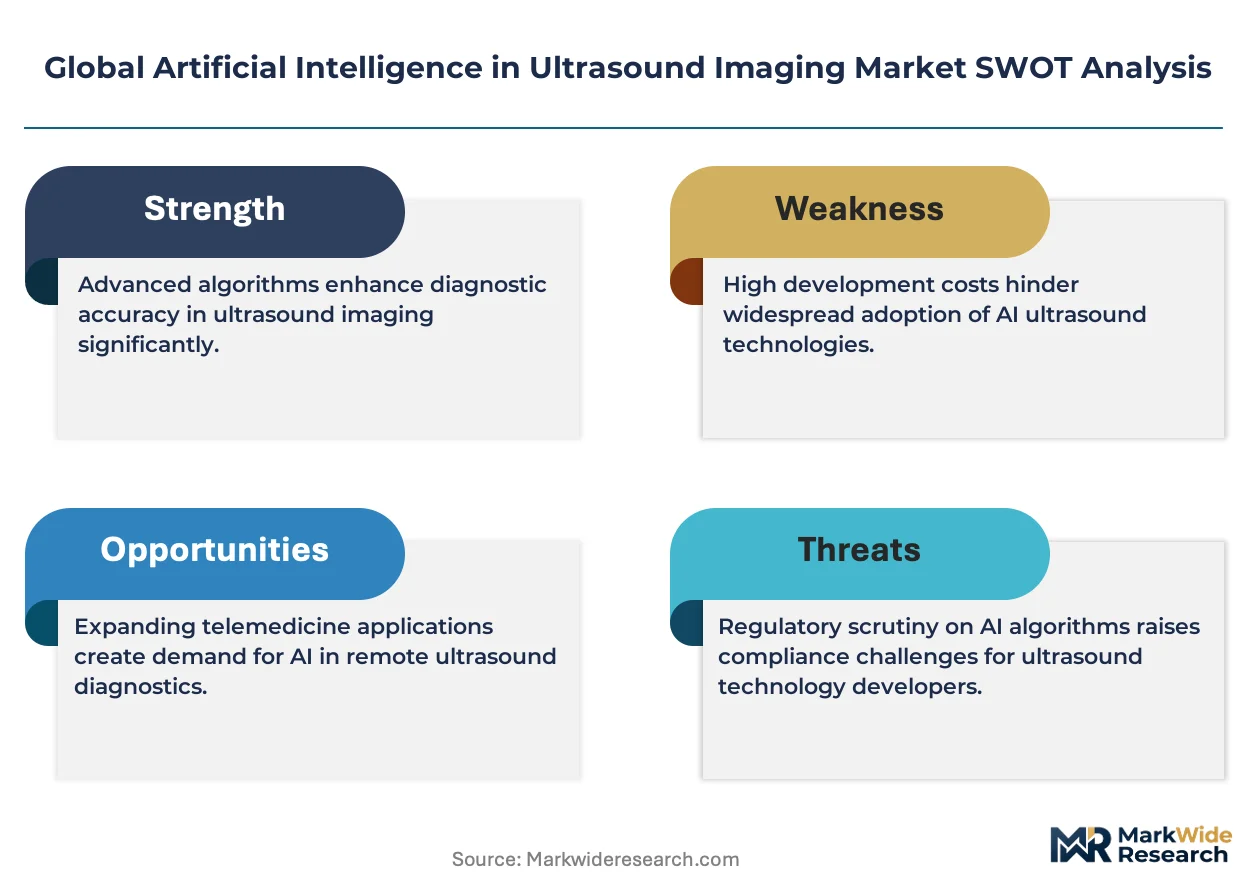
- EU MDR Evidence Requirements:Clinical performance studies mandated under the Medical Device Regulation filter lower-validity algorithms from European markets, raising barriers for mid-stage developers.
- GPU Supply Concentration:Inference hardware dependence on Taiwan-based semiconductor fabrication creates vulnerability in edge computing deployment timelines.
Strategic Opportunities
- Obstetric Point-of-Care:Automated fetal biometry in low-resource settings offers expansion paths for algorithms validated on limited training data from diverse maternal populations.
- Japan METI Standards Alignment:Coordinated JIS frameworks for AI-enabled diagnostic equipment create preferential procurement pathways for compliant vendors in Japanese hospital networks.
- 5G-Enabled Mobile Screening:Low-latency connectivity allows real-time cloud inference for rural ultrasound units previously constrained by bandwidth economics.
Industry Challenges
- Regulatory Divergence:Misaligned evidentiary requirements across FDA, EMA, and PMDA fragment product development roadmaps and delay synchronized multi-territory launches.
- Integration Complexity:Legacy PACS and EMR systems in established radiology networks resist seamless API connectivity for AI-generated structured reports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence in Ultrasound Imaging Market |
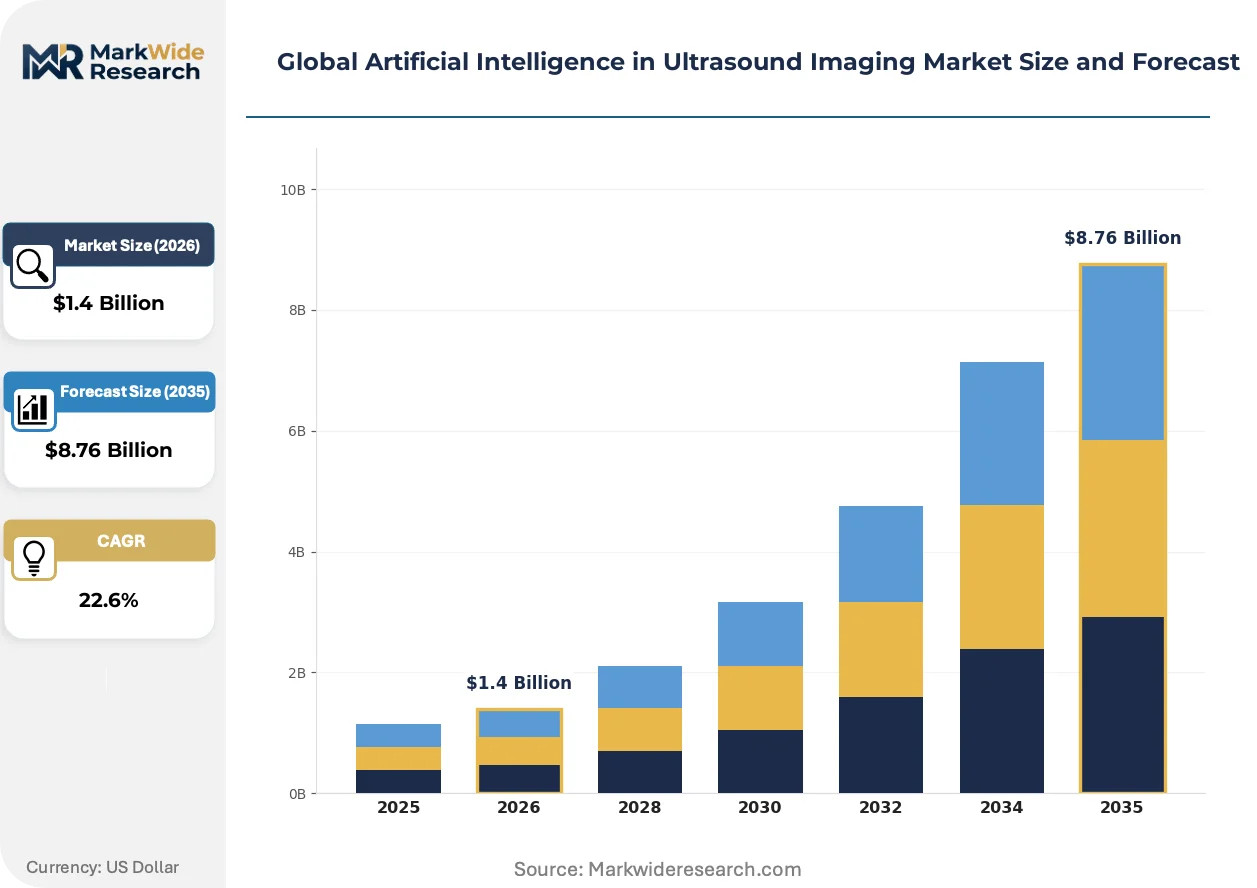
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $8.76 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Cardiology, Obstetrics & Gynecology, Radiology, Neurology, Musculoskeletal Technology: Deep Learning, Machine Learning, Natural Language Processing, Computer Vision, Neural Networks End User: Diagnostic Centers, Research Laboratories, Imaging Clinics, Academic Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Samsung Healthcare, Butterfly Network, Inc., EchoNous, Inc., Qure.ai, Clarius, Fujifilm Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence in Ultrasound Imaging Market Shifts & Advancements
Deep learning architectures are migrating from post-processing workstations to real-time acquisition streams, compressing the gap between image capture and diagnostic output while reshaping operator training requirements.
Edge computing configurations for ultrasound AI are expanding into emergency departments and mobile screening units where sub-100-millisecond latency constraints override cloud economics. Critical care teams in US trauma centers are deploying cart-based systems with onboard neural inference engines for immediate pathology flagging. This architecture is compressing the traditional workflow separation between acquisition, transfer, and interpretation roles.
The EU AI Act risk classification framework is mandating conformity assessments for high-risk diagnostic algorithms before CE marking, extending validation timelines for developers targeting European hospital procurement. Siemens Healthineers and Philips are restructuring quality management systems to accommodate post-market monitoring obligations for continuously learning models. Cardiology applications face the steepest compliance burden given their direct patient outcome implications.
Radiology group purchasing organizations are consolidating algorithm procurement decisions across multi-hospital networks, displacing individual department-level software acquisitions. US-based integrated delivery networks are negotiating enterprise licenses covering AI modules across cardiology, obstetrics, and point-of-care applications. This concentration is visible most acutely in Midwestern health systems building unified imaging infrastructure across acquired community hospitals.
Global Artificial Intelligence in Ultrasound Imaging Market Segmentation
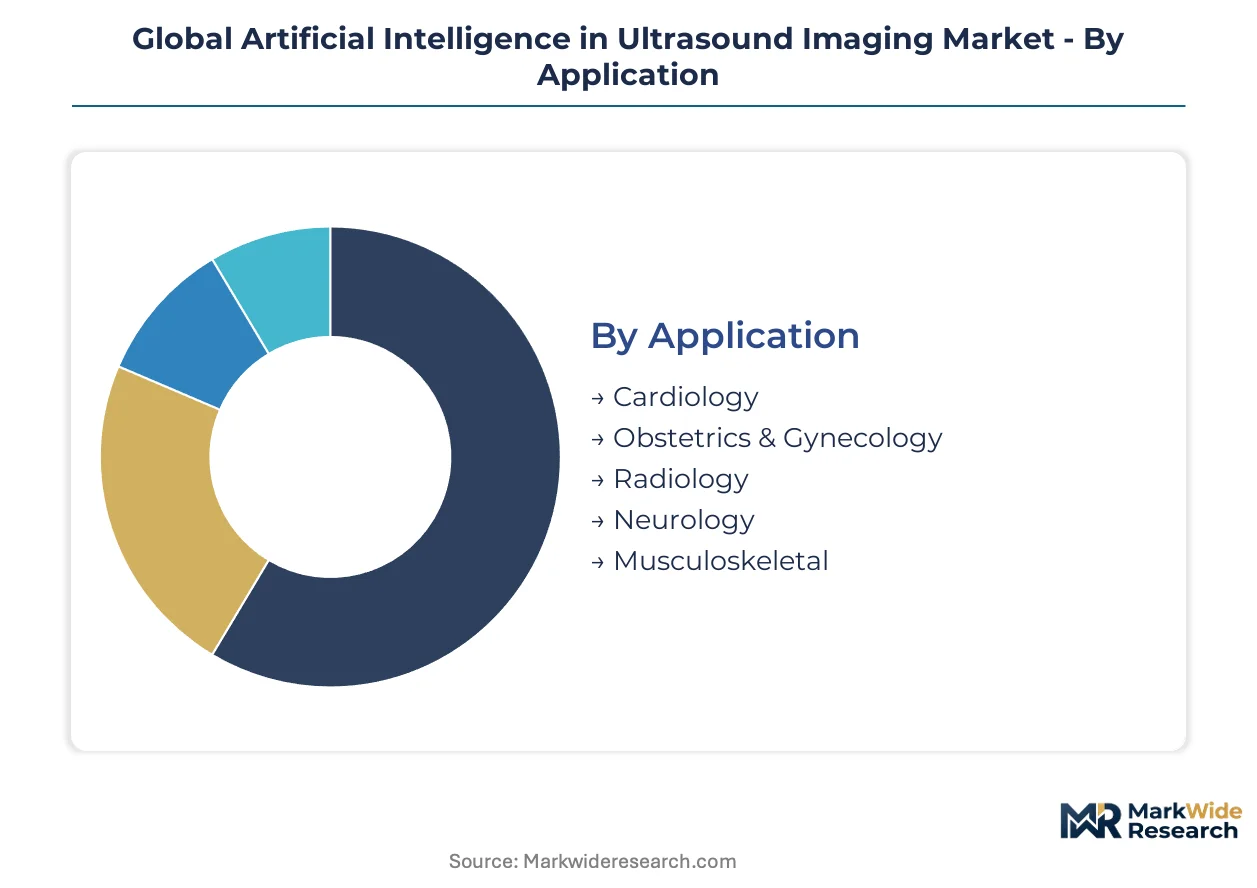
Segmentation in AI ultrasound imaging reflects divergent hardware requirements, regulatory pathways, and reimbursement models across clinical settings. Understanding how algorithmic tools map to specific deployment architectures and end-user workflows enables precise market positioning for developers navigating fragmented procurement channels.
Application:
Supply concentration in algorithm development clusters around high-volume, high-reimbursement clinical domains where training data abundance accelerates regulatory clearance timelines.
- Cardiology:Automated ejection fraction measurements and valve assessment algorithms process real-time echocardiography streams. US hospital systems embed these tools into standard protocols, eliminating manual caliper placement bottlenecks in high-throughput cath labs.
- Obstetrics & Gynecology:Fetal biometry automation reduces operator dependency for gestational age estimation and growth monitoring. Demand concentrates in Germany and Japan where maternal screening programs mandate standardized documentation across regional networks.
- Radiology:General-purpose lesion detection and organ segmentation tools integrate with PACS workflows for abdominal and thyroid imaging.
- Neurology:Transcranial Doppler analysis for stroke detection and intracranial pressure monitoring deploys primarily in US and Japanese trauma centers.
- Musculoskeletal:Tendon and ligament assessment algorithms serve sports medicine clinics and orthopedic practices with point-of-care systems.
Cardiology absorbs the bulk of installed capacity; Obstetrics & Gynecology is expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive training infrastructure from lightweight inference deployments, with cloud-native architectures lowering entry barriers for mid-stage developers.
- Deep Learning:Multi-layered neural architectures extract hierarchical features from raw radiofrequency data or reconstructed B-mode images. US and Japanese regulators have cleared convolutional and transformer-based models for cardiac and obstetric applications, establishing precedent for subsequent submissions.
- Machine Learning:Traditional supervised methods using handcrafted feature engineering persist in resource-constrained settings and legacy system integrations. These lighter-weight approaches serve mobile screening units in India and Brazil where computational budgets limit deep learning deployment.
- Natural Language Processing:Structured report generation from free-text operator annotations automates documentation workflows in German and Dutch radiology networks.
- Computer Vision:Real-time image quality assessment and probe guidance tools reduce operator training requirements for novice sonographers.
- Neural Networks:Recurrent and graph neural architectures model temporal sequences in cardiac cycles and vascular flow patterns.
Deep Learning captures dominant development investment; Natural Language Processing is gaining share fastest as structured reporting mandates spread across EU hospital procurement specifications.
End User:
Volume concentration among integrated health networks is displacing fragmented departmental purchasing, with enterprise licensing reshaping vendor commercial strategies.
- Diagnostic Centers:High-throughput facilities process outsourced imaging referrals from multiple hospital systems. These operators prioritize cross-platform algorithm compatibility to accommodate heterogeneous scanner fleets from GE, Philips, and Siemens.
- Imaging Clinics:Independent operators adopt cloud-based deployments to bypass capital-intensive server infrastructure. Japanese metropolitan clinics lead this transition, leveraging METI-coordinated standards for seamless vendor switching.
- Research Laboratories:Academic medical centers in the US, Germany, and Japan validate novel architectures and curate training datasets for regulatory submission packages.
- Academic Institutions:Training programs integrate AI-assisted feedback systems to accelerate sonographer competency development.
Diagnostic Centers absorb the bulk of installed capacity; Imaging Clinics is expanding most quickly.
Deployment:
Margin structure varies sharply across architectures, with edge computing commanding hardware premiums while cloud deployments shift revenue toward recurring subscription models.
- Cloud-Based:Scalable inference infrastructure enables rapid algorithm updates and multi-site model synchronization without on-premise maintenance. US imaging clinic chains and German radiology networks favor this architecture for centralized quality control across distributed sites.
- Edge Computing:On-device neural inference engines deliver sub-100-millisecond latency for emergency department triage and mobile screening. US trauma centers and Japanese disaster response units deploy cart-based systems with NVIDIA Jetson or Qualcomm hardware for immediate pathology flagging.
- On-Premise:Hospital-controlled server installations address data sovereignty requirements in Swiss and German healthcare systems with strict patient information localization mandates.
- Hybrid:Tiered architectures process sensitive data locally while offloading non-critical workloads to cloud infrastructure, balancing latency and cost optimization.
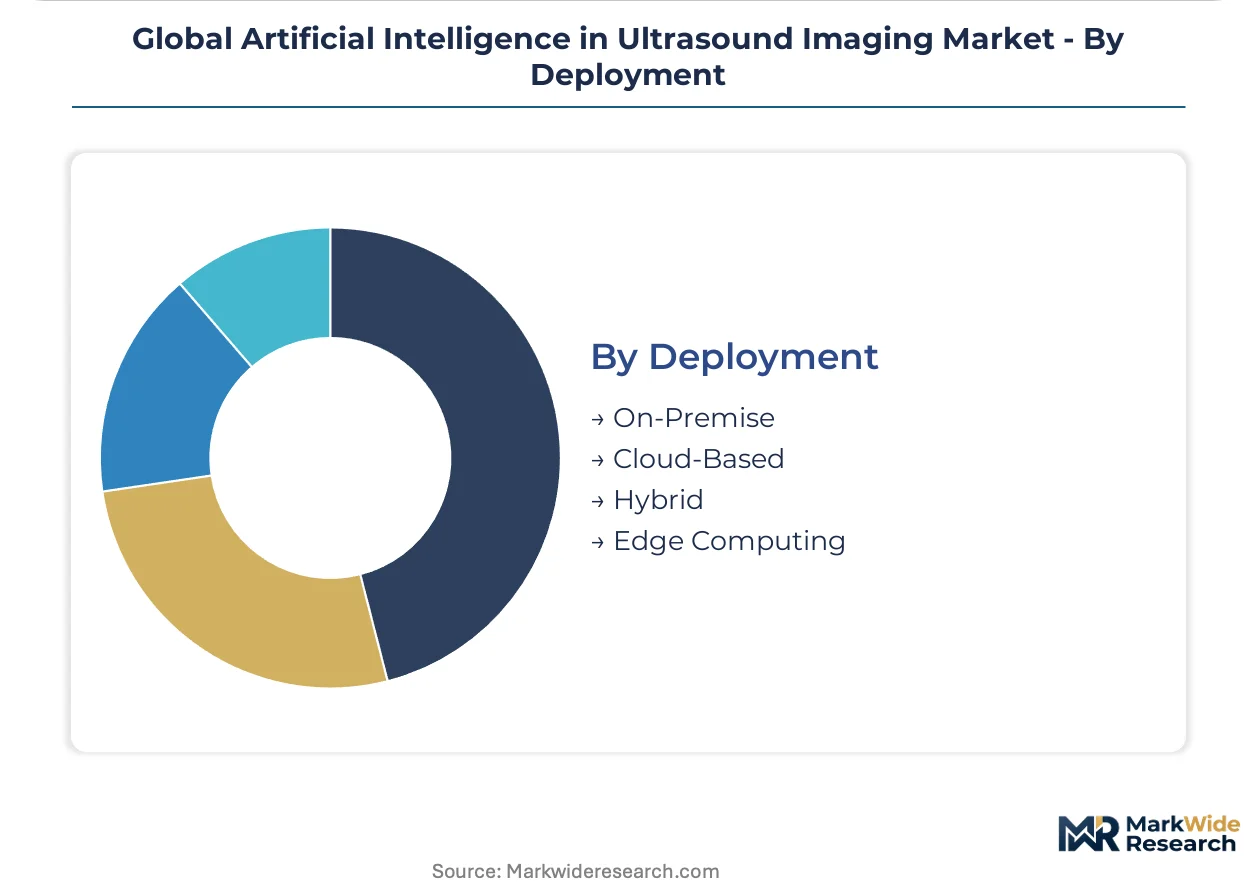
Cloud-Based absorbs the bulk of new deployment decisions; Edge Computing is expanding most quickly as semiconductor efficiency improvements reduce hardware cost barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Algorithm development concentrates in the United States, Germany, and Japan, while deployment demand spreads across hospital networks in secondary markets. Production of AI training infrastructure and regulatory validation expertise clusters in established medtech hubs. Consumption patterns diverge between integrated health systems adopting enterprise licenses and independent clinics pursuing cloud-based deployments.
United States
FDA's software-as-a-medical-device framework accelerates 510(k) clearances for cardiology AI algorithms, compressing validation timelines. Integrated delivery networks in the Midwest negotiate enterprise licenses spanning echocardiography and point-of-care modules. The Boston-Cambridge corridor anchors algorithm development for real-time inference systems.
Germany
EU Medical Device Regulation filters lower-validity algorithms from hospital procurement, elevating evidence requirements for market entry. METI-coordinated standards alignment creates preferential pathways for compliant vendors in Baden-Württemberg's industrial medical cluster. Siemens Healthineers leverages Munich-based R&D for edge computing configurations in emergency departments.
Japan
PMDA clearance precedents for cardiac and obstetric applications establish regulatory templates for subsequent submissions. METI's JIS frameworks for AI-enabled diagnostic equipment standardize interoperability across Tokyo-Osaka hospital networks. The Kanto region concentrates validation partnerships between academic medical centers and algorithm developers.
United Kingdom
NHS England's imaging networks consolidate algorithm procurement decisions across regional trusts, displacing fragmented departmental purchasing. MHRA recognition of FDA-cleared algorithms streamlines parallel market entry for US developers. London's academic hospitals curate training datasets for regulatory submission packages targeting EU and Commonwealth markets.
South Korea
MFDS accelerated review pathways for AI diagnostic software attract developers seeking Asian market expansion beyond Japan. Seoul National University Hospital anchors validation partnerships for fetal biometry algorithms targeting low-resource deployment. The Pangyo Techno Valley cluster hosts inference hardware integration facilities for edge computing systems.
Global Artificial Intelligence in Ultrasound Imaging Market Competitive Landscape
Top-tier vendors anchor integrated platform strategies, while mid-stage developers compete through specialized algorithm modules and cloud-native deployment. The vendor base stratifies across three tiers: diversified medtech conglomerates with hardware-software integration, AI-native specialists with regulatory-first validation approaches, and point-of-care innovators with mobile-first architectures. Dominant competitive moves include strategic partnerships for training data access and portfolio diversification across cardiology, obstetrics, and radiology applications.
Within the diversified conglomerate tier, GE Healthcare, Koninklijke Philips N.V., and Siemens Healthineers occupy positions defined by existing ultrasound hardware installed bases and enterprise workflow integration. These manufacturers exemplify platform-centric competition where AI algorithm deployment anchors recurring revenue streams beyond initial equipment sales. Their geographic footprints span US, European, and Japanese hospital procurement networks where regulatory clearance precedents accumulate competitive moats.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Samsung Healthcare |
| Butterfly Network, Inc. |
| EchoNous, Inc. |
| Qure.ai |
| Clarius |
| Fujifilm Corporation |
| Others |
Supply & Pricing Matrix
Platform-anchored conglomerates with captive ultrasound hardware installed bases exercise asymmetric pricing power over algorithm developers lacking scanner integration. Private-equity-rolled-up imaging clinic chains in the United States and Germany consolidate procurement leverage, forcing SaaS pricing compression while semiconductor supply concentration in Taiwan and South Korea constrains edge computing hardware availability.
Pricing Analysis
Margin tightening in cloud-based algorithm tiers reflects hyperscaler infrastructure cost pass-throughs and radiology GPO consolidated purchasing. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared cardiac modules from CE-marked general imaging tools and unvalidated research-use algorithms. Price differentiation hinges on regulatory clearance tier and scanner OEM certification status. Imaging clinics exhibit highest price sensitivity; integrated US health systems absorb premium pricing for enterprise workflow integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for NVIDIA Jetson and Qualcomm neural inference hardware, bypassing distributor markups for trauma center deployments. GPU fabrication concentrates in Taiwan and South Korea, with advanced packaging operations in Malaysia and Vietnam. Raw material dependencies span silicon wafers, high-bandwidth memory stacks, and specialized ultrasound transducer ceramics. Single-source vulnerability in TSMC's 7nm and 5nm process nodes threatens edge computing deployment timelines for real-time cardiac inference systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as algorithm developers pursue backward integration into training data curation and scanner OEMs absorb inference software capabilities to defend hardware attach rates.
For Market Incumbents: Lock in algorithm deployment exclusivity through Edison platform ecosystem commitments and Philips HealthSuite API integrations. Defend against AI-native specialists by accelerating FDA 510(k) clearance accumulation for cardiac and obstetric modules. Prioritize cloud infrastructure partnerships with AWS and Microsoft Azure to neutralize independent clinic price erosion. For New Entrants and Emerging Players: The premium-economy price-point gap in point-of-care obstetric applications creates entry space for validated fetal biometry algorithms targeting Indian and Brazilian mobile screening units. Pursue METI JIS framework compliance for preferential Japanese hospital procurement access. Lead with 5G-enabled cloud inference architectures to bypass capital-intensive edge hardware requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-stage algorithm developers with FDA clearance precedents but constrained distribution reach in United States and German hospital networks. Long-term viability centers on regulatory moat accumulation and training data exclusivity. Watch PMDA clearance velocity for cardiac applications as inflection indicator for Asian market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Accumulation | Regulatory precedents for cardiac AI algorithms establish competitive moats against late entrants in US hospital procurement. |
| Cloud Infrastructure Partnership | AWS and Azure alliances enable scalable inference deployment without capital-intensive on-premise server investments. |
| Training Data Exclusivity Agreements | Academic medical center partnerships in Boston and Tokyo secure curated datasets for algorithm validation packages. |
| Scanner OEM API Integration | Native embedding into GE and Philips acquisition workflows displaces standalone post-processing software vendors. |
| METI JIS Standards Alignment | Compliance with Japanese interoperability frameworks unlocks preferential procurement in Tokyo-Osaka hospital networks. |
Research Methodology
Independent corroboration across FDA 510(k) clearance databases, EU MDR conformity assessment records, and PMDA approval registries underwrites the qualitative findings on regulatory pathway divergence. Primary interviews with hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and algorithm development executives combined with secondary validation from CMS Medicare reimbursement data, hospital procurement databases, and SEC filings from listed medtech conglomerates. Bottom-up installed base estimates triangulate against top-down market sizing from imaging equipment trade associations.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by application, technology, deployment architecture, and end-user concentration. Segmentation dimensions modeled span cardiology versus obstetric versus radiology applications, cloud versus edge versus on-premise deployment, and integrated health network versus independent clinic purchasing patterns. CAGRs derive from algorithm adoption curve analysis and scanner replacement cycle timing. Forecast inputs incorporate GPU supply availability trajectories and regulatory clearance velocity differentials across FDA, EMA, and PMDA jurisdictions.
Inputs from FDA 510(k) databases and EU MDR notified body assessments were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around cloud deployment adoption rates. Forecasts reflect assumptions regarding semiconductor supply normalization and regulatory harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
US Contrast Media Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Medical Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Medical Imaging Agent-Producing System Market