
 Cardiac Medical Device Market | 2026-2036
Cardiac Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiac Medical Device Market Analysis
Remote monitoring subscription services for implantable cardiac devices is hardening into a core revenue stream alongside hardware sales. Medtronic leverages its CareLink network to sustain recurring revenue from pacemaker and defibrillator patients. Abbott differentiates through Bluetooth-enabled implantable devices that transmit arrhythmia data directly to clinic dashboards. Boston Scientific Corporation anchors its electrophysiology franchise with integrated mapping and ablation platforms that bundle capital equipment with per-procedure consumables.
Cardiac medical devices encompass implantable and external instruments engineered to diagnose, monitor, or treat cardiovascular pathologies, typically incorporating biocompatible alloys, polymeric coatings, and microelectronic sensors with operational lifespans measured in years for permanent implants. These devices serve to restore rhythm, maintain perfusion, or structurally repair damaged cardiac tissue in clinical and ambulatory settings. Implantable cardioverter defibrillators and pacemakers command mature installed bases where replacement cycles and battery longevity drive steady revenue. Wearable devices represent the fastest-expanding technology segment as patch-based monitors and consumer-integrated ECG sensors shift arrhythmia detection toward outpatient and home-based settings. Catheters concentrate margin pools in electrophysiology procedures where specialized ablation technologies command premium pricing against commodity interventional tools.
The FDA's breakthrough device program and the European Union's Medical Device Regulation reshape competitive access by accelerating review timelines for novel technologies while imposing stricter clinical evidence requirements on legacy product lines. Japan's PMDA maintains distinct approval pathways for innovative cardiac rhythm devices that influence regional launch sequencing for multinational manufacturers. Stakeholders must weigh escalating cybersecurity mandates for connected cardiac implants against the operational burden of continuous software validation across distributed patient populations.
Market Dynamics
Catheter ablation volumes are compressing hospital reimbursement models toward bundled payment structures, forcing device manufacturers to demonstrate per-procedure cost efficiency alongside clinical efficacy. This structural pressure reshapes how electrophysiology platforms are priced, sold, and integrated into health system workflows.
Growth Catalysts
- FDA Breakthrough Device Pathway:Accelerated review timelines for novel electrophysiology tools compress commercialization cycles for innovative mapping and ablation technologies.
- Wearable Patch Monitors:Outpatient arrhythmia detection shifts diagnostic volumes away from hospital-based Holter systems toward home-based monitoring services.
- Japan:PMDA maintains distinct approval pathways for cardiac rhythm devices that incentivize early launch sequencing and localized clinical trials.
Market Restraints
- Palladium and Platinum Volatility:Electrode materials in ablation catheters face input cost swings that compress gross margins on consumable product lines.
- EU MDR Clinical Evidence Burden:Legacy pacemaker and defibrillator portfolios require costly retrospective studies to maintain CE marking under tightened requirements.
- Consumer-Grade ECG Substitution:Apple Watch and similar devices capture low-acuity arrhythmia screening that previously generated cardiology referrals.
Strategic Opportunities
- Remote Monitoring Subscriptions:Recurring revenue models for implantable device data transmission harden into core revenue streams alongside hardware sales.
- Bluetooth-Enabled Implants:Direct-to-dashboard data transmission eliminates intermediary hardware and opens clinic efficiency gains.
- Germany:Catheter ablation program expansion creates procurement windows for integrated mapping platforms in university hospital networks.
Industry Challenges
- Electrophysiologist Training Pipeline:Complex ablation procedures require specialized operators; fellowship slot constraints limit procedure volume growth.
- Legacy EMR Integration:New device data formats face interoperability friction with entrenched hospital information systems, delaying deployment timelines.
- Cybersecurity Validation Burden:Connected implants require continuous software patching across distributed patient populations, straining post-market surveillance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiac Medical Device Market |
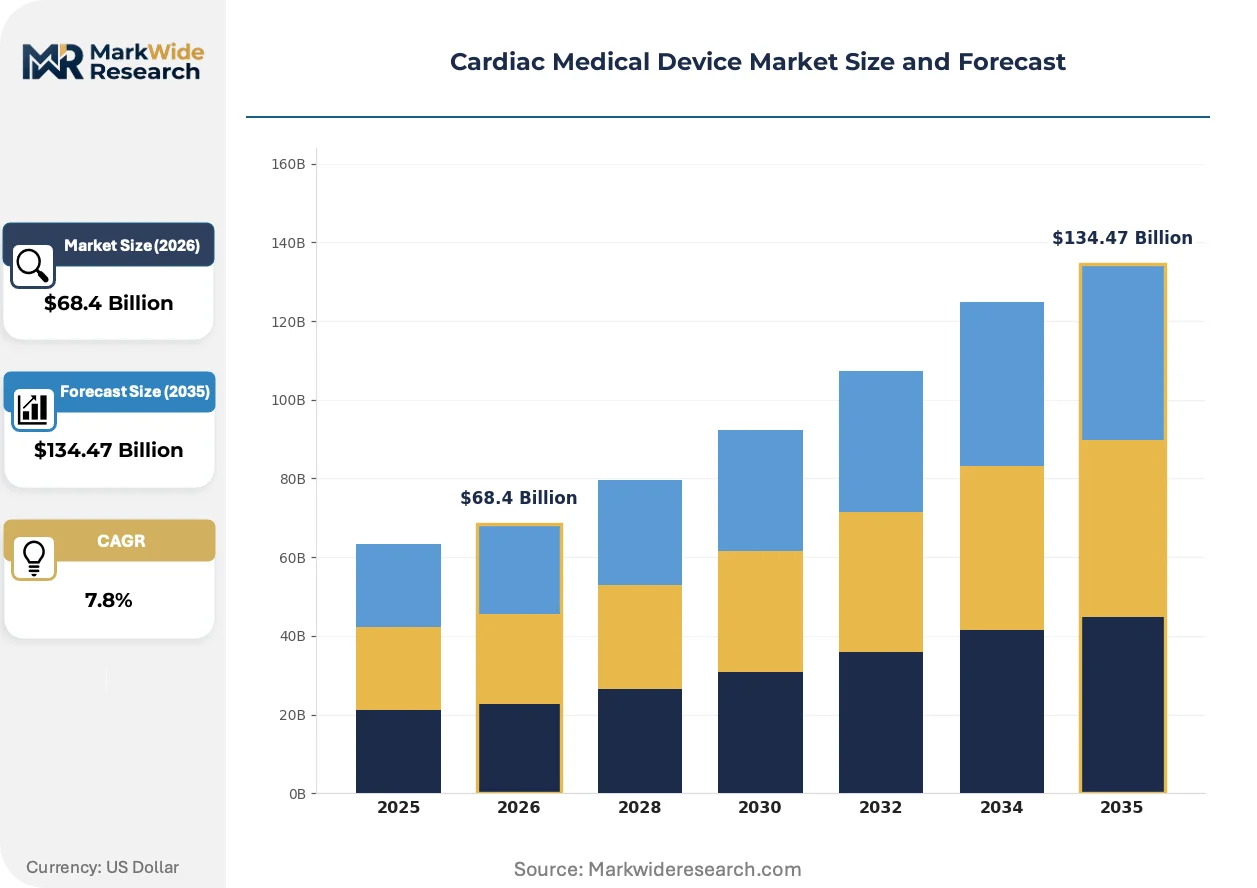
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Cardioverter Defibrillators, Pacemakers, Stents, Catheters End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Technology: Non-Invasive Monitoring, Invasive Procedures, Wearable Devices, Surgical Instruments Application: Arrhythmia Management, Heart Failure Treatment, Coronary Artery Disease, Electrophysiological Studies |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, Edwards Lifesciences Corporation, GE HealthCare, BIOTRONIK, Terumo Corporation, Johnson & Johnson, LivaNova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiac Medical Device Market Emerging Trajectories
Artificial intelligence is embedding into cardiac device workflows, compressing diagnostic interpretation timelines and enabling predictive arrhythmia modeling that shifts clinical decision points earlier in care pathways.
Machine learning algorithms are integrating into electroanatomic mapping systems to automate scar tissue identification and ablation target prediction. Academic medical centers in the United States and Germany are deploying these tools to reduce procedure duration and fluoroscopy exposure. The technology is integrating real-time catheter navigation with pre-procedural imaging, compressing the learning curve for complex atrial fibrillation ablations.
MDR's post-market surveillance requirements are mandating systematic implant registries and active device monitoring across European member states. Manufacturers must now fund long-term follow-up studies as a condition of market access. High-risk cardiac rhythm devices face the steepest compliance burden, with notified bodies demanding granular adverse event tracking that delays legacy product recertification.
Hospital procurement committees are consolidating electrophysiology vendor relationships to secure volume-based discounts on consumables and capital equipment. Integrated platform contracts that bundle mapping systems with ablation catheters are displacing best-of-breed purchasing in United States health systems. This concentration is most visible in multi-hospital IDNs where standardization across cath labs generates procurement leverage.
Cardiac Medical Device Market Segmentation
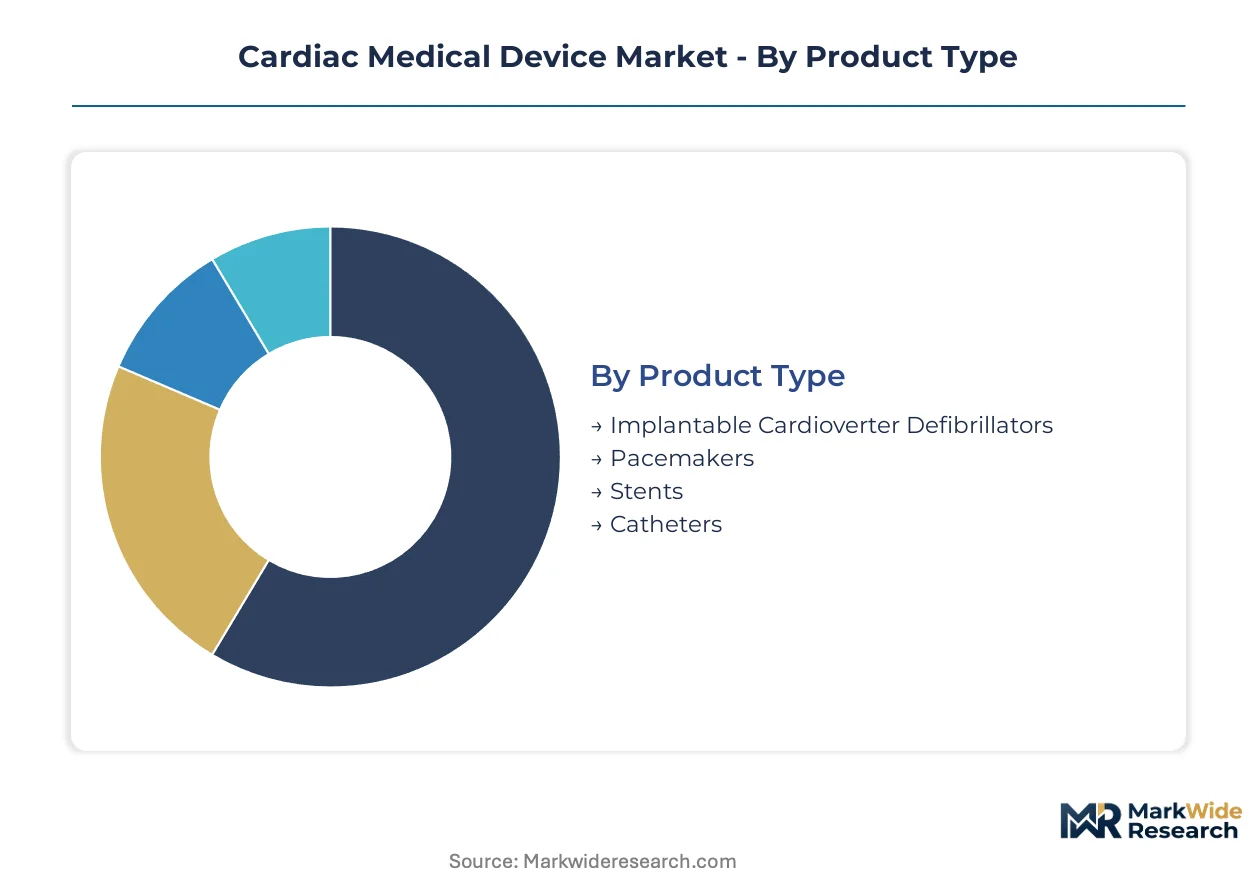
Segmentation in cardiac medical devices reveals how procurement authority, reimbursement pathways, and clinical workflow integration determine commercial access. Manufacturers must align product configurations with distinct buyer economics across implantable hardware, consumable catheters, and connected monitoring services.
Product Type:
Cost tier separates replacement-cycle implants from per-procedure consumables, reshaping how vendors structure pricing and service contracts.
- Implantable Cardioverter Defibrillators:These devices incorporate lithium-silver vanadium oxide batteries and titanium housings engineered for multi-year operational lifespans. Demand concentrates in United States hospital systems where bundled cardiac resynchronization contracts consolidate vendor relationships.
- Pacemakers:Dual-chamber units with leadless miniaturization command premium positioning against traditional transvenous systems. German university hospitals drive adoption of MRI-conditional designs that eliminate scan restrictions for aging patient populations.
- Stents:Drug-eluting platforms with bioresorbable polymer coatings dominate coronary intervention workflows.
- Catheters:Irrigated ablation designs with force-sensing technology capture margin pools in electrophysiology suites.
Volume sits with Stents; growth tilts toward Catheters.
End User:
Procurement authority shifts from centralized hospital supply chains to distributed outpatient settings, fragmenting vendor sales motions.
- Hospitals:Integrated delivery networks in the United States negotiate enterprise-wide electrophysiology platform contracts that bundle capital equipment with multi-year consumable commitments. These structures favor vendors with comprehensive mapping and ablation portfolios.
- Clinics:Cardiology group practices in Germany leverage catheter ablation program expansion to secure direct-to-manufacturer pricing on single-use devices.
- Ambulatory Surgical Centers:Medicare reimbursement shifts for routine pacemaker implants accelerate site-of-care migration.
- Home Care:Remote monitoring subscriptions for implantable devices create recurring revenue streams outside institutional settings.
Procurement volume clusters at Hospitals; patient volume is expanding most quickly at Home Care.
Technology:
Application setting determines regulatory pathway and reimbursement coding, creating divergent commercialization timelines.
- Wearable Devices:Patch-based ECG monitors with adhesive electrodes and cloud-connected analytics enable multi-day arrhythmia detection without clinic visits. United States cardiology practices deploy these systems to reduce Holter monitor backlogs and capture diagnostic revenue in outpatient settings.
- Invasive Procedures:Electroanatomic mapping systems integrate magnetic location tracking with real-time ablation catheter navigation. Japanese academic medical centers prioritize platforms with reduced fluoroscopy protocols to minimize radiation exposure during complex atrial fibrillation cases.
- Non-Invasive Monitoring:Transthoracic impedance sensors and acoustic cardiography devices support heart failure surveillance.
- Surgical Instruments:Beating-heart stabilizers and endoscopic vessel harvesters serve coronary bypass procedures.
Revenue concentration remains with Invasive Procedures; Wearable Devices show the steepest expansion trajectory.
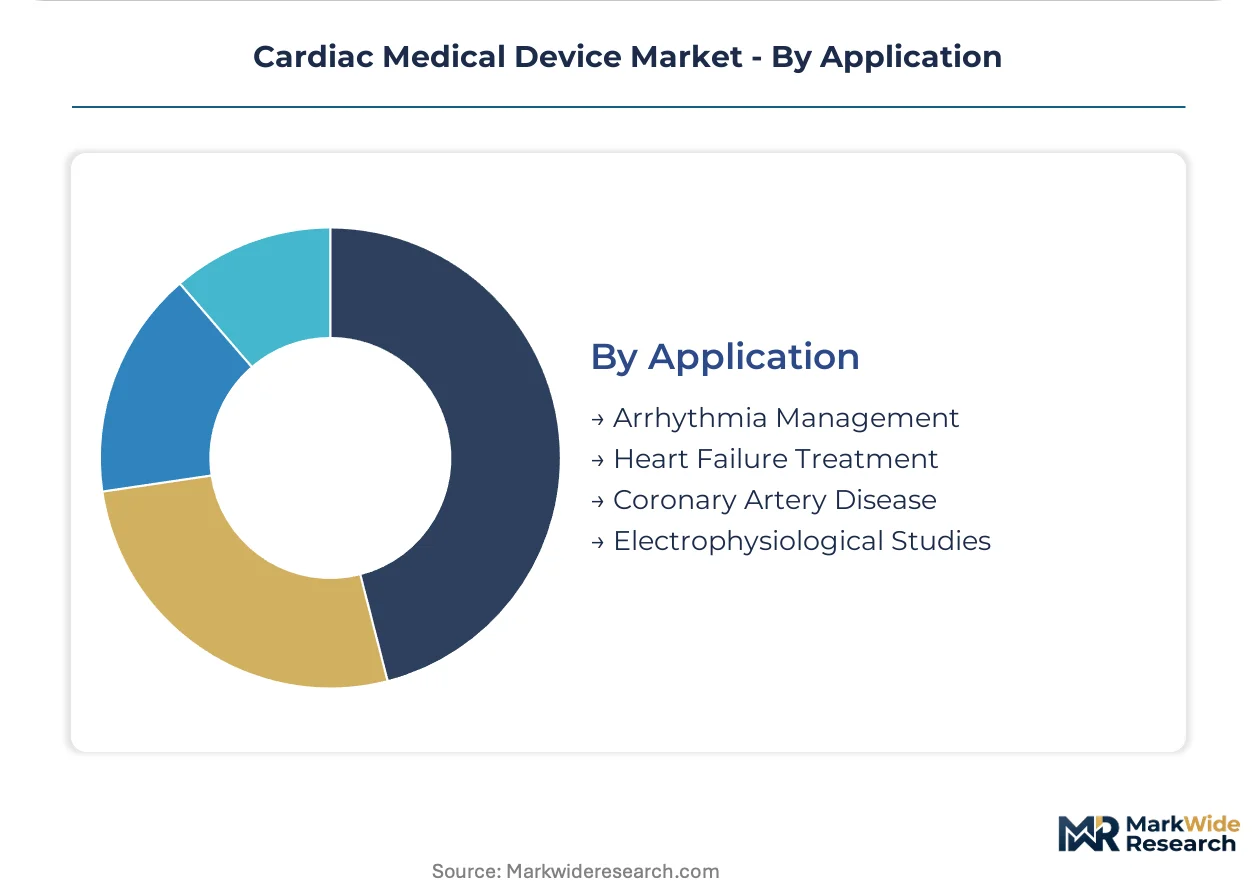
Application:
Clinical outcome metrics and procedure reimbursement rates determine device selection and technology investment priorities.
- Arrhythmia Management:Catheter ablation for atrial fibrillation employs pulsed field energy sources that selectively target myocardial tissue while sparing esophageal structures. German electrophysiology centers lead adoption of these next-generation platforms to reduce procedure complications.
- Coronary Artery Disease:Percutaneous coronary intervention with drug-coated balloons and bioresorbable scaffolds addresses diffuse vessel disease. Japanese reimbursement policy favors intravascular imaging guidance to optimize stent deployment outcomes.
- Heart Failure Treatment:Cardiac resynchronization therapy and ventricular assist devices serve declining ejection fraction patients.
- Electrophysiological Studies:Diagnostic catheter mapping precedes therapeutic ablation in complex arrhythmia cases.
Procedure volume concentrates in Coronary Artery Disease; technology innovation investment flows toward Arrhythmia Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of cardiac medical devices concentrates in the United States, Germany, and Japan, while demand expansion accelerates across hospital networks in these same markets. Production capabilities align with catheter ablation program scaling and regulatory pathway efficiency.
United States
FDA breakthrough device designations accelerate electrophysiology tool approvals, compressing commercialization timelines for novel mapping platforms. Hospital procurement committees at integrated delivery networks negotiate enterprise-wide contracts bundling capital equipment with consumables. The Cleveland Clinic and Mayo Clinic anchor demand for integrated ablation systems in the Midwest.
Germany
University hospital networks expand catheter ablation programs, creating procurement windows for force-sensing ablation catheters. EU MDR post-market surveillance mandates systematic implant registries across member states. The Rhine-Ruhr and Bavarian medical technology clusters concentrate electrophysiology platform development and clinical adoption.
Japan
PMDA maintains distinct approval pathways for cardiac rhythm devices that incentivize early launch sequencing. Academic medical centers prioritize reduced-fluoroscopy mapping protocols to minimize radiation exposure. Tokyo and Osaka metropolitan areas concentrate specialized electrophysiologist training programs and high-volume ablation centers.
India
CDSCO regulatory harmonization accelerates market entry for multinational implantable device manufacturers. Private hospital chains in metropolitan centers scale cardiac resynchronization therapy programs. The Delhi-NCR and Mumbai-Pune corridors concentrate interventional cardiology infrastructure and medical device distribution networks.
Switzerland
Swissmedic maintains stringent clinical evidence requirements for high-risk cardiac rhythm devices that filter market entrants. Precision manufacturing capabilities in the Basel-Zurich corridor support biocompatible alloy component supply. The country's medical technology cluster specializes in miniaturized pacemaker and leadless device engineering.
Cardiac Medical Device Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cardiac medical device sector. The market structure consolidates around diversified multinationals with comprehensive electrophysiology portfolios, while specialized players occupy niche technology segments. Three archetypes dominate: integrated platform vendors bundling hardware with consumables, remote monitoring service providers monetizing recurring data transmission, and wearable diagnostic specialists capturing outpatient arrhythmia detection. Competitive moves center on strategic partnerships for EMR interoperability and geographic expansion into catheter ablation program growth markets.
Among diversified multinational manufacturers, Medtronic, Abbott, and Boston Scientific Corporation occupy positions representing distinct strategic vectors. Medtronic anchors the integrated care network archetype through its established remote monitoring infrastructure. Abbott exemplifies the wireless connectivity tier with Bluetooth-enabled implantable devices transmitting directly to clinical dashboards. Boston Scientific Corporation represents the electrophysiology platform bundling model, combining mapping systems with procedure-specific consumables. These three entities collectively illustrate how hardware sales, recurring service revenue, and per-procedure consumable streams coexist within competitive positioning.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| Edwards Lifesciences Corporation |
| GE HealthCare |
| BIOTRONIK |
| Terumo Corporation |
| Johnson & Johnson |
| LivaNova |
| Others |
Supply Flow & Price Mechanics
Backward integration into biocompatible alloy component manufacturing anchors supply positions for major cardiac device producers while insulating premium pricing tiers from raw material volatility. Captive production of titanium housings and lithium-silver vanadium oxide battery cells in the United States and Switzerland concentrates cost control capabilities among integrated platform vendors.
Pricing Analysis
Margin tightening in consumable ablation catheters reflects palladium and platinum electrode cost swings that compress gross margins on per-procedure product lines. Three-tier pricing structure across premium force-sensing designs, standard irrigated catheters, and economy diagnostic tools differentiates based on technology sophistication and clinical outcome data depth. Bundled payment structures in United States hospital systems intensify cost-down pressure on manufacturers to demonstrate per-procedure efficiency. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement constraints, while German university hospitals prioritize clinical performance over unit cost.
Supply Chain Analysis
Device return and refurbishment flows for explanted pacemakers and defibrillators create reverse logistics channels that recover rare earth elements and precious metals for reprocessing. Manufacturing concentration in the United States, Germany, and Japan draws from specialized biocompatible alloy foundries and microelectronic sensor fabricators. Single-source vulnerability in force-sensing catheter tip production creates supply risk exposure for electrophysiology platform vendors. Distribution runs through hospital procurement committees at integrated delivery networks and specialized cardiovascular GPOs that consolidate volume leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiologist training pipeline constraints limit procedure volume expansion, propping pricing power for platforms that compress the learning curve through automation.
For Market Incumbents: To counter consumer-grade ECG substitution from Apple Watch and similar devices, Medtronic and Abbott should deepen software companion development for predictive arrhythmia analytics and secure exclusive EMR interoperability partnerships with Epic and Cerner. Backward integration into Bluetooth module production secures connectivity supply security. For New Entrants and Emerging Players: The mid-tier pricing gap between premium integrated mapping platforms and economy diagnostic catheters presents white-space opportunity for wireless patch monitor specialists targeting United States cardiology group practices with direct-to-clinic subscription models. India's CDSCO harmonization pathway offers regulatory entry leverage for implantable device challengers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified medtech conglomerates seeking electrophysiology platform completeness. Long-term viability over the next decade hinges on AI-integrated mapping software capabilities and remote monitoring infrastructure scale. Watch FDA breakthrough device designation velocity as inflection indicator for platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress commercialization cycles for novel ablation technologies. |
| Hospital System Partnership | Enterprise-wide contracts with United States IDNs secure multi-year consumable commitments. |
| Software Companion Development | AI-embedded arrhythmia prediction differentiates hardware platforms through predictive analytics. |
| CE Marking Pathway | MDR compliance investment maintains European market access for legacy rhythm device portfolios. |
| Reimbursement Strategy | CPT code optimization for remote monitoring subscriptions hardens recurring revenue streams. |
Methodological Framework
Document review covered FDA 510(k) filings, PMDA approval summaries, and EU MDR technical documentation, complemented by interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary sources included CMS Medicare reimbursement databases, hospital procurement records, and trade data from the Advanced Medical Technology Association. Bottom-up device shipment estimates and top-down healthcare expenditure allocations were cross-validated for triangulation.
Historical catheter ablation volume trends were cross-referenced against panel input from electrophysiology lab directors across the analysis window. Segmentation modeling incorporated product type, end user setting, technology application, and geographic regulatory cluster dimensions. CAGRs were derived from procedure volume trajectories, replacement cycle assumptions for implantable devices, and remote monitoring subscription penetration curves.
Underlying measurement precision varies by segment; wearable device shipment estimates carry tighter precision than emerging pulsed field ablation adoption curves. Forecasts reflect assumptions regarding FDA breakthrough designation velocity, EU MDR recertification timelines, and electrophysiologist fellowship slot expansion. Material deviation in palladium pricing, cybersecurity incident frequency, or consumer ECG diagnostic accuracy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Global External Ventricular Drain Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Global Ventricular Assist Device Market
Cardiovascular Devices
Endovascular Aneurysm Repair Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
Global Drug Eluting Balloon Catheters Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Dual Therapy Stent Market
Cardiovascular Devices
North America Interventional Cardiology and Peripheral Vascular Devices Market