
 Peripheral Vascular Devices Market | 2026-2036
Peripheral Vascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Vascular Devices Market Intelligence
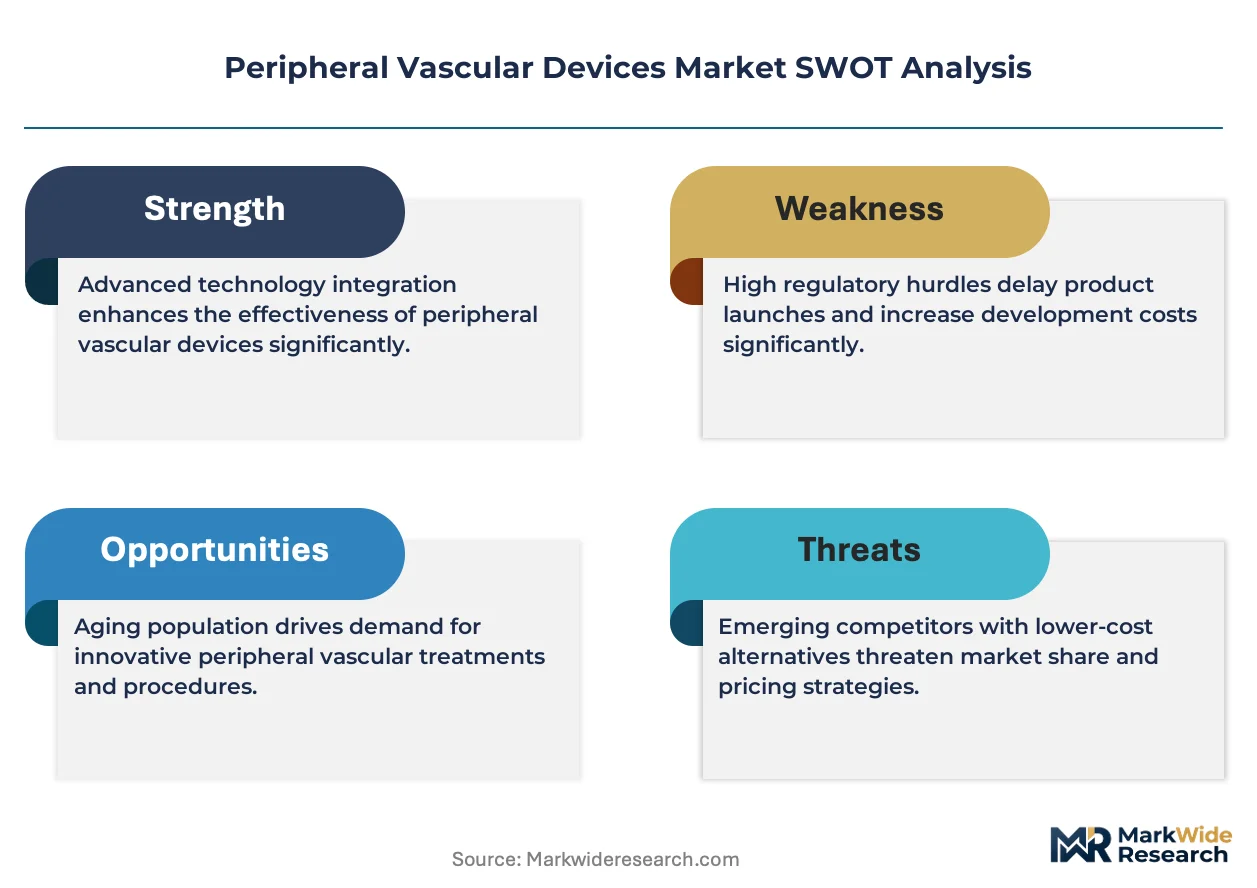
The EU Green Deal's emphasis on sustainable material lifecycles is recalibrating supply chain strategies for device manufacturers. This shift pressures companies to evaluate the environmental impact of polymers and metals used in single-use devices. Medtronic leverages its extensive R&D pipeline to develop devices with improved biocompatibility. Boston Scientific Corporation differentiates through its focus on next-generation bioresorbable stents, while Abbott sustains its market position with a broad portfolio addressing diverse peripheral artery disease complexities.
Peripheral vascular devices encompass a range of instruments designed to treat stenosis or occlusion in arteries and veins, excluding the coronary and cerebral vasculature. These devices, often made from materials like nitinol or cobalt-chromium, function to restore blood flow through techniques like angioplasty or stenting. Stents and angioplasty balloon catheters form the core product volume, while thrombectomy devices show significant growth. Treatment for peripheral artery disease constitutes the largest application segment, with procedures frequently performed in specialized cardiovascular centers.
Market access hinges on stringent regulatory approvals, with the US FDA's Premarket Approval (PMA) process and the EU's Medical Device Regulation (MDR) setting high bars for safety and efficacy. In China, the National Medical Products Administration (NMPA) mandates specific clinical trial data for device registration, shaping entry strategies for foreign firms. Navigating the divergent reimbursement policies and clinical evidence requirements across key markets remains a critical challenge for manufacturers.
Market Dynamics
The central dynamic shaping the peripheral vascular devices market is the tension between the need for advanced, high-performance materials like nitinol and the growing regulatory pressure from frameworks like the EU Green Deal demanding sustainable material lifecycles for single-use products.
Growth Catalysts
- Advancing Procedure Sites:The expansion of ambulatory surgical centers equipped for minimally invasive interventions creates new demand channels, moving procedures out of traditional hospital settings and increasing patient access.
- Demographic Pressures:Japan's super-aging population presents a concentrated source of demand for treatments related to peripheral artery disease, sustaining high procedural volumes and supporting premium device adoption.
- Material Science Innovation:Continuous improvements in polymer and metal alloys, such as cobalt-chromium and nitinol, enhance device flexibility, durability, and radiopacity, enabling physicians to treat more complex and distal lesions effectively.
Market Restraints
- Stringent Regulatory Pathways:The US FDA's Premarket Approval (PMA) process for high-risk devices involves extensive clinical data requirements and long review timelines, creating significant barriers to entry for novel technologies.
- Reimbursement Disparities:Inconsistent reimbursement policies for new device technologies across different healthcare systems, such as in various EU member states, can limit patient access and slow the adoption of clinically superior products.
- Technical Limitations:The persistent clinical challenge of in-stent restenosis and thrombosis, particularly in long or small-diameter vessel segments, remains a technical restraint that can limit the long-term effectiveness of stenting procedures.
Strategic Opportunities
- Bioresorbable Scaffolds:Next-generation bioresorbable stents and scaffolds, which dissolve after vessel healing, offer an opportunity to avoid permanent implants and address long-term complications, representing a significant area for R&D investment.
- Venous Disease Applications:There is an opportunity to expand device portfolios to better address venous disorders, such as deep vein thrombosis and chronic venous insufficiency, an application segment with significant unmet clinical needs.
- Emerging Economies:Markets in Latin America and Southeast Asia with rising healthcare expenditure and increasing prevalence of vascular disease offer substantial growth potential for manufacturers able to navigate local registration and distribution complexities.
Industry Challenges
- Post-Market Surveillance Burden:Complying with the heightened post-market surveillance and clinical follow-up requirements of the EU's Medical Device Regulation (MDR) places a substantial operational and financial burden on manufacturers.
- Supply Chain Transparency:Device makers face the challenge of re-engineering supply chains to provide the material traceability and lifecycle data mandated by new environmental regulations, impacting sourcing strategies for polymers and metals.
- Interventionalist Training Gap:The rapid evolution of complex devices, especially in thrombectomy and atherectomy, creates a challenge in ensuring an adequate number of physicians are trained to use them safely and effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Vascular Devices Market |
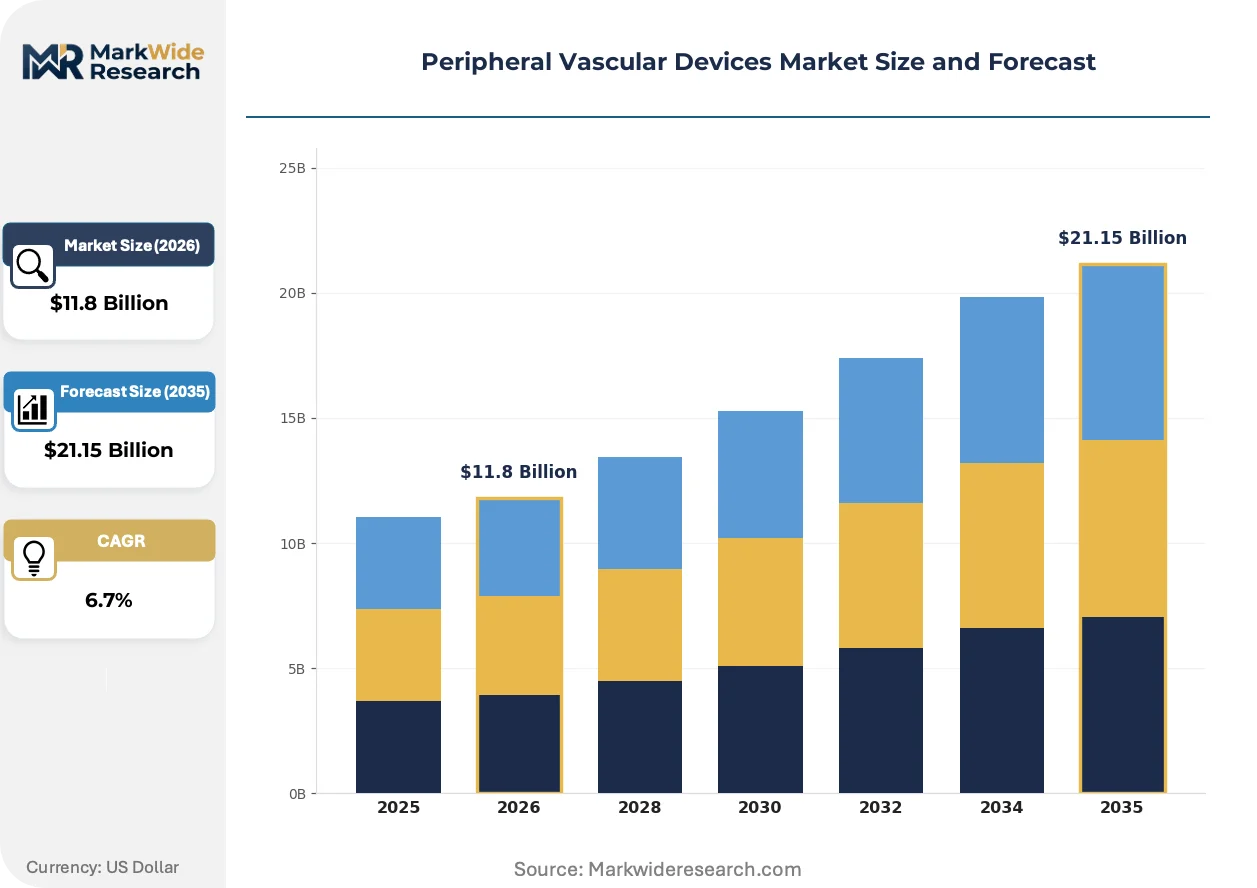
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angioplasty Balloon Catheters, Stents, Thrombectomy Devices, Embolic Protection Devices, Vascular Closure Devices Application: Peripheral Artery Disease, Varicose Vein Treatment, Deep Vein Thrombosis, Chronic Venous Insufficiency, Aneurysm Repair End User: Cardiovascular Centers, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Labs Deployment: Hospital Settings, Outpatient Facilities, Mobile Clinics, Telemedicine Platforms |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, B. Braun SE, Terumo Corporation, Edwards Lifesciences Corporation, W. L. Gore & Associates, BD, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Vascular Devices Market Strategic Shifts & Innovations
The convergence of material science with real-time data analytics is fundamentally altering interventional procedures. This integration allows for more precise and personalized treatments, moving beyond purely mechanical solutions to incorporate active feedback during device deployment and operation.
Sensor-integrated guidewires and catheters provide real-time intravascular data, such as blood flow and pressure gradients. These smart devices are being adopted by interventional radiologists and cardiologists in advanced cardiovascular centers. This technology is decentralizing clinical assessment from separate diagnostic sessions to the point of intervention, enabling immediate therapeutic adjustments within a single procedure.
China's National Medical Products Administration (NMPA) is enforcing stricter requirements for local clinical trial data before granting registration for imported medical devices. This policy directly impacts market entry timelines and costs for foreign device manufacturers. Consequently, companies targeting the Chinese market must now invest in country-specific clinical studies, affecting their global R&D and regulatory strategies, particularly for Class III devices.
A notable behavioral change is the shift in purchasing decisions from hospital-wide committees to physician-operators in office-based labs (OBLs). This trend disintermediates traditional hospital procurement channels, giving individual practitioners or small groups more direct influence over device selection. This pattern is particularly visible in the United States, where reimbursement structures favor outpatient procedures for peripheral artery disease.
Peripheral Vascular Devices Market Segmentation
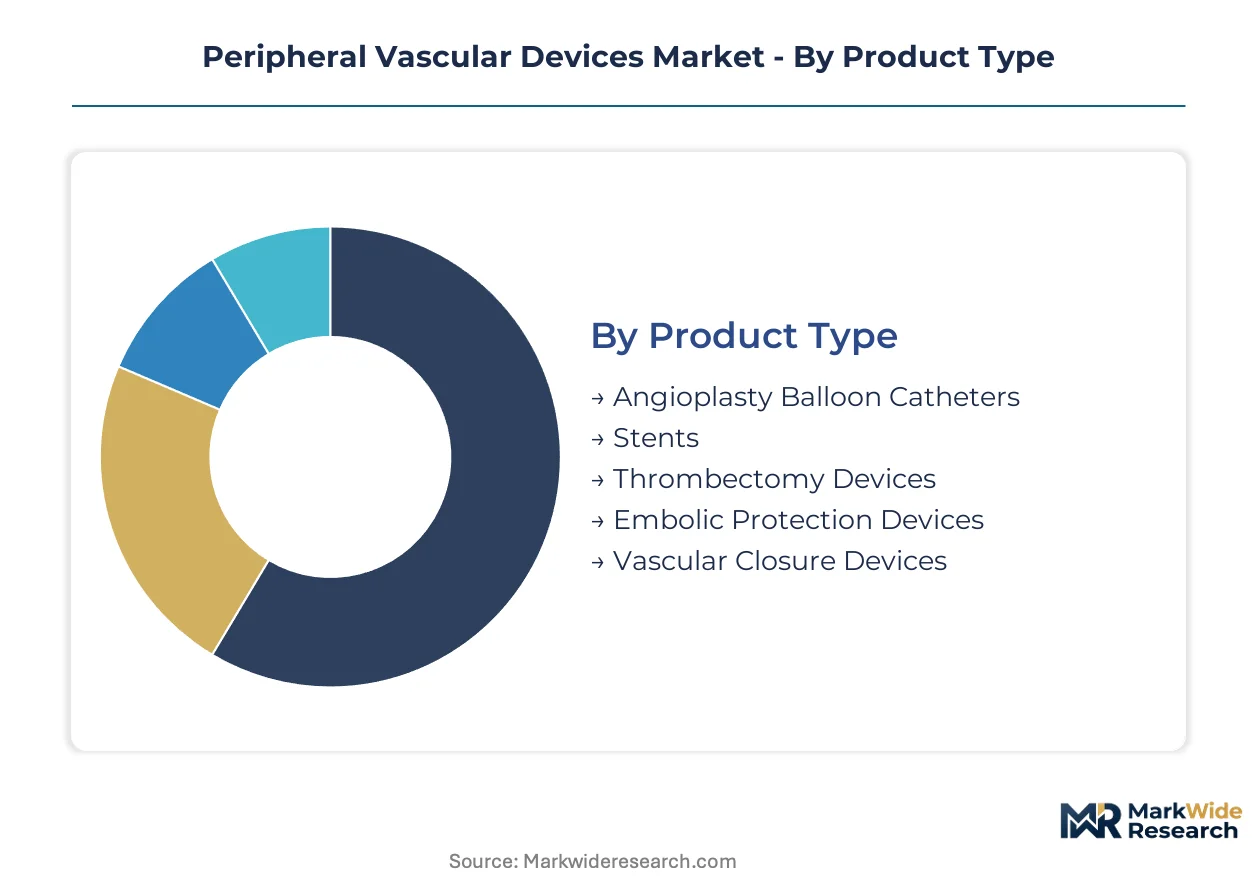
The peripheral vascular devices market is intrinsically segmented by the specific anatomical challenges and clinical objectives driving interventions. Understanding these distinct segments is crucial for manufacturers to align product development with unmet clinical needs and for healthcare providers to optimize patient outcomes across diverse vascular conditions.
Product Type:
Product selection for peripheral vascular interventions often hinges on the specific anatomical lesion and procedural goals.
- Angioplasty Balloon Catheters:These devices employ an inflatable balloon to compress plaque and widen narrowed peripheral arteries, often serving as a preparatory step for stent placement or as a standalone therapy for less calcified lesions. Demand for drug-coated balloons is rising in Europe, driven by efforts to reduce restenosis rates.
- Stents:Permanent or bioresorbable mesh tubes, typically made from nitinol or cobalt-chromium, are deployed to maintain vessel patency after angioplasty, preventing re-narrowing. The US market sees significant adoption of advanced stent designs for complex peripheral artery disease cases.
- Thrombectomy Devices:Specialized catheters designed to remove blood clots from peripheral arteries and veins, restoring immediate blood flow. These devices are witnessing rapid technological advancements, particularly in the treatment of acute limb ischemia in specialized cardiovascular centers.
- Embolic Protection Devices:Filters or occlusion balloons temporarily deployed during procedures to capture and remove emboli, preventing downstream complications like stroke or limb ischemia.
- Vascular Closure Devices:Tools used to achieve hemostasis at the vascular access site after catheter-based procedures, reducing manual compression time and improving patient comfort.
Stents lead procedural volumes today; thrombectomy devices are gaining share fastest.
Application:
The range of clinical indications dictates the specific device requirements and procedural protocols within the peripheral vascular market.
- Peripheral Artery Disease:This segment addresses the diagnosis and treatment of atherosclerotic blockages in arteries outside the heart and brain, representing the largest application for peripheral vascular devices. Procedures for peripheral artery disease are frequently performed in specialized cardiovascular centers across the US.
- Varicose Vein Treatment:Procedures targeting enlarged, twisted veins, primarily in the legs, often involving minimally invasive techniques like ablation or sclerotherapy. Demand for these devices is consistent in markets like Germany, driven by patient aesthetics and symptom relief.
- Deep Vein Thrombosis:Treatment for blood clots forming in deep veins, most commonly in the legs, often requiring thrombectomy or vena cava filters to prevent pulmonary embolism. This application segment presents significant unmet clinical needs, particularly in China's expanding healthcare landscape.
- Chronic Venous Insufficiency:Management of conditions where leg veins struggle to return blood to the heart, leading to swelling, pain, and skin changes.
- Aneurysm Repair:Surgical or endovascular repair of weakened, bulging sections in peripheral arteries, primarily using grafts or stent grafts to prevent rupture.
Peripheral Artery Disease treatments dominate the application landscape; Deep Vein Thrombosis interventions show the steepest expansion trajectory.
End User:
Procurement patterns for peripheral vascular devices vary significantly based on the end-user facility's operational model and patient volume.
- Cardiovascular Centers:Highly specialized facilities equipped for complex diagnostic and interventional procedures, housing advanced imaging and surgical capabilities. These centers represent the primary purchasers of high-end peripheral vascular devices in Japan.
- Ambulatory Surgical Centers:Outpatient facilities performing minimally invasive procedures, offering cost-effective alternatives to hospital stays. The expansion of these centers in the US is creating new demand channels for peripheral vascular devices.
- Specialty Clinics:Focused medical practices, such as vascular clinics or wound care centers, providing diagnosis and treatment for specific peripheral vascular conditions.
- Diagnostic Labs:Facilities primarily focused on imaging and functional assessments to diagnose peripheral vascular diseases, guiding treatment decisions.
Cardiovascular Centers represent the primary point of care; Ambulatory Surgical Centers are increasingly influencing device selection.
Deployment:
The operational maturity and technological infrastructure of deployment sites influence the types of peripheral vascular procedures performed.
- Hospital Settings:Traditional inpatient facilities offering a full spectrum of care, from emergency interventions to complex surgical procedures. Hospitals remain the core environment for high-acuity peripheral vascular cases globally.
- Outpatient Facilities:Settings where patients receive care without an overnight stay, including ambulatory surgical centers and dedicated clinics. This trend is driven by favorable reimbursement policies in the US for peripheral artery disease procedures.
- Mobile Clinics:Healthcare units on wheels providing diagnostic screenings and basic treatments in underserved or remote areas.
- Telemedicine Platforms:Virtual care solutions offering remote consultations and follow-up for chronic peripheral vascular conditions.
Hospital Settings remain the core deployment environment; Outpatient Facilities are expanding their procedural capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The peripheral vascular devices industry historically scaled within established healthcare systems, particularly in North America and Western Europe, where early innovations in interventional cardiology and angiography provided foundational technologies. These regions developed robust regulatory frameworks and specialized medical infrastructure, fostering initial market expansion.
United States
Demand for peripheral vascular devices in the United States is driven by a high prevalence of peripheral artery disease and an expanding network of ambulatory surgical centers. The US FDA's Premarket Approval (PMA) process sets stringent safety and efficacy standards for novel devices. Major medical device clusters in California and Massachusetts foster intense R&D and manufacturing activities.
Japan
Japan's super-aging population creates a concentrated source of demand for peripheral vascular interventions, particularly for treatments addressing age-related vascular conditions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing clinical data requirements. Tokyo and Osaka serve as key hubs for medical device innovation and distribution within the country.
Germany
Germany represents a significant European market for peripheral vascular devices, supported by its advanced healthcare infrastructure and high adoption rates of sophisticated medical technologies. Compliance with the EU's Medical Device Regulation (MDR) is critical for market access and post-market surveillance. The Bavaria region, particularly around Munich, hosts numerous medical technology companies and research institutions.
China
The Chinese market for peripheral vascular devices is expanding rapidly, fueled by a growing patient pool and increasing healthcare expenditure. The National Medical Products Administration (NMPA) mandates local clinical trial data for device registration, influencing market entry strategies for foreign firms. Shanghai and Beijing are central to medical device manufacturing and clinical research activities.
France
France shows consistent demand for peripheral vascular devices, with a focus on advanced angioplasty and stenting techniques within its public and private healthcare systems. The EU Green Deal's emphasis on sustainable material lifecycles is influencing product design and supply chain recalibration for French manufacturers. The Lyon region is a notable center for medical device production and cardiovascular research.
Peripheral Vascular Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure for peripheral vascular devices. This market sees large, diversified medical technology companies alongside specialized innovators. Strategic archetypes include broad portfolio providers, technology specialists, and regional market leaders. Dominant competitive moves involve portfolio diversification and strategic partnerships to access new technologies or markets.
Among the established, diversified medical technology corporations, Medtronic and Boston Scientific Corporation exemplify companies with extensive R&D pipelines and broad product portfolios. Abbott, another significant player, sustains its market position by addressing diverse peripheral artery disease complexities across its wide range of offerings. These companies often leverage their global distribution networks and deep clinical relationships to maintain their market presence.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| B. Braun SE |
| Terumo Corporation |
| Edwards Lifesciences Corporation |
| W. L. Gore & Associates |
| BD |
| Cook Medical |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's emphasis on sustainable material lifecycles gates both qualified supply and premium-tier pricing access for peripheral vascular devices. This mandate pressures manufacturers to evaluate the environmental impact of polymers and metals, influencing product costs and market entry strategies.
Pricing Analysis
Value-based pricing models dominate the peripheral vascular devices market, driven by clinical efficacy and stringent regulatory approvals. Price differentiation stems from advanced material science innovations like bioresorbable stents and the extensive clinical evidence supporting device safety. Pricing pressure stems from inconsistent reimbursement policies across EU member states, limiting market access for novel technologies. Ambulatory surgical centers exhibit higher price sensitivity compared to specialized cardiovascular centers.
Supply Chain Analysis
Stringent regulatory qualifications, including the US FDA's PMA process and the EU's MDR, gate the supply of high-performance peripheral vascular devices. Supply concentration for advanced components like nitinol and cobalt-chromium is noted in specialized manufacturing hubs in the United States and Germany. The supply chain relies on critical raw materials such as medical-grade polymers and specialized metal alloys. Regulatory restrictions, particularly NMPA requirements for local clinical trials in China, represent a structural risk. Distribution runs through direct sales channels to cardiovascular centers and specialized distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peripheral vascular devices market acts as a stable compounder, with demographic pressures from super-aging populations driving consistent long-term demand for interventional treatments.
For Market Incumbents:Acquire specialized R&D capabilities in bioresorbable scaffolds to mitigate the long-term complication threat of in-stent restenosis. Diversify product portfolios to address unmet needs in venous disease applications, leveraging existing global distribution networks. Invest in localized clinical trial infrastructure, particularly in markets like China, to navigate stringent NMPA regulatory pathways. Medtronic and Abbott can utilize their extensive R&D pipelines as a key lever against emerging technological threats.
For New Entrants and Emerging Players:Digital-first training platforms offer a scalable go-to-market angle for novel thrombectomy devices, addressing the interventionalist training gap. Target the underpenetrated deep vein thrombosis application segment in emerging economies like Southeast Asia, focusing on cost-effective, minimally invasive solutions. Develop devices specifically for office-based labs in the United States, where physician-operators directly influence device selection. Pursue strategic partnerships with local distributors to navigate complex market access and reimbursement landscapes.
For Investors and Strategic Acquirers:Roll-up economics work for specialized medical device innovators because structural fragmentation exists across niche product categories and regional markets. Long-term viability is sustained by the increasing prevalence of peripheral artery disease and continuous material science advancements over the next decade. Acquisition targets include companies with established NMPA approvals or proprietary bioresorbable stent technologies. A key signal to watch is the successful long-term clinical outcomes of next-generation bioresorbable devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bioresorbable Stents | Boston Scientific Corporation can reduce long-term complications and expand treatment options for peripheral artery disease patients. |
| Expand Venous Disease Portfolio | Abbott can address significant unmet clinical needs in deep vein thrombosis and chronic venous insufficiency. |
| Invest in Localized Clinical Trials | Foreign firms can accelerate market entry and NMPA registration for Class III devices in China. |
| Enhance Physician Training Programs | Manufacturers can ensure safe and effective adoption of complex thrombectomy and atherectomy devices. |
| Strengthen Supply Chain Transparency | Companies can comply with EU Green Deal mandates for material lifecycle data and sustainable sourcing strategies. |
Research Approach
Bottom-up end-user adoption modeling reconciled against top-down device shipment tracking forms the analytical core for this study. The approach combines insights from primary interviews with interventional radiologists, hospital procurement managers, device R&D leads, and regulatory affairs specialists. Secondary validation draws from US FDA filings, EU MDR documentation, NMPA guidelines, and clinical trial registries, ensuring robust data triangulation.
An input-output matrix frames the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, application, end user, deployment, and key material compositions. Compound annual growth rates are derived from historical trends and projected adoption rates, integrating inputs like prevalence rates of peripheral artery disease and expansion of ambulatory surgical centers.
Regulatory shifts, material science breakthroughs, and evolving reimbursement policies are the dominant revision risks for market projections. Forecasts reflect assumptions documented through extensive primary and secondary research. A model refresh is warranted upon material change in global healthcare spending or major clinical guideline updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Intravascular Ultrasound Market
Cardiovascular Devices
China Vascular Grafts Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Global Arterial Stents Market
Cardiovascular Devices
Catheter-Directed Thrombolysis Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market