
 Global 3D Ultrasound Market | 2026-2036
Global 3D Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Ultrasound Market Intelligence
The direct sales channel for large hospital procurement is narrowing as group purchasing organizations consolidate buying power across health systems. GE Healthcare leverages its established relationships and extensive service contracts to maintain its position within these large networks. Siemens Healthineers differentiates through its syngo Virtual Cockpit, enabling remote scanning support on its advanced cart-based systems. Meanwhile, Samsung Medison competes aggressively on price-performance, particularly targeting private clinics in the obstetrics and gynecology segment.
3D ultrasound is a medical imaging modality using sound waves to reconstruct three-dimensional images of internal anatomy from a volumetric dataset. This technique enables post-acquisition analysis of anatomical planes and provides detailed surface rendering. Cart-based systems command the largest revenue share, while handheld devices are the fastest-growing product type for point-of-care use. Obstetrics & gynecology is the dominant application, though cardiology increasingly adopts 4D imaging for cardiac function assessment.
Market access requires adherence to stringent regulations, including the FDA's 510(k) clearance in the United States and the EU's Medical Device Regulation (MDR). In China, devices must receive NMPA approval, which often necessitates local clinical trials and compliance with specific GB standards. Navigating the evolving rules for AI-enabled diagnostic software and data privacy remains a critical challenge for all manufacturers.
Market Dynamics
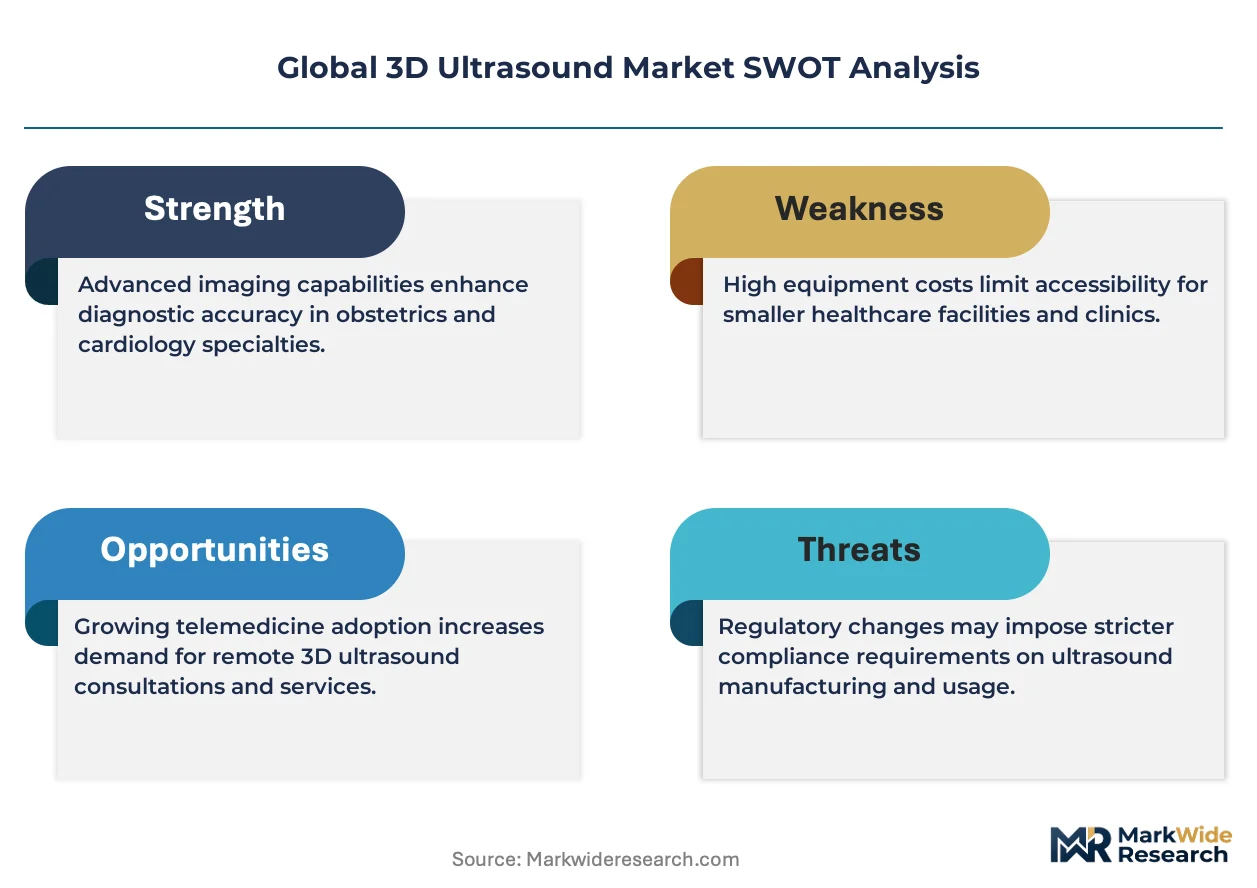
The market's central dynamic is the tension between the clinical demand for higher diagnostic fidelity in fetal and cardiac imaging and the increasing regulatory complexity governing AI-powered analytical software, which is becoming integral to system functionality.
Growth Catalysts
- AI-Powered Automation:The integration of artificial intelligence algorithms to automate fetal biometry, organ recognition, and image optimization significantly reduces scan times and improves diagnostic consistency, driving adoption in high-volume obstetrics departments.
- Cardiology Application Expansion:Increasing clinical use of 4D ultrasound for real-time assessment of cardiac valve function and ventricular wall motion provides a non-invasive alternative to other imaging techniques, creating new growth avenues beyond obstetrics. -
- Modernizing Healthcare Networks:Rapid infrastructure upgrades within hospital systems and private clinics in emerging economies, particularly in Brazil and parts of Southeast Asia, create consistent demand for advanced imaging equipment like 3D ultrasound.
Market Restraints
- High System Costs:The substantial capital investment required for premium cart-based 3D/4D ultrasound systems remains a significant barrier for smaller healthcare facilities, private practices, and hospitals in budget-constrained regions.
- Technical Skill Requirements:Effective operation of advanced 3D imaging and post-processing tools requires specialized training, and a shortage of highly skilled sonographers can limit the utility and adoption of these sophisticated systems.
- Regulatory Approval Timelines:Navigating the stringent and often lengthy device clearance processes, such as the FDA's 510(k) pathway and the EU's Medical Device Regulation (MDR), delays market entry for new technologies and software updates.
Strategic Opportunities
- Point-of-Care Handheld Devices:Developing affordable, portable 3D handheld ultrasound systems creates an opportunity to expand usage into new settings like emergency medicine, critical care, and primary care offices for rapid diagnostics.
- Interventional Guidance:There is a significant opportunity to expand the use of real-time 3D ultrasound for guiding minimally invasive procedures, including biopsies, ablations, and catheter placements, improving accuracy and patient safety.
- Tele-Ultrasound Platforms:The development of platforms enabling remote expert guidance for sonographers in rural or underserved areas can address skill gaps and improve diagnostic quality, opening a service-based revenue model.
Industry Challenges
- Data Interoperability:Ensuring seamless integration of 3D ultrasound systems and their associated AI software with existing hospital IT infrastructure, including diverse PACS and EHR systems, remains a persistent operational hurdle for vendors.
- Cybersecurity and Data Privacy:Protecting sensitive patient data on networked ultrasound systems and cloud-based analysis platforms against cyber threats while complying with regulations like HIPAA and GDPR is a critical and complex challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Ultrasound Market |
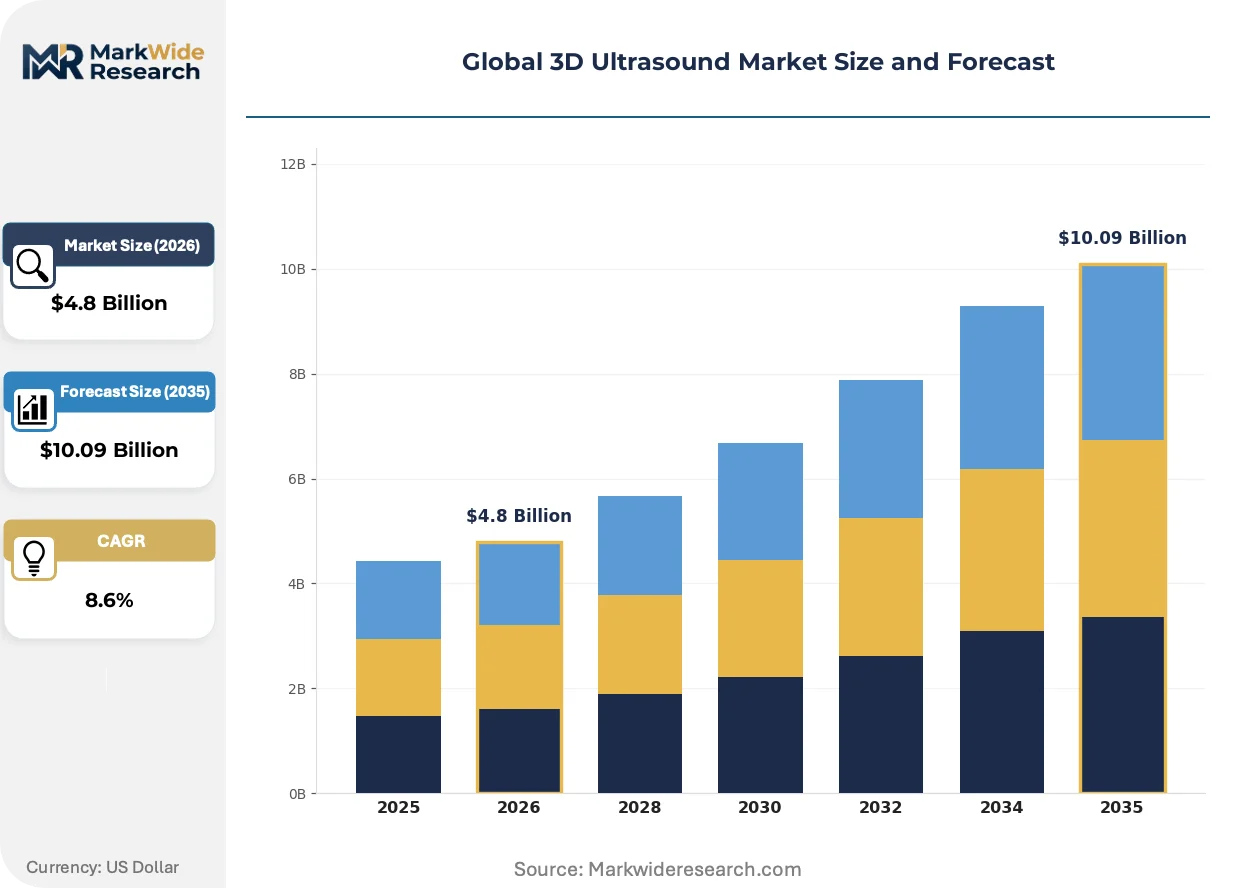
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cart-Based Systems, Handheld Devices, Portable Units, Stationary Machines Technology: Doppler Imaging, Volumetric Imaging, Contrast-Enhanced Ultrasound, Elastography Application: Obstetrics & Gynecology, Cardiology, Musculoskeletal, Urology End User: Diagnostic Centers, Ambulatory Care, Radiology Clinics, Academic Institutions |
| Companies Covered | Canon Medical Systems, Samsung Medison, GE Healthcare, Hitachi Healthcare, Fujifilm, Philips Healthcare, Mindray, Clarius Mobile Health, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Ultrasound Market Strategic Shifts & Innovations
The evolution of 3D ultrasound is defined by a pivot from hardware performance to software-driven capabilities. This shift prioritizes workflow efficiency, remote access, and automated diagnostic insights, reshaping the value proposition for clinicians and healthcare administrators alike.
Remote scanning support platforms allow expert sonographers to guide or control ultrasound examinations from a separate location using high-speed connectivity. Hospital networks and teleradiology service providers are adopting this technology to standardize imaging protocols and mitigate shortages of specialized staff. This capability is virtualizing the physical presence of expert operators, enabling centralized clinical expertise to support multiple decentralized scanning sites.
Regulatory bodies worldwide, including the FDA in the United States and competent authorities under the EU AI Act, are formalizing rules for software as a medical device. This action imposes rigorous requirements for algorithmic transparency, clinical validation, and lifecycle management on manufacturers. The AI-powered diagnostic software segment is most impacted, forcing vendors to invest in robust data governance and post-market surveillance to maintain compliance.
A clear transition from traditional capital expenditure models toward more flexible, subscription-based access is underway for advanced features. This model displaces the one-time sale by allowing clinics to pay for specific AI analysis tools or software upgrades through recurring fees. The trend is most visible among private obstetrics and gynecology clinics seeking access to premium technology without a prohibitive upfront investment.
Global 3D Ultrasound Market Segmentation
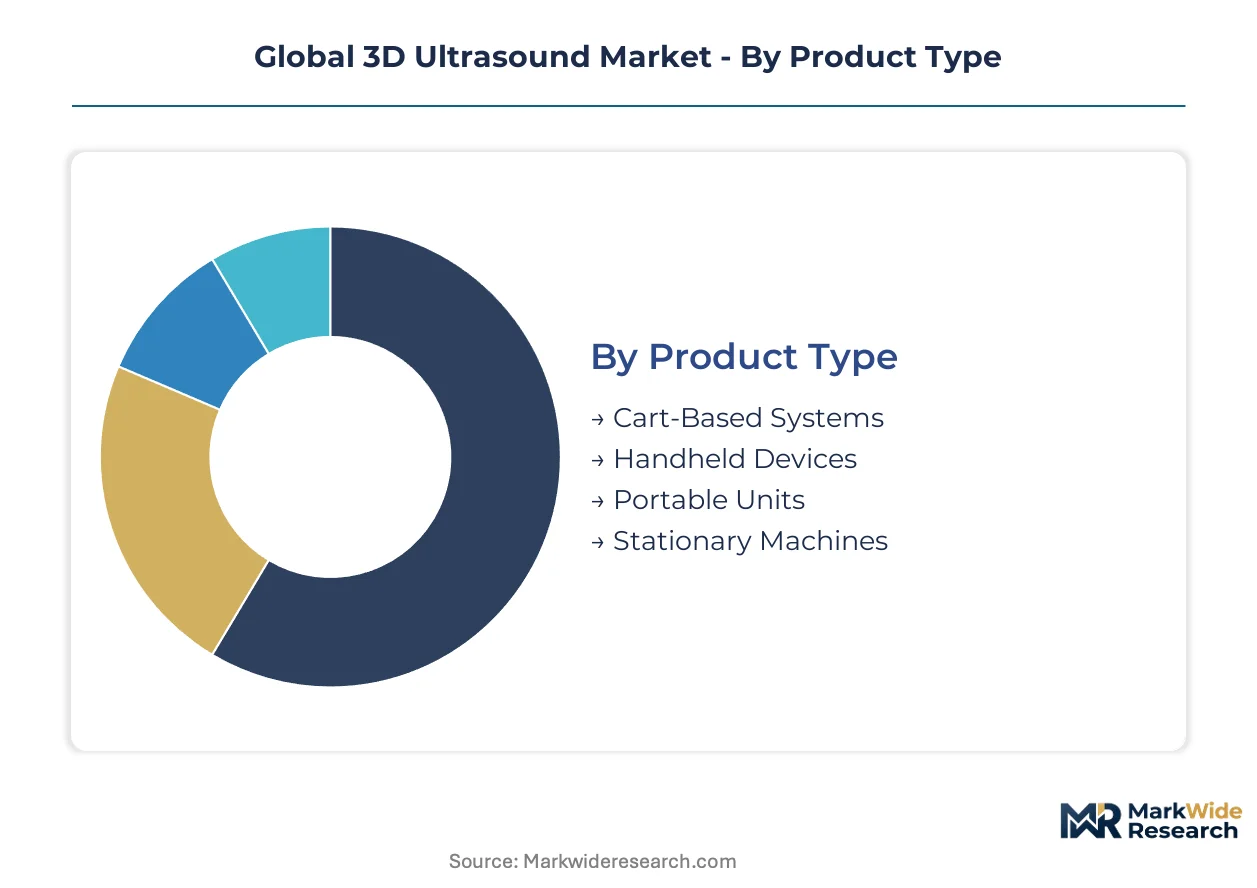
The global 3D ultrasound market is analyzed across various dimensions to understand specific demand patterns and technological preferences. This segmentation highlights how product characteristics and application areas drive adoption across different clinical settings. Understanding these segments is crucial for manufacturers targeting specific healthcare provider needs and geographic markets.
Product Type:
The product type spectrum ranges from high-throughput systems for specialized departments to portable solutions for rapid diagnostics.
- Cart-Based Systems:These comprehensive units offer advanced imaging capabilities, multiple transducer ports, and integrated processing power for detailed volumetric data acquisition. Demand for these systems remains high in large hospital networks due to their diagnostic fidelity and extensive service contracts.
- Handheld Devices:Compact and lightweight, these devices provide basic 3D imaging for quick assessments and point-of-care applications, often connecting to mobile platforms. Their rapid expansion is observed in emergency medicine and primary care settings due to affordability and ease of use.
- Portable Units:These systems offer a balance between mobility and diagnostic capability, suitable for smaller clinics and mobile healthcare services.
- Stationary Machines:Dedicated systems typically found in specialized imaging centers, providing robust performance for complex diagnostic procedures.
Established volume favors Cart-Based Systems; emerging adoption favors Handheld Devices.
Technology:
Functional capabilities define the technological segmentation, enabling diverse diagnostic approaches from real-time visualization to tissue characterization.
- Volumetric Imaging:This core technology captures 3D datasets, allowing for multi-planar reconstruction and detailed surface rendering of anatomical structures post-acquisition. Its utility is paramount in fetal anomaly detection and complex cardiac assessment, requiring sophisticated image processing.
- Doppler Imaging:Utilizing the Doppler effect, this technique measures blood flow direction and velocity, essential for assessing vascular health and cardiac function. Clinical demand is strong in cardiology and vascular surgery for non-invasive hemodynamic evaluations.
- Contrast-Enhanced Ultrasound:This method uses microbubble contrast agents to improve visualization of blood flow in tissues and organs, enhancing diagnostic accuracy in oncology and liver studies.
- Elastography:Employing sound waves to measure tissue stiffness, elastography assists in differentiating benign from malignant lesions, particularly in liver and breast imaging.
The most advanced capabilities are found in Volumetric Imaging; foundational imaging relies on Doppler Imaging.
Application:
The market's application landscape addresses specific patient cohorts and diagnostic requirements across various medical specialties.
- Obstetrics & Gynecology:This segment dominates 3D ultrasound usage, providing detailed visualization of fetal development, placental assessment, and gynecological pathology. Demand is particularly high for early and accurate detection of congenital anomalies and monitoring pregnancy progression.
- Cardiology:Increasingly leveraging 4D ultrasound, this application supports real-time assessment of cardiac chamber function, valve dynamics, and blood flow patterns. Its expansion is driven by the need for non-invasive, comprehensive evaluation of heart disease.
- Musculoskeletal:Ultrasound aids in diagnosing soft tissue injuries, joint inflammation, and guiding interventional procedures in orthopedics and sports medicine.
- Urology:Used for imaging the kidneys, bladder, and prostate, this application assists in detecting stones, tumors, and assessing urinary tract conditions.
Primary diagnostic demand centers on Obstetrics & Gynecology; expanding clinical utility drives Cardiology.
End User:
Operational scale and specialized diagnostic needs differentiate end-user segments, influencing procurement and technology adoption.
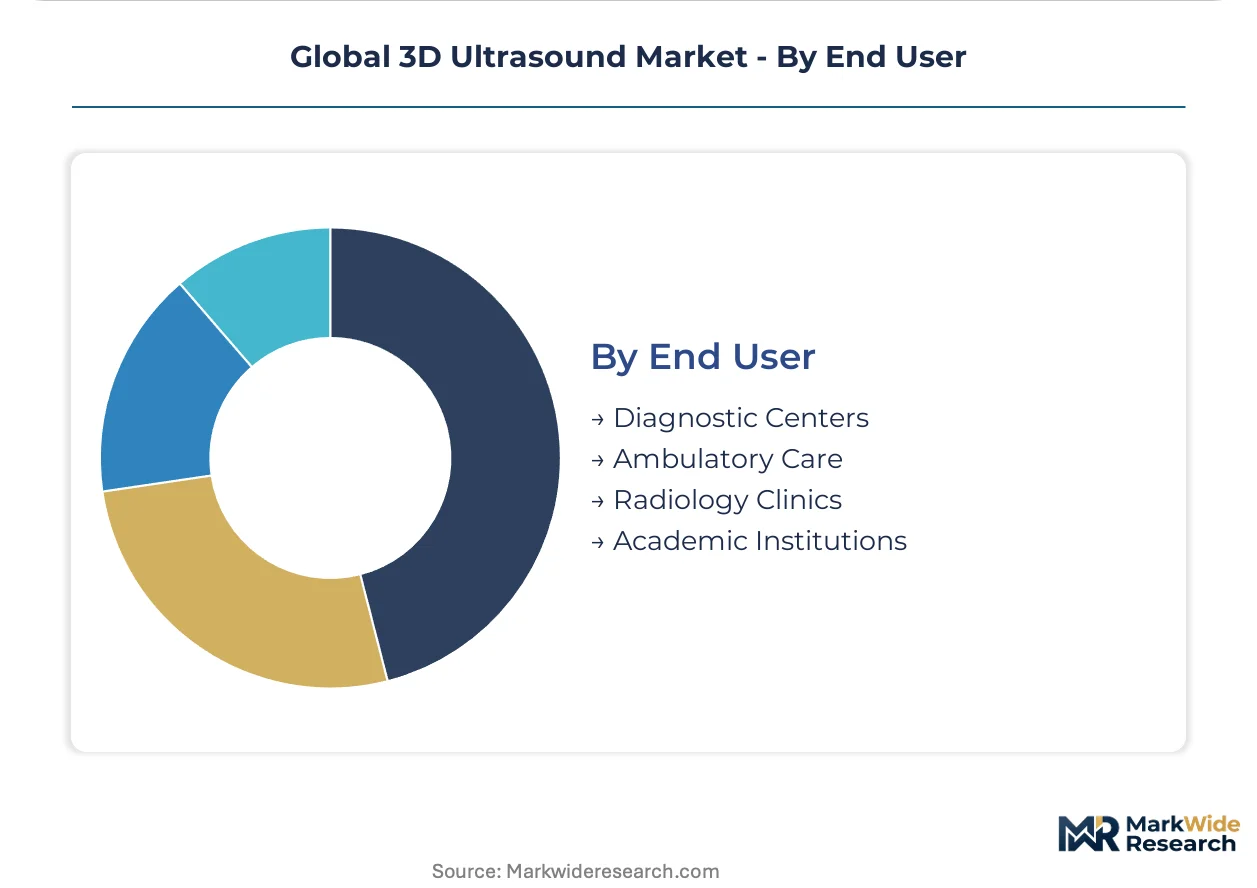
- Diagnostic Centers:These facilities specialize in providing a wide range of imaging services, including advanced 3D ultrasound, serving both referred patients and walk-ins. Their adoption is driven by the need for high-throughput systems and specialized diagnostic capabilities.
- Ambulatory Care:Including private clinics and outpatient facilities, this segment utilizes 3D ultrasound for routine check-ups, follow-up diagnostics, and point-of-care examinations. The focus here is on cost-effectiveness and ease of integration into existing clinical workflows.
- Radiology Clinics:Offering specialized diagnostic imaging, these clinics often invest in high-end ultrasound systems for complex cases and expert interpretations.
- Academic Institutions:Universities and teaching hospitals use 3D ultrasound for medical education, clinical research, and advanced patient care, driving innovation in imaging protocols.
Large-scale diagnostic services are primarily handled by Diagnostic Centers; decentralized care models are increasingly served by Ambulatory Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry is evident between developed and emerging markets for 3D ultrasound systems. North American and European markets support premium pricing for advanced features and service contracts. Conversely, manufacturers in rapidly expanding economies like China and Brazil face pressure to offer competitive price-performance ratios.
United States
Demand for advanced 3D ultrasound systems stems from a focus on early fetal anomaly detection and comprehensive cardiac assessment. The FDA's 510(k) clearance process rigorously regulates new device introductions into the market. Major medical technology hubs like Boston and Silicon Valley drive innovation in AI-powered imaging software development.
China
Modernizing hospital networks and private clinics in China drive substantial demand for 3D ultrasound equipment, particularly for obstetrics and gynecology. NMPA approval, often requiring local clinical trials, governs market access for foreign manufacturers. Manufacturing centers in Shenzhen and Shanghai are developing localized imaging solutions for domestic and regional markets.
Brazil
Private clinics in Brazil exhibit strong demand for cost-effective 3D ultrasound solutions, particularly in obstetrics and gynecology. ANVISA regulations ensure device safety and efficacy before market entry across the country. Sao Paulo and Rio de Janeiro serve as key distribution and clinical training centers for advanced imaging technologies.
Germany
High diagnostic fidelity and integrated AI algorithms stimulate demand for premium 3D ultrasound systems across German hospitals. The EU's Medical Device Regulation (MDR) imposes strict requirements for device certification and post-market surveillance. Research institutions in Erlangen and Aachen advance new ultrasound technologies and clinical applications.
Japan
Demand for high-precision 3D ultrasound imaging in Japan focuses on early disease detection and advanced therapeutic guidance. The PMDA oversees medical device approvals, emphasizing clinical safety and performance standards. Tokyo's medical device cluster fosters collaboration between manufacturers and academic hospitals for new imaging protocols.
Global 3D Ultrasound Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing transducers and software modules. The 3D ultrasound market exhibits a tiered structure, with a few global conglomerates dominating the premium segment and numerous smaller players competing in specialized niches. Strategic archetypes include full-suite medical imaging providers, focused point-of-care device manufacturers, and software-centric solution developers. Portfolio diversification and strategic partnerships are dominant competitive moves among these diverse players.
Within the full-suite medical imaging provider archetype, GE Healthcare and Siemens Healthineers exemplify established market presence and extensive service networks across large hospital systems. Samsung Medison, a South Korean company, occupies a position emphasizing price-performance in specific segments like obstetrics and gynecology, particularly targeting private clinics. These companies leverage their global footprints and R&D capabilities to maintain their competitive edge. Their offerings often integrate advanced AI features and remote support functionalities to enhance diagnostic workflows and user experience.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Samsung Medison |
| GE Healthcare |
| Hitachi Healthcare |
| Fujifilm |
| Philips Healthcare |
| Mindray |
| Clarius Mobile Health |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Underutilization of advanced 3D ultrasound systems in some budget-constrained regions drives supplier behavior towards flexible financing models and competitive pricing. This utilization rate directly influences equipment manufacturing volumes and market entry strategies for new technologies.
Pricing Analysis
Configured-to-order pricing for premium cart-based systems contrasts with standard pricing for handheld devices. The dominant pricing structure combines transactional sales for hardware with subscription-based models for advanced AI analysis tools and software upgrades. Price differentiation stems from brand premium, after-sales service contracts, and the level of integrated AI features. Pricing softness reflects intense competition from price-performance focused manufacturers, particularly in emerging markets. Private clinics in Brazil demonstrate high price sensitivity, while large hospital networks in Germany prioritize diagnostic fidelity and comprehensive service bundles.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming crucial for manufacturers supporting hospital procurement in emerging economies. Geographic supply concentration for critical components like transducers and imaging processors centers on manufacturing hubs in China, South Korea, and Japan. Raw material dependencies include specialized ceramics for transducers and advanced semiconductors for processing units. Logistics chokepoints and geopolitical trade tensions represent a structural supply chain risk. Distribution runs through direct sales channels for major hospital systems and established distributor networks for smaller clinics and handheld device markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market faces a capability gap, specifically a shortage of highly skilled sonographers capable of operating advanced 3D ultrasound systems and interpreting complex volumetric data.
For Market Incumbents:Build ecosystem lock-in by deepening integration capabilities with existing hospital IT infrastructure, including PACS and EHR systems. Expand comprehensive service contracts and remote support platforms to mitigate technical skill requirements. Aggressive price-performance competitors from Asia pose a significant threat. Investing in AI-powered automation for image acquisition and analysis serves as a critical lever to enhance workflow efficiency and diagnostic consistency.
For New Entrants and Emerging Players:Establish a beachhead in the rapidly expanding point-of-care diagnostics segment with affordable handheld devices. Target private clinics in emerging economies like Brazil and Southeast Asia, where underpenetration of advanced imaging equipment is high. The most penetrable segment involves basic 3D imaging for primary care and emergency medicine. A compelling go-to-market angle involves offering subscription-based access to essential 3D imaging features coupled with mobile connectivity.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among software-centric solution developers offering AI-powered diagnostic tools and tele-ultrasound platforms. Long-term viability hinges on the sustained clinical demand for non-invasive, high-fidelity imaging solutions. Acquisition targets should include niche AI software companies specializing in fetal biometry or cardiac assessment, and providers of remote expert guidance platforms. Rapid NMPA or FDA approvals for AI-enabled diagnostic software should be a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Diagnostic Modules | Enhances diagnostic accuracy and reduces scan times, attracting high-volume obstetrics departments. |
| Expand Tele-Ultrasound Platform Offerings | Addresses sonographer skill gaps and improves access to expert interpretation in underserved areas. |
| Secure Key Component Supply Agreements | Mitigates supply chain risks and ensures consistent production of advanced imaging systems. |
| Pursue Targeted Acquisitions of Software Startups | Integrates specialized AI capabilities and accelerates product development in niche applications. |
| Invest in Point-of-Care Device R&D | Captures new market segments in emergency medicine and primary care with portable solutions. |
Research Approach
The analysis maps cart-based systems, handheld devices, obstetrics & gynecology applications, and cardiology applications, each validated through extensive primary interviews with hospital procurement managers and sonographers. This approach combines insights from radiology department heads and medical device engineers with secondary data from FDA 510(k) clearances, EU MDR certification databases, NMPA approval records, and academic clinical trial publications, ensuring both bottom-up and top-down triangulation.
Assumptions regarding healthcare expenditure growth and regulatory approval rates for AI-enabled software were held fixed across the analysis window, while adoption rates of handheld devices were varied. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, geographic region, and the level of AI integration. Compound annual growth rates were derived through a comprehensive regression analysis, utilizing industry-specific forecast inputs such as the per capita healthcare spending and the number of new clinic establishments.
Stress conditions across regulatory changes, component supply disruptions, and shifts in healthcare policy were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions, but specific risk factors like new competitive entrants or unforeseen technological breakthroughs could prompt revision. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
United States Diagnostic Imaging Market