
 Pcb Laminate Materials Market | 2026-2036
Pcb Laminate Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Pcb Laminate Materials Market Analysis
The EU RoHS directive is pivoting laminate demand toward halogen-free and low-Dk/Df formulations. Kingboard Laminates Holdings Ltd. leverages its integrated copper-cladding capacity to dominate cost-sensitive supply tiers. Shengyi Technology Co., Ltd. anchors the high-frequency segment through specialized resin systems for 5G infrastructure. Panasonic Holdings Corporation differentiates via proprietary thermally conductive fillers that sustain performance at elevated operating temperatures.
PCB laminate materials are composite substrates—typically woven glass fiber impregnated with epoxy, polyimide, or PTFE resin systems—that provide mechanical support and electrical insulation for printed circuit board fabrication, with critical parameters including glass transition temperature (Tg), dielectric constant (Dk), and dissipation factor (Df) determining signal integrity and thermal reliability. Epoxy laminates occupy the highest volume tier due to mature supply chains and cost efficiency in consumer electronics, while PTFE formulations command premium positioning in aerospace equipment and telecommunications where ultra-low signal loss justifies material costs. Multi-layer form factors are expanding fastest as advanced packaging and high-density interconnect designs proliferate across automotive components and medical devices.
REACH in Europe, China's GB standards administered by SAMR, and the EPA's TSCA framework in the US collectively restrict brominated flame retardants and mandate traceability in resin chemistry, compelling reformulation investments across all major supply bases. The EU F-Gas Regulation and Japan's METI energy-efficiency benchmarks further constrain material choices in high-performance segments. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance-driven specification changes before they disrupt qualification cycles.
Market Dynamics
EV thermal management requirements are forcing laminate suppliers to reformulate resin systems for sustained operation above 150°C, compressing qualification cycles and fragmenting material specifications across automotive tiers.
Growth Catalysts
- EU RoHS Directive:Halogen-free mandates in European electronics manufacturing are accelerating material transitions toward phosphorus-nitrogen flame retardant systems, opening specification windows for compliant suppliers.
- 5G Infrastructure Deployment:Base station and antenna manufacturers require ultra-low Dk/Df laminates for millimeter-wave signal integrity, pulling specialized PTFE and modified epoxy formulations into volume production.
- China's Dual Carbon Goals:SAMR-administered GB standards on embodied carbon are redirecting procurement toward domestic suppliers with verified low-carbon resin chemistry and renewable energy-powered curing operations.
Market Restraints
- Copper Foil Supply Concentration:Electrodeposited copper foil production clusters in East Asian manufacturing hubs, exposing laminate fabricators to price volatility and allocation risk during semiconductor cycle peaks.
- High-Frequency Material Cost Structure:PTFE resin systems require fluoropolymer feedstocks subject to EU F-Gas Regulation restrictions, compressing margins for telecommunications-grade laminates.
- Glass Fiber Technical Limitation:Standard E-glass weave architectures introduce signal loss at frequencies above 10 GHz, constraining laminate performance in 5G mmWave and satellite communication applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor and component fabrication are attracting laminate qualification programs for domestic PCB producers serving automotive and industrial automation.
- Embedded Die Packaging:Convergence of laminate substrates with chip-embedding processes enables system-in-package architectures, creating material specifications for redistribution layer compatibility.
- Medical Device Miniaturization:Implantable and wearable diagnostic equipment requires biocompatible polyimide laminates with flexible circuit capability, opening premium positioning for specialized resin formulators.
Industry Challenges
- Material Scientist Talent Gap:Formulation expertise combining polymer chemistry with RF engineering remains scarce, extending R&D timelines for high-frequency laminate development.
- Automotive Qualification Compression:AEC-Q100 and PPAP timelines for EV powertrain electronics now run 18-24 months, misaligning with semiconductor node advancement cycles and straining supplier engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pcb Laminate Materials Market |
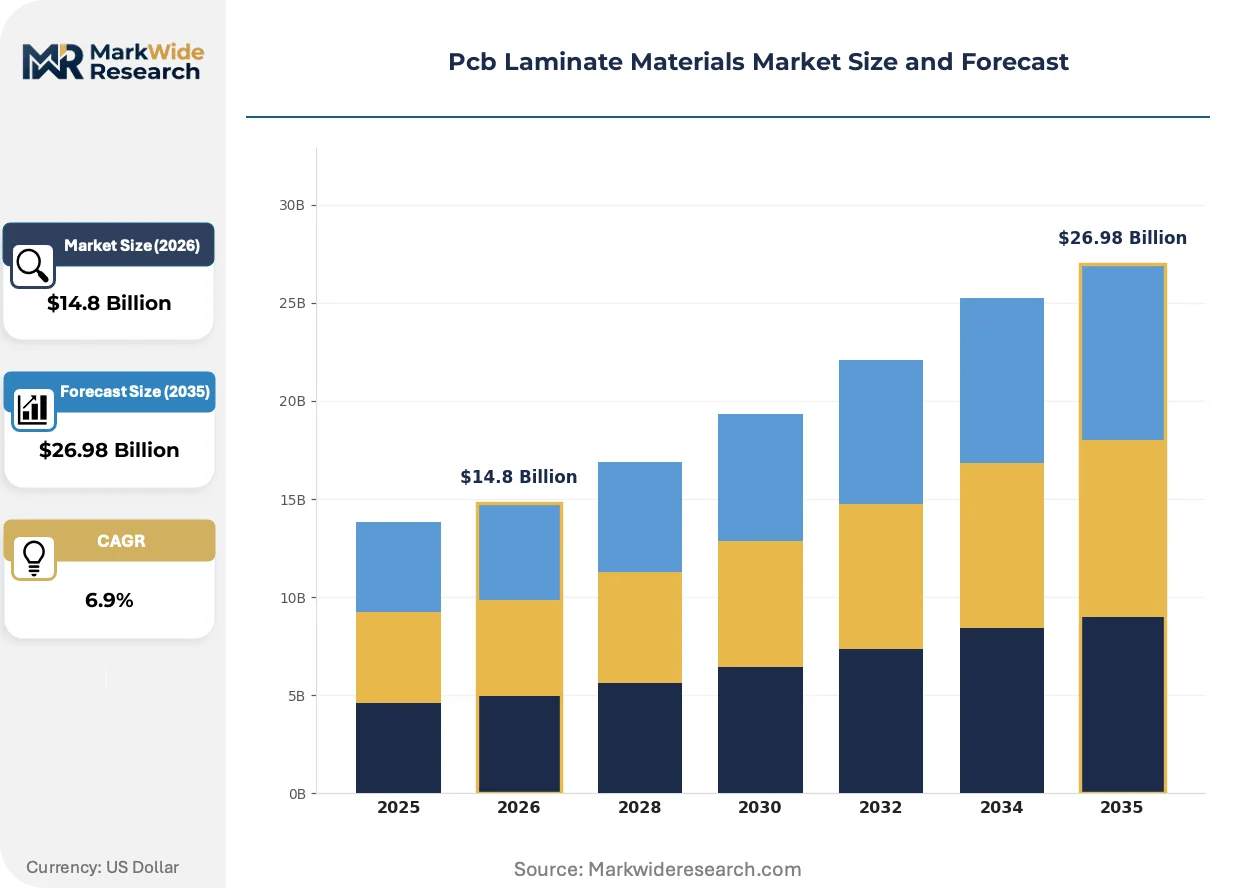
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Epoxy, Polyimide, PTFE, Paper Application: Consumer Electronics, Automotive Components, Aerospace Equipment, Industrial Machinery Form Factor: Single-Sided, Double-Sided, Multi-Layer, Rigid-Flex End User: Telecommunications, Medical Devices, Defense, Renewable Energy |
| Companies Covered | Kingboard Laminates Holdings Ltd., Shengyi Technology Co., Ltd., Nan Ya Plastics Corporation, Panasonic Holdings Corporation, Taiwan Elite Material Co., Ltd., ITEQ Corporation, Doosan Corporation, Isola Group, Rogers Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pcb Laminate Materials Market Emerging Trajectories
Active material reformulation is fragmenting the laminate landscape into application-specific tiers, with thermal, electrical, and environmental performance specifications diverging rather than converging.
Modified polyimide resin systems with silica filler integration are decentralizing high-temperature laminate supply chains away from traditional epoxy-centric manufacturing footprints. Automotive tier-1 suppliers are qualifying these materials for inverter and onboard charger applications at accelerated pace. This decentralization is enabling regional fabrication hubs to capture value previously concentrated in East Asian high-volume laminate production.
REACH authorization requirements for brominated flame retardants are forcing systematic substitution toward phosphorus-based and inorganic alternatives across European electronics supply chains. Industrial consequence includes mandatory requalification of all existing PCB designs for halogen-free laminate compatibility. Telecommunications infrastructure and aerospace equipment categories face the most severe compliance compression, with OEMs now requiring full material disclosure to downstream recyclers.
Consolidated procurement by hyperscale data center operators is compressing supplier negotiation cycles and unbundling technical service from material supply contracts. Distributors and compounders are losing margin to direct mill relationships as buyers consolidate volume for price leverage. This pattern is most visible in North American cloud infrastructure buildouts, where Microsoft, Amazon, and Google procurement teams specify laminate performance benchmarks and audit resin chemistry directly.
Pcb Laminate Materials Market Segmentation
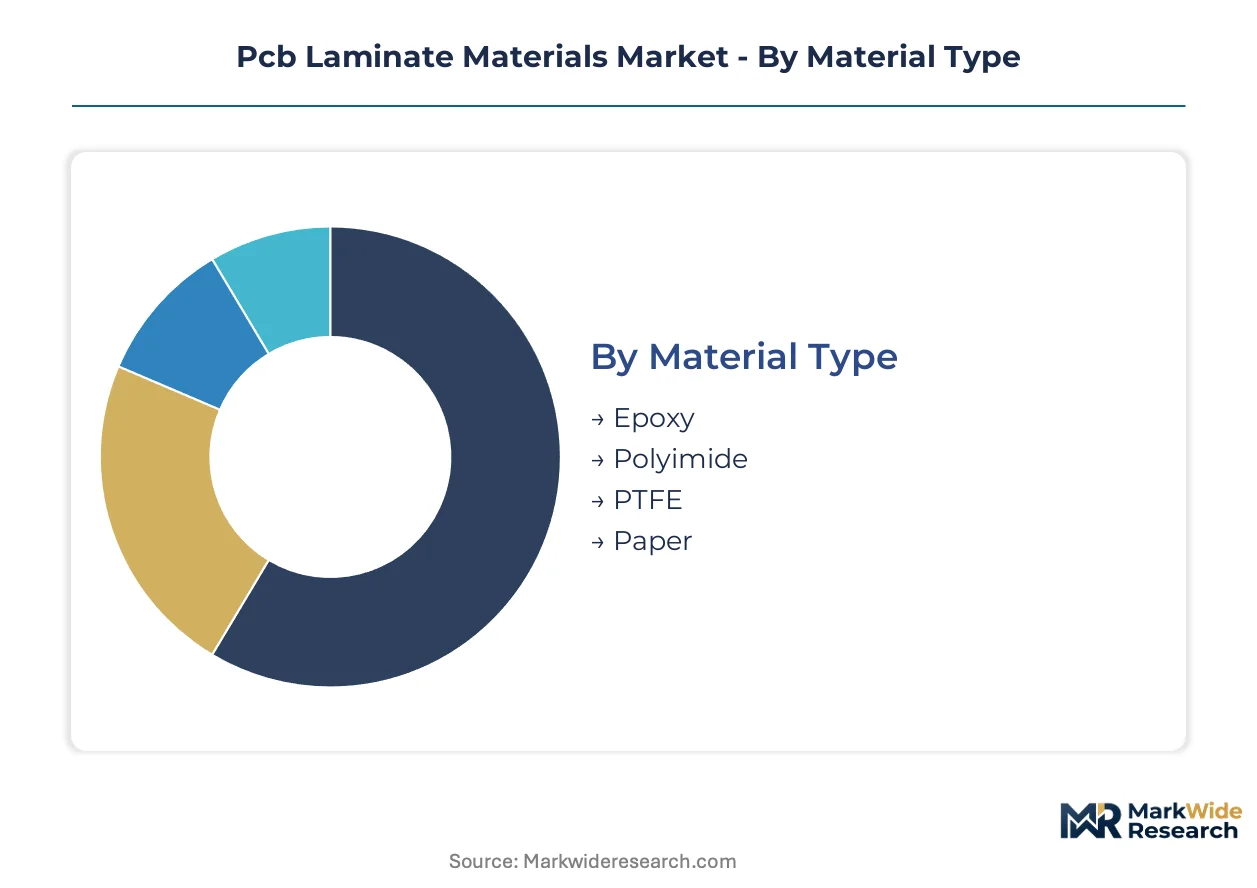
PCB laminate segmentation reveals how material specifications fragment across thermal, electrical, and mechanical requirements. Each dimension—material chemistry, application environment, physical form, and end-use industry—creates distinct procurement criteria that reshape supplier positioning.
Material Type:
Customization intensity varies sharply across resin systems, from commodity epoxy formulations to engineered fluoropolymer architectures.
- Epoxy:Glass-reinforced thermoset resin dominates volume production due to mature curing infrastructure and cost efficiency. Consumer electronics assembly in China, Vietnam, and Thailand absorbs the majority of standard-grade epoxy output for smartphones, tablets, and computing equipment.
- Polyimide:High-temperature aromatic polymer enables flexible circuit fabrication with thermal stability exceeding 200°C. Automotive powertrain electronics and medical implantable devices drive qualification programs for modified polyimide systems with silica filler integration.
- PTFE:Fluoropolymer base delivers ultra-low dielectric loss for millimeter-wave signal transmission. Base station antenna manufacturers specify PTFE laminates for 5G infrastructure deployment.
- Paper:Phenolic-impregnated cellulose substrate serves cost-sensitive single-sided applications. Legacy consumer appliances and basic industrial controls maintain residual demand.
Leading the category by volume: Epoxy. Expanding most quickly: Polyimide.
Application:
Performance thresholds diverge by operating environment severity, from benign indoor electronics to thermally stressed automotive underhood locations.
- Consumer Electronics:Smartphones, laptops, and wearables require thin-core multi-layer laminates with controlled impedance. Assembly plants in China, Mexico, and India specify halogen-free epoxy systems to meet EU RoHS and REACH downstream requirements.
- Automotive Components:Inverter modules, onboard chargers, and battery management systems demand glass transition temperatures above 150°C. EV platforms in Germany, South Korea, and the United States are accelerating qualification of thermally conductive filled laminates.
- Aerospace Equipment:Satellite communication and avionics systems specify ultra-low outgassing polyimide and PTFE formulations. Radiation-hardened laminates serve geostationary and low-earth orbit applications.
- Industrial Machinery:Motor drives, programmable logic controllers, and power supplies utilize standard FR-4 epoxy systems. Factory automation buildouts in Japan and Germany sustain steady demand for double-sided and multi-layer configurations.
Highest specification intensity: Aerospace Equipment. Fastest volume expansion: Automotive Components.
Form Factor:
Layer count and flexibility determine manufacturing process compatibility and signal routing density.
- Multi-Layer:Stacked copper and dielectric constructions enable high-density interconnect for advanced semiconductor packaging. Data center servers and networking equipment in the United States and Ireland specify 16+ layer counts for backplane applications.
- Rigid-Flex:Hybrid construction combining rigid laminate islands with flexible polyimide sections. Medical imaging equipment and military avionics integrate rigid-flex for three-dimensional packaging.
- Double-Sided:Through-hole plated construction serves industrial controls and automotive body electronics. Standard thicknesses of 1.6mm dominate cost-optimized applications.
- Single-Sided:Simple printed circuit format for basic interconnect in appliances and lighting. Paper-based phenolic laminates compete with entry-level epoxy in price-sensitive segments.
Widest application coverage: Double-Sided. Steepest expansion trajectory: Multi-Layer.
End User:
Procurement sophistication ranges from hyperscale volume consolidation to fragmented specialty qualification.
- Telecommunications:Base station, antenna, and optical transport equipment demand tightly controlled dielectric constant and dissipation factor. 5G millimeter-wave deployment in South Korea, Japan, and the United States pulls ultra-low Dk/Df laminates into volume production.
- Defense:Secure communication, radar, and electronic warfare systems require ITAR-controlled supply chains and radiation tolerance. Domestic sourcing mandates in the United States and United Kingdom restrict qualified supplier pools.
- Medical Devices:Implantable pacemakers, diagnostic imaging, and surgical robotics specify biocompatible polyimide with ISO 10993 compliance. Wearable monitoring equipment drives flexible circuit laminate demand.
- Renewable Energy:Solar inverters, wind turbine power converters, and energy storage systems utilize high-thermal-conductivity laminates. Grid-scale battery installations in China and Germany specify extended temperature range materials.
Most stringent qualification: Defense. Gaining share fastest: Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dongguan anchors laminate production capacity through its concentration of copper-cladding facilities and multi-layer PCB fabrication clusters serving consumer electronics assembly lines across the Pearl River Delta.
China
SAMR-administered GB standards on embodied carbon redirect procurement toward domestic suppliers with renewable energy-powered curing operations. The dual carbon goals compel laminate fabricators in Jiangsu and Guangdong provinces to verify low-carbon resin chemistry through third-party audit protocols. Suzhou industrial parks host qualification programs for halogen-free epoxy systems destined for EU RoHS-compliant export channels.
United States
EPA TSCA framework restrictions on brominated flame retardants accelerate phosphorus-based formulation transitions across telecommunications infrastructure buildouts. Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth consolidate procurement volumes for direct mill relationships. Arizona and Texas fabrication hubs qualify thermally conductive laminates for domestic EV powertrain electronics serving Detroit and Austin automotive design centers.
Germany
EU F-Gas Regulation constraints on fluoropolymer feedstocks compress margins for PTFE-based telecommunications-grade laminates. ECHA REACH authorization timelines force systematic requalification of existing PCB designs for halogen-free compatibility. Bavarian industrial corridors concentrate automotive tier-1 supplier qualification activity for inverter and onboard charger applications.
Japan
METI energy-efficiency benchmarks constrain material choices in high-performance telecommunications and aerospace segments. Base station antenna manufacturers in Nagoya and Osaka metropolitan areas specify ultra-low Dk/Df laminates for domestic 5G millimeter-wave deployment. Kyushu fabrication clusters advance modified polyimide systems with silica filler integration for satellite communication equipment.
South Korea
MFDS-equivalent industrial standards align laminate specifications with semiconductor packaging advancement cycles. Samsung and SK Hynix ecosystem demands pull specialized resin systems into volume production for advanced memory module substrates. Gyeonggi Province manufacturing complexes host multi-layer qualification programs for high-density interconnect designs in smartphone and computing equipment.
Pcb Laminate Materials Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermal performance and dielectric specification tiers. The vendor base stratifies into integrated copper-cladding operators, specialized high-frequency formulators, and regional epoxy compounders. Three archetypes dominate: scale-driven integrated producers commanding cost-sensitive supply tiers, technology specialists capturing telecommunications and aerospace premiums, and regional fabricators serving protected domestic markets. Competitive moves concentrate on backward integration into resin chemistry and captive supply of electrodeposited copper foil.
Among East Asian integrated producers, Kingboard Laminates Holdings Ltd. and Shengyi Technology Co., Ltd. occupy positions exemplifying scale-driven cost leadership. Panasonic Holdings Corporation represents the technology-specialist archetype through proprietary formulation capabilities. Isola Group and Rogers Corporation anchor North American supply for specification-intensive telecommunications and defense applications. Taiwan Elite Material Co., Ltd. and ITEQ Corporation sit within the high-frequency specialist tier serving 5G infrastructure deployment.
| Leading Market Players |
|---|
| Kingboard Laminates Holdings Ltd. |
| Shengyi Technology Co., Ltd. |
| Nan Ya Plastics Corporation |
| Panasonic Holdings Corporation |
| Taiwan Elite Material Co., Ltd. |
| ITEQ Corporation |
| Doosan Corporation |
| Isola Group |
| Rogers Corporation |
| Others |
Supply Flow & Price Mechanics
Electrodeposited copper foil feedstock moves from East Asian smelters through laminate fabricators into three pricing tiers downstream. Procurement consolidation by hyperscale data center operators compresses margins at the premium end while commodity epoxy grades face cost pressure from energy-intensive curing operations in Jiangsu and Guangdong provinces.
Pricing Analysis
Signal integrity benchmarks anchor value-based pricing for telecommunications-grade laminates serving 5G millimeter-wave deployment. Three-tier pricing structure across premium, standard, and economy levels separates PTFE formulations for aerospace from modified epoxy for automotive and commodity FR-4 for consumer electronics. Cost compression in standard-grade epoxy is intensifying because SAMR-administered carbon verification requirements add compliance overhead. Automotive tier-1 suppliers exhibit lowest price sensitivity due to AEC-Q100 qualification barriers, while appliance manufacturers drive hardest bargaining on single-sided phenolic laminates.
Supply Chain Analysis
Regional distribution centers in Dongguan, Nagoya, and Dallas-Fort Worth enable hub-and-spoke fulfillment patterns for multi-layer laminate shipments. Production concentrates in China, Japan, and South Korea, with raw material supply drawing from brominated flame retardant producers in Shandong, fluoropolymer resin compounders in Osaka, and glass fiber weavers in Taiwan. Single-source vulnerability persists in electrodeposited copper foil supply from concentrated East Asian electrowinning capacity. Distribution runs through direct mill relationships for hyperscale buyers and electronics distributors serving fragmented PCB fabrication shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified polyimide resin systems are displacing legacy epoxy formulations in automotive powertrain electronics, compressing qualification timelines and fragmenting supplier tiers.
For Market Incumbents: Anticipate margin erosion in standard-grade epoxy as China's dual carbon goals force renewable energy retrofit investments at curing facilities. Defensive consolidation should prioritize backward integration into halogen-free flame retardant chemistry to secure REACH-compliant supply. Capacity addition in Vietnam or India hedges against carbon-border adjustment exposure on EU-bound exports. For New Entrants and Emerging Players: Domestic PCB fabricators in India under the PLI scheme represent the most penetrable buyer archetype for laminate qualification programs. White-space targets include thermally conductive filled laminates for solar inverter OEMs and biocompatible polyimide for wearable diagnostic equipment. A technical service-led go-to-market angle bypasses entrenched distributor relationships in East Asian supply chains. For Investors and Strategic Acquirers: Accelerated AEC-Q100 qualification cycles for EV onboard chargers are the leading indicator that automotive laminate specifications are diverging from consumer electronics heritage. Long-term viability favors formulators with proprietary silica filler integration and captive copper-cladding capacity. The signal to monitor is tier-1 automotive supplier consolidation of qualified vendor lists below six sources per material specification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | Captive supply of phosphorus-nitrogen flame retardants secures REACH compliance for EU automotive exports. |
| Green Manufacturing Transition | Renewable energy-powered curing operations satisfy SAMR-administered GB standards on embodied carbon verification. |
| Long-term Supply Agreement | Direct mill relationships with hyperscale data center operators compress distributor margins and stabilize volume. |
| Joint Venture | Regional fabrication partnerships in India capture PLI scheme incentives for domestic PCB producer qualification. |
| Capacity Expansion | Multi-layer laminate buildout in Vietnam hedges carbon-border exposure on European electronics supply chains. |
Methodological Framework
Independent corroboration across laminate plant managers, procurement leads at tier-1 automotive suppliers, distribution channel partners, and technical R&D directors at resin compounders underwrites the qualitative findings. Secondary validation draws from customs and trade data, SAMR GB standard filings, SEC 10-K disclosures by listed laminate producers, and copper foil import records. Bottom-up build from application-level consumption and top-down cross-check against fabrication capacity yields convergent estimates.
Rate-of-change decomposition separates volume effects from mix shifts and price movements across the analysis window. Segmentation dimensions modeled include material chemistry tier, end-use industry thermal severity, layer count configuration, and regional regulatory cluster. CAGRs derive from fitted growth curves against qualification pipeline visibility. Forecast inputs incorporate EV platform ramp schedules and 5G base station deployment trajectories reported by telecommunications infrastructure OEMs.
Revisions become necessary when REACH authorization timelines for brominated flame retardants accelerate, EU F-Gas Regulation tightens fluoropolymer feedstock availability, or semiconductor cycle downturns trigger copper foil allocation freezes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Composites Cylinder Market
Composite Materials
Lignin-Based Graphene Market
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Global Carbon Fiber Reinforced Plastic Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
Composite Preforms Market
Composite Materials
CFRTP Market
Composite Materials
Medical Composite Material Market
Composite Materials
Structural Core Materials Market
Composite Materials
Europe Marine Composites Market
Composite Materials
FRP Tanks Market
Composite Materials
Malaysia High Pressure Laminate Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Composite Drums Market