
 Composites Distributor Market | 2026-2036
Composites Distributor Market Size, Share, and Industry Trends Forecast 2026-2036
Composites Distributor Market Analysis
Aerospace-grade prepreg certification is redrawing competitive boundaries among composites distributors. Composites One leverages its North American branch network to sustain same-day delivery commitments for autoclave-qualified materials. Euroresins International GmbH anchors its position through REACH-registered formulations across European aerospace tier suppliers. Gazechim Composites UK specializes in cryogenic-rated systems for satellite and launch vehicle fabricators.
A composites distributor functions as an intermediary managing inventory, technical specification matching, and cold-chain logistics for fiber-reinforced polymers, prepregs, and resin systems with defined gel times and Tg parameters. These entities bridge manufacturers requiring lot-traceable, certified materials with producers lacking direct channel infrastructure. Thermoset distribution occupies the dominant volume share due to epoxy and polyester saturation in marine and construction supply chains. Thermoplastic composites represent the fastest-expanding product category as automotive OEMs seek recyclable, weldable alternatives to thermoset structures. Wholesale channels capture the largest margin pool through mill-direct volume commitments and long-term offtake agreements with wind blade and boat builders.
EPA oversight governs volatile organic compound thresholds in resin formulations sold through US distribution networks, while REACH registration requirements in Europe restrict uncertified chemical introductions. ECHA substance evaluation periodically delists legacy hardeners, forcing distributor portfolio adjustments. China's GB standards and MEE environmental compliance protocols now require import registration for specialty epoxy systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and maintain cross-border material mobility.
Market Dynamics
Certification-driven procurement for aerospace-grade prepregs is compressing distributor margins while elevating technical service requirements above pure logistics capabilities.
Growth Catalysts
- Wind blade manufacturing scale-up:China's wind energy zones are driving bulk epoxy system orders through specialized distributors with cold-chain infrastructure.
- REACH-registered formulation mandates:ECHA substance evaluation protocols are filtering uncertified competitors from European aerospace supply chains.
- Thermoplastic composite weldability:Automotive OEMs in Germany's supply corridor are specifying recyclable alternatives to thermoset structures.
Market Restraints
- Raw resin price volatility:Epoxy precursor costs fluctuate with benzene and propylene feedstock markets, squeezing distributor working capital cycles.
- Supply concentration risk:Carbon fiber precursor manufacturing clusters in Japan and the US create geographic single-point vulnerabilities for aerospace distributors.
- Gel time technical limitations:Out-of-autoclave prepregs face restricted shelf life windows that complicate inventory positioning strategies.
Strategic Opportunities
- India's defense aerospace procurement:Indigenous fighter programs and satellite launches are creating demand for cryogenic-rated composite systems without established local supply chains.
- Digital inventory platforms:Real-time lot-traceability systems are enabling distributors to offer specification-matching services that command premium positioning.
- EU Green Deal material mandates:Recyclability requirements for wind turbine blades are accelerating thermoplastic composite specification in offshore energy projects.
Industry Challenges
- Autoclave qualification timelines:OEM certification cycles for new prepreg lots extend 18-24 months, freezing distributor product range flexibility.
- Cold-chain infrastructure capex:Maintaining minus-18°C storage integrity across multiple warehouse nodes demands continuous refrigeration investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composites Distributor Market |
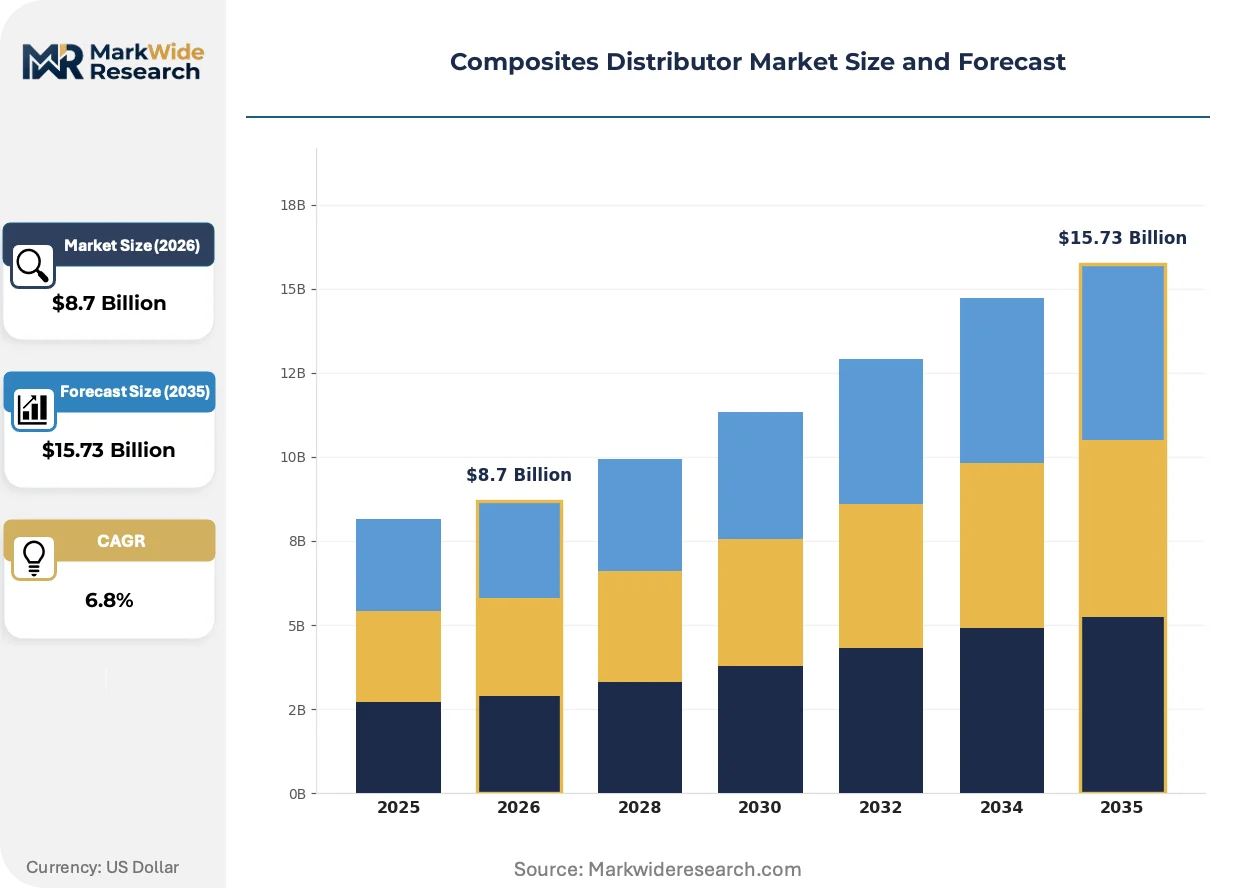
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoset, Thermoplastic, Reinforced, Composite Matrix End User: Aerospace, Marine, Construction, Automotive Application: Structural, Electrical, Thermal, Aerospace Components Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Composites One, Euroresins International GmbH, FRP Services & Company, Gazechim Composites UK, IMCD N.V., Lintech International LLC, Microtex Composites Srl, North American Composites, Toray International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composites Distributor Market Emerging Trajectories
Digital specification-matching platforms and out-of-autoclave processing advances are redrawing how technical distributors capture value beyond commodity logistics.
Out-of-autoclave (OOA) curing systems are supplanting traditional autoclave-dependent prepregs in satellite fabrication workflows. Spacecraft manufacturers in California and Bavaria are specifying OOA epoxies to eliminate autoclave size constraints on large antenna structures. This technology compression is enabling smaller distributors to compete for aerospace contracts without capital-intensive pressure vessel infrastructure.
ECHA's substance evaluation protocols are systematically delisting legacy amine hardeners from REACH-registered portfolios. European distributors must reformulate or discontinue product lines containing restricted cycloaliphatic amines. Aerospace tier suppliers in Toulouse and Hamburg are accelerating qualification of alternative catalyst systems to maintain material continuity.
Consolidated procurement through mill-direct offtake agreements is fragmenting traditional wholesale relationships. Wind blade manufacturers in China's Jiangsu province are bypassing regional distributors for volume resin commitments. This channel compression is forcing mid-tier distributors to specialize in technical specification services or niche cold-chain segments.
Composites Distributor Market Segmentation
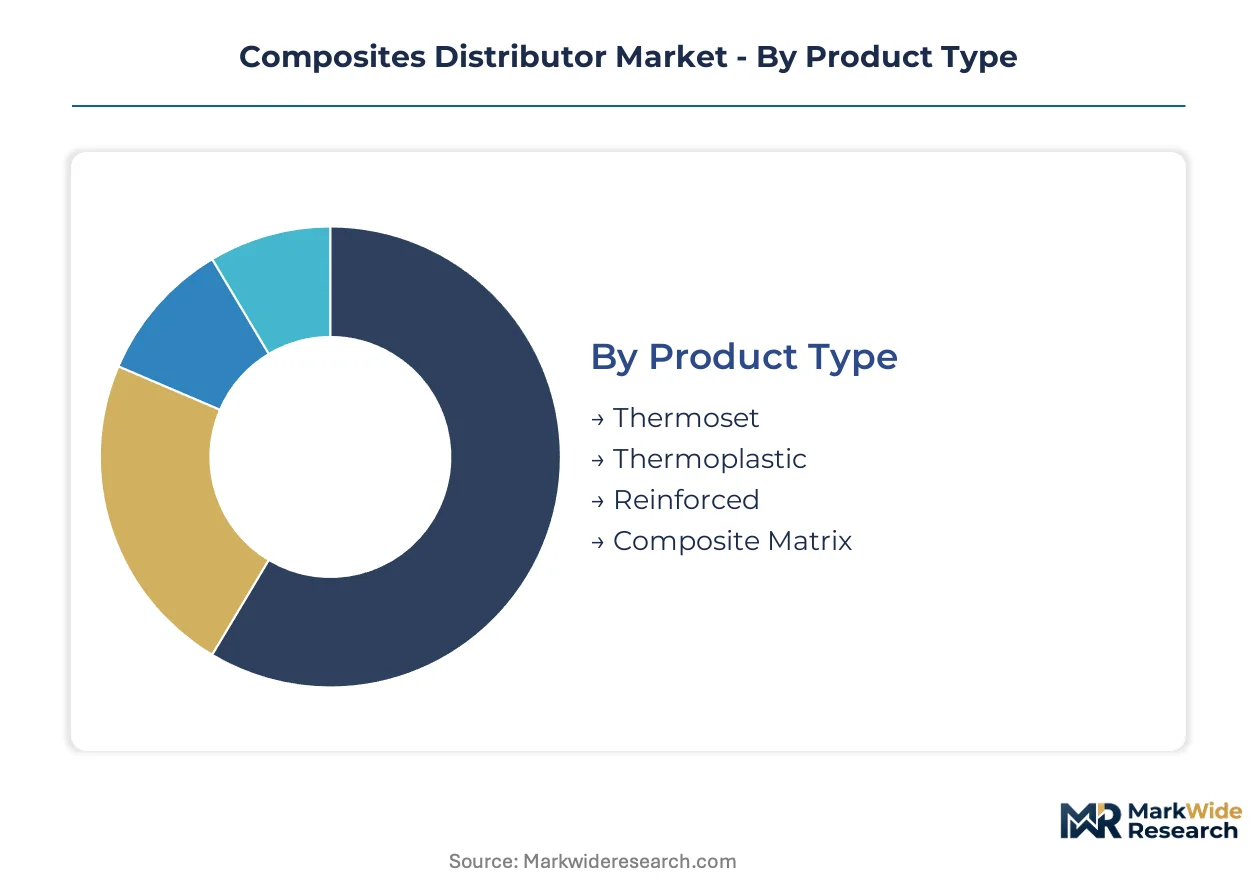
Composites distributors segment their operations around thermal stability requirements, certification tiers, and channel economics. Each dimension carries distinct regulatory footprints and margin structures that shape inventory positioning strategies.
Product Type:
EPA volatile organic compound thresholds and ECHA REACH registration requirements create divergent compliance burdens across material chemistries.
- Thermoset:Epoxy and polyester systems dominate marine and construction supply chains with established gel time protocols and Tg parameters. Demand concentrates in China's Jiangsu wind blade manufacturing zones where bulk epoxy orders flow through distributors with cold-chain infrastructure.
- Thermoplastic:Recyclable, weldable alternatives to thermoset structures are gaining specification from automotive OEMs in Germany's supply corridor. Polyamide and PEEK-based systems command premium positioning due to reprocessing compatibility under EU Green Deal material mandates.
- Reinforced:Carbon and glass fiber prepregs require lot-traceable certification for aerospace tier suppliers in Toulouse and Hamburg.
- Composite Matrix:Hybrid resin-fiber systems serve satellite fabricators in California and Bavaria with cryogenic-rated performance specifications.
Established volume favors Thermoset; emerging adoption favors Thermoplastic.
End User:
Customer procurement patterns range from mill-direct volume commitments to specification-matched technical service contracts.
- Aerospace:Autoclave-qualified prepregs demand 18-24 month OEM certification cycles that freeze distributor product range flexibility. Procurement concentrates through specialized distributors serving tier suppliers in Hamburg and Toulouse with REACH-registered formulations.
- Automotive:Recyclability requirements under EU Green Deal protocols are accelerating thermoplastic composite specification for structural components. Germany's automotive supply corridor drives weldable material adoption to replace thermoset assemblies.
- Marine:Polyester saturation in boat builder supply chains sustains wholesale channel volume through mill-direct offtake agreements.
- Construction:Epoxy and vinyl ester systems serve infrastructure reinforcement applications with less stringent cold-chain requirements than aerospace grades.
Certification intensity peaks with Aerospace; volume scale concentrates in Marine.
Application:
Performance specifications determine refrigeration investment levels and technical service staffing ratios.
- Structural:Load-bearing composite systems serve wind turbine blades and civil infrastructure with defined mechanical property thresholds. China's wind energy zones drive bulk orders through distributors maintaining minus-18°C storage integrity.
- Aerospace Components:Out-of-autoclave curing systems are supplanting traditional autoclave-dependent prepregs for satellite antenna structures in California and Bavaria. This technology compression enables smaller distributors to compete without pressure vessel infrastructure.
- Electrical:Dielectric-grade prepregs serve radar dome and antenna applications with controlled dissipation factor specifications.
- Thermal:High-Tg resin systems address exhaust and engine compartment applications in automotive and aerospace propulsion segments.
Capital intensity clusters in Aerospace Components; margin stability characterizes Structural.
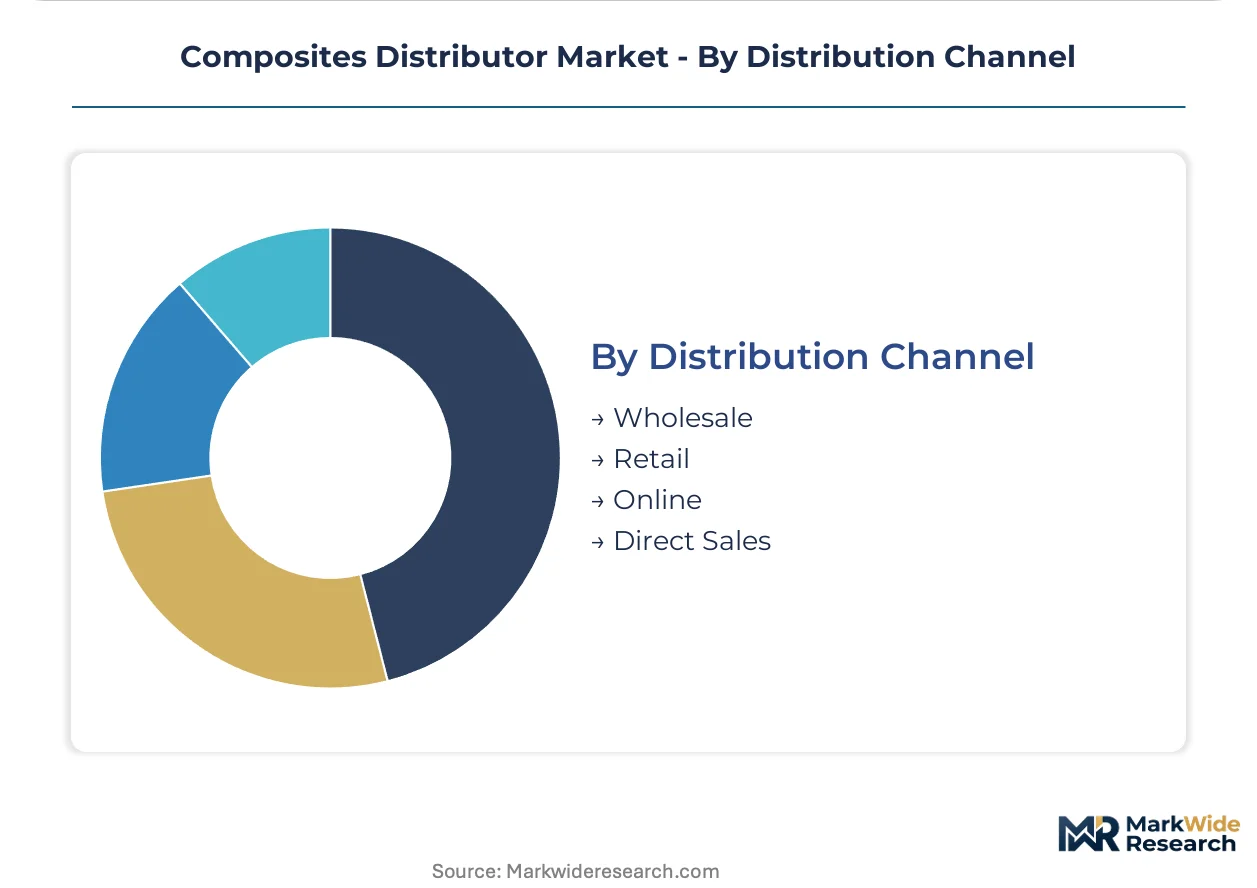
Distribution Channel:
Channel selection reflects customer scale, technical complexity, and geographic concentration of demand.
- Wholesale:Mill-direct volume commitments and long-term offtake agreements with wind blade and boat builders capture the largest margin pool. China's Jiangsu manufacturers increasingly bypass regional distributors for consolidated resin procurement.
- Direct Sales:Aerospace tier suppliers in Toulouse and Hamburg require specification-matching services and lot-traceability systems that command premium positioning beyond commodity logistics.
- Retail:Small-batch epoxy and polyester systems serve marine repair shops and construction contractors with limited cold-chain requirements.
- Online:Digital inventory platforms with real-time lot-traceability are emerging for standard-grade materials with established certification histories.
Relationship depth defines Direct Sales; transaction velocity drives Online expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports REACH-registered epoxy systems to aerospace fabricators in Toulouse and Hamburg. China's Jiangsu province ships bulk carbon fiber prepregs to wind blade manufacturers across Asia-Pacific. These trade corridors concentrate procurement authority with distributors maintaining cold-chain integrity and lot-traceability systems.
United States
EPA volatile organic compound thresholds govern resin formulations sold through domestic distribution networks. Aerospace manufacturers in California specify out-of-autoclave prepregs for satellite antenna structures. The FAA maintains certification protocols for autoclave-qualified materials serving commercial aviation supply chains.
Germany
Automotive OEMs in Baden-Württemberg specify thermoplastic composites for recyclable structural components. ECHA substance evaluation protocols filter uncertified hardeners from REACH-registered portfolios. The country's automotive supply corridor drives weldable material adoption to replace thermoset assemblies.
China
Wind blade manufacturers in Jiangsu province consolidate bulk epoxy orders through distributors with minus-18°C storage infrastructure. MEE environmental compliance protocols require import registration for specialty epoxy systems. The province's wind energy zones bypass regional distributors for mill-direct volume commitments.
Japan
Carbon fiber precursor manufacturing clusters supply aerospace distributors with lot-traceable materials. METI oversees industrial standards for fiber-reinforced polymers in automotive and aviation applications. Tokyo-based fabricators serve satellite manufacturers requiring cryogenic-rated composite systems.
India
Indigenous fighter programs and satellite launches create demand for cryogenic-rated composites without established local supply chains. BIS certification requirements govern structural materials for defense aerospace procurement. Maharashtra's emerging aerospace clusters rely on imported prepregs through specialized distributors.
Composites Distributor Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The vendor base stratifies between multinational chemical distributors with mill-direct volume commitments and regional specialists with cold-chain infrastructure. Three archetypes dominate: aerospace-grade certification specialists, thermoplastic composite technical advisors, and wholesale volume consolidators. M&A activity targets REACH-registered formulation portfolios, while geographic expansion concentrates on India's defense aerospace corridor.
Among North American distributors, Composites One exemplifies the branch-network archetype with same-day delivery capabilities. Euroresins International GmbH occupies a position within the European REACH-registered specialist tier. Gazechim Composites UK represents the cryogenic-rated systems segment serving satellite fabricators. These three anchors illustrate how certification depth and cold-chain infrastructure separate premium positioning from commodity logistics.
| Leading Market Players |
|---|
| Composites One |
| Euroresins International GmbH |
| FRP Services & Company |
| Gazechim Composites UK |
| IMCD N.V. |
| Lintech International LLC |
| Microtex Composites Srl |
| North American Composites |
| Toray International Inc. |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month autoclave qualification timelines concentrate pricing power with distributors maintaining REACH-registered portfolios and minus-18°C infrastructure, compressing margins for generalists while rewarding cold-chain specialists with premium positioning in aerospace procurement corridors.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium aerospace-grade prepregs, standard thermoset systems, and economy polyester formulations. Price differentiation rests on certification depth and volume scale, with REACH-registered aerospace materials commanding substantial premiums over construction-grade epoxies. Pricing pressure intensifies as China's Jiangsu wind blade manufacturers consolidate mill-direct offtake agreements, bypassing regional distributors. Marine boat builders exhibit highest price sensitivity due to commoditized polyester saturation, while satellite fabricators in California and Bavaria show lowest sensitivity for cryogenic-rated systems.
Supply Chain Analysis
Panama Canal transit constraints and Red Sea routing disruptions expose inventory positioning vulnerabilities for distributors serving European aerospace clusters. Raw material sourcing concentrates in Japan's carbon fiber precursor manufacturing, China's epoxy resin production, and Germany's specialty hardener formulations. Supply chains draw from acrylonitrile feedstocks, cycloaliphatic amine catalysts, and polyamide thermoplastic resins. Single-source vulnerability clusters in Japanese PAN-based fiber supply for aerospace qualification lots. Distribution runs through specialized technical distributors for aerospace, wholesale consolidators for marine volume, and emerging digital platforms for standard-grade construction materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through REACH registration and autoclave qualification cycles constructs formidable defensive moats, locking incumbent distributors into long-term relationships with aerospace tier suppliers while freezing out uncertified competitors.
For Market Incumbents: Consolidate REACH-registered formulation portfolios through targeted acquisition of European specialty distributors facing ECHA substance evaluation delistings. Deepen cold-chain infrastructure in India's Maharashtra defense aerospace corridor before indigenous supply chains mature. Prioritize certification investment in out-of-autoclave epoxy systems to capture satellite fabrication demand from California and Bavaria fabricators.
For New Entrants and Emerging Players: Specification-matching digital platforms represent the most penetrable service layer where incumbents under-serve mid-tier automotive OEMs seeking thermoplastic composite weldability guidance. Target Germany's automotive supply corridor with technical advisory services for recyclable polyamide and PEEK system selection. Deploy direct sales teams offering real-time lot-traceability as a go-to-market wedge against wholesale volume consolidators.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest non-core distribution assets lacking aerospace certification depth. Long-term viability favors distributors with captive cold-chain networks and established OEM qualification relationships. Watch ECHA substance evaluation announcements as inflection indicators for portfolio restructuring opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Captive acrylonitrile supply secures lot-traceability for aerospace qualification cycles. |
| REACH-Registered Formulation Acquisition | ECHA-compliant hardener portfolios retain access to Toulouse and Hamburg tier suppliers. |
| Minus-18°C Infrastructure Expansion | Cold-chain integrity enables same-day delivery commitments for autoclave-qualified prepregs. |
| Digital Specification-Matching Platform Launch | Real-time lot-traceability commands premium positioning beyond commodity logistics services. |
| Thermoplastic Composite Technical Advisory Service | Weldability expertise captures EU Green Deal recyclability mandates in automotive supply chains. |
Methodological Framework
A spread of perspectives from aerospace procurement directors, thermoset plant managers, cold-chain logistics operators, and ECHA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with distribution channel partners and secondary validation through customs trade data, ACC industry reports, SEC distributor filings, and wind energy project development databases. Bottom-up volume estimates triangulated against top-down market sizing across thermoset, thermoplastic, and reinforced product categories.
Segmentation dimensions modeled include product chemistry tier, end-use industry certification intensity, application performance specification, and channel relationship depth across the projection horizon. CAGRs derived from weighted average growth contributions across Germany's automotive corridor, China's Jiangsu wind zones, and California-Bavaria satellite fabrication clusters. Industry-specific forecast inputs incorporated EPA volatile organic compound threshold revisions and ECHA substance evaluation pipeline timing.
Underlying assumptions cover sustained aerospace build rates, stable benzene-propylene feedstock pricing, and REACH registration continuity, with deviation risk concentrated in autoclave qualification timeline extensions and carbon fiber precursor supply disruptions. Practitioners should keep alternative scenarios live as ECHA regulatory actions and China's MEE environmental compliance protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Laminar Composites Market
Composite Materials
Global Carbon Fiber Reinforced Polymer Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Turbine Blade Material Market
Composite Materials
Global Geocomposites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Thermoset Composites Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Expandable Graphite Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Automotive Carbon Fiber Materials Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Composite Adhesives Market