
 Structural Core Materials Market | 2026-2036
Structural Core Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Core Materials Market Outlook
Balsa wood is restructuring cost-performance tradeoffs across wind turbine blade manufacturing as OEMs seek alternatives to petroleum-derived cores. Diab International AB leverages its vertically integrated balsa plantation network to sustain raw material security across Atlantic supply routes. Gurit Holdings AG anchors its competitive position through specialized PET foam formulations designed for resin infusion compatibility. Changzhou Tiansheng New Materials Co. Ltd. dominates Asian supply channels through concentrated production of PVC structural foams for domestic wind energy programs.
Structural core materials are engineered cellular substrates—typically honeycomb, foam, or balsa—bonded between composite face sheets to create sandwich structures with high stiffness-to-weight ratios and shear resistance. These assemblies reduce mass by 30-50% compared to monolithic laminates while preserving buckling stability, serving critical load-bearing functions in aerospace flight control surfaces, automotive floor pans, and marine hulls. Honeycomb configurations, particularly aluminum and aramid variants, lead aerospace penetration due to decades of airworthiness certification and established repair protocols. Foam cores, spanning PVC, PET, and PMI chemistries, represent the fastest-expanding category as automated fiber placement and resin transfer molding accelerate cycle times in automotive and wind energy applications.
The Federal Aviation Administration maintains stringent flammability and smoke toxicity standards under FAR 25.853 that dictate core material selection for commercial aircraft interiors and primary structures. The European Chemicals Agency enforces REACH substance restrictions on isocyanates and halogenated flame retardants used in polyurethane foam production, compelling reformulation investments across core suppliers. China's Ministry of Ecology and Environment implements dual carbon goals that tighten energy efficiency benchmarks for composite manufacturing facilities, reshaping plant location decisions and process technology adoption. Stakeholders must monitor how evolving certification requirements for hydrogen storage vessels and electric aircraft battery enclosures redirect core density specifications and fire-resistance testing protocols.
Market Dynamics
Aerospace OEMs are compressing sandwich panel qualification cycles as next-generation aircraft programs accelerate, forcing core suppliers to front-load certification investments before production contracts finalize.
Growth Catalysts
- EU Green Deal carbon intensity rules:REACH substance restrictions on halogenated flame retardants are redirecting material selection toward bio-based balsa and PET foam alternatives in European wind blade manufacturing.
- Automated fiber placement:Resin transfer molding acceleration is expanding foam core adoption in automotive floor pan production, cutting cycle times versus honeycomb layup methods.
- Germany:Airbus supply chain localization and Fraunhofer Institute research partnerships concentrate engineering talent and testing infrastructure for aerospace-grade core validation.
Market Restraints
- Raw material concentration:Balsa plantation control by a limited supplier base across Atlantic supply routes creates vulnerability to weather-driven harvest volatility and shipping bottlenecks.
- Isocyanate restrictions:ECHA enforcement of REACH limits on polyurethane foam precursors compels reformulation investments that extend R&D timelines and raise unit costs.
- Aluminum honeycomb substitution ceiling:Decades of airworthiness certification lock-in limits foam core penetration in primary flight control surfaces despite weight advantages.
Strategic Opportunities
- Hydrogen storage vessels:Emerging certification requirements for cryogenic composite pressure vessels are redirecting core density specifications toward high-shear PMI foam configurations.
- Electric aircraft battery enclosures:FAR 25.853 fire-resistance testing protocol evolution is creating demand for intumescent-coated PET foam cores in next-generation aviation battery systems.
- China's dual carbon goals:MEE energy efficiency benchmarks for composite manufacturing facilities are reshaping plant location decisions and process technology adoption among core producers.
Industry Challenges
- Airworthiness certification timelines:FAA flammability and smoke toxicity validation for new core chemistries extends qualification periods beyond typical automotive or wind energy product development cycles.
- Resin infusion compatibility:Matching foam core cell structure to variable viscosity resin systems requires iterative testing that strains technical service capacity at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Core Materials Market |
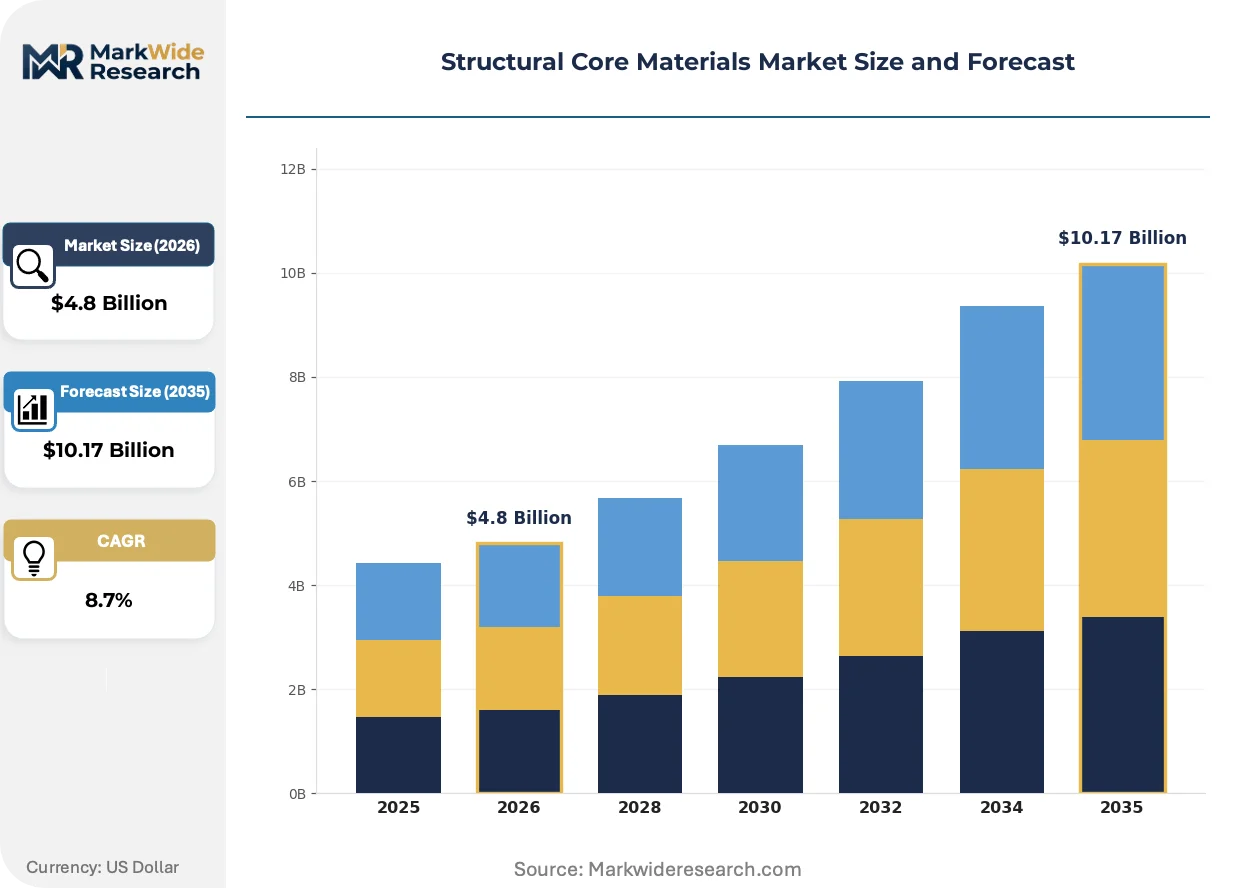
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Honeycomb, Foam, Balsa, Composite Application: Aerospace, Automotive, Marine, Construction Density: Low Density, Medium Density, High Density, Ultra-High Density Manufacturing Process: Injection Molding, Compression Molding, Hand Layup, Automated Fiber Placement |
| Companies Covered | Evonik Industries AG, 3A Composites GmbH, Diab International AB, Gurit Holdings AG, Hexcel Corporation, Armacell International, The Gill Corporation, Euro-Composites, Changzhou Tiansheng New Materials Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Core Materials Market Strategic Shifts
Material substitution logic is inverting as sustainability metrics penetrate procurement scoring, elevating lifecycle carbon accounting alongside mechanical performance in core selection algorithms.
Thermoplastic foam cores are absorbing resin infusion process loads that previously degraded PVC formulations, enabling wind turbine blade OEMs to consolidate core inventories across blade lengths. Vestas and Siemens Gamesa procurement teams are specifying PET foam for root sections previously reserved for balsa. This substitution is compressing balsa demand growth in onshore wind programs while preserving premium applications in longer offshore blades.
China's Ministry of Ecology and Environment is tightening energy efficiency benchmarks for composite manufacturing facilities under dual carbon implementation rules, compelling core producers to relocate molding operations toward western provinces with hydroelectric baseload. PET foam extrusion lines in Jiangsu and Zhejiang face power cost restructuring that advantages newer facilities in Sichuan. The policy is accelerating capital rotation among domestic suppliers serving wind energy programs.
Buyer concentration among tier-one aerospace primes is compressing supplier negotiation leverage and extending payment terms for core material shipments. Airbus and Boeing procurement teams are consolidating sandwich panel contracts with tiered suppliers who maintain dual-source foam core inventories. This behavior is most visible in Germany, where Hamburg and Bremen assembly lines specify qualified PET and PMI foam alternatives from approved vendor lists that exclude unqualified challengers.
Structural Core Materials Market Segmentation
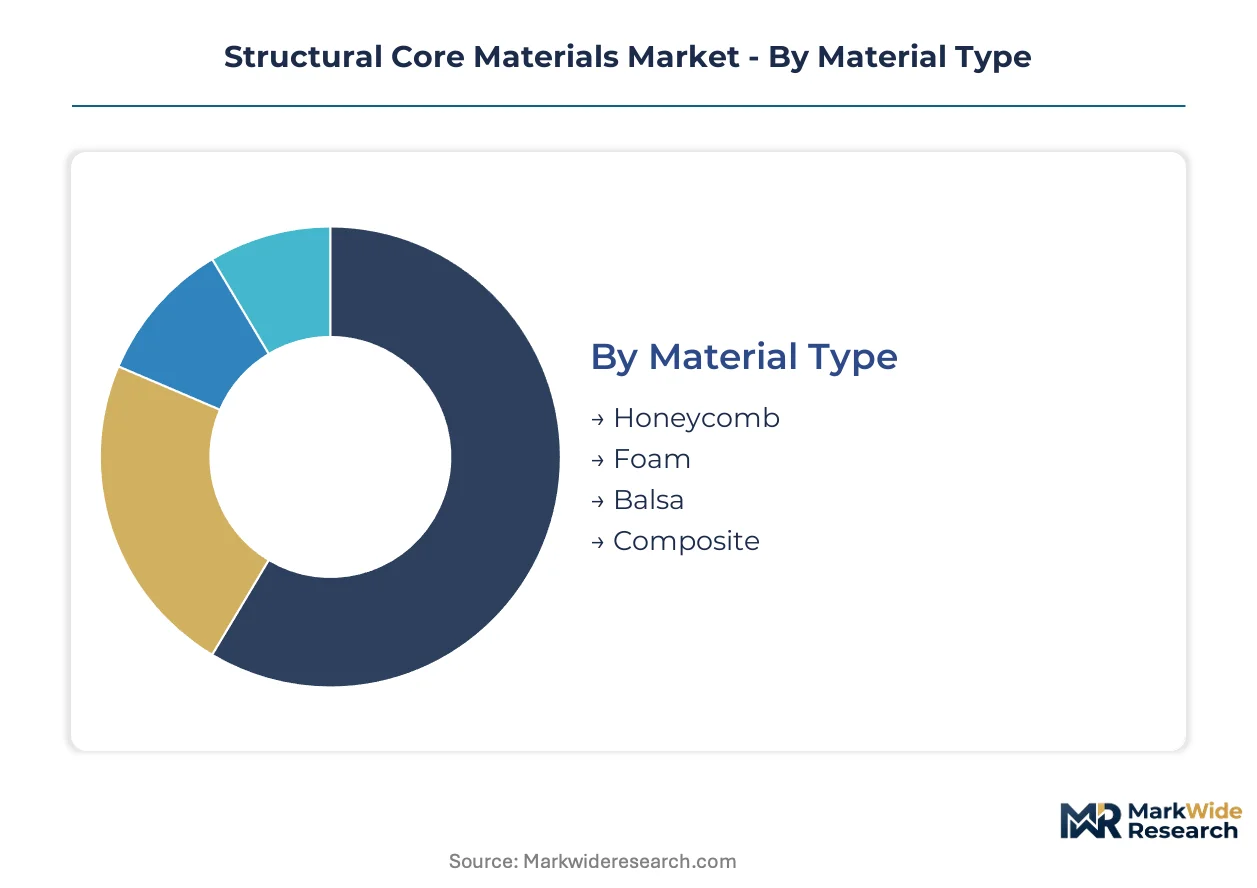
Structural core materials demand fragments across material chemistries, density grades, and manufacturing methods that each impose distinct capital requirements and certification barriers. Procurement teams align specifications with end-use performance thresholds rather than optimizing for single variables.
Material Type:
Honeycomb configurations demand the heaviest upfront tooling investment for precision cell formation and bonding equipment.
- Honeycomb:Aluminum and aramid variants maintain aerospace dominance through decades of FAA airworthiness certification and established repair protocols. Airbus and Boeing procurement teams specify qualified honeycomb suppliers for primary flight control surfaces where foam cores remain locked out by certification inertia.
- Foam:PVC, PET, and PMI chemistries enable automated fiber placement and resin transfer molding acceleration in automotive floor pans and wind turbine blades. Vestas procurement specifications now mandate PET foam for root sections previously reserved for balsa, compressing inventory complexity across blade lengths.
- Balsa:Plantation-controlled raw material security drives vertical integration strategies among Atlantic suppliers serving offshore wind programs.
- Composite:Hybrid constructions combining syntactic and natural fiber architectures address niche cryogenic and fire-resistant applications.
Honeycomb absorbs the bulk of installed capacity; foam is expanding most quickly.
Application:
End-use selection pivots on fire-resistance mandates and mass reduction targets that vary sharply across mobility sectors.
- Aerospace:FAR 25.853 flammability and smoke toxicity standards dictate core material selection for commercial aircraft interiors and primary structures. Hamburg and Bremen assembly lines specify qualified PET and PMI foam alternatives from approved vendor lists that exclude unqualified challengers.
- Automotive:Floor pan production cycles favor foam cores that withstand resin infusion pressures without cell collapse, cutting layup time versus honeycomb methods.
- Marine:Hull stiffness requirements and moisture resistance specifications favor balsa and PVC foam configurations in yacht and commercial vessel manufacturing.
- Construction:Sandwich panels for facade and roofing applications prioritize cost efficiency over aerospace-grade certification, opening channels for medium-density foam alternatives.
Aerospace commands premium pricing tiers; automotive is climbing the fastest as electrification accelerates lightweighting programs.
Density:
Density grading determines shear strength and compression modulus thresholds that map directly to structural load paths.
- Low Density:Below 100 kg/m³ configurations serve non-structural interior panels and insulation layers where mass reduction outweighs mechanical loading.
- Medium Density:Wind turbine blade OEMs specify this grade for shear webs and spar caps balancing stiffness against resin uptake efficiency.
- High Density:Primary aerospace structures and marine bulkheads require this specification for concentrated load distribution and fastener pull-through resistance.
- Ultra-High Density:Cryogenic composite pressure vessels for hydrogen storage redirect specifications toward PMI foam configurations with high-shear performance at temperature extremes.
Medium density captures current volume leadership; ultra-high density shows steepest expansion trajectory from emerging hydrogen and electric aircraft programs.
Manufacturing Process:
Process selection locks in cycle time economics and capital equipment amortization schedules across production scales.
- Injection Molding:High-volume automotive components favor this method for thermoplastic core integration with face sheet materials.
- Compression Molding:Marine and construction panels utilize this approach for consistent thickness control in medium-batch production.
- Hand Layup:Custom aerospace prototypes and repair operations retain this method despite labor intensity and cycle time penalties.
- Automated Fiber Placement:Siemens Gamesa and Vestas production lines specify this process for wind blade root sections, enabling PET foam consolidation across blade lengths previously segmented by material type.
Hand layup retains installed base dominance; automated fiber placement is gaining share fastest as wind energy scales manufacturing throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates aerospace-grade engineering talent and testing infrastructure through Airbus supply chain localization and Fraunhofer Institute partnerships, anchoring European demand for qualified sandwich panel suppliers.
United States
FAA flammability standards under FAR 25.853 dictate core material selection for commercial aircraft interiors and primary structures. The Federal Aviation Administration maintains stringent smoke toxicity thresholds that extend qualification timelines beyond automotive or wind energy development cycles. Boeing procurement teams in Seattle and Charleston specify qualified honeycomb and foam core alternatives from approved vendor lists.
China
MEE energy efficiency benchmarks under dual carbon goals reshape plant location decisions for PET foam extrusion operations. The Ministry of Ecology and Environment tightens power cost structures in Jiangsu and Zhejiang provinces. Sichuan facilities with hydroelectric baseload capture capital rotation among domestic suppliers serving wind energy programs.
Japan
METI industrial policy supports lightweighting initiatives in automotive and aerospace manufacturing sectors. The Ministry of Economy, Trade and Industry coordinates composite R&D consortia linking material suppliers with tier-one manufacturers. Nagoya and Osaka industrial corridors concentrate precision engineering capabilities for high-performance core validation.
India
PLI scheme incentives for advanced materials manufacturing attract composite core producers to Gujarat and Maharashtra industrial zones. The Department of Heavy Industry channels production-linked benefits toward domestic wind blade and aerospace component suppliers. Pune and Ahmedabad clusters emerge as testing and qualification hubs for sandwich panel applications.
Brazil
ANEEL renewable energy auctions accelerate wind farm deployment across Northeast and South regions. The National Electric Energy Agency procurement rules favor domestic content requirements that stimulate local blade manufacturing. Ceará and Rio Grande do Sul states concentrate balsa plantation development and foam core conversion facilities.
Structural Core Materials Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers front-load certification investments before aerospace production contracts finalize. The vendor base separates into three tiers: multinational chemical conglomerates with diversified materials portfolios, specialized core manufacturers with captive raw material access, and regional fabricators serving single-industry demand pockets. Strategic archetypes include plantation-integrated balsa operators, PET foam specialists with resin infusion expertise, and honeycomb incumbents leveraging decades of airworthiness certification. M&A activity and backward integration into upstream raw material production represent the dominant competitive vectors reshaping supply security.
Among European-based material suppliers, Evonik Industries AG and 3A Composites GmbH exemplify the chemical-conglomerate archetype with diversified high-performance materials portfolios. Diab International AB occupies a position within the plantation-integrated tier through its Atlantic balsa supply network. Gurit Holdings AG represents the specialized foam formulation segment with PET chemistry expertise. Hexcel Corporation anchors the honeycomb incumbent category with established aerospace certification pathways. Changzhou Tiansheng New Materials Co. Ltd. sits within the Asia-Pacific regional fabricator tier serving domestic wind energy procurement channels.
| Leading Market Players |
|---|
| Evonik Industries AG |
| 3A Composites GmbH |
| Diab International AB |
| Gurit Holdings AG |
| Hexcel Corporation |
| Armacell International |
| The Gill Corporation |
| Euro-Composites |
| Changzhou Tiansheng New Materials Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Balsa plantation harvest cycles cascade through Atlantic shipping lanes into aerospace-grade core pricing tiers, with Diab International AB's vertically integrated Ecuadorian estates anchoring premium quotations while spot-market PVC foam trades at compressed margins in Asian wind energy procurement channels.
Pricing Analysis
Volume scale separates contract structures across the market. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and raw material provenance. Pricing pressure stems from buyer consolidation among Airbus and Boeing procurement teams extending payment terms for qualified suppliers. Wind energy OEMs exhibit highest price sensitivity, accepting medium-density PET foam substitutions that sacrifice marginal performance for unit cost reduction.
Supply Chain Analysis
Scrap balsa recovery and offcut reprocessing into lower-grade construction cores create reverse-logistics value streams that subsidize plantation economics. Ecuador, Papua New Guinea, and Indonesia concentrate balsa raw material supply. Foam core production draws from petrochemical feedstocks, isocyanate precursors, and extrusion equipment. Single-source vulnerability runs through Atlantic shipping bottlenecks and weather-driven harvest volatility. Distribution runs through tiered supplier networks with approved vendor lists gating aerospace-qualified channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airworthiness certification backlog functions as the binding capacity constraint, propping pricing power for qualified incumbents while locking challengers out of primary aerospace contracts.
For Market Incumbents: Lock in long-term balsa plantation leases and PET foam extrusion capacity before dual carbon implementation tightens energy cost structures in coastal Chinese provinces. Certification inertia protects honeycomb positions in flight control surfaces, but PMI foam substitution in hydrogen vessel applications demands R&D redirection. Backward integration into raw material security remains the critical defensive lever. For New Entrants and Emerging Players: Launch via direct technical service partnerships with mid-scale wind blade manufacturers seeking resin infusion compatibility testing outside approved vendor list constraints. Brazil's ANEEL-driven domestic content requirements and Ceará manufacturing clusters offer the most penetrable geography. Position around balsa-foam hybrid formulations for offshore blade spar caps. For Investors and Strategic Acquirers: Airbus and Boeing dual-sourcing announcements for next-generation narrowbody programs are the leading indicator that certification capacity scarcity will persist, underwriting long-term margin structures for qualified suppliers. Acquisition targets should screen for captive plantation access or established FAA/EASA test data libraries. Watch for MEE enforcement actions triggering facility relocation among Chinese PET foam producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Secures balsa supply continuity against Atlantic shipping disruptions and climate volatility. |
| PMI Foam Certification for Cryogenic Applications | Captures hydrogen storage vessel specifications as emerging energy infrastructure scales. |
| Resin Infusion Compatibility Testing Expansion | Accelerates PET foam adoption in Vestas and Siemens Gamesa blade root sections. |
| Dual Carbon Compliance Facility Relocation | Relocates extrusion operations to Sichuan hydroelectric baseload under MEE benchmarks. |
| Intumescent Coating Development Partnership | Addresses FAR 25.853 evolution for electric aircraft battery enclosure fire resistance. |
Study Parameters
Independent corroboration across supply chain managers at tier-one aerospace primes, procurement directors at wind turbine OEMs, and technical service leads at core material suppliers underwrites the qualitative findings. Primary fieldwork engaged plant managers at PET foam extrusion facilities, composite R&D directors at Fraunhofer Institute partnerships, and distribution channel partners serving marine and construction end-uses. Secondary validation drew from FAA certification databases, ECHA REACH substance restriction filings, and customs trade data tracking balsa and foam core shipments. Bottom-up demand modeling triangulated against top-down capacity assessments across Atlantic and Asia-Pacific production hubs.
Rate-of-change decomposition across material substitution trajectories, certification timeline compression, and regional regulatory implementation schedules structured the analytical framework. Segmentation dimensions spanned material chemistry, density grade, end-use application, and manufacturing process intensity. CAGRs derived from installed capacity expansion plans, procurement contract visibility windows, and historical penetration curves for foam core substitution in wind energy applications. Hydrogen vessel certification pathways and electric aircraft battery enclosure fire-resistance testing protocols served as industry-specific forecast inputs.
Regulatory enforcement variance, raw material harvest disruption, and aerospace program delay are the dominant revision risks to the projection framework. Forecasts reflect documented assumptions regarding certification timeline elasticity and substitution elasticity between balsa and synthetic foam cores. Material deviation in ECHA enforcement intensity, ANEEL auction outcomes, or FAA rulemaking schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
FRP Tanks Market
Composite Materials
Wind Turbine Composites Market
Composite Materials
United States Marine Composites Market
Composite Materials
Composite Adhesives Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Thermoplastic Prepreg Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Low Temperature Sealing Glass Composite Powder Market
Composite Materials
Green Composites Market
Composite Materials
Balsa Core Materials Market
Composite Materials
Composite Cans Market
Composite Materials
Expandable Graphite Market
Composite Materials
Composite Market
Composite Materials
Composite Metal Finishing Market