
 Temporary Bonding Adhesives Market | 2026-2036
Temporary Bonding Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Temporary Bonding Adhesives Market Outlook
Software-defined process control and predictive maintenance subscriptions for bonding equipment is realigning how adhesive vendors capture lifetime value. 3M Company leverages its materials science depth to anchor premium film-format temporary bonding solutions for wafer-level packaging. Henkel Corporation competes through specialized thermal release formulations that sustain foundry qualification cycles. Dow Inc. differentiates via silicone chemistry leadership, occupying high-temperature process niches where debonding integrity is critical.
Temporary bonding adhesives are thermoplastic or thermoset formulations applied to mechanically secure device wafers to carrier substrates during backside processing, with typical debonding temperatures ranging from room-temperature solvent release to 200°C thermal slide mechanisms. The primary industrial purpose is enabling ultrathin wafer handling without fracture during grinding, etching, and metallization steps. Acrylic formulations lead in cost-sensitive packaging applications where moderate thermal budgets apply, while epoxy segments command margin pools in high-reliability automotive and aerospace bonding scenarios. Liquid delivery modes dominate high-volume semiconductor fabrication lines, though film formats are gaining traction in advanced packaging where thickness uniformity directly impacts yield.
EPA regulations in the United States restrict volatile organic compound emissions from adhesive manufacturing, pushing reformulation toward waterborne and UV-curable platforms. REACH registration requirements in Europe mandate full substance disclosure for imported chemistries, creating compliance barriers for non-EU suppliers. FDA oversight applies where temporary bonding adhesives contact medical device components during assembly. Stakeholders must monitor evolving dual-use export controls on semiconductor materials and decide whether to qualify multiple regional supply sources before qualification windows tighten.
Market Dynamics
Advanced packaging architectures—fan-out wafer-level packaging and 3D stacking—are compressing debonding temperature windows while demanding higher mechanical integrity during thinning operations.
Growth Catalysts
- Semiconductor packaging densification:Heterogeneous integration roadmaps from foundries in Taiwan and South Korea are mandating temporary bonding for ultrathin wafer handling below 50 micrometers.
- REACH substance registration:ECHA's full disclosure requirements for imported chemistries are accelerating qualified supplier consolidation among European device manufacturers.
- UV-curable platform adoption:Waterborne and radiation-cured formulations are capturing share in cost-sensitive packaging lines where thermal slide debonding adds process steps.
Market Restraints
- Specialty monomer supply concentration:Acrylic acid and epoxy resin precursors cluster among petrochemical complexes in China and the US Gulf Coast, exposing formulators to feedstock volatility.
- Qualification cycle duration:Foundry and OSAT adhesive qualification protocols extend 18-24 months, freezing incumbent positions and delaying new entrant revenue.
- Thermal budget compression:Low-temperature debonding chemistries sacrifice cohesive strength, limiting applicability in high-stress grinding operations for power semiconductors.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme incentives for domestic fabs in Gujarat and Assam are creating first-mover qualification opportunities for adhesive suppliers before supplier lists close.
- Medical device microassembly:FDA-regulated temporary bonding for catheter and implantable component handling represents an adjacent vertical with premium pricing tolerance.
- Laser debonding convergence:Integration of UV laser release mechanisms with thermoplastic adhesives is enabling room-temperature carrier separation for temperature-sensitive device layers.
Industry Challenges
- Process engineer scarcity:Wafer-level packaging expertise concentrates among veteran technicians in Taiwan and South Korea, constraining fab expansion timelines in emerging manufacturing regions.
- Dual-use export control navigation:US Bureau of Industry and Commerce restrictions on semiconductor materials to specific foundries are forcing suppliers to maintain parallel formulation portfolios with divergent supply chain documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temporary Bonding Adhesives Market |
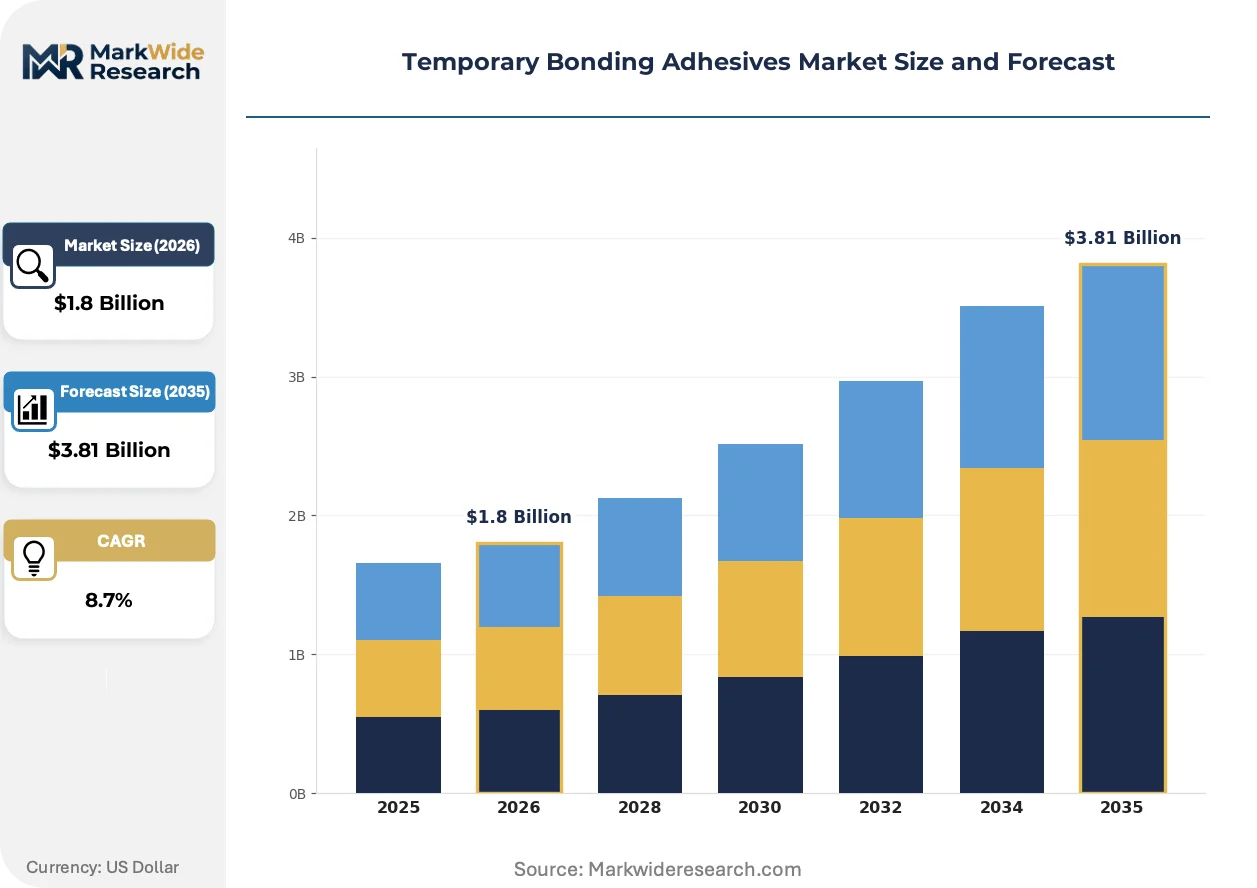
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Silicone, Epoxy Application: Automotive, Electronics, Packaging, Construction End User: Manufacturers, Contractors, OEMs, Retailers Delivery Mode: Aerosol, Liquid, Paste, Film |
| Companies Covered | AI Technology, Inc., YINCAE Advanced Materials, 3M Company, Dow Inc., SUSS MicroTec, Henkel Corporation, Daxin Materials, Nitto Denko, Brewer Science, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temporary Bonding Adhesives Market Strategic Shifts
Temporary bonding chemistry is bifurcating between thermal release systems for high-volume logic and solvent-release platforms for compound semiconductors with temperature-sensitive epitaxial layers.
Silicone-based temporary bonding adhesives are absorbing process thermal loads exceeding 200°C while maintaining clean debonding surfaces for subsequent metallization steps. Power semiconductor manufacturers in automotive qualification pipelines are adopting these chemistries fastest, with thermal slide mechanisms replacing mechanical peel methods that risk die fracture. This absorption of extreme thermal stress is compressing the viable formulation space for acrylic alternatives in high-reliability segments.
EPA volatile organic compound emission limits under the Clean Air Act are forcing manufacturing facility retrofits among US-based adhesive producers. Reformulation investments are redirecting capital toward UV-curable and waterborne platforms that eliminate solvent-based coating operations. Semiconductor packaging lines in Oregon and Arizona are experiencing the tightest compliance timelines as state implementation plans accelerate beyond federal minimums.
After-sales service unbundling is separating equipment maintenance contracts from adhesive supply agreements in advanced packaging lines. OSAT procurement teams in Singapore and Penang are negotiating standalone technical service subscriptions that provide predictive debonding failure monitoring without exclusive chemical purchasing commitments. This behavioral shift is most pronounced among mid-tier packaging houses seeking to diversify supplier risk while retaining process expertise access.
Temporary Bonding Adhesives Market Segmentation
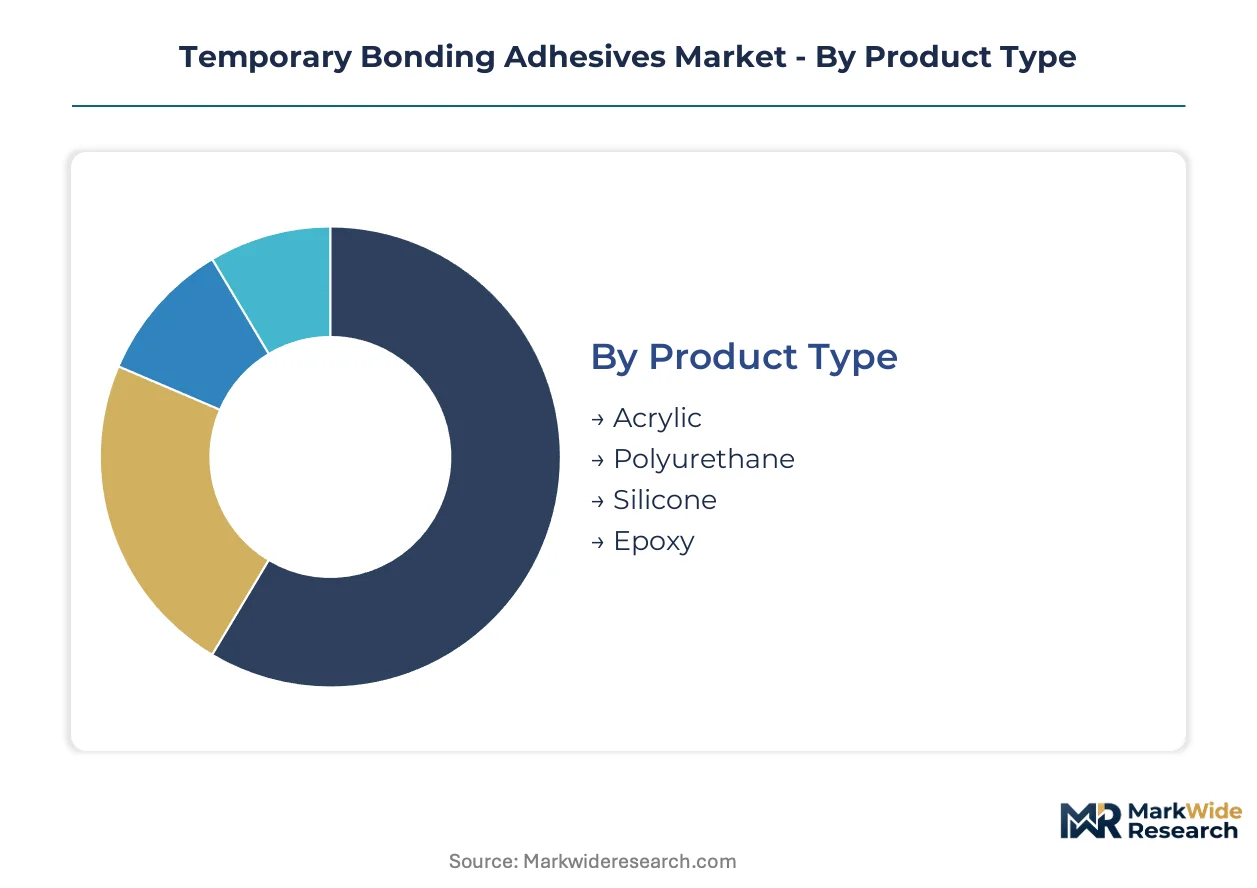
Segmentation in temporary bonding adhesives reveals how formulation chemistry, application thermal budgets, and delivery format interact to determine supplier selection criteria. Buyers prioritize debonding temperature compatibility with device architectures above raw material cost.
Product Type:
Cost tier and thermal performance requirements dominate procurement decisions across packaging lines.
- Acrylic:Thermoplastic formulations offer solvent-release or moderate thermal debonding below 150°C. Cost-sensitive packaging applications in mainland China and Southeast Asia favor these chemistries where grinding stress remains moderate.
- Silicone:Elastomeric networks withstand thermal slides exceeding 200°C while leaving residue-free surfaces. Power semiconductor manufacturers in automotive qualification pipelines specify silicone for high-stress thinning operations where cohesive strength preservation is mandatory.
- Polyurethane:Hybrid thermoset-thermoplastic behavior enables tailored modulus control for compound semiconductor handling.
- Epoxy:Crosslinked architectures deliver highest mechanical integrity for aerospace and defense bonding scenarios demanding thermal cycling resistance.
Volume sits with acrylic formulations; growth tilts toward silicone as power device packaging expands.
Application:
End-use thermal budgets and reliability requirements fragment demand across industrial verticals.
- Electronics:Semiconductor packaging lines in Taiwan, South Korea, and mainland China consume the majority of temporary bonding adhesives. Fan-out wafer-level packaging architectures mandate sub-50 micrometer wafer handling where debonding integrity directly impacts yield.
- Automotive:Power module assembly for electric traction inverters requires adhesives surviving 200°C thermal slides during backside metallization. Tier-1 suppliers in Germany and Japan specify silicone formulations for silicon carbide device packaging.
- Packaging:Flexible electronics and display lamination employ lower-temperature release systems.
- Construction:Temporary panel fixation and surface protection applications utilize cost-optimized acrylic aerosols.
Electronics commands the dominant share; automotive applications are climbing the fastest as wide-bandgap semiconductor adoption accelerates.
End User:
Procurement sophistication and qualification cycle tolerance separate customer tiers.
- Manufacturers:Integrated device manufacturers and foundries operate 18-24 month adhesive qualification protocols that freeze incumbent positions. Direct technical collaboration with formulators enables custom rheology tuning for specific grinding equipment.
- OEMs:Original equipment manufacturers in medical device and aerospace verticals specify temporary bonding adhesives through subsystem supplier mandates rather than direct procurement.
- Contractors:Construction and renovation specialists prioritize immediate availability and application speed over formulation customization.
- Retailers:Consumer-facing channels stock standardized aerosol and liquid formats for DIY and light industrial maintenance.
Qualification intensity concentrates with manufacturers; retailer channels are expanding most quickly in emerging Asian markets.
Delivery Mode:
Process integration requirements and thickness uniformity demands shape format selection.
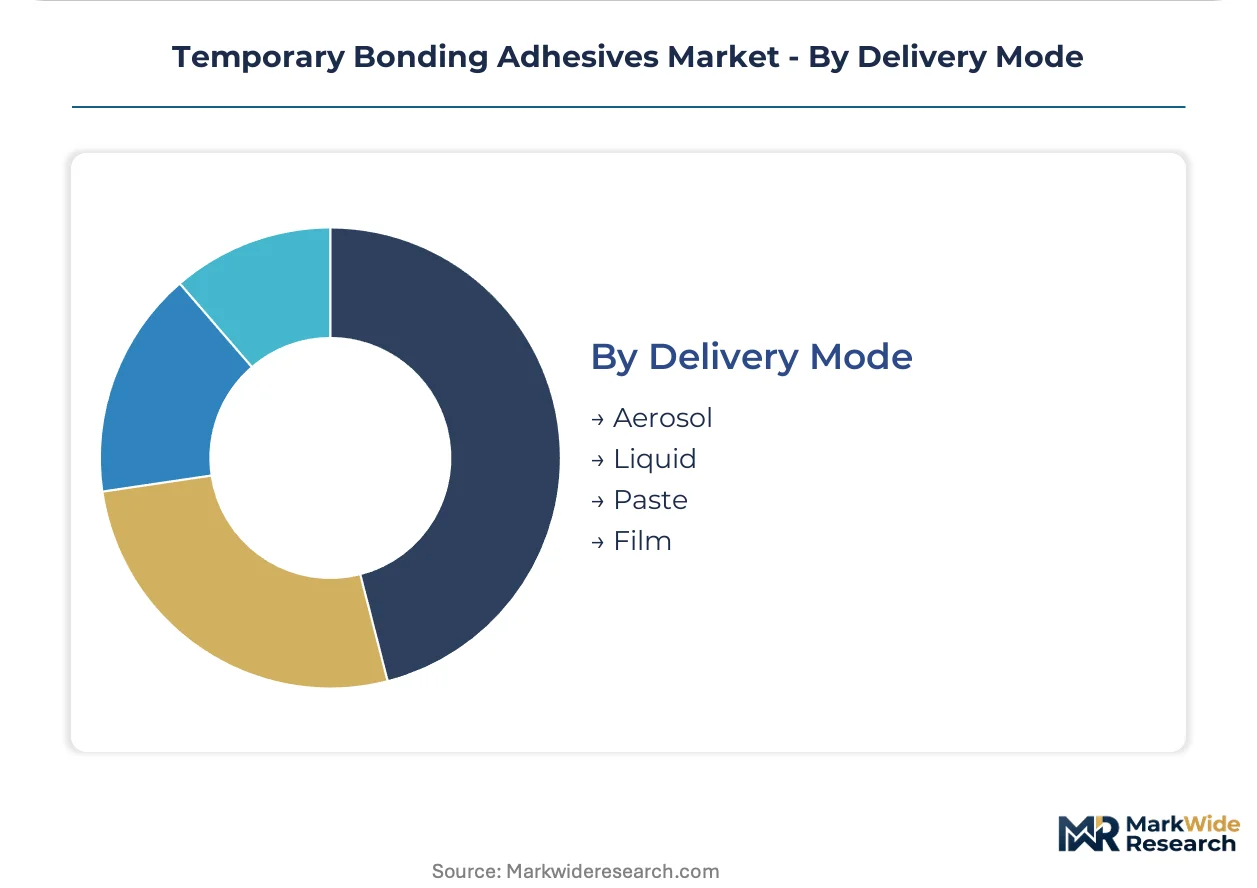
- Liquid:Spin-coat and dispense systems dominate high-volume semiconductor fabrication lines. Established infrastructure in Taiwan and South Korean foundries perpetuates liquid preference despite film format advances.
- Film:Pre-cast layers deliver thickness uniformity critical for advanced packaging yield. OSAT facilities in Singapore and Penang are retrofitting lamination equipment to capture film-format benefits for heterogeneous integration.
- Aerosol:Spray application suits construction and maintenance scenarios requiring rapid coverage of irregular geometries.
- Paste:Trowel-grade consistency enables manual application in prototype and repair environments.
Liquid retains volume leadership; film formats are gaining share fastest as advanced packaging capital investment intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors temporary bonding adhesive consumption as Taiwan Semiconductor Manufacturing Company scales 3D packaging capacity. Foundry clustering in Tainan and Taichung feeds continuous demand for thermal release formulations.
United States
Intel's Oregon and Arizona fabs drive adhesive qualification for advanced packaging nodes. EPA Clean Air Act enforcement accelerates waterborne formulation transitions among domestic suppliers. Austin and Phoenix metro areas concentrate OSAT investment requiring sub-50 micrometer wafer handling solutions.
China
SMIC and Hua Hong Semiconductor expand mature-node capacity in Shanghai and Wuxi. MIIT domestic substitution policies favor qualified local adhesive formulators for state-backed fabs. Yangtze River Delta clustering around Suzhou and Hangzhou absorbs the majority of regional temporary bonding volume.
South Korea
Samsung Foundry and SK Hynix mandate silicone-based formulations for high-bandwidth memory stacking. MFDS chemical substance notification requirements extend qualification timelines for imported adhesives. Pyeongtaek and Yongin semiconductor complexes dominate regional consumption patterns.
Germany
Bosch and Infineon specify thermal slide adhesives for silicon carbide power module packaging. REACH registration obligations filter supplier pools toward ECHA-compliant formulators. Dresden and Regensburg microelectronics corridors concentrate automotive-qualified adhesive demand.
Japan
Tokyo Electron and SCREEN Semiconductor Solutions integrate adhesive process modules for domestic packaging lines. METI supply chain resilience programs incentivize dual-sourcing from qualified Japanese formulators. Kyushu Island foundry expansion in Kumamoto drives incremental thermal release chemistry consumption.
Temporary Bonding Adhesives Market Competitive Environment
Capital-heavy producers compete with asset-light designers for specification control in temporary bonding adhesive selection. The market exhibits tiered consolidation with three to five qualified suppliers dominating foundry approval lists per geography. Strategic archetypes separate materials science conglomerates, semiconductor equipment integrators, and regional specialty formulators. Incumbents defend positions through foundry qualification lock-in while challengers pursue laser debonding chemistry convergence.
Within the materials science tier, 3M Company and Dow Inc. exemplify scale-driven formulation depth. SUSS MicroTec occupies equipment-integrated positioning where process module sales bundle adhesive recommendations. Henkel Corporation sits within the industrial adhesive specialist archetype with thermal release expertise. These three anchors demonstrate how competitive positioning fragments across chemistry leadership, equipment integration, and application specialization vectors.
| Leading Market Players |
|---|
| AI Technology, Inc. |
| YINCAE Advanced Materials |
| 3M Company |
| Dow Inc. |
| SUSS MicroTec |
| Henkel Corporation |
| Daxin Materials |
| Nitto Denko |
| Brewer Science, Inc. |
| Others |
Value Chain & Pricing Dynamics
Laser debonding chemistry convergence is simultaneously compressing formulation premiums and redrawing supplier qualification maps, as foundries in Taiwan and South Korea demand room-temperature release systems that obsolete thermal slide equipment investments. This technology shift forces acrylic and silicone formulators to recalibrate pricing models around yield guarantees rather than material throughput.
Pricing Analysis
Yield-based pricing anchors procurement negotiations, with adhesive suppliers guaranteeing defect rates below threshold levels during carrier separation. Three-tier pricing structure across premium, standard, and economy levels separates silicone formulations for automotive qualification from acrylic alternatives for consumer packaging. Price differentiation rests on ECHA REACH registration status and thermal budget compatibility. Cost compression in mid-tier acrylic segments is intensifying because Chinese domestic formulators are qualifying under MIIT substitution policies. Contract manufacturers in Southeast Asia exhibit highest price sensitivity; IDMs in Germany and Japan tolerate premium positioning for automotive-qualified silicone.
Supply Chain Analysis
Dual-sourcing requirements from Bosch and Infineon are mandating parallel qualification tracks for silicone precursors across Germany, Japan, and the United States. Acrylic acid and epoxy resin feedstocks draw from petrochemical complexes in China and the US Gulf Coast, exposing formulators to feedstock volatility. Single-source vulnerability concentrates in specialty monomer synthesis for high-temperature silicone networks. Distribution runs through foundry-approved chemical distributors in Hsinchu and Pyeongtaek, with direct technical service contracts increasingly unbundled from material supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with formulators pursuing backward integration into specialty monomer synthesis to escape petrochemical price volatility and qualification delays.
For Market Incumbents: Deepen foundry qualification lock-in by embedding predictive debonding monitoring into adhesive supply agreements, countering the unbundling trend among OSAT procurement teams in Singapore and Penang. Expand captive production of thermal release additives in Taiwan to shorten qualification cycles threatened by MFDS notification delays for imported chemistries. For New Entrants and Emerging Players: Begin with laser debonding chemistry convergence for compound semiconductor applications, where temperature-sensitive epitaxial layers create specification gaps that thermal release incumbents cannot address without reformulation. Target medical device microassembly in FDA-regulated verticals, where premium pricing tolerance exceeds semiconductor packaging norms. Pursue technical service subscription models that decouple expertise access from exclusive chemical purchasing. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by materials science conglomerates seeking semiconductor packaging exposure. Long-term viability favors formulators with dual ECHA REACH and MIIT qualification status, positioned for supplier consolidation among European device manufacturers. Watch for laser debonding equipment adoption curves as inflection indicator—penetration above threshold levels would accelerate thermal release chemistry obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive supply of acrylic acid precursors insulates margin pressure from US Gulf Coast petrochemical volatility. |
| Laser Debonding Chemistry Convergence | UV laser release compatibility opens room-temperature carrier separation for temperature-sensitive power semiconductor layers. |
| ECHA REACH Registration Acceleration | Full substance disclosure compliance filters supplier pools toward qualified formulators for Bosch and Infineon procurement. |
| Predictive Service Subscription Unbundling | Standalone technical monitoring contracts diversify supplier risk for OSAT facilities in Penang while retaining process expertise. |
| India PLI Scheme Qualification | First-mover adhesive approval for Gujarat and Assam fabs secures position before domestic supplier lists close. |
Study Parameters
Document review covered SEC 10-K filings from materials science conglomerates, ECHA REACH registration databases, and MIIT domestic substitution policy circulars, complemented by interviews with foundry process engineers, OSAT procurement leads, adhesive formulator R&D directors, and semiconductor equipment integration specialists. Secondary validation drew from customs trade data, SEMI equipment spending reports, and foundry capex disclosures. Bottom-up segment sizing and top-down market reconciliation provided cross-checks across the analysis window.
Historical volume trajectories were cross-referenced against panel input from packaging line operators to anchor growth assumptions. Segmentation dimensions modeled include formulation chemistry, debonding temperature tier, delivery format, and foundry qualification status across regional production clusters. CAGRs were derived from elasticity-adjusted demand projections incorporating heterogeneous integration roadmaps and wide-bandgap semiconductor adoption curves.
Underlying measurement precision varies by segment; silicone formulations for automotive qualification carry tighter precision than cost-optimized acrylic alternatives in consumer packaging. Forecasts reflect assumptions about foundry capacity expansion timelines and regulatory enforcement intensity. Deviation in laser debonding equipment penetration or REACH registration compliance costs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
North America Glue-Laminated Timber Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
Indonesia Adhesives Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
South America Epoxy Adhesives Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Middle-East and Africa Waterborne Adhesives Market