
 Short Fiber Thermoplastic Composites Market | 2026-2036
Short Fiber Thermoplastic Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Short Fiber Thermoplastic Composites Market Analytics
Automotive-grade fiber loading specifications above 30% by weight is collapsing the gap between metal stampings and polymer substitutes in under-the-hood applications. BASF SE leverages its Ludwigshafen polymer compounding footprint to supply OEM-qualified material streams across Europe. SABIC anchors its position through backward integration into base resin production at Yanbu, giving it feedstock cost discipline competitors cannot match. Celanese Corporation specializes in long-fiber hybrid formulations that bridge short-fiber price points with structural performance.
Short fiber thermoplastic composites consist of chopped glass or carbon fibers, typically 0.2 to 6 millimeters in length, dispersed within a thermoplastic matrix and processed by injection molding or extrusion to achieve stiffness-to-weight ratios superior to unreinforced polymers. Polyamide formulations dominate structural parts demand due to their thermal stability and chemical resistance in powertrain environments, while polypropylene compounds occupy high-volume interior components where cost sensitivity limits specification upgrades. Injection molding technology leads unit economics for complex geometries, though compression molding is gaining traction in exterior panels where fiber orientation control improves surface finish.
EPA fuel economy standards and the EU Green Deal's embodied carbon tracking rules are tightening material selection criteria for vehicle platforms sold across North America and Europe. REACH chemical registration requirements and China's GB standards for automotive plastics govern market access for compounders serving multinational OEMs. Japan's METI circular economy guidelines for industrial plastics are reshaping post-consumer recycling mandates for fiber-reinforced materials. Stakeholders must monitor regulatory divergence between jurisdictions where compliance costs fragment supply chain configurations.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating metal-to-polymer substitution to meet EU fleet emissions rules and Japan's fuel economy standards, compressing qualification timelines and reshaping supplier qualification hierarchies across the value chain.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Vehicle platforms sold across Europe now face material selection criteria that favor lightweight composites over stamped metal in under-the-hood applications.
- China's Yangtze River Delta manufacturing cluster:Injection molders serving domestic EV producers concentrate demand for polyamide formulations with thermal stability for powertrain environments.
- Glass-fiber reinforced polyamide:Loadings above 30% by weight deliver stiffness-to-weight ratios that collapse the performance gap with aluminum stampings in structural brackets and housings.
Market Restraints
- Base resin cost volatility:Polyamide and polypropylene feedstock prices fluctuate with naphtha and propylene chain dynamics, compressing compounder margins during upstream spikes.
- REACH chemical registration complexity:ECHA requirements for fiber-reinforced materials create compliance friction for compounders serving multinational OEMs with divergent formulation standards.
- Long-fiber thermoplastic substitution:Hybrid formulations bridge short-fiber price points with structural performance, threatening volume in load-bearing applications above 15 kilograms per part.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic EV production incentives create virgin demand for localized compounding capacity serving Maruti Suzuki and Tata Motors platforms.
- Recycled carbon fiber integration:Pyrolysis-recovered fiber dispersed in thermoplastic matrices opens circular economy positioning for compounders ahead of Japan's METI industrial plastics guidelines.
- Direct OEM qualification pipelines:Tier 1 suppliers are bypassing traditional distributor channels to secure captive material streams with locked volume commitments.
Industry Challenges
- Fiber orientation control expertise:Compression molding for exterior panels requires rheology engineering talent scarce in legacy injection molding operations.
- Multi-jurisdiction certification timelines:Simultaneous EPA, ECHA, and GB standard compliance stretches R&D bandwidth for mid-cap compounders.
- Post-consumer recycling infrastructure:Fiber-reinforced thermoplastic recovery lacks scaled mechanical or chemical pathways, complicating OEM circularity pledges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Short Fiber Thermoplastic Composites Market |
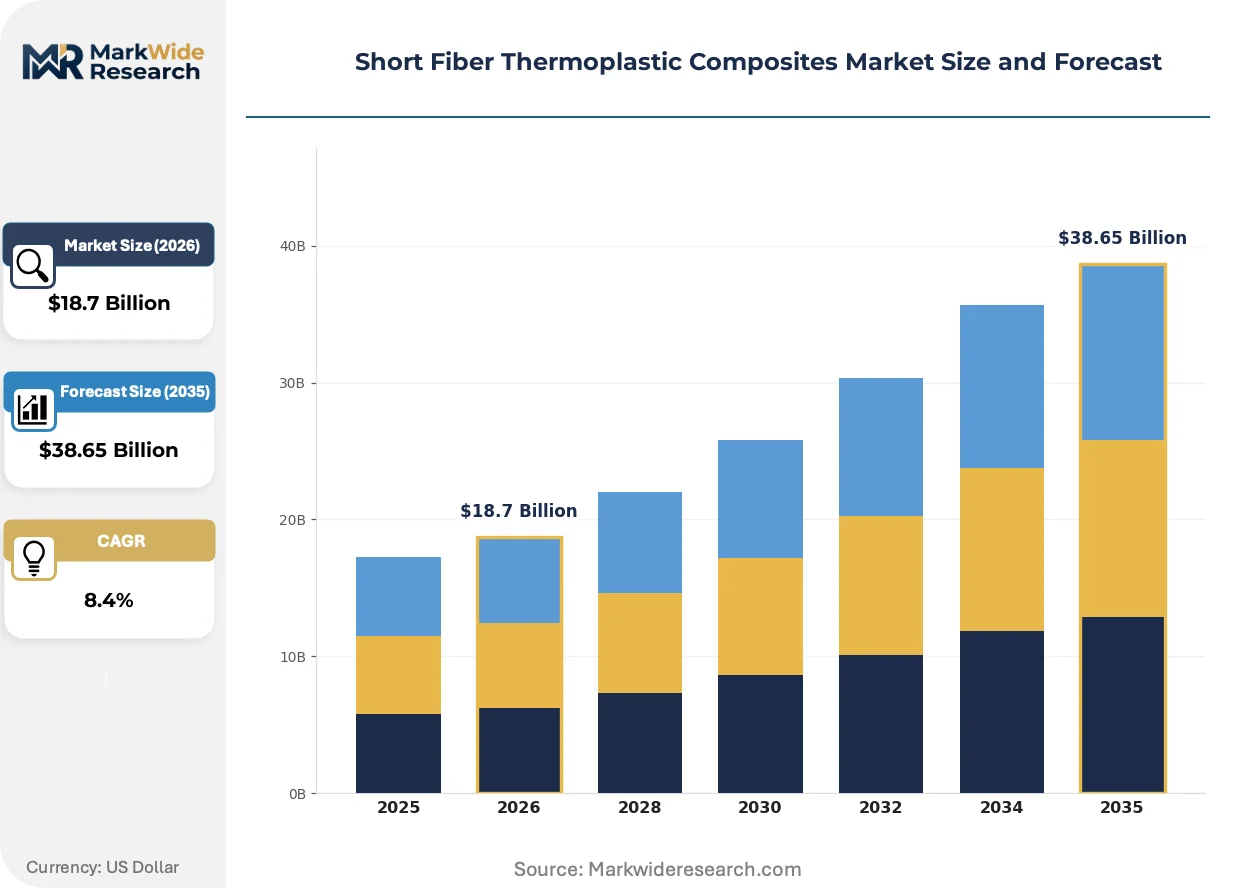
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Polyamide, Polycarbonate End User: Automotive, Aerospace, Consumer Goods, Electronics Technology: Injection Molding, Thermoforming, Extrusion, Compression Molding Application: Structural Parts, Interior Components, Exterior Panels, Electrical Enclosures |
| Companies Covered | BASF SE, SABIC, Celanese Corporation, LANXESS AG, Avient Corporation, Solvay, DuPont, DSM, SGL Carbon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Short Fiber Thermoplastic Composites Market Evolving Landscape
Material science advances and regulatory tightening are converging to redefine performance benchmarks and procurement patterns across automotive, industrial, and consumer end-uses.
Hybrid long-short fiber formulations are fragmenting the traditional dichotomy between injection-molded commodity compounds and compression-molded structural prepregs. Tier 1 automotive suppliers in Stuttgart and Nagoya are piloting these materials for battery tray brackets and motor housings. The technology is fragmenting established supplier tiers by enabling mid-cap compounders to bid on previously inaccessible structural programs.
REACH authorization requirements for certain flame retardant additives are forcing reformulation of interior-grade polypropylene compounds. Compounders serving European OEMs must validate halogen-free alternatives without sacrificing UL94 V-0 ratings. The policy shift most affects high-volume dashboard and door panel applications where cost sensitivity limits specification upgrades.
Buyers are consolidating qualified supplier lists from twelve-plus vendors to four or five strategic partners with captive resin production and regional compounding footprints. Procurement teams at German OEMs now demand mill certificate traceability from polymerization through final pellet. This concentration is most visible in powertrain applications where BASF and SABIC have secured multi-platform supply agreements.
Short Fiber Thermoplastic Composites Market Segmentation
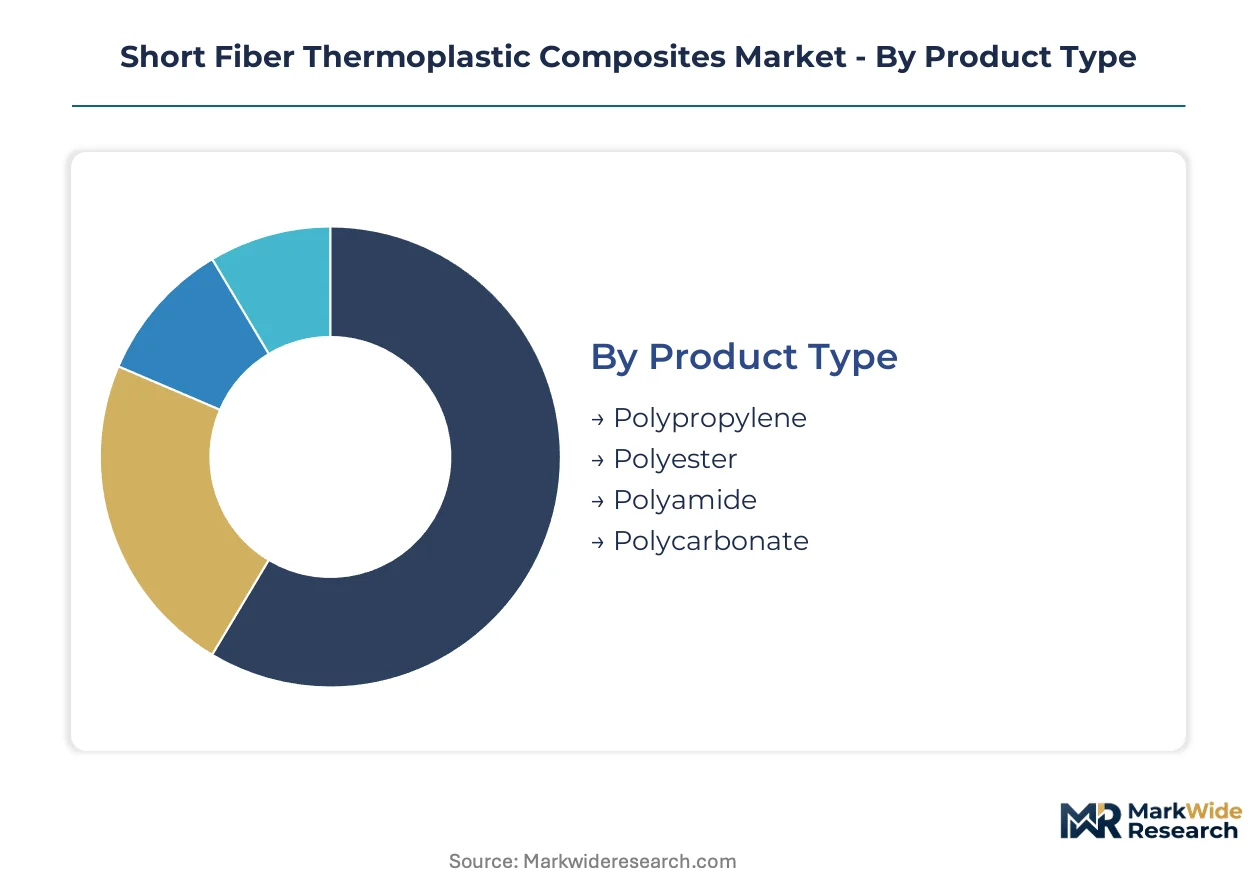
Material selection criteria diverge sharply across end-use environments, with thermal stability thresholds and fiber loading specifications dictating resin-matrix pairings. Procurement teams segment suppliers by compounding technology and regional certification footprints rather than commodity resin pricing alone.
Product Type:
Margin pools concentrate in formulations qualifying for under-the-hood automotive specifications, where thermal cycling resistance commands formulation premiums.
- Polyamide:Glass-fiber loadings above 30% by weight deliver stiffness-to-weight ratios that collapse the performance gap with aluminum stampings in powertrain brackets and housings. Demand concentrates in Germany's automotive OEM supply chain, where EU fleet emissions rules accelerate metal-to-polymer substitution in thermal management modules.
- Polypropylene:Cost-driven formulations dominate high-volume interior components where specification upgrades face procurement resistance. China's Yangtze River Delta manufacturing cluster anchors volume for domestic EV producers seeking dashboard and door panel materials with halogen-free flame retardancy under GB standards.
- Polycarbonate:Optical clarity combined with dimensional stability serves headlamp housings and transparent armor applications.
- Polyester:Lower-cost alternative for non-structural industrial components with moderate thermal exposure requirements.
The dominant share belongs to Polyamide, while Polypropylene is closing the gap fastest through EV interior platform proliferation.
End User:
Application-specific certification timelines fragment supplier hierarchies, with automotive qualification pipelines stretching 18-36 months versus consumer goods cycles.
- Automotive:Structural brackets, battery housings, and under-the-hood components drive specification intensity. OEMs in Stuttgart and Nagoya compress qualification timelines to meet Japan's fuel economy standards and EU Green Deal embodied carbon tracking requirements.
- Electronics:Miniaturized connectors and housings demand tight dimensional tolerance control. Japan's METI circular economy guidelines for industrial plastics reshape post-consumer recycling mandates for fiber-reinforced materials in this segment.
- Aerospace:Interior cabin components and secondary structures balance flammability ratings against weight reduction targets.
- Consumer Goods:Power tool housings and appliance components prioritize cost-positioning over structural performance thresholds.
Automotive commands the largest revenue pool, though Electronics is expanding most quickly through 5G infrastructure connector demand.
Technology:
Capital equipment intensity and cycle time economics determine process selection, with fiber orientation control emerging as a technical differentiator.
- Injection Molding:Complex geometries achieve unit cost minima through high-speed cycling. The Yangtze River Delta cluster concentrates installed capacity serving domestic Chinese EV producers with polyamide powertrain components.
- Compression Molding:Exterior panel applications favor this technology where fiber orientation control improves surface finish quality. Tier 1 suppliers in Germany pilot these methods for battery tray programs requiring Class A surface specifications.
- Extrusion:Continuous profiles for structural sections and electrical conduit applications.
- Thermoforming:Large-area shallow-draw components with moderate structural requirements.
Injection Molding retains volume leadership, while Compression Molding gains share fastest through exterior panel qualification wins.
Application:
Performance thresholds and regulatory exposure vary dramatically, with structural parts facing the most stringent multi-jurisdiction certification burdens.
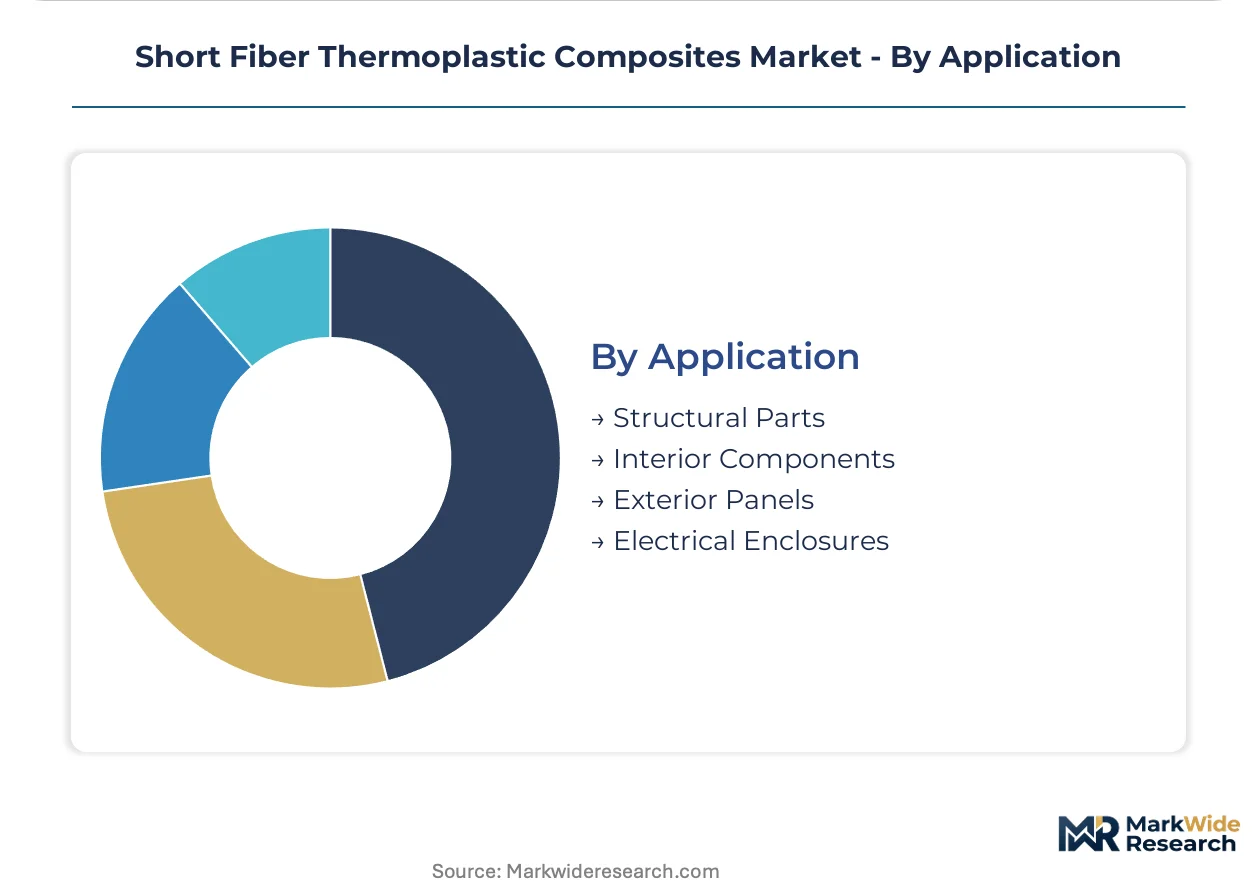
- Structural Parts:Load-bearing brackets and housings require fiber loadings above 30% by weight to meet stiffness specifications. EPA fuel economy standards and EU fleet emissions rules tighten material selection criteria for vehicle platforms across North America and Europe.
- Interior Components:Dashboard assemblies and door panels balance cost sensitivity against REACH chemical registration requirements for flame retardant additives. European OEMs demand halogen-free alternatives without sacrificing UL94 V-0 ratings.
- Exterior Panels:Surface finish quality and UV stability requirements limit qualified supplier pools.
- Electrical Enclosures:Dielectric properties and thermal management specifications govern resin selection.
Structural Parts holds the dominant position, though Interior Components is climbing the fastest through EV platform interior redesign cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Germany, China, and Japan dominate global trade in short fiber thermoplastic composites, while import dependence in India and Mexico creates localization opportunities for compounders seeking tariff-advantaged supply positions.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive demand for glass-fiber reinforced polyamide in thermal management modules. EU Green Deal embodied carbon tracking rules tighten material selection criteria for vehicle platforms sold across Europe. The BASF Ludwigshafen complex anchors regional compounding capacity with captive polymerization and qualification pipelines serving multi-platform supply agreements.
China
Domestic EV producers in the Yangtze River Delta manufacturing cluster concentrate injection molding demand for polyamide powertrain components. GB standards for automotive plastics govern market access for compounders serving multinational OEMs with localized production. Shanghai and Suzhou house the densest concentration of qualified molders serving BYD, NIO, and XPeng platform requirements.
Japan
Toyota and Honda accelerate metal-to-polymer substitution to meet METI fuel economy standards and circular economy guidelines for industrial plastics. JIS standards and post-consumer recycling mandates reshape fiber-reinforced material specifications across automotive and electronics segments. Nagoya-based Tier 1 suppliers pilot hybrid long-short fiber formulations for battery tray brackets and motor housings.
United States
EPA fuel economy standards drive lightweighting adoption in Detroit Three powertrain programs. NHTSA safety regulations and state-level emissions rules fragment compliance requirements across the manufacturing footprint. Michigan and Ohio host qualified compounder operations serving Ford, GM, and Stellantis under-the-hood specifications with regional resin sourcing.
India
Maruti Suzuki and Tata Motors expand domestic EV production under the PLI scheme for automotive, creating virgin demand for localized compounding capacity. BIS certification requirements and DGFT import tariffs incentivize resin production investment near Chennai and Pune. The Delhi-Mumbai Industrial Corridor attracts compounder greenfield projects targeting captive supply to emerging EV platforms.
Short Fiber Thermoplastic Composites Market Competitive Landscape
Listed leaders compete with private specialists across resin production and compounding technology, creating a tiered structure where scale-driven public companies anchor premium qualification pipelines while private mid-caps capture niche formulation segments. The market consolidates around three strategic archetypes: integrated resin-to-compound operators, independent compounders with regional certification footprints, and hybrid specialists bridging short-fiber price points with structural performance. Dominant competitive moves include backward integration into base resin production and direct OEM qualification pipelines that bypass traditional distributor channels.
Within the integrated resin-to-compound tier, BASF SE and SABIC exemplify archetypes with polymerization assets feeding qualified material streams. SABIC anchors its position through upstream control over base resin production at Yanbu. Celanese Corporation occupies a specialist position in hybrid formulation development. Among European-based compounders, LANXESS AG and Solvay sit within the premium-tier vector serving powertrain specifications.
| Leading Market Players |
|---|
| BASF SE |
| SABIC |
| Celanese Corporation |
| LANXESS AG |
| Avient Corporation |
| Solvay |
| DuPont |
| DSM |
| SGL Carbon |
| Others |
Value Network & Pricing Analysis
REACH chemical registration requirements gate both supplier qualification and price differentiation simultaneously, as ECHA compliance costs fragment formulation standards across European OEM supply chains while creating tiered access premiums for pre-registered compounders.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across automotive-grade certification, volume scale, and captive resin production tiers. Price differentiation rests on fiber loading specifications above 30% by weight and direct OEM qualification pipelines versus distributor-mediated supply. Cost compression in interior-grade polypropylene compounds is intensifying because REACH flame retardant reformulation burdens compounders with validation expenses. High-volume dashboard assemblers exhibit the greatest price sensitivity, while powertrain specification teams prioritize thermal stability over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes compound feedstock delivery uncertainty for naphtha-dependent polyamide compounders. Manufacturing gravity centers on Germany, China, and Japan, where BASF Ludwigshafen, Yangtze River Delta molders, and Nagoya Tier 1 suppliers anchor regional capacity. Raw material draws from Saudi Arabian base resin production, pyrolysis-recovered carbon fiber streams, and glass fiber roving from specialized melt facilities. Single-source vulnerability concentrates in qualified polymerization assets serving multi-platform OEM agreements. Distribution runs through captive material streams with locked volume commitments bypassing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where 18-36 month OEM qualification timelines and divergent multi-jurisdiction certification standards create switching costs that protect incumbent positions.
For Market Incumbents: Fortify backward integration into base resin production to match SABIC's Yanbu feedstock cost discipline and defend margin position against long-fiber thermoplastic substitution threats. Expand captive compounding capacity in India's Delhi-Mumbai Industrial Corridor ahead of PLI scheme localization mandates. Prioritize fiber orientation control expertise acquisition for compression molding exterior panel programs. For New Entrants and Emerging Players: Differentiate on recycled carbon fiber integration capabilities ahead of Japan's METI circular economy guidelines implementation. Target India's nascent domestic EV compounding demand where Maruti Suzuki and Tata Motors platforms lack localized qualified supply. Pursue direct OEM qualification pipelines for battery tray bracket applications using hybrid long-short fiber formulations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid formulation development and multi-jurisdiction certification infrastructure. Viability over the medium-term projection horizon favors acquisition of mid-cap compounders with regional certification footprints in underserved production clusters. Monitor pyrolysis-recovered fiber cost curves as inflection signal for circular economy positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Resin | SABIC's Yanbu polymerization assets demonstrate feedstock cost discipline competitors cannot replicate. |
| Direct OEM Qualification Pipelines | BASF secures multi-platform supply agreements bypassing distributor channels for powertrain specifications. |
| Recycled Carbon Fiber Integration | Pyrolysis-recovered fiber dispersion opens circular economy positioning ahead of Japan's METI guidelines. |
| Hybrid Long-Short Fiber Formulation | Celanese bridges short-fiber price points with structural performance for battery tray bracket applications. |
| Regional Compounding Footprint Expansion | India's PLI scheme incentives attract greenfield projects targeting captive supply to emerging EV platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with polymer compounding plant managers, OEM platform engineers, Tier 1 supplier procurement leads, and distribution channel partners; and secondary validation through customs and trade flow databases, SEC 10-K filings of listed compounders, ACC and Cefic industry reports, and vehicle production registration data. Bottom-up triangulation across resin consumption volumes and top-down cross-check against OEM platform material specifications ensured convergence.
Across the modeling period, the analytical framework segmented by resin-matrix pairing, fiber loading tier, end-use application intensity, and regional production cluster. CAGRs derived from trend extrapolation of automotive lightweighting adoption curves, EV platform proliferation rates, and regulatory compliance cost trajectories. Industry-specific inputs included EPA fuel economy standard stringency schedules and EU Green Deal embodied carbon tracking implementation phases.
The analysis sits within stated boundaries; outcomes outside sustained OEM metal-to-polymer substitution momentum or stable naphtha-propylene feedstock pricing would require recalibration. Forecasts reflect assumptions around qualification timeline compression and multi-jurisdiction certification harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Carbon Thermoplastic Composites Market
Composite Materials
Global Closed Molding Composites Market
Composite Materials
Reinforced Carbon-Carbon Composite Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Phenolic Panel Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
Thermoset Composites Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
High Performance Carbon Fiber Precursor Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
Global Composite Resin Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Pultrusion Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Lignin-Based Graphene Market