
 White Carbon Black Market | 2026-2036
White Carbon Black Market Size, Share, and Industry Trends Forecast 2026-2036
White Carbon Black Market Analytics
ISO 9001 quality certification is reorganizing competitive access in precipitated silica manufacturing, favoring producers with validated process controls and traceable supply chains. Evonik Industries AG leverages its integrated fumed silica network across European and Asian production sites. Cabot Corporation sustains rubber-grade specialization through captive precipitated silica technology. Wacker Chemie AG anchors high-purity dispersions for electronics and personal care segments.
White carbon black, or precipitated and fumed silicon dioxide, functions as a reinforcing filler, rheology modifier, and anti-caking agent with specific surface areas ranging from 50 to 400 m²/g depending on production method. Rubber applications dominate volume consumption as tire makers substitute silica for carbon black to improve rolling resistance and wet grip performance. High-purity grades command margin concentration in electronics and pharmaceutical end uses where trace metal specifications gate supplier qualification. Powder form retains logistical advantages in bulk industrial procurement despite growing dispersion demand in automated compounding systems.
REACH registration requirements in Europe, EPA air-quality standards governing silica emissions in the United States, and China's GB standards for industrial chemical purity collectively elevate compliance costs and consolidate qualified supplier pools. Tire-labeling regulations in the European Union directly mandate silica content thresholds for rolling-resistance ratings, redirecting compounder procurement toward certified precipitated silica sources. Stakeholders must monitor evolving carbon-footprint disclosure rules and regional carbon-border adjustments that threaten to reroute trade flows and reshape plant location decisions.
Market Dynamics
EU tire-labeling mandates are compressing compounder procurement timelines as silica-reinforced formulations displace carbon black for rolling-resistance compliance, forcing precipitated silica suppliers to synchronize capacity expansion with automotive certification cycles.
Growth Catalysts
- REACH Registration Thresholds:Chemical compliance in Europe consolidates qualified supplier pools toward ISO 9001-certified precipitated silica producers with traceable supply chains.
- Automotive Lightweighting Mandates:Tire manufacturers in China and Germany substitute silica for carbon black to achieve wet-grip ratings under regional efficiency frameworks.
- Dual Carbon Goals:China's MIIT targets for industrial emissions reduction accelerate domestic precipitated silica capacity expansion serving automotive clusters.
Market Restraints
- Sodium Silicate Cost Volatility:Feedstock price swings for the primary precipitated silica input compress margin stability at mid-scale producers.
- High-Purity Grade Concentration:Electronics-grade fumed silica supply concentrates among integrated chemical conglomerates with captive chlorosilane access.
- Carbon Black Substitution Limits:Technical performance ceilings in heavy-load truck tire compounds prevent complete silica displacement in specific rubber applications.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for domestic tire manufacturing create precipitated silica demand as OEMs localize supply chains.
- Battery Separator Coatings:Lithium-ion cell producers adopt high-surface-area fumed silica for thermal stability in electric vehicle battery architectures.
- Pharmaceutical Excipient Certification:USP and EP monograph compliance opens margin-rich pharmaceutical anti-caking applications for qualified producers.
Industry Challenges
- Process Control Engineering Talent:Precipitated silica manufacturing requires specialized reactor optimization expertise that competes with broader chemical engineering demand.
- ISO 9001 Certification Timelines:12-18 month validation cycles delay market entry for new precipitated silica producers targeting automotive compounders.
- Legacy Carbon Black Integration:Tire makers face compound reformulation complexity when retrofitting silica into existing carbon black-optimized production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Carbon Black Market |
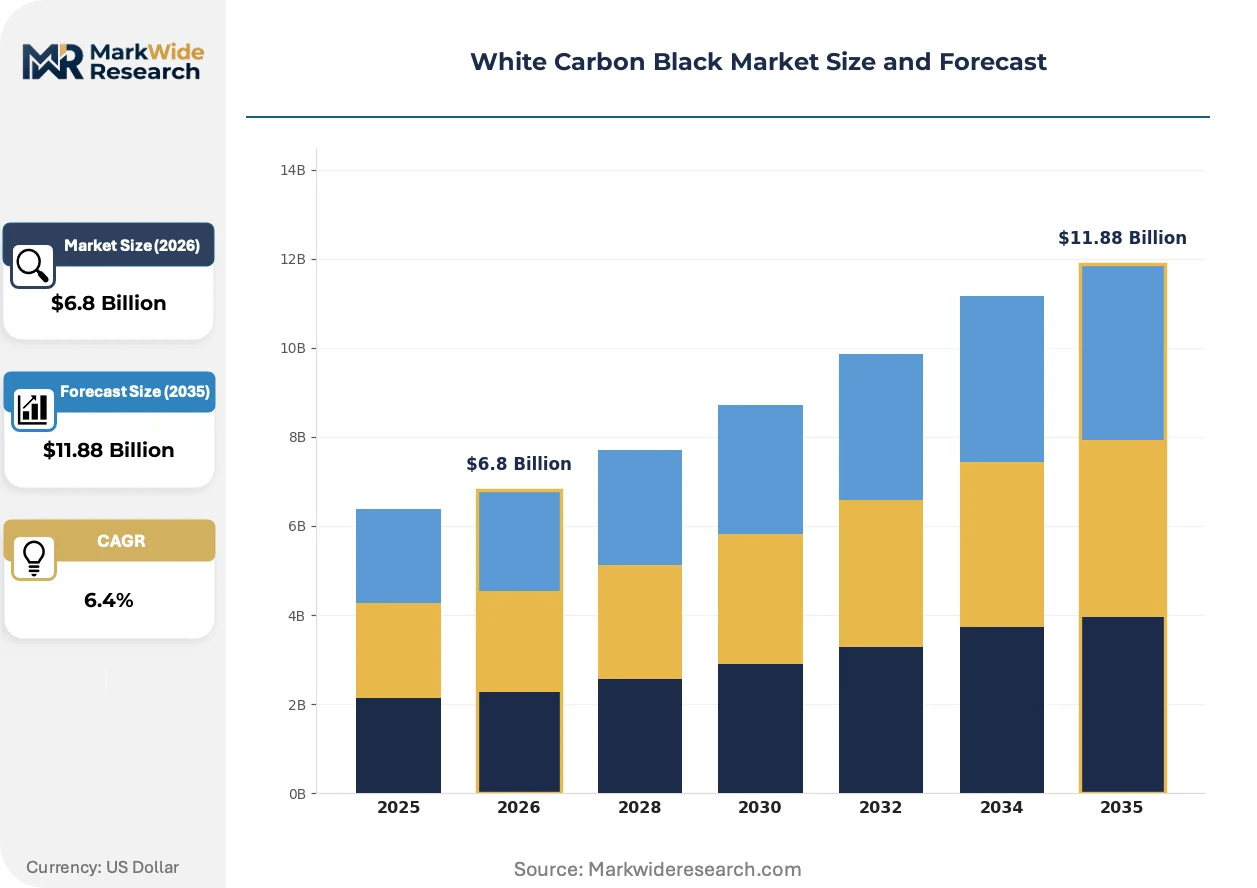
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Plastics, Rubber, Coatings, Cosmetics Form: Powder, Granules, Dispersions, Masterbatch End User: Automotive, Electronics, Construction, Aerospace Grade: High Purity, Food Grade, Industrial Grade, Pharma Grade |
| Companies Covered | Evonik Industries AG, Cabot Corporation, Wacker Chemie AG, Tokuyama Corporation, Solvay S.A., PPG Industries, Inc., Nippon Aerosil Co., Ltd., OCI Company Ltd., Huber Engineered Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Carbon Black Market Evolving Landscape
Silica manufacturing is bifurcating between commodity rubber-grade precipitated production and high-purity fumed silica for electronics, with process innovation and regulatory disclosure requirements compressing the middle tier.
Surface-functionalized precipitated silica is decomposing the traditional trade-off between rolling resistance and wet grip in tire compounds. Major tire makers in Germany and Japan are adopting these grades for premium passenger vehicle lines. The technology is decomposing carbon black's residual share in high-performance tire segments by enabling simultaneous fuel-efficiency and safety-rating compliance.
EU CSRD carbon-footprint disclosure rules are forcing precipitated silica producers to document Scope 3 emissions from sodium silicate sourcing through tire compounder delivery. Chemical manufacturers with integrated energy assets are consolidating advantage. Rubber-grade suppliers serving automotive OEMs face the steepest compliance cost escalation as they retrofit traceability systems.
Compounders are consolidating supplier relationships toward single-source precipitated silica contracts with certified carbon accounting. Long-term offtake agreements are displacing spot procurement in automotive supply chains. This concentration is most visible in Germany and South Korea, where tire makers synchronize silica qualification with platform-level sustainability reporting to OEM customers.
White Carbon Black Market Segmentation
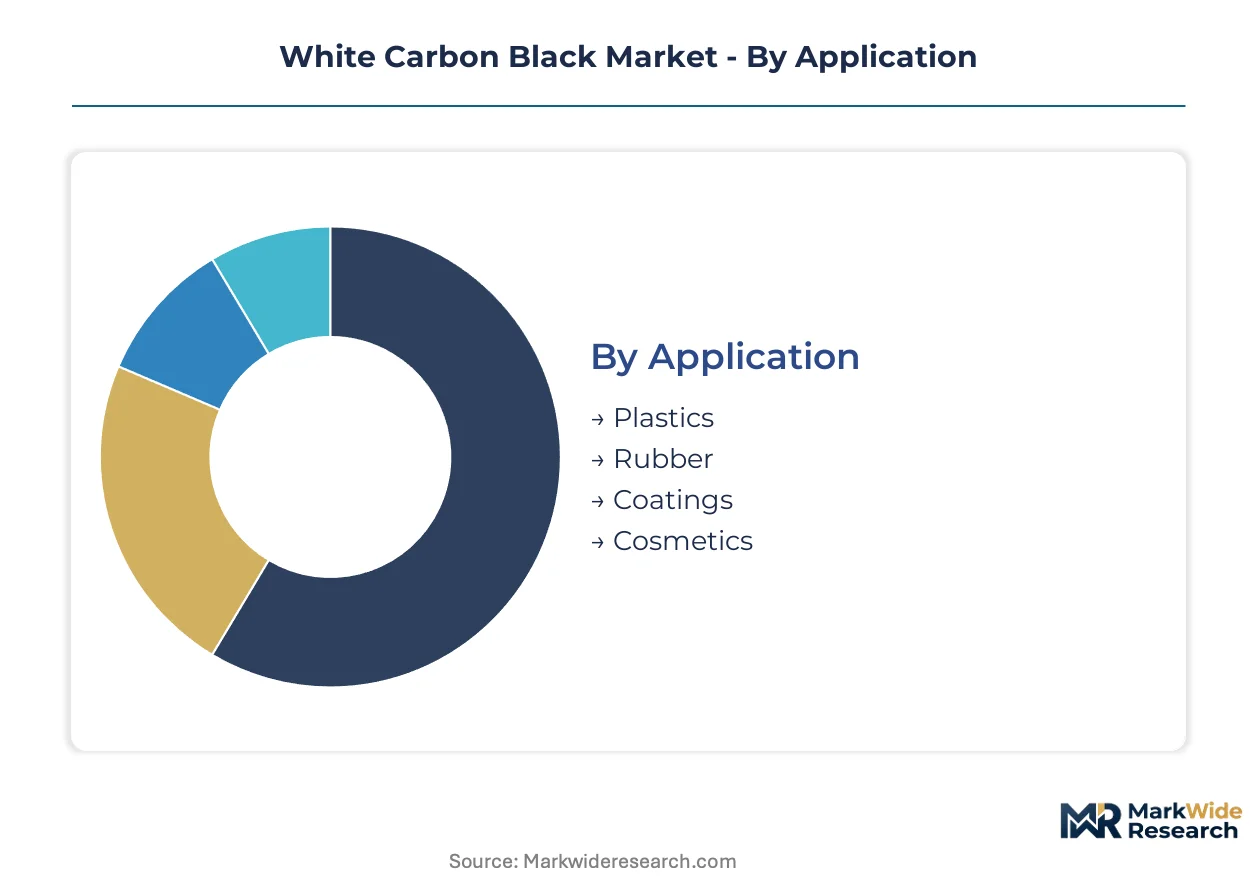
White carbon black segmentation reveals divergent margin structures across purity thresholds and delivery formats. Rubber-grade precipitated silica operates on volume economics while pharmaceutical and electronics grades capture value through certification barriers.
Application:
Rubber applications concentrate revenue pools through tire-industry procurement scale, while cosmetics and coatings command premium positioning via formulation complexity.
- Rubber:Precipitated silica reinforces tire compounds to reduce rolling resistance under EU tire-labeling mandates. German and Japanese tire manufacturers drive procurement volume as silica displaces carbon black in passenger vehicle lines.
- Plastics:Anti-blocking and rheology modification in polyethylene films and engineering polymers. Chinese packaging producers and German automotive compounders dominate demand as thin-film specifications tighten.
- Coatings:Matting agents and viscosity control in industrial and decorative paints.
- Cosmetics:Thickening and anti-caking in color cosmetics and sun care formulations.
Rubber holds installed capacity. Cosmetics is rotating up the share rankings.
Form:
Delivery format selection hinges on compounder automation level and dust-control requirements, with dispersed forms capturing margin in just-in-time supply chains.
- Dispersions:Pre-dispersed silica in liquid carriers eliminates dust exposure and accelerates mixing cycles in automated tire plants. South Korean and German compounders are standardizing aqueous dispersions for silica-silane coupling efficiency.
- Masterbatch:Concentrated silica-polymer blends reduce handling complexity in high-throughput extrusion. Chinese tire makers favor masterbatch formats for integration with existing carbon black logistics infrastructure.
- Powder:Bulk logistics advantage persists in commodity rubber applications with established dust-collection systems.
- Granules:Intermediate flowability for intermediate-scale compounders without dispersion equipment.
Masterbatch holds installed capacity. Dispersions are rotating up the share rankings.
End User:
Automotive procurement dominates volume throughput, while electronics and aerospace concentrate value through purity certification and lot-traceability requirements.
- Automotive:Tire manufacturing consumes the majority of rubber-grade precipitated silica as OEMs comply with regional efficiency regulations. Chinese production clusters and German premium tire makers anchor demand through platform-level sustainability reporting.
- Electronics:High-purity fumed silica serves semiconductor packaging and battery separator coatings. Japanese and South Korean battery producers are qualifying fumed silica for thermal management in electric vehicle cell architectures.
- Construction:Silica fume and precipitated grades in concrete additives and sealants.
- Aerospace:Specialized thermal insulation and composite matrices requiring lot-traceable high-purity material.
Automotive holds installed capacity. Electronics is rotating up the share rankings.
Grade:
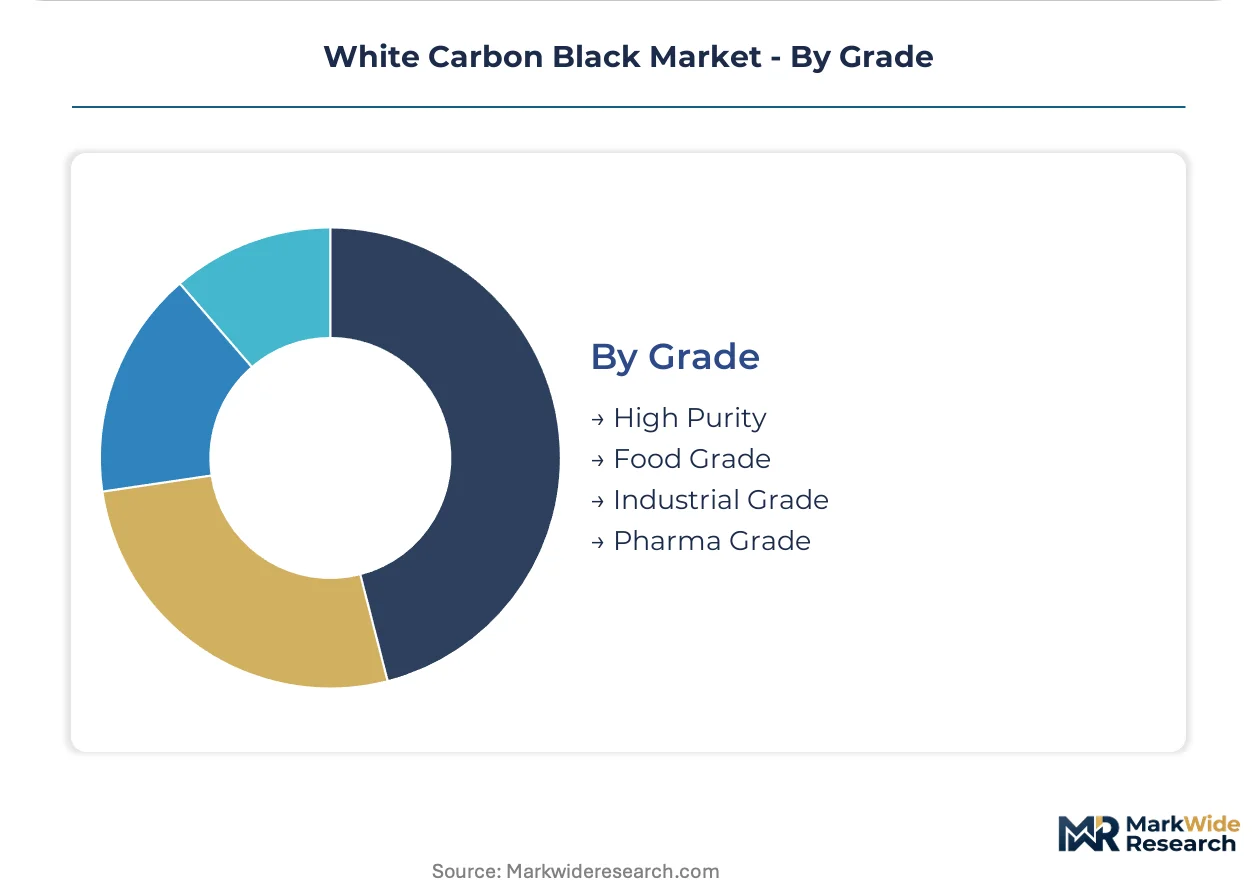
Purity tiering creates discrete margin bands with pharmaceutical and food grades insulated from commodity volatility through regulatory qualification timelines.
- High Purity:Sub-ppm trace metal specifications for electronics and pharmaceutical applications. Integrated chlorosilane producers in Germany and Japan control supply through captive raw material access and clean-room packaging infrastructure.
- Pharma Grade:USP and EP monograph compliance for anti-caking and glidant applications in solid-dose formulations. Indian and Chinese API manufacturers are driving qualification demand as they upgrade to ICH Q7 standards.
- Industrial Grade:Standard precipitated silica for rubber and general industrial filler applications.
- Food Grade:FSSAI and FDA compliance for anti-caking in powdered food products.
Industrial Grade holds installed capacity. Pharma Grade is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU tire-labeling mandates and China's dual carbon targets are redirecting silica procurement flows across automotive manufacturing clusters. National regulations now dictate plant location decisions and supplier qualification timelines.
China
MIIT emissions reduction targets accelerate precipitated silica capacity expansion serving Yangtze River Delta tire plants. GB standards for industrial chemical purity gate domestic supplier qualification. Qingdao and Shanghai automotive clusters absorb volume from integrated sodium silicate-to-silica producers.
Germany
Premium tire manufacturers in Baden-Württemberg and Lower Saxony drive silica-silane coupling adoption for rolling-resistance compliance. KBA vehicle certification cycles synchronize with compounder procurement timelines. Cologne chemical corridor hosts fumed silica production for electronics-grade export.
United States
EPA air-quality standards governing silica emissions elevate compliance costs for rubber-grade producers. NHTSA fuel-economy standards indirectly sustain silica substitution in passenger tire lines. Gulf Coast petrochemical corridor supplies chlorosilane feedstock for high-purity fumed silica manufacturing.
Japan
METI industrial efficiency frameworks push tire makers toward silica-reinforced compounds. JIS standards for precipitated silica purity anchor supplier qualification protocols. Osaka-Kobe chemical belt concentrates fumed silica production for semiconductor packaging and battery separator coatings.
South Korea
Seoul Capital Area battery producers qualify high-surface-area fumed silica for electric vehicle thermal management. MFDS pharmaceutical-grade certification opens anti-caking applications for qualified precipitated silica suppliers. Ulsan automotive cluster integrates aqueous silica dispersions into automated tire compounding lines.
White Carbon Black Market Competitive Landscape
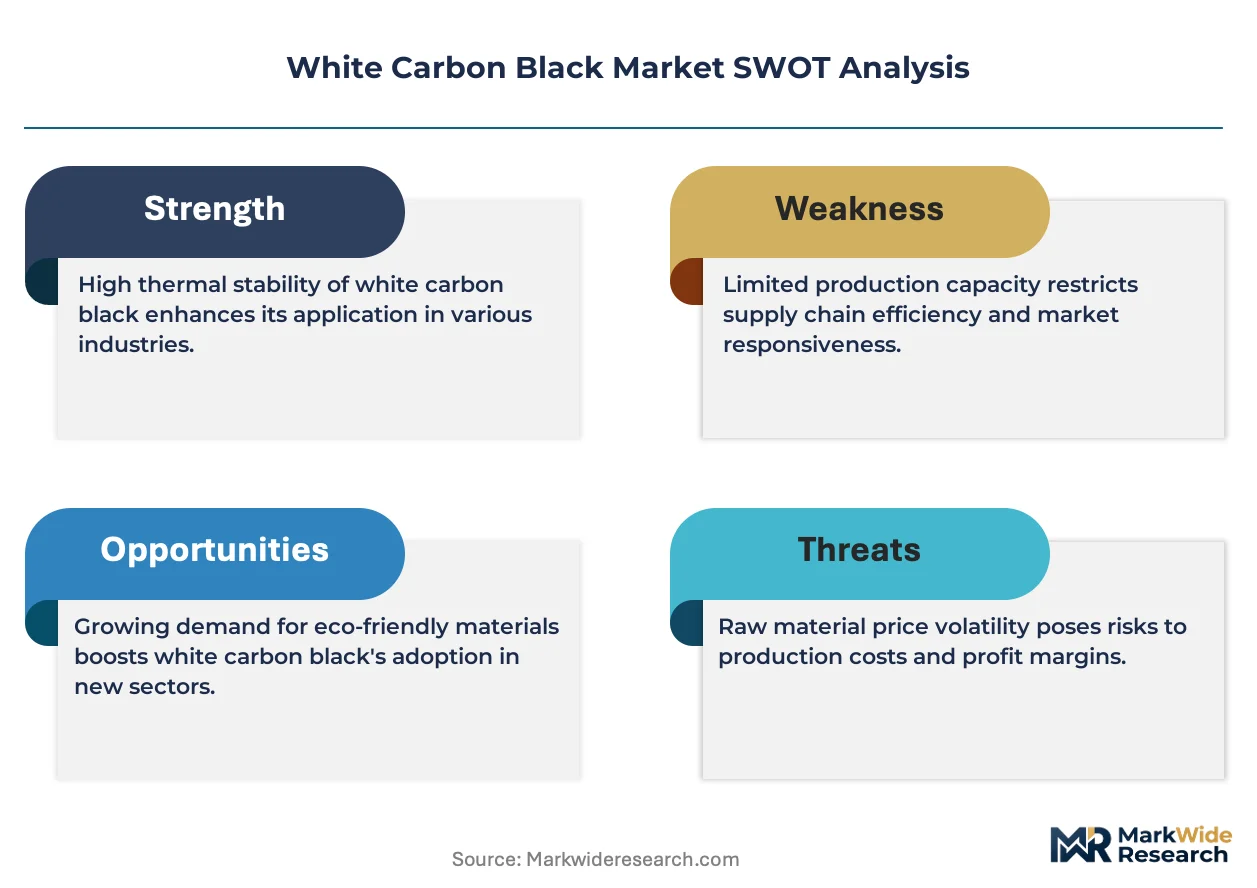
Listed leaders compete with private specialists across integrated versus merchant supply models, creating tiered access to automotive compounder contracts. The vendor base stratifies between chlorosilane-integrated conglomerates and sodium silicate-based precipitated silica merchants. Three archetypes dominate: captive raw material integrators, rubber-grade volume specialists, and high-purity dispersion formulators. Capacity expansion and ISO 9001 certification acceleration represent the dominant competitive moves as qualification timelines compress procurement decisions.
Within the integrated chemical conglomerate tier, Evonik Industries AG and Wacker Chemie AG exemplify European-based producers with multi-site fumed silica networks. Cabot Corporation occupies a position as a rubber-grade specialist with captive precipitated silica technology. These three entities anchor the supplier landscape through differentiated access to feedstock integration and end-market certification depth.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Cabot Corporation |
| Wacker Chemie AG |
| Tokuyama Corporation |
| Solvay S.A. |
| PPG Industries, Inc. |
| Nippon Aerosil Co., Ltd. |
| OCI Company Ltd. |
| Huber Engineered Materials |
| Others |
Value Network & Pricing Analysis
Capacity utilization at chlorosilane-integrated fumed silica plants in Germany and Japan anchors price floors across purity tiers, compressing margin headroom for sodium silicate-based precipitated silica merchants in China and India. Scale concentration among integrated conglomerates with captive energy assets translates into structural pricing power over rubber-grade compounders facing EU tire-labeling compliance deadlines.
Pricing Analysis
Certification level creates the primary spread across the white carbon black spectrum, with ISO 9001-validated precipitated silica for automotive rubber commanding sustained premiums over industrial-grade filler material. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical USP/EP-grade fumed silica from electronics high-purity dispersions and commodity rubber reinforcement. Cost compression in standard rubber-grade material is intensifying because Chinese domestic capacity expansion outpaces regional demand absorption. Tire compounders in Germany and South Korea exhibit the lowest price sensitivity due to sustainability-linked OEM procurement mandates, while Chinese packaging producers of polyethylene films demonstrate acute cost consciousness.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock security for sodium silicate-to-silica producers serving Southeast Asian tire plants, exposing the network to concentrated logistics risk. Supply concentrates in China, Germany, and Japan, with Qingdao and Shanghai clusters anchoring precipitated silica output while the Cologne and Osaka-Kobe chemical belts dominate fumed silica manufacturing. Raw material dependencies center on sodium silicate for precipitation routes, chlorosilane for fume processes, and sulfuric acid for pH control in reactor optimization. Single-source vulnerability concentrates in chlorosilane supply from integrated petrochemical complexes along the US Gulf Coast and Rhine-Ruhr corridor. Distribution runs through long-term offtake agreements with automotive OEMs, displacing spot procurement in German and South Korean tire compounding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where ISO 9001 certification timelines and REACH registration create switching costs that protect qualified incumbent positions from rapid displacement.
For Market Incumbents: Consolidate supplier relationships through captive sodium silicate integration or backward control over chlorosilane feedstock to defend against margin compression from Chinese capacity expansion. Accelerate carbon-footprint traceability systems ahead of EU CSRD disclosure mandates to lock in automotive compounder contracts. Prioritize aqueous dispersion capacity additions in South Korea and Germany where automated tire plants standardize just-in-time delivery formats. For New Entrants and Emerging Players: Service-layer gaps in pharmaceutical-grade precipitated silica qualification present accessible entry points where Indian and Chinese API manufacturers upgrade to ICH Q7 standards. Battery separator coatings for lithium-ion thermal management offer the most penetrable application wedge, with Japanese and South Korean cell producers actively qualifying new fumed silica sources. Pursue toll-manufacturing partnerships with established ISO 9001 facilities to bypass 12-18 month validation timelines while building proprietary reactor expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chlorosilane-to-fumed silica producers with multi-decade semiconductor packaging relationships. Long-term viability over the next decade favors targets with clean-room packaging infrastructure and captive energy assets insulating against Scope 3 disclosure costs. Monitor qualification velocity at Indian pharmaceutical compounders as the inflection signal for pharma-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive feedstock supply secures margin stability against raw material volatility for rubber-grade producers. |
| ISO 9001 Certification Acceleration | Compressed validation timelines synchronize supplier qualification with EU tire-labeling compliance cycles. |
| Green Manufacturing Transition | Integrated energy assets reduce Scope 3 exposure under CSRD carbon-footprint disclosure requirements. |
| Long-term Supply Agreement | Automotive OEM offtake contracts displace spot procurement and lock in volume commitments. |
| Joint Venture | Localized production partnerships in India leverage PLI scheme incentives for domestic tire manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC 10-K filings, and Cefic industry reports to establish baseline capacity and demand estimates. Primary interviews engaged plant managers at precipitated silica facilities, procurement leads at German and Japanese tire OEMs, distribution channel partners serving Chinese packaging producers, and technical R&D directors specializing in silica-silane coupling. Bottom-up triangulation across production facility audits and top-down validation against end-use consumption patterns ensure cross-verified output reliability.
Segmentation dimensions modeled include grade tier across industrial, pharmaceutical, and high-purity specifications; end-use industry spanning automotive rubber, electronics, and cosmetics; packaging format distinguishing powder, dispersion, and masterbatch delivery; and regional production hub concentration. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules across the analysis window. Forecast inputs incorporate EU tire-labeling mandate compliance timelines and China MIIT emissions reduction targets for industrial chemical manufacturing.
Forecasts assume regulatory continuity in REACH registration requirements, EPA air-quality standards, and China's GB industrial purity regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanisms and sodium silicate cost volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market
Specialty Compounds
Global Specialty Amines Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Calcium Sulphite Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Thioglycolate Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market