
 Metal Matrix Composites (Mmcs) Market | 2026-2036
Metal Matrix Composites (Mmcs) Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Matrix Composites (Mmcs) Market Foresight
Aerospace-grade silicon carbide reinforcement specifications are redrawing procurement benchmarks across the MMC supply base. Materion Corporation leverages captive beryllium and advanced powder metallurgy capabilities to dominate defense-aerospace hybrid segments. GKN Powder Metallurgy GmbH anchors European automotive brake rotor supply through its aluminum-matrix composite foundry network. Plansee SE specializes in refractory metal matrix systems for high-temperature industrial tooling, competing on thermal stability rather than cost.
Metal matrix composites consist of a metallic base alloy reinforced with ceramic fibers, whiskers, or particulates such as silicon carbide or alumina, typically achieving 15-40% reinforcement volume fraction to enhance stiffness, wear resistance, and thermal conductivity beyond monolithic metals. The primary industrial purpose centers on replacing conventional alloys in applications where simultaneous thermal management and structural load-bearing are non-negotiable. Aluminum-matrix composites lead commercial volume due to mature liquid metal infiltration processing and established automotive brake and piston supply chains, while titanium-matrix composites capture the fastest growth trajectory driven by jet engine compressor ring demand where specific stiffness requirements exceed superalloy limits. Thermal management applications concentrate margin pools in electronics packaging substrates, where coefficient of thermal expansion matching between MMC heat spreaders and semiconductor dies commands premium pricing over copper-molybdenum alternatives.
The US FAA mandates airworthiness qualification under DO-160 environmental standards and specialized material allowables development for flight-critical MMC components, extending certification timelines but creating durable supplier lock-in once approved. Europe's REACH regulation and ECHA substance restrictions constrain certain reinforcement surface treatments and matrix alloying elements, forcing reformulation investments that favor established compounders with in-house toxicology testing. Japan's METI promotes MMC lightweighting through its energy efficiency standards for transportation equipment, indirectly subsidizing domestic automotive adoption. Stakeholders must monitor evolving sustainability disclosure requirements under the EU CSRD, as embodied carbon accounting for ceramic reinforcement production threatens to reshape sourcing geography and process technology selection.
Market Dynamics
Aerospace manufacturers are accelerating MMC adoption in turbine engine components as the US FAA airworthiness certification framework and Europe's REACH substance restrictions tighten material qualification pathways, concentrating demand in Germany's precision engineering corridor around Munich and Stuttgart.
Growth Catalysts
- Jet engine compressor ring demand:Specific stiffness requirements exceeding superalloy limits are pulling titanium-matrix composites into next-generation propulsion systems. Commercial aviation OEMs qualify these materials under accelerated thermal cycling protocols.
- REACH substance restrictions:Europe's ECHA constraints on certain reinforcement surface treatments are forcing reformulation investments that favor established compounders with in-house toxicology testing capabilities, consolidating supplier tiers.
- Automotive brake rotor supply chains:Aluminum-matrix composites leverage mature liquid metal infiltration processing to capture volume in performance braking applications where thermal conductivity and wear resistance outperform cast iron.
Market Restraints
- Silicon carbide reinforcement cost volatility:Ceramic particulate supply concentrates among limited specialty chemical producers, exposing compounders to input price swings that compress margin pools in electronics packaging substrates.
- DO-160 environmental qualification timelines:The US FAA mandates specialized material allowables development for flight-critical components, extending certification cycles and creating durable supplier lock-in that freezes out new entrants.
- Copper-molybdenum heat spreader substitution:Established semiconductor packaging materials compete on near-term cost despite inferior coefficient of thermal expansion matching, delaying MMC penetration in cost-sensitive consumer electronics tiers.
Strategic Opportunities
- Japan's METI energy efficiency standards:Transportation equipment lightweighting mandates indirectly subsidize domestic automotive MMC adoption, creating a policy-tethered demand anchor distinct from Western aerospace cycles.
- Thermal management-electronics convergence:Coefficient of thermal expansion matching between MMC heat spreaders and semiconductor dies commands premium pricing in high-reliability computing and power electronics verticals.
- Direct-to-fabricator digital channels:Powder metallurgy feedstock suppliers are bypassing traditional distributor networks to serve precision engineering clusters with specification-matched preforms and just-in-time reinforcement delivery.
Industry Challenges
- Material allowables database construction:Generating statistically valid mechanical property datasets for FAA certification demands multi-year test programs that strain mid-tier compounders without captive aerospace customer commitments.
- EU CSRD embodied carbon accounting:Sustainability disclosure requirements for ceramic reinforcement production threaten to reshape sourcing geography and process technology selection before standardized measurement protocols stabilize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Matrix Composites (Mmcs) Market |
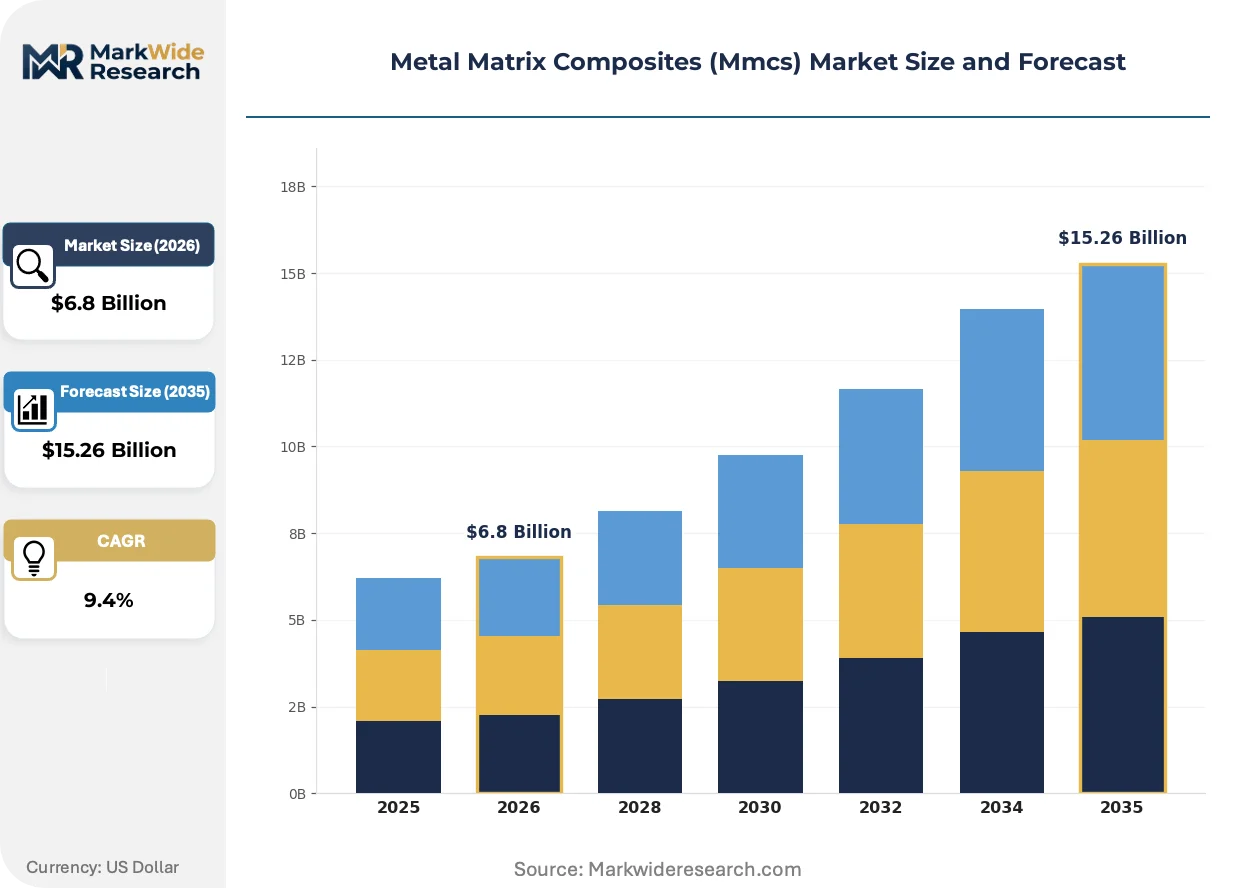
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
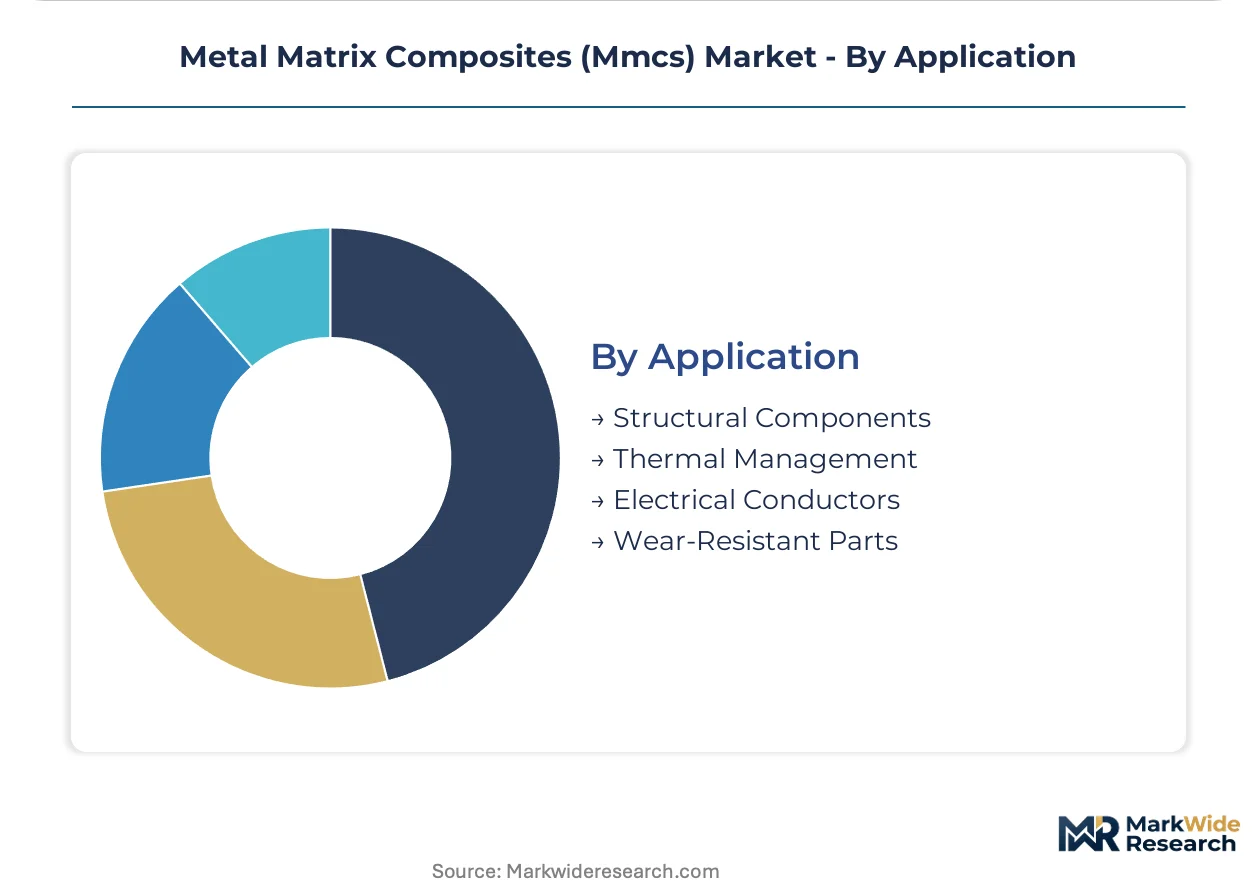
| Segmentation | Product Type: Aluminum-Matrix Composites, Titanium-Matrix Composites, Magnesium-Matrix Composites, Bismuth-Matrix Composites Industry Vertical: Aerospace, Automotive, Electronics, Defense Form: Sheet, Rod, Tube, Coating Application: Structural Components, Thermal Management, Electrical Conductors, Wear-Resistant Parts |
| Companies Covered | Materion Corporation, CPS Technologies, GKN Powder Metallurgy GmbH, DWA Aluminum Composites USA, Coherent Corp., Plansee SE, Ferrotec Corporation, 3M, CeramTec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Matrix Composites (Mmcs) Market Shifts & Advancements
Processing technology advances and regulatory disclosure mandates are restructuring how metal matrix composites are formulated, qualified, and supplied to end-use verticals with divergent performance and compliance requirements.
Spark plasma sintering is displacing conventional hot isostatic pressing for near-net-shape titanium-matrix composite fabrication. Aerospace tier-1 suppliers are adopting this solid-state consolidation method to reduce machining scrap and compress lead times for compressor ring geometries. The shift is displacing legacy wrought superalloy forgings in intermediate-pressure turbine sections where specific stiffness governs design selection.
Europe's CSRD sustainability disclosure requirements are mandating granular embodied carbon reporting across supply tiers. Compounders must now trace ceramic reinforcement production emissions from precursor synthesis through final densification, forcing process technology investments that favor electrically heated synthesis routes over carbon-intensive thermal processes. German precision engineering clusters around Munich are responding fastest, integrating supplier audits into procurement qualification workflows ahead of enforcement deadlines.
Specification-driven procurement is compressing qualification cycles as OEMs consolidate approved material lists. Tier-1 aerospace and automotive buyers are bypassing distributor intermediaries to contract directly with compounders holding active FAA or KBA certifications, collapsing traditional two-step supply chains into direct feedstock-fabricator relationships. This pattern concentrates most visibly in Southern Germany's automotive brake rotor supply base and the US Southeast's emerging aerospace manufacturing corridor.
Metal Matrix Composites (Mmcs) Market Segmentation
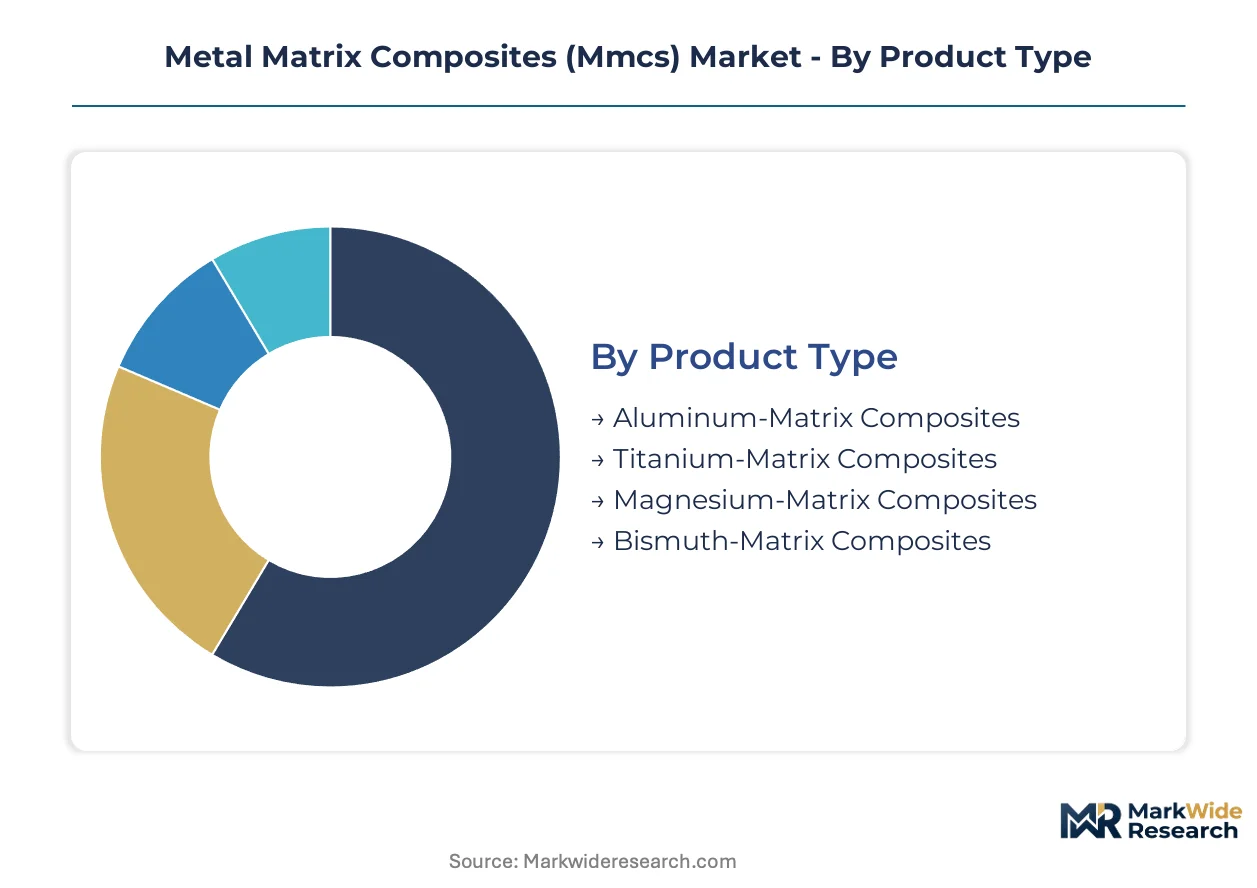
Metal matrix composites fragment across four orthogonal dimensions that determine qualification pathways, margin structures, and supplier relationships. Each segmentation axis carries distinct regulatory weight and shapes how compounders configure their technical service and certification investments.
Product Type:
FAA DO-160 environmental standards and ECHA REACH substance restrictions create divergent compliance burdens across matrix families, with certification timelines stretching longest for flight-critical titanium systems.
- Aluminum-Matrix Composites:Silicon carbide or alumina reinforcement at 15-40% volume fraction dominates commercial volume through mature liquid metal infiltration processing. Automotive brake rotor demand in Germany's precision engineering corridor around Munich and Stuttgart anchors supply chain investments, with KBA certification requirements shaping formulation specifications.
- Titanium-Matrix Composites:Continuous silicon carbide fiber reinforcement achieves specific stiffness exceeding superalloy limits for jet engine compressor rings. FAA material allowables development extends qualification timelines, creating durable supplier lock-in for aerospace tier-1 fabricators.
- Magnesium-Matrix Composites:Lightweight transport applications leverage magnesium's density advantage for automotive powertrain components under Japan METI energy efficiency standards.
- Bismuth-Matrix Composites:Niche radiation shielding and non-toxic ammunition applications exploit bismuth's high density and low toxicity profile against REACH-constrained alternatives.
Aluminum-matrix systems handle the majority of throughput; titanium-matrix formulations are climbing the fastest on share as next-generation propulsion programs accelerate qualification.
Industry Vertical:
Customer concentration and procurement power vary sharply, with aerospace and defense buyers demanding captive supply relationships while electronics and automotive segments tolerate distributor intermediaries.
- Aerospace:Turbine engine compressor rings and structural airframe components require FAA-certified material allowables and specialized environmental testing under DO-160 protocols.
- Automotive:Performance brake rotors and pistons in Germany's Munich-Stuttgart corridor exploit aluminum-matrix thermal conductivity, with OEMs consolidating approved supplier lists to compress qualification cycles.
- Electronics:Heat spreader substrates for semiconductor packaging command premium pricing where coefficient of thermal expansion matching outweighs copper-molybdenum cost advantages.
- Defense:Armor systems and precision guidance components leverage beryllium-aluminum hybrids and refractory metal matrices under national security procurement protocols.
Automotive absorbs the greatest tonnage; aerospace is expanding most quickly as specific stiffness requirements pull titanium-matrix composites into propulsion architectures.
Form:
Near-net-shape processing economics and machining scrap rates determine how form factors map to end-use margin pools, with spark plasma sintering disrupting traditional wrought product supply.
- Sheet:Aerospace skin panels and electronics substrates demand tight thickness tolerance and surface finish, with powder metallurgy feedstock suppliers bypassing distributors to serve precision engineering clusters directly.
- Rod:Structural tie rods and piston pins in automotive applications leverage continuous extrusion of aluminum-matrix billets for mechanical property consistency.
- Tube:Drive shafts and pressure vessels exploit hoop strength from aligned reinforcement architectures, with hydrostatic testing protocols varying by vertical.
- Coating:Wear-resistant surfaces on industrial tooling apply MMC layers through thermal spray or laser cladding, competing on deposition rate against monolithic hardfacings.
Sheet products command the highest unit values; tube forms are gaining share fastest in drivetrain lightweighting programs.
Application:
Functional performance requirements dictate reinforcement architecture selection, with thermal management and structural applications diverging on fiber continuity and interface engineering priorities.
- Structural Components:Continuous fiber titanium-matrix systems for jet engine compressor rings achieve directional stiffness through aligned silicon carbide architectures, with FAA certification extending development cycles.
- Thermal Management:Discontinuously reinforced aluminum-matrix heat spreaders match semiconductor die expansion coefficients, with electronics packaging substrates concentrating margin pools in high-reliability computing verticals.
- Electrical Conductors:Aluminum-graphite hybrids balance conductivity and thermal expansion for power transmission and busbar applications, competing against copper on density-adjusted performance.
- Wear-Resistant Parts:Ceramic particulate reinforcement in aluminum and magnesium matrices extends service life for brake rotors and industrial tooling, with Germany's automotive supply base driving volume specifications.
Thermal management commands premium pricing; structural applications are expanding most quickly as propulsion OEMs qualify next-generation compressor architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty ceramic reinforcement production clusters in Germany, Japan, and the United States concentrate upstream supply leverage for compounders serving aerospace and automotive verticals. Regulatory fragmentation across FAA, ECHA, and METI jurisdictions shapes divergent qualification investments.
United States
Jet engine OEMs in the US Southeast aerospace corridor drive titanium-matrix composite qualification under FAA DO-160 protocols. The FAA mandates specialized material allowables development that extends certification timelines. Georgia and South Carolina manufacturing clusters absorb defense-aerospace hybrid demand for beryllium-aluminum systems.
Germany
Automotive brake rotor specifications from Munich-Stuttgart precision engineering clusters anchor European aluminum-matrix volume. KBA certification requirements shape formulation standards for performance braking applications. ECHA REACH substance restrictions on reinforcement surface treatments force reformulation investments favoring established compounders.
Japan
METI energy efficiency standards for transportation equipment indirectly subsidize domestic automotive MMC lightweighting adoption. Toyota and Honda supply chains integrate magnesium-matrix powertrain components under policy-tethered demand structures. Nagoya-area fabricators specialize in continuous fiber architectures for thermal management substrates.
China
MIIT industrial upgrading directives accelerate domestic silicon carbide reinforcement capacity for electronics packaging substrates. Yangtze River Delta semiconductor clusters demand coefficient of thermal expansion matched heat spreaders. State-backed materials institutes consolidate powder metallurgy feedstock supply for regional compounders.
Metal Matrix Composites (Mmcs) Market Competitive Landscape
Concentration sits with diversified materials conglomerates and captive aerospace compounders rather than pure-play specialists. Three to five vertically integrated holding groups control upstream ceramic reinforcement supply and downstream qualification relationships. The competitive terrain separates into defense-aerospace hybrids, automotive volume compounders, and refractory metal specialists. Dominant moves include direct-to-fabricator channel bypassing and spark plasma sintering capacity additions for near-net-shape titanium systems.
Among US-based diversified materials groups, Materion Corporation and CPS Technologies occupy positions within the defense-aerospace hybrid archetype, leveraging captive beryllium and advanced powder metallurgy capabilities. German fabricator GKN Powder Metallurgy GmbH anchors European automotive supply through aluminum-matrix foundry networks, representing the volume-compounder tier where KBA certification creates durable supplier relationships.
| Leading Market Players |
|---|
| Materion Corporation |
| CPS Technologies |
| GKN Powder Metallurgy GmbH |
| DWA Aluminum Composites USA |
| Coherent Corp. |
| Plansee SE |
| Ferrotec Corporation |
| 3M |
| CeramTec GmbH |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between aerospace tier-1 fabricators and certified compounders lock in multi-year silicon carbide fiber supply while fixing price visibility against ceramic reinforcement volatility. These contracts concentrate procurement leverage in Germany's Munich-Stuttgart corridor and the US Southeast manufacturing belt, where KBA and FAA qualification timelines create durable supplier relationships that insulate approved vendors from spot-market price swings.
Pricing Analysis
FAA DO-160 certification dictates the pricing tier structure across titanium-matrix composite grades, separating flight-critical compressor ring specifications from non-structural applications. Three-tier pricing structure across premium, standard, and economy levels reflects material allowables development investment, with aerospace-grade continuous fiber systems commanding substantial premiums over automotive brake rotor formulations. Cost compression in standard-grade aluminum-matrix composites is intensifying because silicon carbide particulate supply concentrates among limited specialty chemical producers. Electronics packaging buyers exhibit highest price sensitivity, deferring MMC heat spreader adoption where copper-molybdenum alternatives satisfy near-term thermal management requirements.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes compound lead time uncertainty for ceramic reinforcement precursors synthesized in China and Japan. Upstream supply concentrates in Germany, Japan, and the United States, where specialty silicon carbide fiber production draws from petroleum-derived precursor chemicals and high-purity metallurgical silicon. Single-source vulnerability characterizes continuous fiber architectures for titanium-matrix systems, where qualified suppliers remain countable on one hand. Distribution runs through direct-to-fabricator digital channels that bypass traditional distributor networks, with powder metallurgy feedstock suppliers serving precision engineering clusters through specification-matched preform delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spark plasma sintering adoption for near-net-shape titanium-matrix fabrication represents a high-growth disruption, accelerated by FAA pressure to compress compressor ring qualification cycles for next-generation propulsion architectures.
For Market Incumbents: Consolidate certification assets by acquiring compounders with active FAA material allowables databases, defending against emerging spark plasma sintering specialists threatening to displace legacy hot isostatic pressing capacity. Prioritize backward integration into ceramic reinforcement synthesis to secure silicon carbide fiber supply against ECHA REACH reformulation mandates that favor in-house toxicology testing capabilities. For New Entrants and Emerging Players: After-sales technical service for thermal management substrate qualification presents a service-layer gap where incumbent compounders under-serve mid-tier electronics packaging fabricators lacking in-house coefficient of thermal expansion matching expertise. Target Japan's METI-subsidized automotive lightweighting programs through magnesium-matrix powertrain component development, leveraging policy-tethered demand structures distinct from Western aerospace qualification cycles. Pursue direct-to-fabricator digital channel partnerships with Nagoya-area semiconductor packaging specialists. For Investors and Strategic Acquirers: Refractory metal matrix specialists with captive tungsten-molybdenum powder metallurgy capabilities represent the priority acquisition target archetype, offering thermal stability differentiation in industrial tooling verticals where cost competition is less acute than aluminum-matrix automotive segments. Monitor EU CSRD embodied carbon disclosure enforcement as the critical inflection signal, as sustainability accounting for ceramic reinforcement production threatens to reshape qualified supplier geography and process technology selection.| Strategic Initiative | Industry Significance |
|---|---|
| Spark Plasma Sintering Capacity Addition | Compresses titanium-matrix compressor ring lead times for Pratt & Whitney and GE Aviation qualification programs. |
| Backward Integration into SiC Fiber Synthesis | Secures reinforcement supply against ECHA REACH surface treatment restrictions and Chinese export license volatility. |
| Direct-to-Fabricator Digital Channel Launch | Bypasses distributor intermediaries to serve Germany's KBA-certified brake rotor foundries with specification-matched preforms. |
| FAA Material Allowables Database Acquisition | Accelerates market entry for aerospace tier-1 supplier relationships that otherwise demand multi-year test programs. |
| EU CSRD Embodied Carbon Audit Implementation | Qualifies compounders for German precision engineering procurement workflows ahead of enforcement deadlines. |
Research Methodology
Desk research of FAA certification databases, ECHA REACH substance restriction filings, and METI energy efficiency standard documentation preceded structured interviews with aerospace tier-1 procurement directors, powder metallurgy plant managers, ceramic reinforcement R&D leads, and semiconductor packaging thermal engineers. Secondary validation drew from customs trade data for silicon carbide fiber imports, SEC 10-K filings of diversified materials conglomerates, and KBA type-approval records for automotive brake rotor applications. Bottom-up volume estimates triangulated against top-down aerospace and automotive production forecasts.
Variance decomposition across matrix type, reinforcement architecture, end-use vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level elasticity modeling against jet engine OEM production schedules and automotive lightweighting content-per-vehicle trajectories. Industry-specific inputs included FAA DO-160 environmental test cycle completion rates and ECHA SVHC candidate list expansion timelines affecting reinforcement surface chemistry.
Material uncertainties — silicon carbide reinforcement capacity expansion delays, REACH substance restriction scope revisions, and CSRD measurement protocol standardization — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and policy subsidy continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
PCR Laminates Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Epoxy Composite Market
Composite Materials
Global Composite Materials Market
Composite Materials
Europe Composites Market
Composite Materials
CFRP Propeller Shaft Market
Composite Materials
Scrim Reinforced Films Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Hybrid Composites Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Global FRP Sheets and Panels Market
Composite Materials
Core Material for Composites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
Lignin-Based Graphene Market