
 North America Molded FRP Grating Market | 2026-2036
North America Molded FRP Grating Market Size, Share, and Industry Trends Forecast 2026-2036
North America Molded FRP Grating Market Analytics
Water treatment infrastructure is broadening its share of molded FRP grating procurement across North America. Strongwell Corporation leverages its pultrusion expertise to dominate heavy-duty industrial applications, while Fibergrate Composite Structures anchors its position through specialized corrosion-resistant product lines. Bedford Reinforced Plastics differentiates via custom fabrication capabilities serving regional municipal projects.
Molded FRP grating consists of fiberglass-reinforced thermoset resin panels formed in heated molds with interwoven roving and continuous strand mat, achieving bar spacing of 19-38 mm and load ratings up to 5,000 pounds per square foot for industrial flooring and elevated platform applications. Heavy duty grating captures the dominant margin pool in chemical processing installations, while architectural grating shows the fastest expansion as building codes favor non-metallic facade and decking materials. Plain grating remains the mature volume base across standard walkway and trench cover applications.
EPA effluent limitation guidelines and OSHA fall protection standards directly shape product specifications and installation compliance costs for grating suppliers across the United States. The US Green Building Council LEED certification framework and Canadian National Building Code provisions increasingly specify FRP alternatives for coastal and chemically exposed structures. Stakeholders must monitor evolving state-level Buy America provisions and infrastructure procurement rules that could redirect supply chain sourcing for federally funded projects.
Market Dynamics
Refinery maintenance cycles across the US Gulf Coast petrochemical corridor are accelerating replacement volume for corrosion-resistant flooring systems. This demand pulse is compressing supplier lead times and reshaping inventory positioning among regional distributors serving chemical processing facilities.
Growth Catalysts
- EPA corrosion-control mandates:Effluent limitation guidelines tighten material specifications for chemical containment structures. Facilities must upgrade aging metallic infrastructure to compliant non-metallic alternatives.
- OSHA fall protection standards:Workplace safety compliance drives elevated platform renovations. Industrial operators face audit pressure to eliminate slip hazards and structural degradation risks.
- Water treatment infrastructure expansion:Municipal and industrial wastewater facilities broaden procurement of molded FRP grating for trench covers, walkways, and chemical exposure zones.
Market Restraints
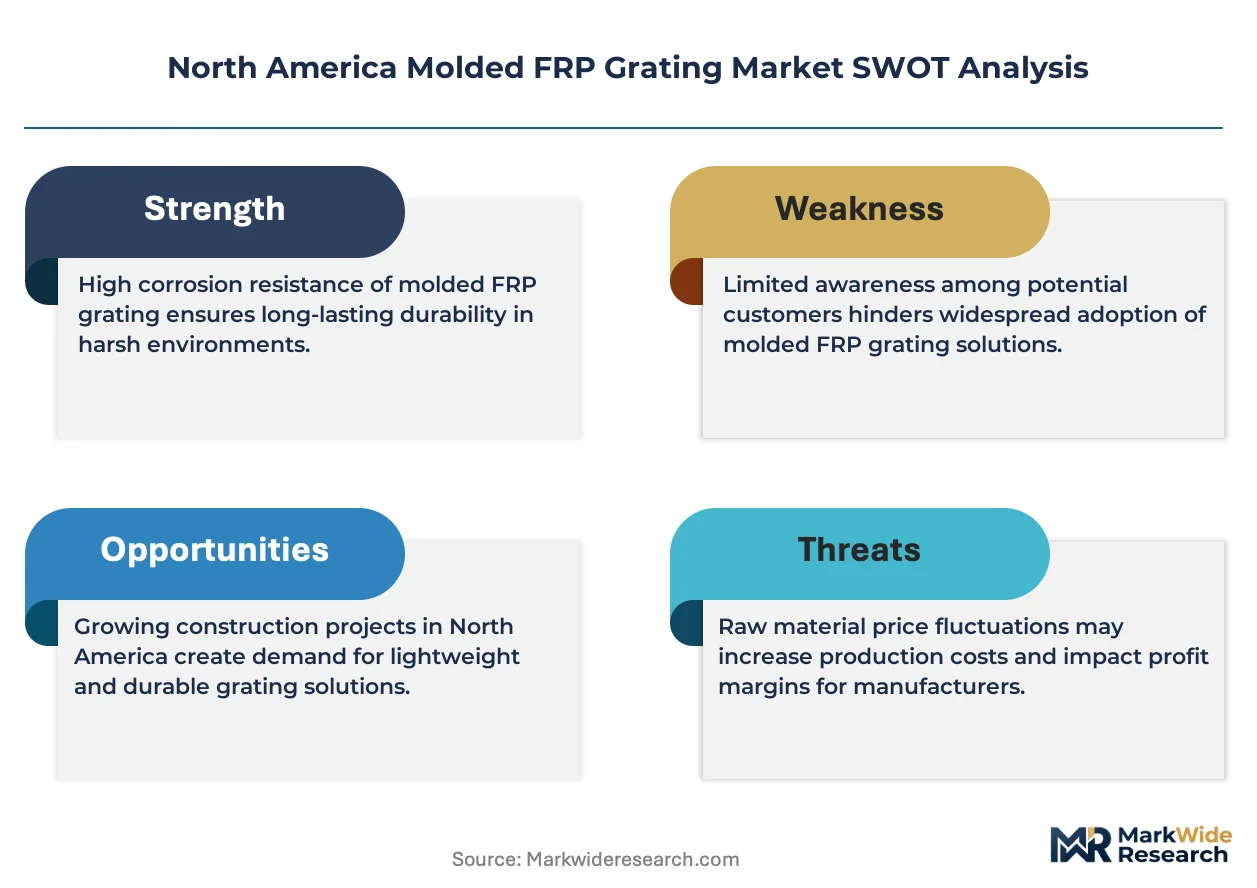
- Resin input cost volatility:Unsaturated polyester and vinyl ester feedstock prices fluctuate with crude oil derivatives. Manufacturers absorb margin compression or pass through costs to price-sensitive municipal buyers.
- Concentrated supply base:Heavy-duty industrial grating production concentrates among specialized composite fabricators. Limited qualified suppliers extend lead times for custom load-rated specifications.
- Steel grating substitution threat:Galvanized metal alternatives retain cost advantage in non-corrosive environments. Budget-constrained infrastructure projects default to conventional materials where chemical exposure is minimal.
Strategic Opportunities
- Canadian coastal infrastructure:National Building Code provisions increasingly specify FRP alternatives for marine-exposed structures. Provincial bridge and port authorities represent underpenetrated demand pools.
- Architectural facade applications:Building codes favor non-metallic decking and screening materials. Designers specify molded grating for aesthetic permeability in commercial and institutional exteriors.
- Buy America procurement rules:Evolving federal infrastructure funding requirements redirect supply chain sourcing. Domestic fabrication capabilities qualify suppliers for federally backed water treatment and transportation projects.
Industry Challenges
- Composite fabrication skill scarcity:Molded FRP production requires specialized thermoset processing expertise. Regional workforce gaps constrain capacity expansion at mid-scale fabricators.
- LEED certification documentation burden:Green building credit claims demand extensive material sourcing transparency. Suppliers invest in lifecycle assessment data collection to satisfy specifier due diligence.
- Legacy steel infrastructure integration:Platform retrofits require dimensional matching and load transfer engineering. Field modification complexity extends project timelines and installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Molded FRP Grating Market |
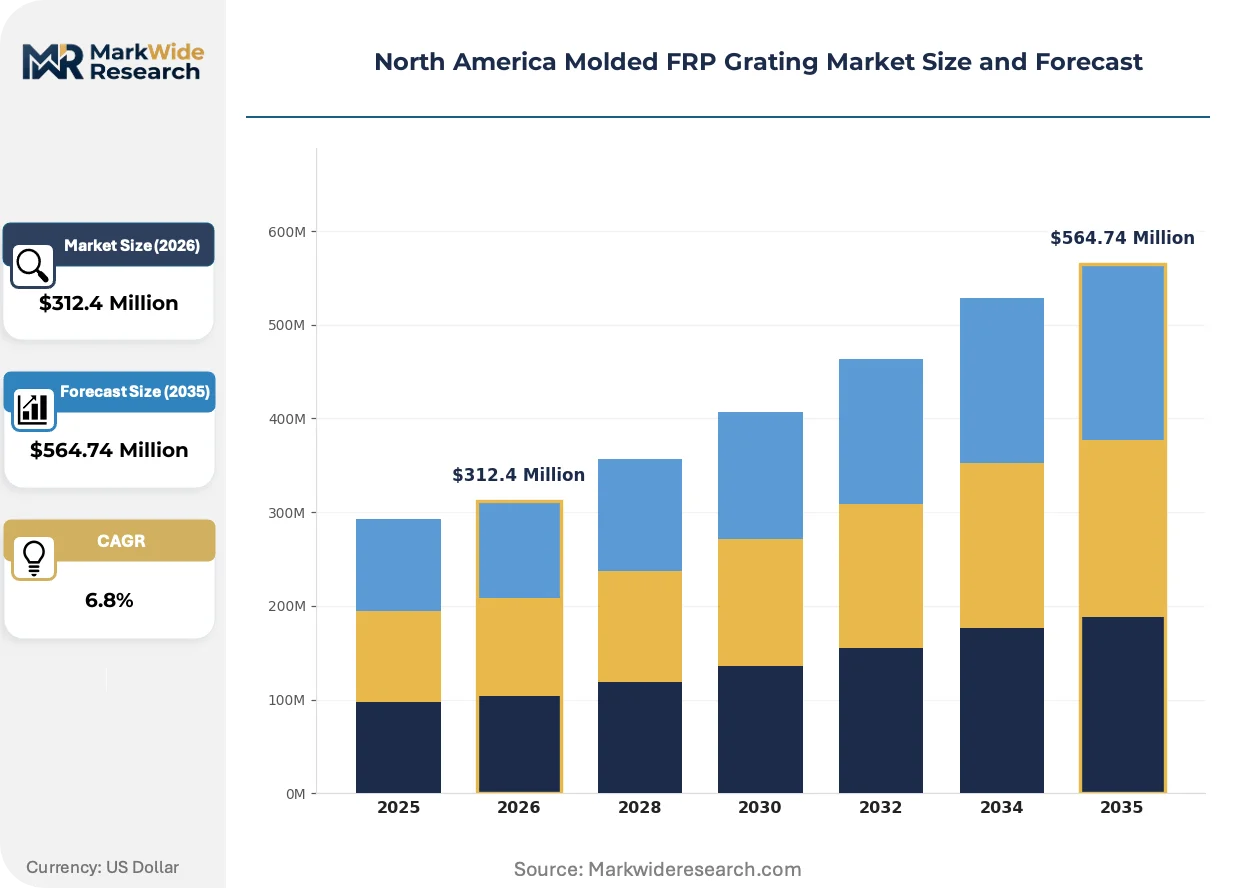
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Grating, Heavy Duty Grating, Light Duty Grating, Architectural Grating Application: Flooring, Walkways, Platforms, Trench Covers Industry Vertical: Aerospace, Chemical Processing, Marine, Infrastructure Performance Feature: Corrosion Resistance, Slip Resistance, UV Stability, Load Bearing |
| Companies Covered | Strongwell Corporation, Fibergrate Composite Structures, Bedford Reinforced Plastics, Liberty Pultrusions, Meiser Grating, National Grating, Peabody Engineering, Delta Composite Structures, American Grating, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Molded FRP Grating Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine product specifications across industrial flooring applications. Suppliers race to differentiate through performance certification and fabrication automation.
Vinyl ester resin formulations are electrifying corrosion resistance benchmarks in chemical processing environments. Refinery operators specify these advanced thermosets for sulfuric acid and caustic exposure zones. The technology is electrifying margin structures as premium formulations command price multiples over standard polyester alternatives.
OSHA fall protection standards are tightening guardrail and toeboard integration requirements for elevated walkways. Compliance deadlines force facility managers into accelerated replacement schedules. Chemical processing installations in Texas and Louisiana face the steepest retrofit obligations as regional enforcement intensifies.
Buyers are consolidating vendor relationships around full-service fabricators with in-house engineering capabilities. Municipal water authorities and industrial operators bypass distribution intermediaries for direct specification support. This pattern concentrates procurement volume among suppliers with regional technical service presence, particularly across the Midwest and Southeast United States.
North America Molded FRP Grating Market Segmentation
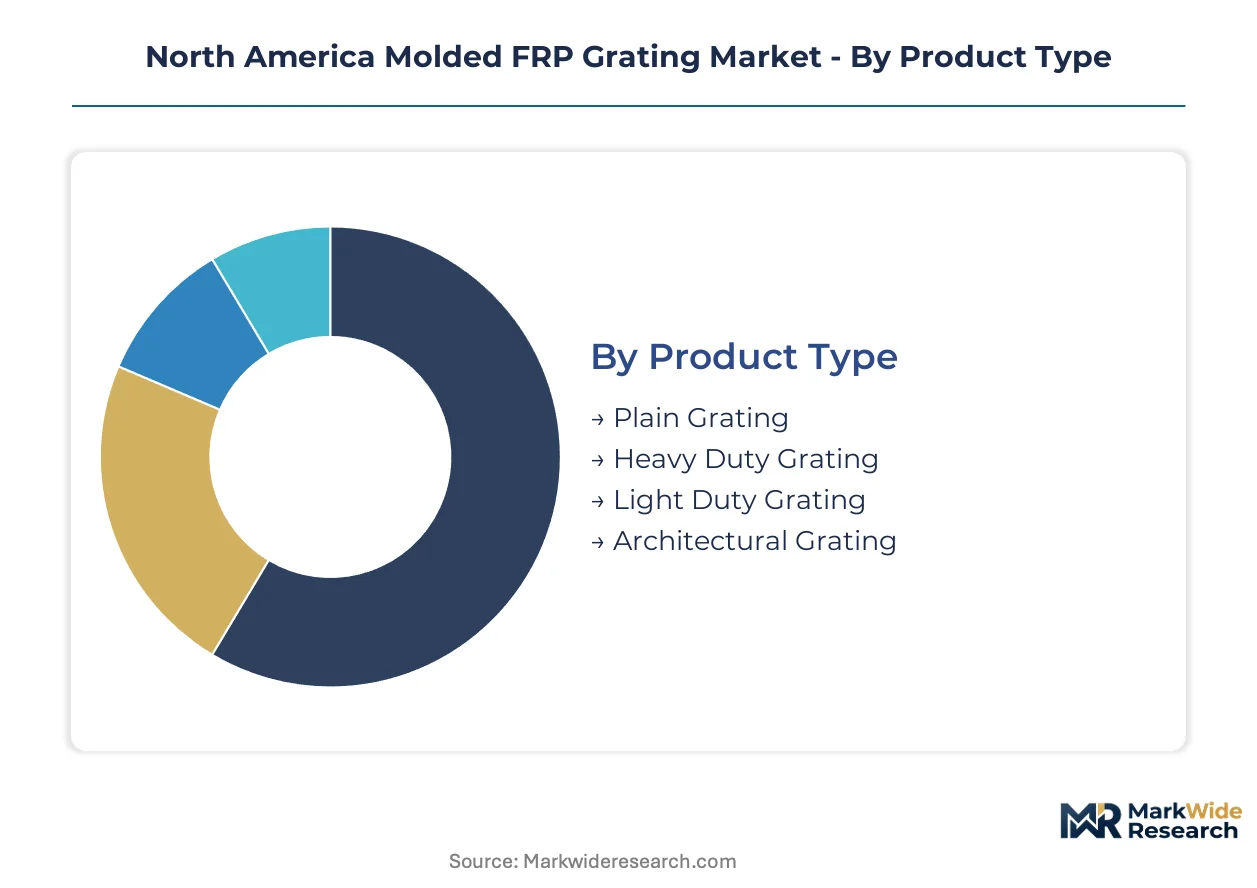
Molded FRP grating suppliers configure certification pathways around load ratings and exposure conditions. Product specifications cascade through application requirements, industry verticals, and performance benchmarks that determine compliance obligations under OSHA and EPA frameworks.
Product Type:
OSHA fall protection mandates and EPA corrosion-control rules apply differentially across load-bearing tiers, with heavy-duty installations facing the steepest documentation burdens for elevated platform approvals.
- Heavy Duty Grating:Engineered with interwoven roving and continuous strand mat achieving load ratings up to 5,000 pounds per square foot. Refinery operators across the US Gulf Coast petrochemical corridor specify these panels for sulfuric acid exposure zones where vinyl ester resin formulations satisfy EPA effluent limitation guidelines.
- Architectural Grating:Designed for aesthetic permeability in commercial facades and institutional decking with bar spacing optimized for visual screening. Municipal building departments in coastal California and Florida jurisdictions specify these for LEED-certified projects where UV stability documentation supports green building credit claims.
- Plain Grating:Standard thermoset panels serving walkway and trench cover applications with 19-38 mm bar spacing configurations.
- Light Duty Grating:Reduced-load panels for pedestrian-only zones and secondary access routes where OSHA guardrail integration requirements are less stringent.
Leading the category by volume: Plain Grating. Growing fastest: Architectural Grating.
Application:
Cost tier stratification separates premium engineered systems from commodity replacements, with flooring and platform installations commanding specification-grade pricing while trench covers compete on procurement cycle efficiency.
- Platforms:Elevated work surfaces requiring integrated toeboard and guardrail systems under OSHA fall protection standards. Chemical processing facilities in Texas and Louisiana face accelerated replacement schedules as regional enforcement intensifies audit compliance deadlines.
- Flooring:Industrial load-bearing surfaces in corrosive environments where vinyl ester resin premiums over standard polyester justify lifecycle cost calculations. Refinery maintenance cycles drive replacement volume through distributor inventory positioning.
- Walkways:Pedestrian circulation routes in water treatment facilities and municipal infrastructure where slip resistance specifications meet workplace safety audits.
- Trench Covers:Access panels for drainage and utility channels where load ratings align with municipal procurement standards and budget-constrained project timelines.
Platform installations dominate margin capture. Trench covers represent the highest procurement frequency.
Industry Vertical:
Application maturity varies sharply across end-use sectors, with chemical processing representing established specification patterns while aerospace adoption remains developmental.
- Chemical Processing:Corrosion-resistant flooring and containment structures in refineries and petrochemical plants. EPA effluent limitation guidelines force upgrades from aging metallic infrastructure to compliant FRP alternatives across the US Gulf Coast corridor.
- Infrastructure:Bridge decking, port facilities, and water treatment installations where Canadian National Building Code provisions increasingly specify FRP for marine-exposed structures.
- Marine:Offshore platforms, ship decking, and coastal boardwalks requiring UV stability and saltwater resistance certifications.
- Aerospace:Maintenance platforms and hangar flooring where weight reduction and non-sparking properties address specialized operational requirements.
Chemical Processing anchors procurement volume. Infrastructure shows the steepest specification expansion trajectory.
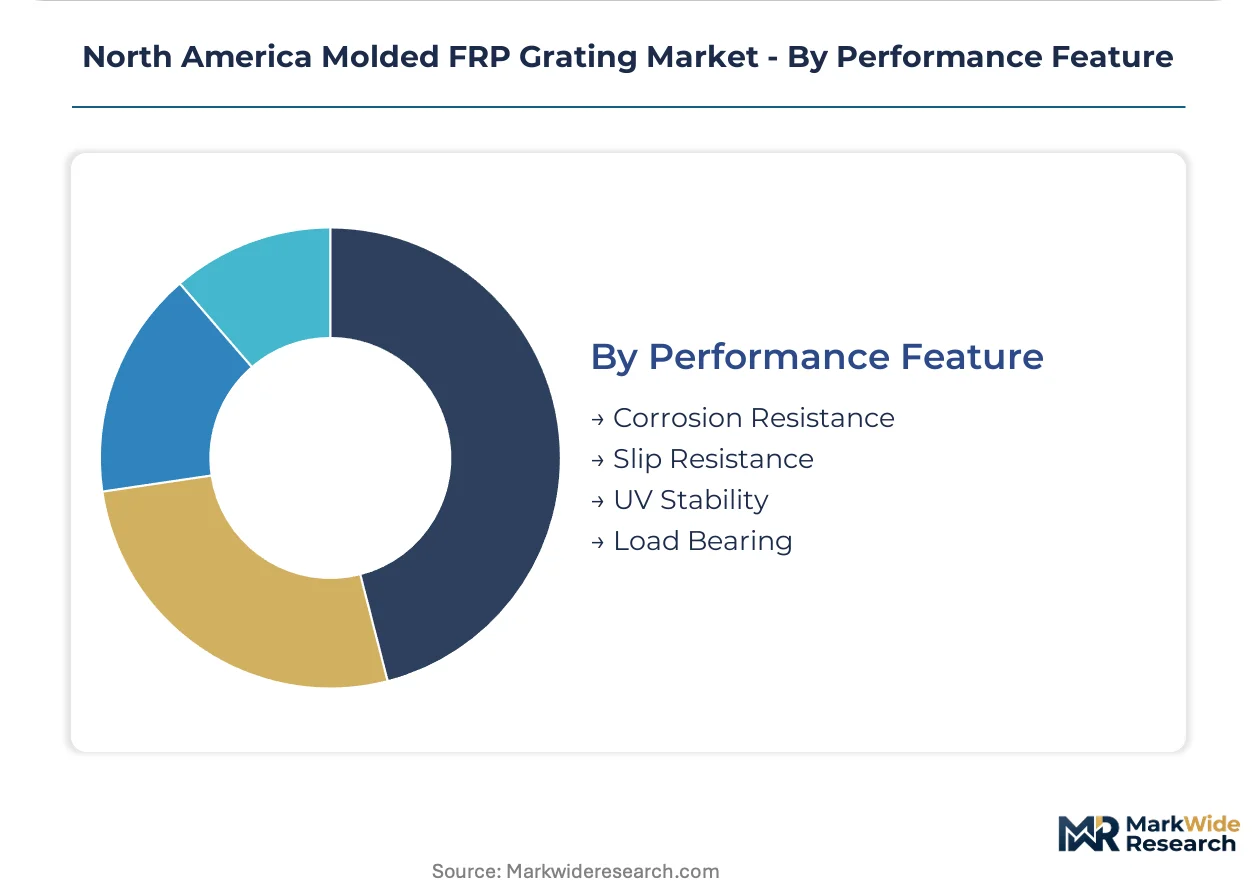
Performance Feature:
Customer type differentiation separates industrial operators with engineering staff who specify composite systems from municipal buyers who default to standardized catalogs.
- Corrosion Resistance:Vinyl ester and isophthalic polyester formulations engineered for sulfuric acid, caustic, and solvent exposure zones. Chemical processing operators specify these for containment structures where EPA mandates eliminate metallic alternatives.
- Load Bearing:Deflection-controlled engineering for elevated platforms and heavy equipment access routes where OSHA standards dictate maximum span ratings and safety factors.
- Slip Resistance:Grit-embedded or concave surface profiles for wet environments in water treatment facilities and food processing installations.
- UV Stability:Stabilized resin systems and surface veils for outdoor architectural and marine applications where color retention and fiber bloom prevention extend service life.
Corrosion Resistance commands specification priority. UV Stability is gaining share fastest among coastal and architectural segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor functions as the dominant demand concentration zone, with Texas and Louisiana refineries driving replacement cycles for corrosion-resistant flooring systems. Canadian coastal provinces and Mexican industrial corridors represent adjacent growth vectors under distinct regulatory frameworks.
United States
Texas and Louisiana refineries dominate procurement volume through accelerated maintenance cycles. EPA effluent limitation guidelines force metallic infrastructure upgrades to FRP alternatives. The Gulf Coast petrochemical corridor compresses supplier lead times as regional distributors reposition inventory.
Canada
Provincial bridge and port authorities expand FRP specifications under National Building Code provisions for marine-exposed structures. Health Canada and PMRA environmental standards shape material selection for coastal infrastructure. British Columbia and Atlantic Canada port modernization projects drive specification expansion.
Mexico
Pemex refinery modernization and private petrochemical investments create demand for corrosion-resistant platforms. Federal environmental regulations under SEMARNAT tighten containment structure requirements. Altamira and Coatzacoalcos industrial zones concentrate procurement for chemical processing facilities.
North America Molded FRP Grating Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with heavy-duty industrial applications concentrating among established composite fabricators while architectural and municipal projects fragment across regional players. The vendor base organizes into three strategic archetypes: full-service fabricators with in-house engineering, specialized corrosion-resistant product specialists, and custom fabrication shops serving localized procurement. Capacity expansion and direct specification relationships represent the dominant competitive moves, as buyers consolidate vendor relationships around technical service presence.
Among established North American fabricators, Strongwell Corporation and Fibergrate Composite Structures occupy positions within the full-service tier, exemplifying scale-driven competitive positioning. Bedford Reinforced Plastics represents the custom fabrication archetype, anchoring regional municipal project engagement through specification support capabilities.
| Leading Market Players |
|---|
| Strongwell Corporation |
| Fibergrate Composite Structures |
| Bedford Reinforced Plastics |
| Liberty Pultrusions |
| Meiser Grating |
| National Grating |
| Peabody Engineering |
| Delta Composite Structures |
| American Grating |
| Others |
Value Network & Pricing Analysis
US Gulf Coast petrochemical operators concentrate procurement volume for heavy-duty molded FRP grating, anchoring a contract-based pricing model where long-term offtake agreements dominate high-specification purchases and spot transactions govern standard inventory replenishment.
Pricing Analysis
Lead-time premiums compress pricing flexibility for rush orders from Texas and Louisiana refineries facing OSHA compliance deadlines. Three-tier pricing structure across premium vinyl ester formulations, standard isophthalic polyester, and economy orthophthalic grades separates specification-grade projects from municipal procurement cycles. Cost compression in standard-grade panels intensifies as resin input volatility transfers margin pressure downstream. Municipal water authorities exhibit acute price sensitivity, while chemical processing operators prioritize corrosion resistance over unit economics.
Supply Chain Analysis
Unsaturated polyester and vinyl ester resin supply rests on US petrochemical producers and specialty chemical imports from Germany and Japan. Continuous strand mat and interwoven roving feedstock draws from domestic fiberglass manufacturers and Chinese glass fiber exporters. Single-source vulnerability concentrates in qualified vinyl ester formulation suppliers serving EPA-mandated containment structures. Distribution runs through regional fabricators with in-house engineering capabilities, bypassing intermediaries for direct specification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite fabrication skill scarcity constrains capacity expansion across mid-scale producers, propping pricing power for qualified suppliers with thermoset processing expertise.
For Market Incumbents: Acquire regional engineering service capabilities to defend against distributor disintermediation. Backward integration into resin compounding secures margin control amid feedstock volatility. Investment in automated molding equipment addresses workforce gaps constraining output expansion. For New Entrants and Emerging Players: Begin with architectural facade applications in California and Florida jurisdictions where LEED certification requirements outpace established supply. Canadian provincial bridge authorities represent underpenetrated demand with distinct National Building Code specifications. Direct specification relationships with coastal municipal building departments bypass incumbent distributor networks. For Investors and Strategic Acquirers: The window for entry favors full-service fabricators with captive vinyl ester formulation capabilities and Gulf Coast technical service presence. Long-term viability hinges on qualification for federally funded infrastructure under evolving Buy America provisions. Monitor EPA effluent guideline enforcement intensity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive vinyl ester supply insulates margins from crude derivative volatility. |
| Capacity Expansion in Texas Gulf Coast | Proximity to petrochemical corridor compresses lead times for refinery maintenance cycles. |
| Green Manufacturing Transition | LEED documentation capabilities unlock municipal and institutional specification pools. |
| Long-term Supply Agreement | Contracted offtake with Pemex modernization secures volume in Mexican industrial corridor. |
| Joint Venture | Partnership with Canadian fabricators addresses National Building Code certification requirements. |
Research Methodology
Multi-period observation of refinery maintenance cycles, EPA enforcement patterns, and resin price indices anchored the trend analysis, supplemented by interviews with plant engineers at chemical processing facilities, procurement leads at municipal water authorities, distribution channel partners, and technical R&D directors at composite fabricators. Secondary validation drew from EPA effluent limitation guidelines, OSHA fall protection standards, customs and trade data, and SEC filings of publicly held material suppliers. Bottom-up project pipeline analysis triangulated against top-down industrial construction spending forecasts.
Segment-weighting applied differential growth assumptions across product type, application, and industry vertical dimensions, with corrosion resistance specifications and load rating tiers modeled as cross-cutting variables. CAGRs derived from regression analysis of historical replacement cycles and projected infrastructure investment flows. Vinyl ester resin adoption curves and Buy America procurement rule evolution served as industry-specific forecast inputs across the projection horizon.
Underlying measurement precision varies by segment; chemical processing procurement carries tighter precision than emerging architectural applications. Forecasts incorporate assumptions regarding EPA enforcement continuity, resin price stabilization, and workforce availability that could revise trajectory if regulatory or macroeconomic conditions shift. A small set of triggers—OSHA audit intensity, state-level Buy America implementation, and Pemex capital allocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Global Carbon Graphite Bushings Market
Composite Materials
Pressure Vessel Composite Materials Market
Composite Materials
Wall Cladding Materials Market
Composite Materials
China Marine Composites Market
Composite Materials
Acrylic Laminates Market
Composite Materials
GCC Decorative Laminates Market
Composite Materials
Global Thermoplastic Composites Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Non-Honeycomb Sandwich Panel Core Materials Market
Composite Materials
Laminar Composites Market
Composite Materials
Polypropylene and Polypropylene Composites Market
Composite Materials
Pultrusion Market
Composite Materials
Core Material for Composites Market
Composite Materials
Expandable Graphite Market
Composite Materials
Graphite Felt Market