
 Lithium Battery Copper Aluminum Composite Pole Market | 2026-2036
Lithium Battery Copper Aluminum Composite Pole Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Copper Aluminum Composite Pole Market Insights
The gap between copper conductivity and aluminum weight savings is narrowing as ultrasonic welding and explosive bonding techniques mature for multi-metal interfaces. Hunan Phohom anchors its position through proprietary cladding processes that reduce contact resistance in high-current applications. Dongguan Lingte Technology leverages automated roll-bonding lines to sustain cost competitiveness at volume. Shenzhen YuQiang New Materials specializes in surface-treated composite strips that extend cycle life for cylindrical cell formats.
Lithium battery copper aluminum composite poles consist of metallurgically bonded bimetallic conductors, typically with copper layers at terminal interfaces and aluminum cores for current collection, engineered to withstand electrochemical corrosion while minimizing ohmic losses. The primary industrial purpose is to replace pure copper terminals in large-format cells, cutting raw material costs without sacrificing thermal performance or weld reliability. Composite poles lead product type demand because OEMs prioritize proven cladding integrity over experimental hybrid geometries. Electric vehicles anchor application growth as cell-to-pack architectures multiply terminal counts per module. Direct sales dominate distribution channels since battery makers require joint qualification protocols and lot-traceability that distributors rarely support.
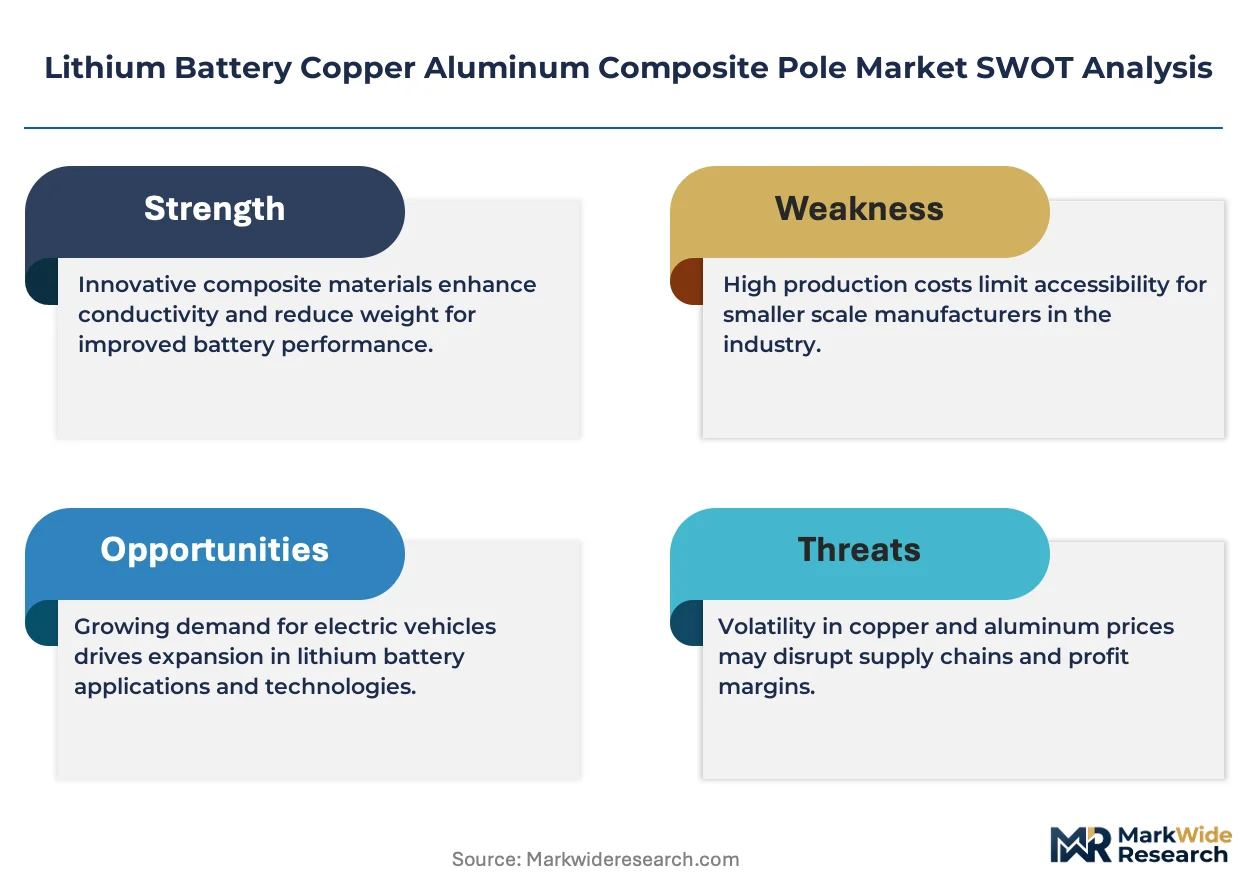
China's MIIT enforces GB/T standards for battery interconnection materials, while SAMR monitors supplier certification under mandatory product liability rules. The EU's Battery Regulation and REACH compliance for metal surface treatments are raising entry barriers for exporters serving European automotive customers. Stakeholders must monitor how solid-state cell formats alter terminal geometry requirements and whether in-house pole production becomes a priority for integrated battery manufacturers.
Market Dynamics
Cell-to-pack architectures are multiplying terminal counts per battery module, forcing composite pole suppliers to scale cladding capacity while maintaining GB/T-compliant metallurgical integrity across thinner conductor profiles.
Growth Catalysts
- GB/T 31485 battery safety standards:China's MIIT mandates enhanced terminal corrosion resistance for high-nickel chemistries, accelerating qualification of copper-aluminum bonded interfaces over pure aluminum alternatives.
- Ultrasonic welding maturation:Multi-metal joining protocols now achieve sub-milliohm contact resistance at production speeds, enabling OEM adoption in prismatic cell formats previously limited to laser-welded pure copper.
- Shenzhen-Suzhou industrial corridor concentration:Pole manufacturers co-locate with electrolyte and separator suppliers, cutting logistics costs and enabling just-in-time delivery to CATL and BYD gigafactories.
Market Restraints
- Copper price volatility:LME copper futures swings above 15% quarterly complicate long-term supply agreements between pole producers and battery OEMs seeking fixed pricing.
- Explosive bonding equipment scarcity:Only three qualified machinery suppliers worldwide manufacture high-tonnage cladding presses, creating 18-month order backlogs for capacity expansion.
- REACH surface treatment compliance:European automotive customers require ECHA-registered passivation chemistries, disqualifying standard Chinese oxide-inhibitor processes from EU-bound supply chains.
Strategic Opportunities
- Solid-state terminal geometry redesign:Sulfide electrolyte cells require hermetic sealing interfaces, opening specification windows for composite poles with engineered copper thickness gradients.
- India PLI scheme for ACC batteries:Reliance Industries and Ola Electric are qualifying domestic pole suppliers under production-linked incentive thresholds, creating first-mover positioning for cladding technology licensors.
- Direct qualification protocols:Battery makers are bypassing distributors to enforce lot-traceability standards, favoring pole manufacturers with integrated ERP-to-MES data pipelines.
Industry Challenges
- Cladding metallurgist shortage:Explosive bonding and roll-bonding process engineering expertise concentrates among retiring technicians in Hunan and Guangdong provinces, constraining knowledge transfer.
- Joint qualification timeline compression:OEMs demand six-month validation cycles for new pole designs versus historical 18-month protocols, straining testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Copper Aluminum Composite Pole Market |
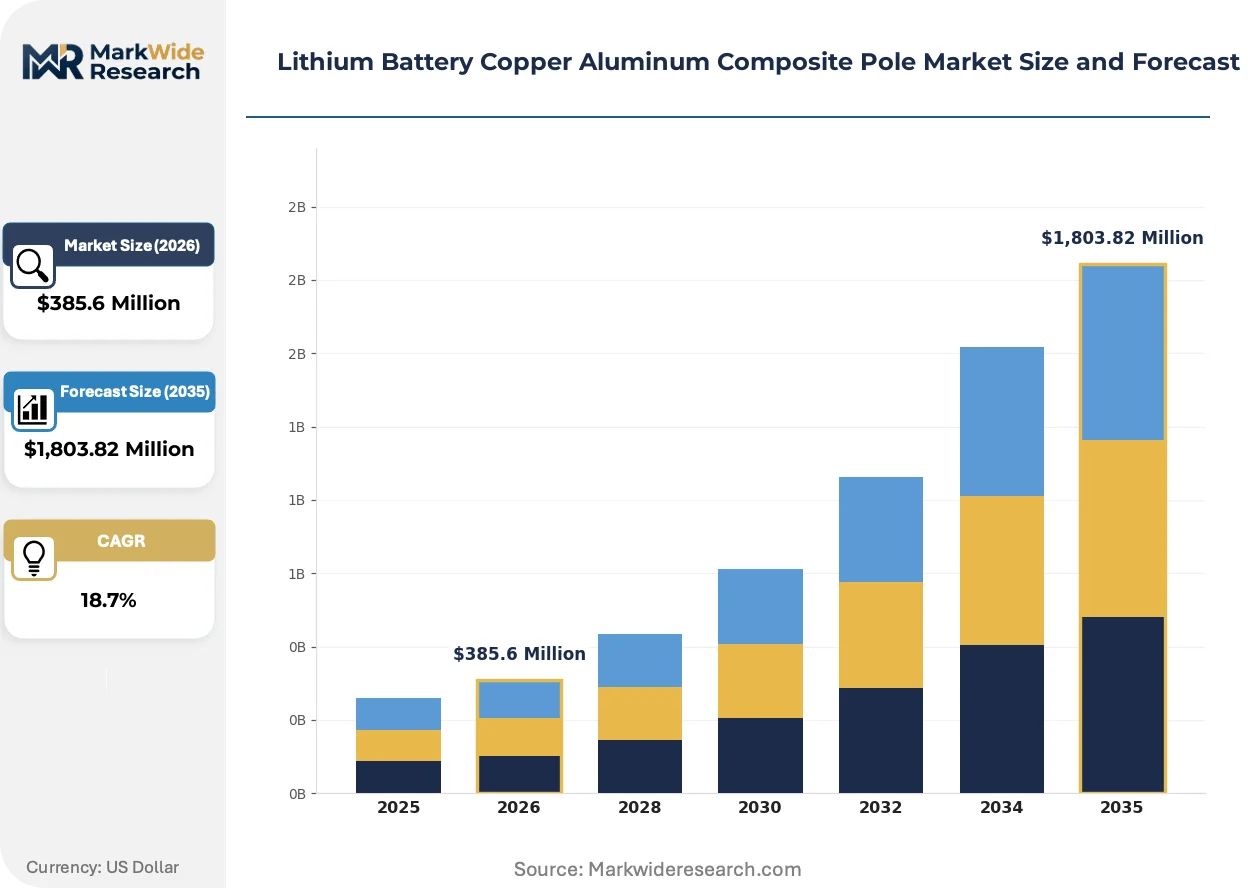
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,803.82 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Poles, Conductive Poles, Hybrid Poles, Reinforced Poles Application: Electric Vehicles, Renewable Energy Storage, Grid Integration, Consumer Electronics End User: Manufacturers, Utilities, Automotive Industry, Electronics Producers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Hunan Phohom, Dongguan Lingte Technology, Shenzhen YuQiang New Materials, Huihua Composite Material, Suzhou Sumzone, Zhengzhou Guangyuan Battery Material, Zhongze Tech, Zetian, Shenzhen KingBest Hardware Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Copper Aluminum Composite Pole Market Trends and Innovations
Material bonding techniques and procurement protocols are restructuring how composite poles move from raw metal to qualified battery components.
Explosive bonding with precisely controlled detonation velocities is rendering obsolete slower roll-bonding methods for high-current applications above 300A. European automotive OEMs specify explosively bonded poles for 800V architectures, compressing supplier qualification to firms with licensed blast-chamber facilities. The technology is rendering obsolete capital-light roll-bonding entrants who cannot amortize explosive bonding infrastructure.
REACH Annex XVII restrictions on nickel release are forcing reformulation of copper surface treatments for European-bound products. ECHA's 2023 guidance on battery material hazard classification now requires SDS documentation for composite pole oxide layers. Korean battery makers with EU assembly plants are accelerating substitution of chromate passivation with silane-based alternatives.
Cell makers are consolidating pole supply bases from 8-12 qualified vendors to 3-4 strategic partners with captive cladding capacity. CATL and BYD now require pole suppliers to co-locate within 200 kilometers of cell assembly plants, displacing distant tier-two metal processors. This geographic consolidation is most visible in Anhui and Sichuan provinces where new battery megafabs are commissioning dedicated pole production lines.
Lithium Battery Copper Aluminum Composite Pole Market Segmentation
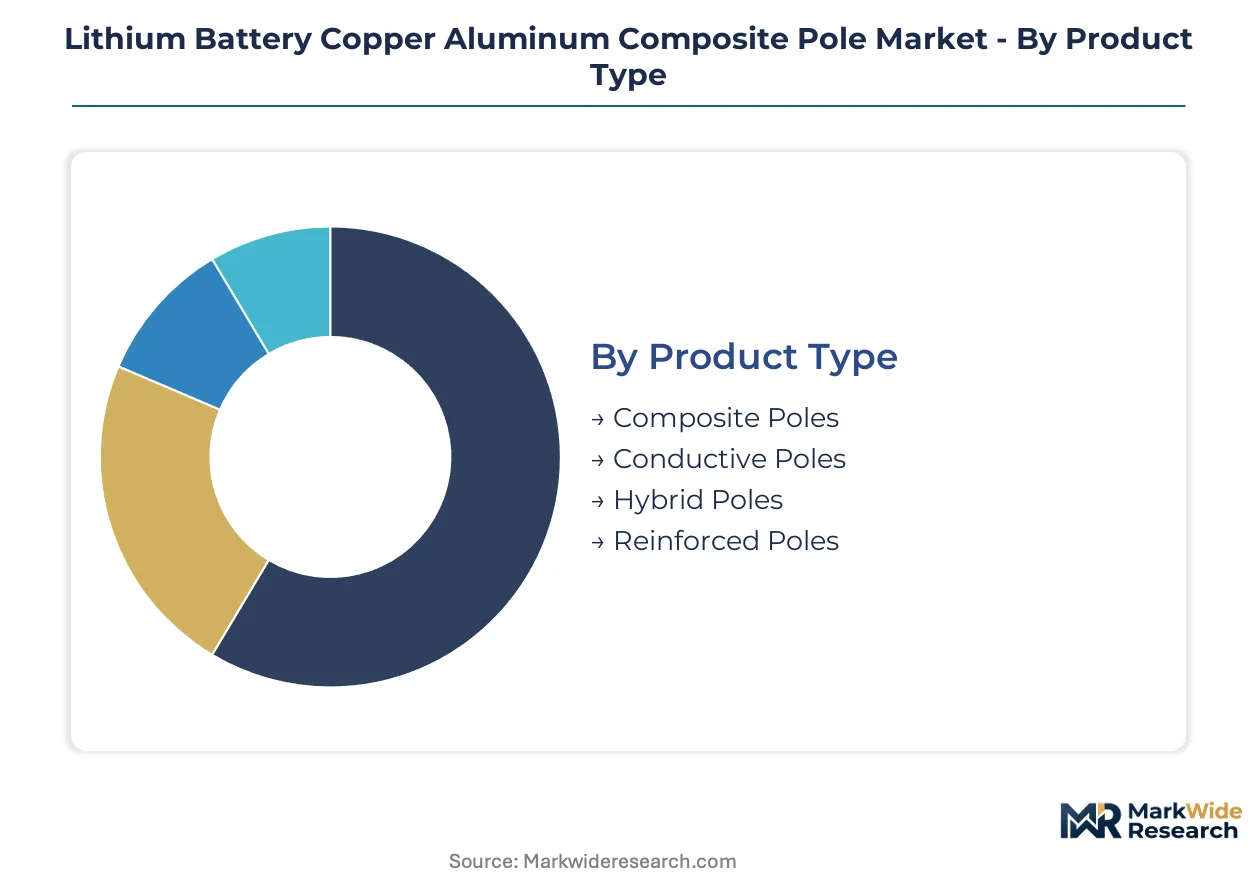
Composite pole procurement varies sharply by product specification, application voltage class, and customer integration depth. Segment boundaries determine which cladding technologies qualify and where pricing power concentrates across the supply base.
Product Type:
Cost tier stratification separates capital-intensive explosive bonding from roll-bonded alternatives and emerging hybrid architectures.
- Composite Poles:Metallurgically bonded copper-aluminum laminates with copper terminal interfaces and aluminum current collection cores. CATL and BYD procurement concentrates here for prismatic cells, driven by GB/T 31485 corrosion resistance mandates for high-nickel cathode systems.
- Conductive Poles:Surface-optimized strips engineered for sub-milliohm contact resistance in ultrasonic welding protocols. Demand clusters around Shenzhen cylindrical cell producers seeking cycle life extension through oxide-inhibitor treatments.
- Hybrid Poles:Experimental geometries combining explosive bonding with selective plating. Korean battery makers evaluate these for solid-state terminal sealing requirements.
- Reinforced Poles:Thickness-graded laminates with engineered copper gradients for 800V architectures. European automotive OEMs specify these for high-current busbar integration.
Composite Poles holds installed capacity. Conductive Poles is rotating up the share rankings.
Application:
End-use voltage and thermal cycling requirements dictate cladding method selection and supplier qualification pathways.
- Electric Vehicles:Cell-to-pack architectures multiply terminal counts per module, forcing pole suppliers to scale capacity while maintaining GB/T-compliant metallurgical integrity across thinner conductor profiles. BYD and Tesla gigafactories in Anhui and Sichuan provinces anchor procurement volume.
- Renewable Energy Storage:Grid-scale battery installations demand reinforced poles for 1500V DC bus configurations. Chinese state grid tenders specify MIIT-certified suppliers with documented thermal cycling performance.
- Grid Integration:Utility-scale frequency regulation systems prioritize cost-optimized roll-bonded poles. Procurement concentrates through centralized state-owned enterprise tendering.
- Consumer Electronics:Cylindrical cell formats for power tools and portable devices specify thinner composite strips. Dongguan contract manufacturers drive spot-market purchasing with limited qualification overhead.
Electric Vehicles commands the steepest expansion trajectory. Renewable Energy Storage is climbing fastest in absolute terminal volume.
End User:
Customer integration depth determines whether procurement flows through joint qualification protocols or spot-market channels.
- Manufacturers:Integrated battery cell producers with captive pole production lines. CATL's vertical pole fabrication in Ningde displaces third-party suppliers for internal consumption.
- Utilities:State grid and provincial power companies procuring through centralized tendering with mandatory GB/T certification. Procurement cycles align with five-year grid investment plans.
- Automotive Industry:OEMs and tier-one battery pack assemblers requiring lot-traceability and ERP-to-MES data pipelines. Direct supplier relationships dominate over distributor intermediation.
- Electronics Producers:Consumer device contract manufacturers with flexible specification tolerance. Price-sensitive procurement through wholesale metal processors in Guangdong province.
Manufacturers holds captive production capacity. Automotive Industry is consolidating qualified supplier bases most aggressively.
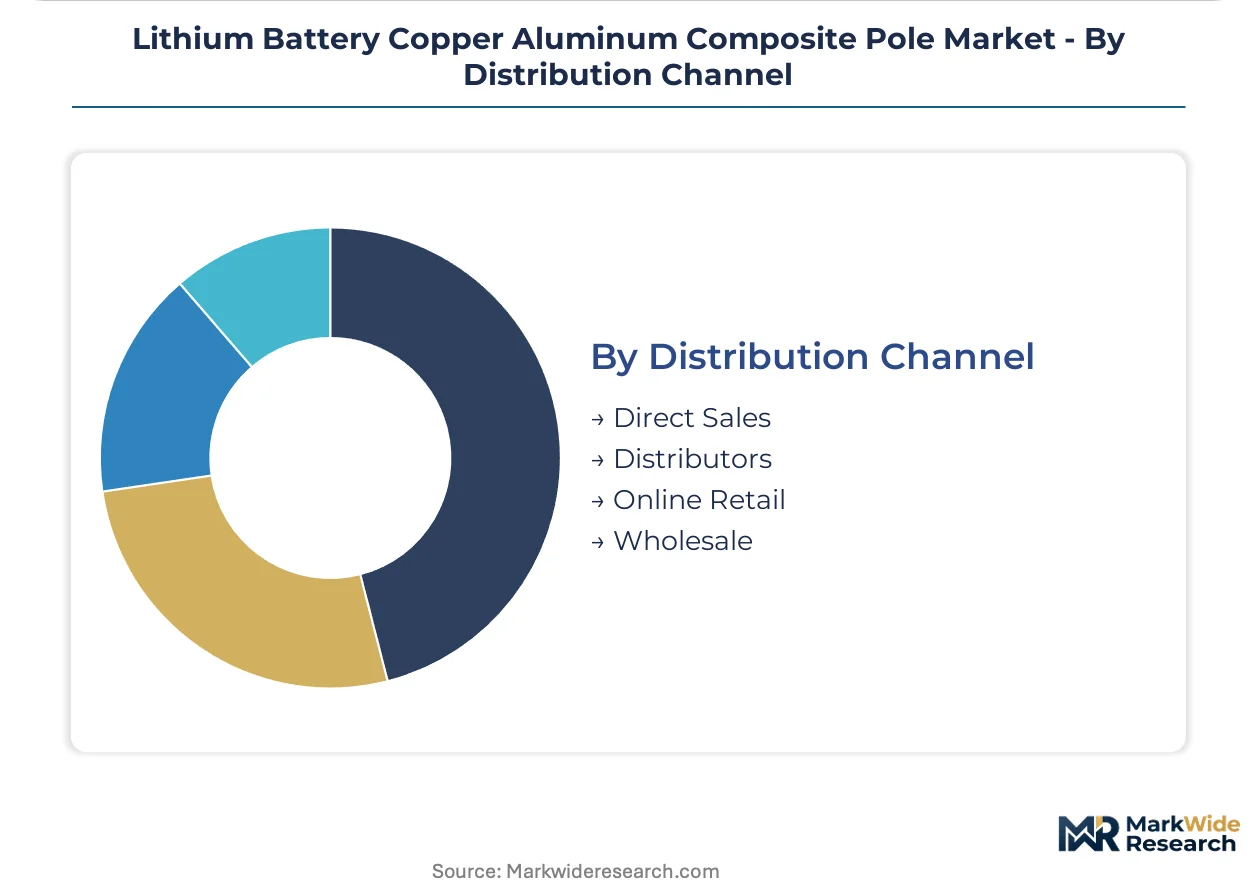
Distribution Channel:
Channel selection reflects traceability requirements and the feasibility of joint technical qualification.
- Direct Sales:Dominant for battery OEMs requiring joint metallurgical validation and lot-level serialization. Hunan Phohom and Dongguan Lingte Technology operate exclusively through this channel for automotive customers.
- Distributors:Limited penetration due to inability to support GB/T compliance documentation. Survive only in consumer electronics spot markets with lower certification burdens.
- Online Retail:Negligible for qualified battery-grade poles. Limited to prototype quantities and research institution purchasing.
- Wholesale:Regional metal traders serving electronics producers with standard-grade roll-bonded strips. Shenzhen commodity markets facilitate small-lot procurement without MIIT certification.
Direct Sales holds contractual volume. Distributors is losing share to mandated supplier consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports composite pole laminates to European automotive assembly plants and Korean battery gigafactories, establishing the dominant trade corridor for metallurgically bonded conductor materials.
China
CATL and BYD procurement volumes drive pole fabrication capacity expansion across Anhui and Sichuan provinces. MIIT enforces GB/T 31485 safety standards for terminal corrosion resistance in high-nickel cell systems. The Shenzhen-Suzhou industrial corridor concentrates cladding specialists alongside electrolyte and separator suppliers serving just-in-time delivery protocols.
Germany
Volkswagen and BMW 800V platform rollouts generate demand for reinforced poles with engineered copper gradients. ECHA REACH Annex XVII restrictions on nickel release mandate reformulation of surface passivation chemistries. Bavarian automotive suppliers qualify explosive bonding vendors through shortened six-month validation cycles.
United States
Tesla's Nevada and Texas gigafactories source composite terminals for cell-to-pack architectures multiplying connection points per module. NHTSA battery safety investigations elevate metallurgical bonding standards for domestic qualification. Michigan-based tier-one pack assemblers consolidate supplier bases to three strategic partners with captive cladding capacity.
South Korea
LG Energy Solution and Samsung SDI solid-state development programs evaluate hybrid pole geometries for sulfide electrolyte hermetic sealing. MFDS battery material hazard classification rules now require SDS documentation for composite oxide layers. Gyeonggi-do manufacturing clusters integrate pole production lines within 200 kilometers of cell assembly plants.
India
Reliance Industries and Ola Electric ACC battery projects under the PLI scheme qualify domestic pole fabricators for production-linked incentive thresholds. BIS certification requirements for battery interconnection materials tighten material traceability standards. Gujarat and Tamil Nadu emerging manufacturing zones attract technology licensors for explosive bonding process transfers.
Lithium Battery Copper Aluminum Composite Pole Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: capital-intensive explosive bonding specialists with licensed blast-chamber facilities, automated roll-bonding operators competing on throughput economics, and vertically integrated battery manufacturers with captive pole production. Competitive positioning hinges on joint qualification speed with OEMs and geographic proximity to gigafactory locations. M&A activity targets cladding equipment access, while capacity expansion concentrates in Anhui and Sichuan provinces near CATL and BYD assembly plants.
Among Chinese fabricators, Hunan Phohom, Dongguan Lingte Technology, and Shenzhen YuQiang New Materials occupy positions representing the explosive bonding, automated roll-bonding, and surface-treatment specialization archetypes respectively. These entities exemplify how regional clustering around Shenzhen and Suzhou industrial corridors creates defensive positioning through logistics integration with downstream battery material suppliers. Suzhou Sumzone and Zhengzhou Guangyuan Battery Material represent secondary-tier operators competing on volume scale within domestic procurement channels. The competitive dynamic favors entities with MIIT-certified metallurgical processes and ERP-to-MES data pipelines supporting lot-traceability mandates from automotive customers.
| Leading Market Players |
|---|
| Hunan Phohom |
| Dongguan Lingte Technology |
| Shenzhen YuQiang New Materials |
| Huihua Composite Material |
| Suzhou Sumzone |
| Zhengzhou Guangyuan Battery Material |
| Zhongze Tech |
| Zetian |
| Shenzhen KingBest Hardware Electronics |
| Others |
Pricing and Supply Chain Analysis
Explosive bonding equipment scarcity among three qualified machinery suppliers worldwide concentrates pricing power with cladding press manufacturers, forcing composite pole fabricators to absorb 18-month order backlogs while battery OEMs demand fixed pricing amid copper futures volatility.
Pricing Analysis
Current-generation explosive bonding commands substantial premiums over roll-bonded alternatives, while next-generation hybrid poles with selective plating remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates MIIT-certified automotive-grade poles from industrial roll-bonded strips and uncertified commodity laminates. Price differentiation hinges on GB/T 31485 corrosion certification and lot-traceability documentation. Cost compression in standard-grade roll-bonded poles is intensifying because Dongguan Lingte Technology's automated lines sustain throughput economics. Electronics producers in Guangdong province exhibit highest price sensitivity, while automotive OEMs prioritize metallurgical qualification over unit economics.
Supply Chain Analysis
Tariff exposure between China and European automotive markets dominates supply chain risk calculations for REACH-compliant surface treatment chemistries. Raw material sourcing draws from Chilean copper cathode, Chinese aluminum smelters, and Korean specialty oxide inhibitors. Component dependencies center on explosive bonding presses, ultrasonic welding electrodes, and silane-based passivation systems. Single-source vulnerability concentrates in blast-chamber equipment licensed through German and Japanese machinery houses. Distribution runs through direct sales channels with ERP-to-MES integration, bypassing distributor intermediaries unable to support joint qualification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-to-pack architecture proliferation fragments procurement across thinner conductor profiles and divergent terminal geometries, creating specialization niches for cladding technology variants.
For Market Incumbents: Build captive production moats through co-location within 200 kilometers of CATL and BYD gigafactories in Anhui and Sichuan provinces. Secure explosive bonding equipment slots through advance deposits with the three qualified machinery suppliers. Defend against roll-bonding entrants by accelerating MIIT certification for 800V architectures. Prioritize backward integration into copper-aluminum coil slitting to control input cost volatility. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-qualified ACC battery supply chain before Reliance Industries and Ola Electric finalize domestic pole vendor rosters. Target cylindrical cell conductive poles for Shenzhen electronics producers with surface-optimized strips requiring lower capital intensity than explosive bonding. Penetrate through silane-based passivation chemistry licensing to Korean battery makers with EU assembly plants. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across explosive bonding infrastructure as blast-chamber equipment backlogs extend. Long-term viability favors acquisition targets with licensed cladding facilities and existing automotive qualification pipelines. Monitor solid-state terminal geometry specifications as inflection indicator for hybrid pole technology licensing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Explosive Bonding Capacity Expansion | Licensed blast-chamber facilities qualify suppliers for 800V European automotive platforms. |
| GB/T 31485 Certification Investment | MIIT corrosion resistance mandates filter tier-two roll-bonding competitors from automotive supply chains. |
| Gigafactory Co-location Partnership | CATL and BYD proximity requirements displace distant pole processors from qualified vendor lists. |
| Silane Passivation Chemistry Licensing | REACH Annex XVII compliance enables European market access for surface treatment specialists. |
| ERP-to-MES Data Pipeline Integration | Lot-traceability mandates from automotive OEMs favor suppliers with serialized production tracking. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with cladding process engineers, battery OEM procurement directors, MIIT certification auditors, and explosive bonding equipment specialists; and secondary validation through customs trade databases, SEC filings of listed battery manufacturers, GB standards documentation, and ECHA REACH registration records. Bottom-up triangulation across regional production capacity and top-down demand modeling from vehicle production databases anchored volume estimates.
Forecast inputs considered cell-to-pack architecture penetration, solid-state battery development timelines, and copper-aluminum price ratio trajectories across the projection horizon. Segmentation dimensions modeled include cladding technology tier, application voltage class, end-user integration depth, and geographic regulatory cluster. CAGRs were derived from slope analysis of year-over-year capacity additions and procurement volume disclosures. Industry-specific forecast inputs encompassed MIIT certification pipeline timelines and explosive bonding equipment delivery schedules.
Stress conditions across copper price volatility bands, REACH regulatory stringency scenarios, and solid-state terminal geometry adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding gigafactory construction cadence and cladding metallurgist labor availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Synthetic Rope Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Composite Cans Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Marine Composites Market
Composite Materials
Molded Underfill Material Market
Composite Materials
Core Material for Composites Market
Composite Materials
Case Material Market
Composite Materials
High-Temperature Composite Materials Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Reinforced Plastic Sheeting Market
Composite Materials
Plastic Composites Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Transportation Composites Market
Composite Materials
Fiber Reinforced Polymer (FRP) Panels and Sheets Market
Composite Materials
CFRP Propeller Shaft Market