
 Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market | 2026-2036
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market Outlook
Japan's Top Runner program for appliance efficiency is realigning specifications toward heat-resistant thermoplastics in power electronics. DIC Corporation leverages captive monomer supply from its Kureha affiliate to sustain cost discipline across the value chain. Polyplastics Co., Ltd anchors regional capacity with compounding operations in Taiwan and mainland China that serve automotive tier ones directly.
Asia-Pacific polyphenylene sulfide composites are high-performance thermoplastic compounds incorporating glass fiber, carbon fiber, or mineral fillers into a semi-crystalline polymer matrix with melting points near 285 degrees Celsius, engineered for dimensional stability in corrosive and high-temperature environments. Carbon fiber reinforced grades command premium positioning due to strength-to-weight requirements in aerospace structural brackets and EV battery trays. Injection molding dominates manufacturing stage volumes because cycle times and part complexity suit automotive and electronics serial production at scale.
China's GB standards for EV battery enclosure flame resistance, Japan's METI material efficiency guidelines, and South Korea's K-REACH chemical registration framework collectively elevate compliance costs for imported and domestic compounds alike. Manufacturers must certify halogen-free formulations and recyclability pathways to maintain market access across all three jurisdictions. Stakeholders should monitor how China's SAMR updates domestic PPS resin testing protocols, as these will cascade into procurement specifications for the region's electronics and automotive supply bases.
Market Dynamics
Automotive electrification across China, Japan, and South Korea is compressing development cycles for thermally stable compounds, forcing compounders to synchronize resin qualification timelines with EV platform launches rather than traditional model-year cadences.
Growth Catalysts
- GB standards for EV battery enclosures:China's flame-resistance mandates for battery housings are pulling high-fill glass fiber grades into serial production. Domestic OEMs now specify PPS compounds for thermal runaway containment.
- Japan's Top Runner appliance efficiency program:METI mandates are redirecting power electronics sourcing toward heat-resistant thermoplastics. Compressor inverters and motor drives now specify 285°C-melting-point resins.
- Yangtze River Delta manufacturing concentration:Tier-one automotive suppliers cluster around Shanghai-Ningbo corridor, creating localized demand density that rewards just-in-time compounding operations.
Market Restraints
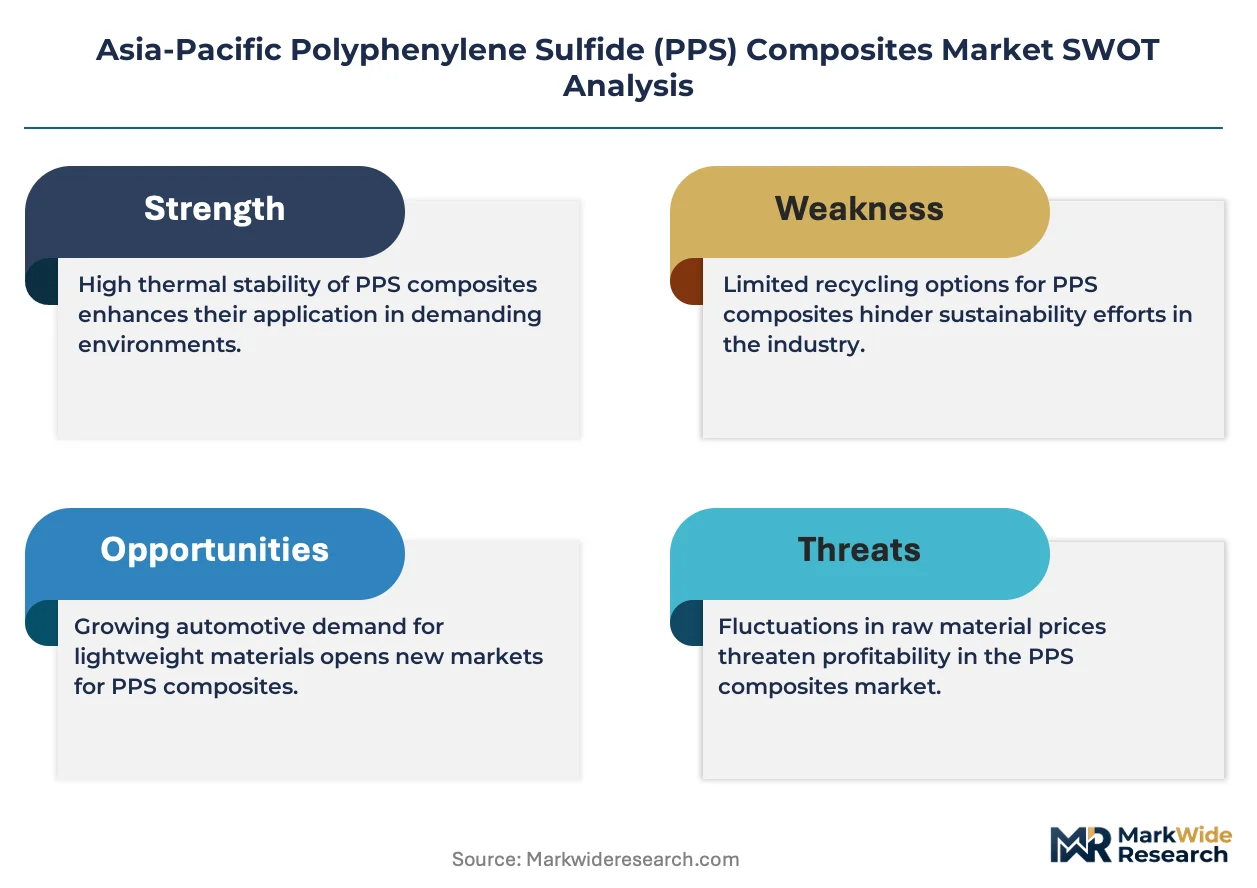
- Para-dichlorobenzene feedstock volatility:Monomer prices fluctuate with chlor-alkali capacity utilization in China, compressing margin predictability for non-integrated compounders.
- K-REACH registration burden:South Korea's chemical framework imposes testing costs on imported PPS grades, creating friction for non-Korean suppliers seeking battery supply chain access.
- Liquid crystal polymer substitution:LCPs compete for high-frequency connector applications in 5G infrastructure, displacing PPS in thin-wall electronic housings where dimensional tolerance is paramount.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging and mobile phone assembly are creating virgin demand for high-temperature connector resins in Tamil Nadu and Karnataka.
- Recyclability certification pathways:Japan's METI and China's SAMR are developing harmonized testing protocols for thermoplastic recyclate streams, rewarding early movers with preferred supplier status.
- Carbon fiber-PPS hybrid development:Aerospace tier ones in Japan are qualifying continuous fiber thermoplastic composites for structural brackets, opening premium positioning beyond conventional injection molding grades.
Industry Challenges
- Polymer rheology expertise scarcity:Compounding operations require technicians capable of optimizing fiber length distribution and crystallization kinetics simultaneously, a skill set concentrated among aging workforces in Japan and Taiwan.
- Multi-jurisdiction certification timelines:Simultaneous GB standard, JIS, and K-REACH compliance testing extends qualification cycles for new formulations, delaying revenue recognition.
- Legacy equipment retrofit costs:Converting polyamide or PBT-dedicated molding lines to PPS processing requires screw and barrel upgrades due to corrosion and wear rates, straining mid-tier processor capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market |
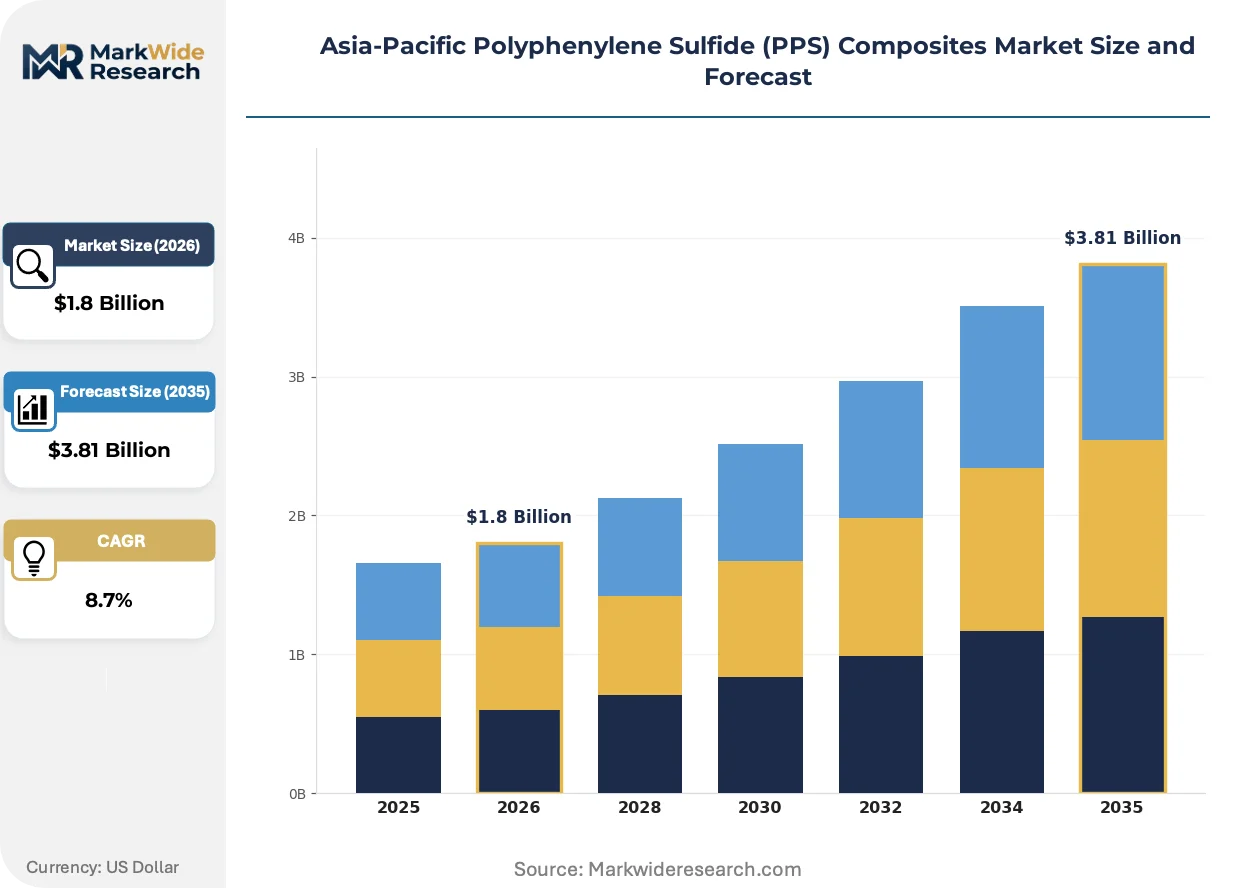
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Fiber Reinforced, Carbon Fiber Reinforced, Mineral Filled, Impact Modified End Use Industry: Aerospace, Automotive, Electronics, Industrial Form: Sheet, Rod, Film, Granules Manufacturing Stage: Injection Molding, Compression Molding, Extrusion, Thermoforming |
| Companies Covered | DIC Corporation, SABIC, Teijin Limited, Celanese Corporation, Solvay, Polyplastics Co., Ltd, Tosoh Corporation, Kolon Plastics Inc., Kureha Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market Strategic Shifts
Material innovation in the Asia-Pacific PPS composites market is pivoting from incremental filler loading optimization toward radical process-structure integration, driven by EV thermal management requirements and electronics miniaturization pressures.
Continuous carbon fiber-reinforced PPS tapes are absorbing structural load-bearing functions previously assigned to metal stampings or epoxy prepregs. Aerospace tier ones in Nagoya and automotive battery tray suppliers in Shenzhen are trialing automated fiber placement and stamp-forming processes. This technology is absorbing capital investment that would otherwise flow toward conventional injection molding capacity expansions.
China's SAMR is revising GB/T resin testing protocols to incorporate flame-retardant performance under thermal runaway simulation conditions. The industrial consequence is a bifurcation between legacy halogen-containing grades and halogen-free formulations that can pass updated smoke density requirements. Battery enclosure manufacturers in Jiangsu and Zhejiang are reformulating compound recipes to maintain access to domestic OEM qualification lists.
Direct sourcing relationships between EV original equipment manufacturers and resin compounders are displacing traditional distributor-mediated procurement in South Korea. Hyundai-Kia and Samsung SDI procurement teams now conduct technical audits at compounding facilities rather than relying on material trading houses. This pattern is most visible in Gyeonggi-do province, where battery cell and pack assembly plants cluster within 50 kilometers of PPS compounding operations.
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market Segmentation
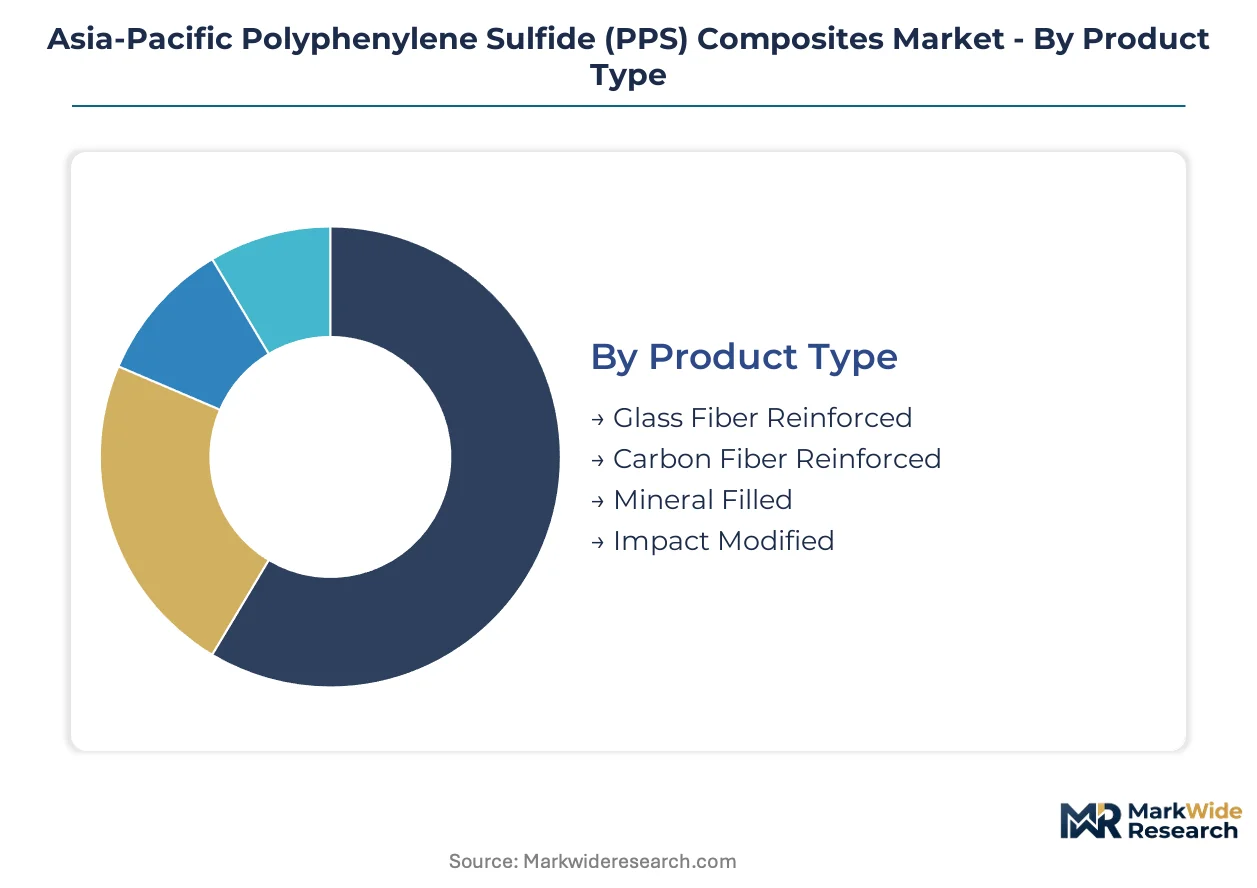
PPS composite formulations diverge sharply across reinforcement chemistry and processing geometry, with each configuration commanding distinct qualification protocols and supply chain footprints. Compounders must align capacity investments with the specific thermal and mechanical thresholds demanded by end-use certification regimes.
Product Type:
Glass fiber and carbon fiber reinforced grades concentrate compounding capacity around the Yangtze River Delta and Japan's Kansai corridor, where captive monomer supply and automotive tier-one proximity intersect.
- Glass Fiber Reinforced:These compounds incorporate 30-60% chopped or long glass fiber to achieve tensile strengths exceeding 150 MPa while maintaining cost positioning below carbon alternatives. China's GB standard flame-resistance mandates for EV battery enclosures are pulling high-fill grades into serial production at Jiangsu and Zhejiang molding facilities. Domestic OEMs now specify these formulations for thermal runaway containment structures.
- Carbon Fiber Reinforced:Continuous fiber thermoplastic tapes and chopped fiber compounds deliver strength-to-weight ratios critical for aerospace structural brackets and EV battery trays. Aerospace tier ones in Nagoya and automotive suppliers in Shenzhen are trialing automated fiber placement processes that absorb capital investment away from conventional injection molding expansions.
- Mineral Filled:Talc and calcium carbonate loadings reduce warpage in precision electronic housings for 5G infrastructure components.
- Impact Modified:Elastomer-modified grades balance ductility with heat resistance for industrial pump housings and fluid handling systems.
Glass fiber reinforced grades absorb the bulk of installed capacity; carbon fiber reinforced is expanding most quickly.
End Use Industry:
Application-driven demand splits across mobility electrification, electronics densification, and industrial corrosion resistance, with each vertical imposing distinct certification timelines and volume profiles.
- Automotive:Battery enclosure manufacturers specify halogen-free PPS compounds to satisfy China's SAMR flame-resistance protocols under thermal runaway simulation. Hyundai-Kia and Samsung SDI procurement teams now conduct direct technical audits at compounding facilities in Gyeonggi-do province, bypassing traditional distributor channels.
- Electronics:Power semiconductor packaging and high-frequency connector housings require 285°C melting-point stability under Japan's METI efficiency mandates. Compressor inverters and motor drives in appliance and industrial motor applications specify heat-resistant thermoplastics that displace thermoset alternatives.
- Aerospace:Structural bracket qualification programs in Japan are absorbing continuous carbon fiber-PPS composite development investment.
- Industrial:Chemical processing equipment and oil field components exploit PPS corrosion resistance against sour gas and aggressive process fluids.
Automotive applications command the dominant share of compounder technical service resources; electronics applications are climbing the fastest as 5G infrastructure deployment accelerates.
Form:
Physical configuration determines downstream processing economics and geographic distribution feasibility, with granule and sheet formats dominating contrasting end-use clusters.
- Granules:Pelletized compounds feed injection molding and extrusion lines across automotive and electronics serial production. Just-in-time compounding operations in the Shanghai-Ningbo corridor optimize logistics for tier-one automotive suppliers.
- Sheet:Compression-molded and extruded sheets serve thermoforming operations for aircraft interior panels and battery tray substructures.
- Rod:Machinable stock shapes target prototype development and low-volume industrial component fabrication.
- Film:Thin-gauge extruded films address capacitor dielectric and flexible circuit substrate applications in semiconductor packaging.
Granule shipments represent the highest volume format; sheet formats are gaining share fastest as thermoforming displaces metal stamping in battery enclosure fabrication.
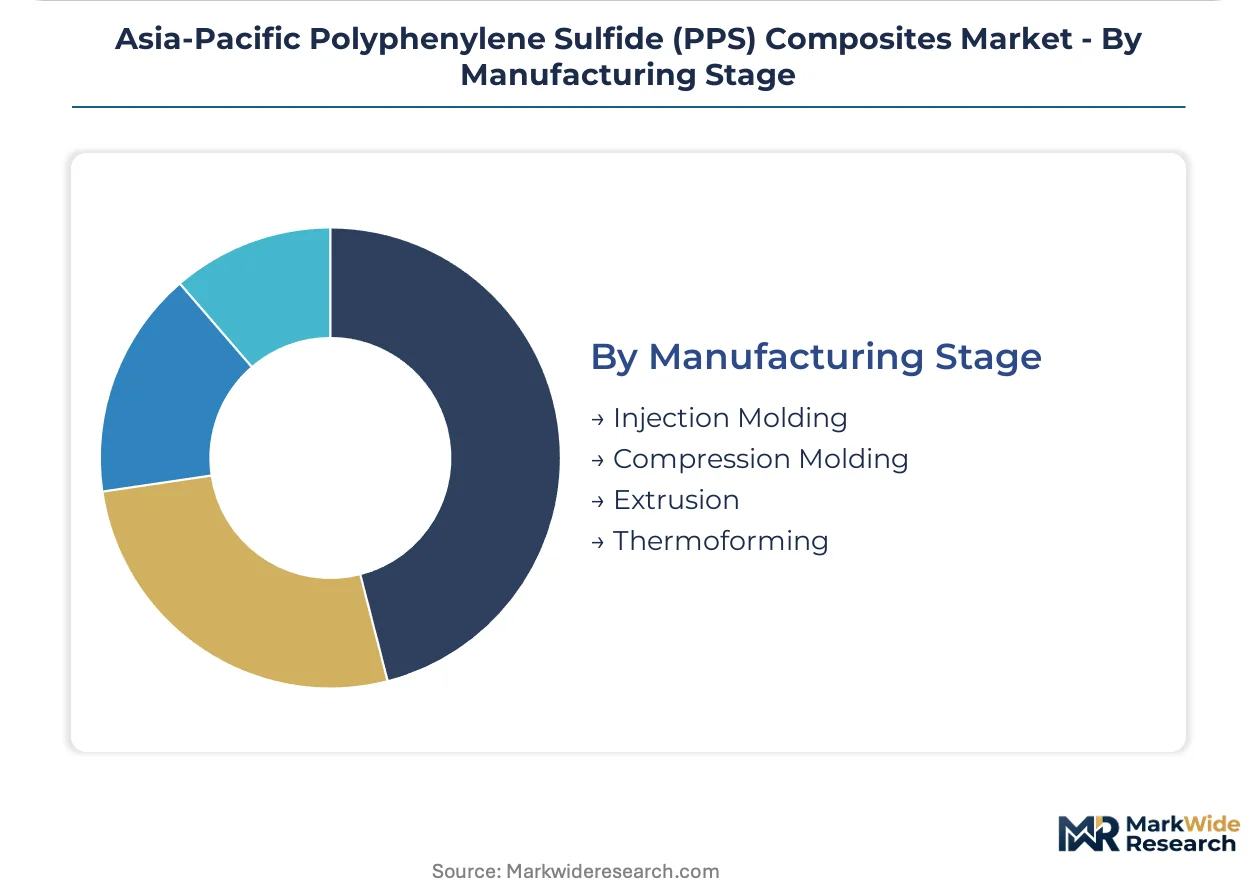
Manufacturing Stage:
Process selection crystallizes around part complexity, fiber orientation control, and cycle time requirements, with injection molding anchoring regional capacity investments.
- Injection Molding:High-pressure molding of fiber-reinforced compounds dominates automotive and electronics serial production due to cycle time efficiency and geometric complexity capability. Legacy polyamide and PBT-dedicated lines require screw and barrel retrofits to handle PPS corrosion and wear rates.
- Compression Molding:Sheet molding compounds and bulk molding compounds serve larger structural components where fiber length preservation outweighs cycle time considerations.
- Extrusion:Profile and film extrusion lines supply continuous geometries for electrical insulation and chemical processing applications.
- Thermoforming:Heated sheet forming of pre-consolidated composite laminates is emerging for aerospace bracket and battery tray fabrication.
Injection molding commands the majority of installed machine hours; thermoforming is expanding most quickly as continuous fiber composite formats penetrate structural applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of PPS resin feedstock while Japan and South Korea consume premium compounds for automotive and electronics applications. This production-consumption asymmetry shapes cross-border supply arrangements and qualification protocols across the region.
China
Domestic OEMs specify halogen-free PPS compounds for EV battery enclosures under SAMR's updated flame-resistance protocols. The dual carbon goals tighten material efficiency benchmarks for automotive suppliers. Yangtze River Delta manufacturing clusters around Shanghai and Ningbo concentrate tier-one compounding operations serving battery pack assemblers.
Japan
METI's Top Runner appliance efficiency program redirects power electronics sourcing toward 285°C-melting-point thermoplastics. Compressor inverters and motor drives now displace thermoset alternatives in industrial and consumer applications. Kansai corridor facilities leverage captive monomer supply from Kureha-affiliated operations to sustain cost discipline.
South Korea
Hyundai-Kia and Samsung SDI procurement teams conduct direct technical audits at compounding facilities rather than relying on distributor channels. K-REACH chemical registration imposes testing costs on imported grades, creating friction for non-Korean suppliers. Gyeonggi-do province hosts clustered battery cell and pack assembly plants within 50 kilometers of PPS compounding operations.
India
PLI scheme incentives for semiconductor packaging and mobile phone assembly generate virgin demand for high-temperature connector resins. Tamil Nadu and Karnataka electronics manufacturing clusters attract compounder technical service resources. Domestic processing capacity remains limited, creating import dependency for certified grades.
Taiwan
Polyplastics Co., Ltd anchors regional compounding capacity with operations serving automotive tier ones directly. Precision electronics molding for 5G infrastructure components consumes mineral-filled grades for dimensional stability. The island's semiconductor packaging ecosystem pulls specialty film and granule formats for capacitor dielectric applications.
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market Competitive Environment
The competitive structure tilts toward integrated petrochemical conglomerates with captive monomer supply. Japanese and Korean players dominate premium compound qualification through direct OEM relationships. Three archetypes populate the landscape: resin producers with backward integration into para-dichlorobenzene, independent compounders serving distributor channels, and automotive-tier-one captive compounding operations. Capacity expansion and strategic partnerships represent the dominant competitive moves, with direct technical auditing displacing traditional procurement mediation.
Among Japanese chemical conglomerates, DIC Corporation and Teijin Limited exemplify the integrated archetype through Kureha-affiliated monomer supply and carbon fiber composite development respectively. Polyplastics Co., Ltd occupies a position bridging resin production and regional compounding proximity to automotive clusters. These three anchors illustrate how qualification timelines and captive supply chains determine competitive positioning in thermally stable compound markets.
| Leading Market Players |
|---|
| DIC Corporation |
| SABIC |
| Teijin Limited |
| Celanese Corporation |
| Solvay |
| Polyplastics Co., Ltd |
| Tosoh Corporation |
| Kolon Plastics Inc. |
| Kureha Corporation |
| Others |
Value Chain & Pricing Dynamics
Direct technical audits by Hyundai-Kia and Samsung SDI procurement teams are compressing distributor margins and forcing compounders to absorb certification costs upfront, reshaping how pricing power distributes across integrated versus non-integrated resin suppliers.
Pricing Analysis
Yield-optimized throughput pricing anchors premium grades, where compounders capture value based on thermal runaway containment performance in EV battery enclosures rather than resin weight. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-standard grades reflects certification investment recovery timelines. Cost compression in glass fiber reinforced tiers intensifies because domestic Chinese compounders are expanding high-fill capacity around the Yangtze River Delta. Tier-one automotive suppliers exhibit lowest price sensitivity due to platform qualification lock-in; mid-tier electronics molders face highest pressure as LCP substitution threatens connector applications.
Supply Chain Analysis
Polymer rheology expertise scarcity in Japan and Taiwan concentrates high-skill compounding operations among aging workforces, constraining capacity expansion regardless of capital availability. Feedstock draws from para-dichlorobenzene producers in China, carbon fiber suppliers in Japan, and glass fiber operations across the region. Single-source vulnerability runs through Kureha-affiliated monomer supply that DIC Corporation and Polyplastics Co., Ltd control. Distribution feeds from just-in-time compounding facilities directly to automotive tier ones, bypassing traditional material trading houses in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Para-dichlorobenzene feedstock concentration among integrated Japanese petrochemical conglomerates props pricing power, constraining margin recovery for non-integrated compounders seeking automotive qualification.
For Market Incumbents: Hedge against LCP substitution in high-frequency electronics by accelerating halogen-free formulation certification under China's SAMR protocols. Secure backward integration into para-dichlorobenzene through long-term offtake agreements with chlor-alkali producers in China. Expand compounding footprint within 50 kilometers of Gyeonggi-do battery assembly clusters to meet Hyundai-Kia direct audit requirements. For New Entrants and Emerging Players: E-commerce-enabled technical service platforms offer a route to bypass established distributor relationships in India's PLI-driven electronics manufacturing clusters. Target Tamil Nadu and Karnataka connector resin demand where domestic processing capacity remains limited and import dependency creates qualification windows. Lead with rapid GB standard compliance testing as a service bundled with compound supply. For Investors and Strategic Acquirers: The window for entry favors compounders with captive monomer supply and existing automotive tier-one relationships. Long-term viability hinges on positioning ahead of recyclability certification harmonization between Japan's METI and China's SAMR. Watch for SAMR protocol updates as the inflection trigger that will cascade through regional procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive para-dichlorobenzene production insulates margin from chlor-alkani capacity volatility in China. |
| Halogen-Free Formulation Certification | GB standard compliance under SAMR protocols secures access to domestic OEM qualification lists. |
| Proximity Compounding Expansion | Gyeonggi-do facility placement enables direct technical audits by Hyundai-Kia procurement teams. |
| Continuous Fiber Composite Development | Automated fiber placement qualification with Nagoya aerospace tier ones opens premium positioning. |
| Recyclability Protocol Alignment | Harmonized METI-SAMR testing pathway rewards early movers with preferred supplier status. |
Study Parameters
Independent corroboration across technical directors at compounding facilities, procurement leads at automotive tier ones, and regulatory affairs specialists at resin producers underwrites the qualitative findings. Primary interviews with plant managers, OEM material engineers, and distribution channel partners combined with secondary validation from customs data, chemical industry association reports, and SEC filings of listed petrochemical conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable historical reference periods anchored the forecast window to pre-pandemic qualification cycle norms and post-GB standard implementation demand shifts. Segmentation dimensions span reinforcement chemistry, end-use industry vertical, physical form factor, and manufacturing process geometry across the projection horizon. CAGRs derive from installed capacity expansion schedules, OEM platform launch timelines, and substitution elasticity estimates for LCP and thermoset alternatives.
Inputs from SAMR protocol draft releases and METI efficiency mandate consultations were available through the study window; gaps in real-time compounding capacity utilization data introduce uncertainty bands around near-term supply-demand balance. Forecasts reflect assumptions regarding K-REACH registration timelines and chlor-alkali capacity additions. A small set of regulatory protocol finalizations and OEM platform qualification decisions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Global Honeycomb Core Materials Market
Composite Materials
Graphite Felt Market
Composite Materials
Global Coupling Agents Market
Composite Materials
Global Composites Cylinder Market
Composite Materials
Thermoplastic Honeycomb Market
Composite Materials
Wind Turbine Blade Repair Material Market
Composite Materials
Composite Adhesives Market
Composite Materials
Composites Testing Market
Composite Materials
Case Material Market
Composite Materials
North America Molded FRP Grating Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Epoxy Composite Market
Composite Materials
FRP Grating Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Green Composites Market
Composite Materials
Aramid Fiber Reinforced Polymer Market