
 Geosynthetic Cementitious Composite Mats Market | 2026-2036
Geosynthetic Cementitious Composite Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Geosynthetic Cementitious Composite Mats Market Foresight
Direct-to-contractor distribution is tilting toward specification-driven procurement as infrastructure developers tighten material qualification protocols. TenCate Geosynthetics leverages its geosynthetics manufacturing heritage to anchor premium positioning in reinforced mat configurations. Solmax competes through integrated geomembrane-to-mat system offerings that reduce field installation complexity. Concrete Canvas Ltd. specializes in cementitious impregnated fabric technology that dominates rapid-deployment shoreline protection contracts.
Geosynthetic cementitious composite mats combine polymeric geotextile substrates with Portland cement or modified cementitious coatings, forming flexible roll goods that hydrate on-site to create thin rigid armor layers typically 5–25 mm thick after curing. Their primary purpose is to replace conventional poured concrete or riprap in erosion control and slope stabilization where access constraints, speed of installation, or environmental sensitivity limit traditional methods. Woven mats occupy the largest volume share due to established supply chains and predictable tensile performance in embankment reinforcement, while hybrid mats represent the fastest-expanding category as polymer modification technologies improve flexural durability in freeze-thaw cycles. Cementitious coating technology concentrates margin pools through proprietary formulation barriers and application equipment lock-in.
EPA stormwater regulations in the United States, EU Green Deal sustainability criteria under REACH and CE marking frameworks, and Australian state-level environmental protection mandates collectively shape product certification requirements and market access conditions for geosynthetic cementitious composite mats. Infrastructure developers and civil engineers must monitor evolving polymer modification standards and hydration performance benchmarks as specification bodies tighten field-proven durability thresholds.
Market Dynamics
Specification-driven procurement is tightening material qualification protocols across infrastructure sectors, forcing manufacturers to prove field-proven durability before contract award. This shift elevates barriers for commodity suppliers while rewarding proprietary formulation capabilities.
Growth Catalysts
- EPA Stormwater Regulations:United States infrastructure mandates require erosion-resistant materials for channel lining and slope stabilization, creating compliance-driven demand for certified mat systems.
- Polymer Modification Advances:Enhanced flexural durability in freeze-thaw cycles expands serviceable climate zones for cementitious composite mats.
- Australian State Protection Mandates:National infrastructure resilience programs specify rapid-deployment shoreline protection, accelerating specification of cementitious impregnated fabric technology.
Market Restraints
- Portland Cement Price Volatility:Energy-intensive clinker production exposes manufacturers to input cost swings that compress margin pools on fixed-price infrastructure contracts.
- Proprietary Equipment Lock-in:Specialized application machinery requirements limit contractor flexibility and create switching costs that slow adoption among smaller installation firms.
- Riprap Substitution Economics:Conventional rock armor retains cost advantages in remote sites with abundant local aggregate supply, constraining addressable market expansion.
Strategic Opportunities
- EU Green Deal Sustainability Criteria:REACH and CE marking frameworks favor low-carbon erosion control solutions, positioning polymer-modified mats for specification preference in European civil engineering.
- Hydration Monitoring Integration:Convergence of embedded moisture sensors with cementitious coating systems enables real-time quality assurance and outcome-based contracting models.
- Direct-to-Contractor Digital Platforms:Bypassing traditional distribution layers through specification databases and online qualification portals reduces friction in project bidding workflows.
Industry Challenges
- Geosynthetics Installation Certification:Qualified technician scarcity delays field deployment and raises labor costs for complex embankment reinforcement projects.
- Multi-Standard Harmonization Delays:Divergent hydration performance benchmarks across EPA, EU, and Australian specification bodies fragment product development roadmaps.
- Legacy Concrete Specification Inertia:Civil engineering procurement templates default to poured concrete methods, requiring sustained technical education to displace established practice.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geosynthetic Cementitious Composite Mats Market |
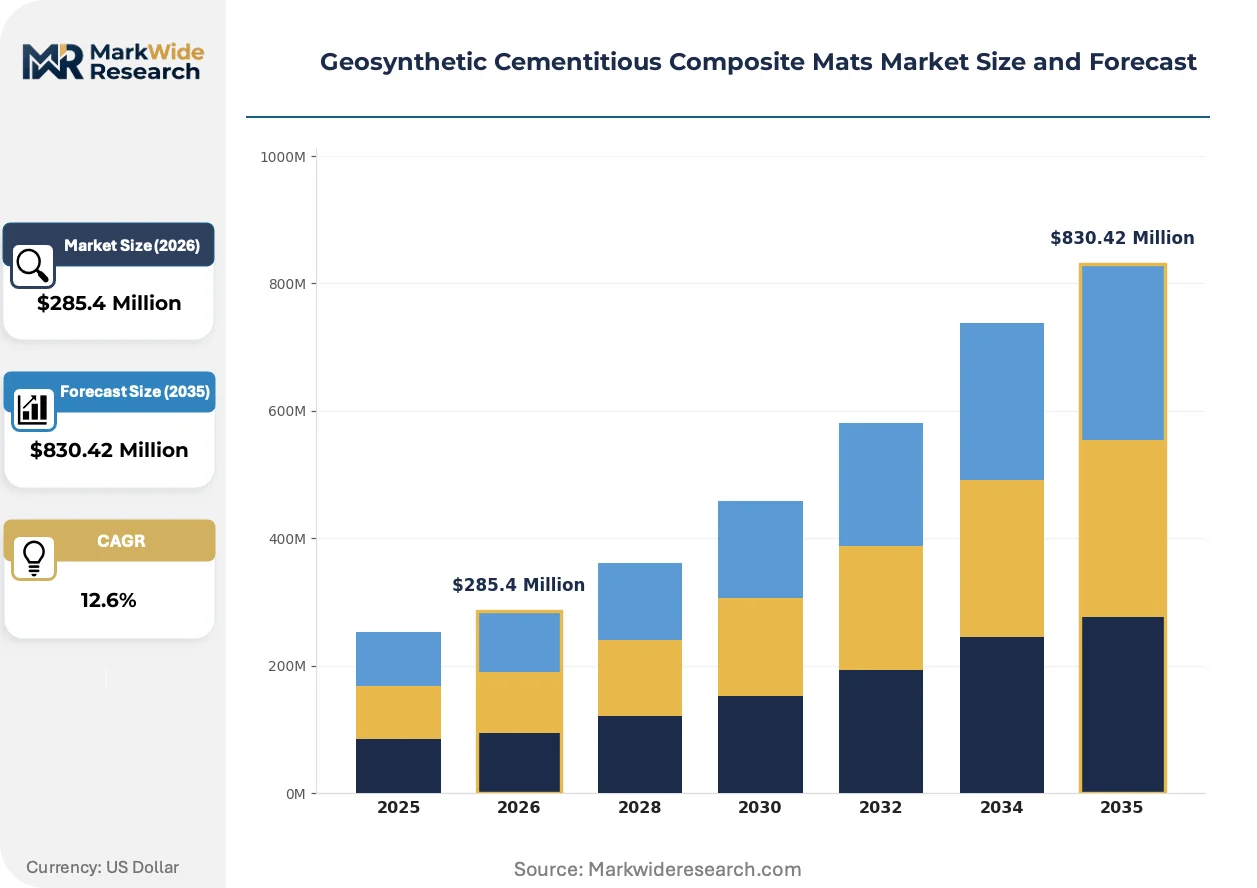
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $830.42 Million |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Mats, Non-Woven Mats, Reinforced Mats, Hybrid Mats, Permeable Mats Technology: Fiber Reinforcement, Mesh Reinforcement, Cementitious Coating, Polymer Modification, Composite Lamination Application: Erosion Control, Slope Stabilization, Shoreline Protection, Embankment Reinforcement, Channel Lining End User: Construction Contractors, Civil Engineers, Infrastructure Developers, Environmental Agencies, Industrial Fabricators |
| Companies Covered | TenCate Geosynthetics, Solmax, Concrete Canvas Ltd., GCP Applied Technologies, Milliken & Company, ACE Geosynthetics, Tensar International, Propex, Huesker Synthetic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geosynthetic Cementitious Composite Mats Market Shifts & Advancements
Digital integration and sustainability mandates are restructuring how cementitious composite mats are specified, installed, and validated across infrastructure value chains. These forces compress traditional procurement cycles while elevating performance transparency requirements.
Embedded sensor arrays are digitizing quality assurance workflows for cementitious mat installations. Transportation agencies in Germany and the Netherlands now pilot moisture and temperature monitoring during hydration, enabling real-time cure verification. This capability is digitizing contract administration by replacing destructive core sampling with continuous data logging that reduces inspection delays and dispute resolution costs.
REACH polymer registration requirements are tightening acceptable additive chemistries for cementitious coatings. ECHA substance evaluation processes now scrutinize plasticizers and retarders used in flexible mat formulations, forcing reformulation investments. European manufacturers are responding by accelerating bio-based polymer modifier development to preempt regulatory exclusion of legacy petrochemical additives.
Performance-based procurement is displacing unit-price contracting in Australian state infrastructure programs. Queensland and New South Wales transport authorities now specify erosion control outcomes rather than material quantities, shifting risk to installation contractors. This behavioral shift concentrates contract awards among vertically integrated firms that control both mat supply and placement quality, compressing the viable vendor base.
Geosynthetic Cementitious Composite Mats Market Segmentation
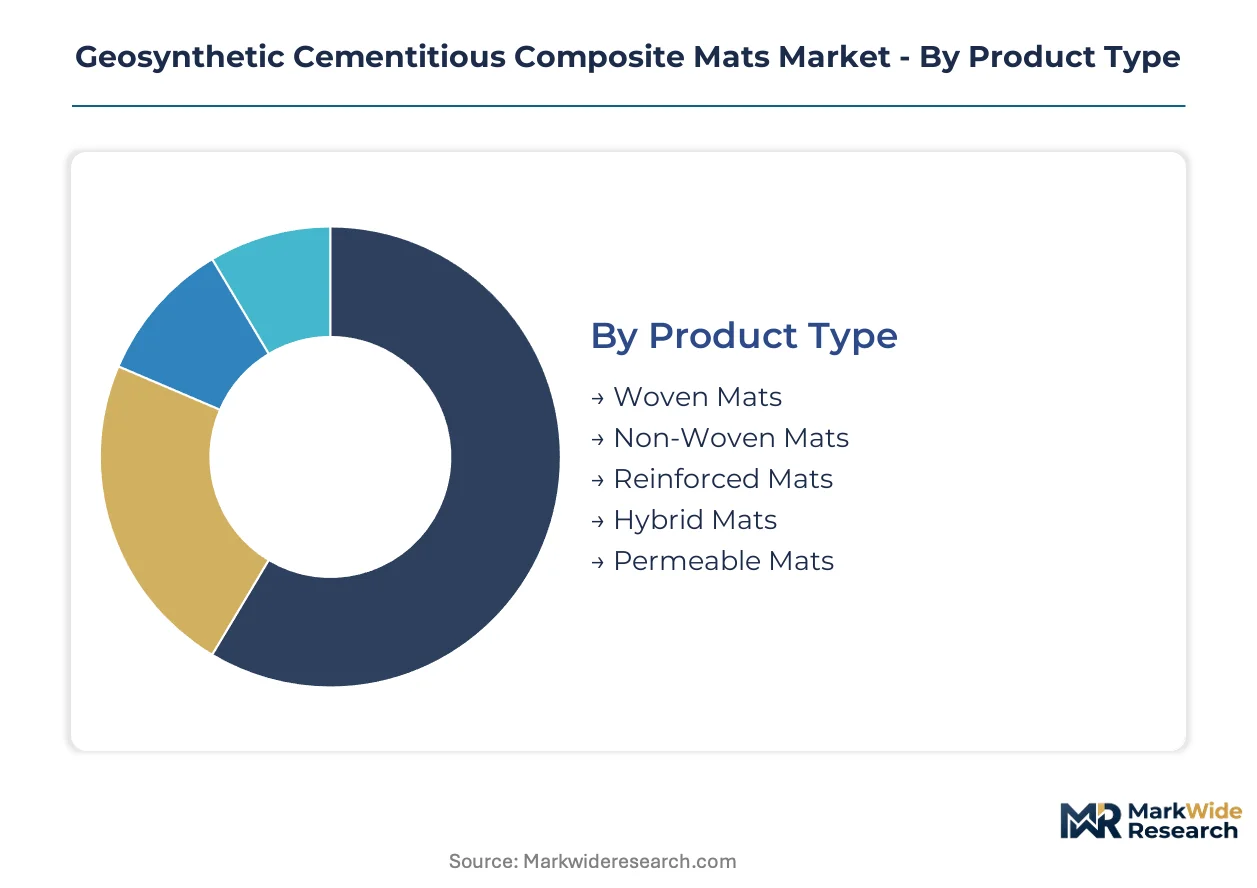
Product differentiation in geosynthetic cementitious composite mats hinges on substrate architecture and coating chemistry, with each configuration matching specific site constraints and performance specifications. Segmentation reveals how manufacturers align material capabilities with procurement protocols across infrastructure value chains.
Product Type:
Mature woven configurations dominate established supply chains while hybrid innovations capture specification-driven upgrades for severe climate exposure.
- Woven Mats:Polypropylene or polyester filament substrates form the structural backbone through interlaced yarn patterns delivering predictable tensile strength in bidirectional stress fields. These configurations anchor volume demand in United States channel lining contracts where EPA stormwater compliance mandates proven field performance.
- Hybrid Mats:Layered combinations of woven scrims with non-woven geotextile cores integrate polymer-modified cementitious coatings for enhanced freeze-thaw durability. Australian state infrastructure programs specify these systems for rapid-deployment shoreline protection where thermal cycling resistance determines service life.
- Non-Woven Mats:Needle-punched continuous filament structures provide isotropic filtration and cushioning properties for subgrade stabilization applications.
- Reinforced Mats:High-tenacity geogrid integration creates composite systems for steep slope anchoring where tensile reinforcement exceeds standard mat capabilities.
- Permeable Mats:Open-weave architectures with controlled void ratios manage groundwater pressure in saturated embankment conditions.
Woven mats handle the majority of throughput; hybrid mats are the fastest mover on share.
Technology:
Coating chemistry and reinforcement integration separate commodity supply from premium specification tiers, with proprietary formulation barriers protecting margin pools.
- Cementitious Coating:Portland cement or modified cement slurries impregnate geotextile substrates to form rigid armor layers upon hydration, with proprietary spray application equipment creating vendor lock-in. German transportation agencies pilot embedded moisture sensors for real-time cure verification, digitizing quality assurance workflows.
- Polymer Modification:Acrylic or EVA latex additives enhance flexural toughness and reduce crack propagation under cyclic loading. REACH registration requirements for plasticizers and retarders force European manufacturers toward bio-based polymer development.
- Fiber Reinforcement:Discontinuous synthetic or natural fibers distributed throughout cementitious matrices improve post-crack integrity.
- Mesh Reinforcement:Welded wire or polymer grid inclusions provide macro-scale tensile capacity for high-stress embankment applications.
- Composite Lamination:Multi-layer bonding of dissimilar geosynthetic and cementitious elements creates engineered performance gradients.
Cementitious coating technology commands the widest specification footprint; polymer modification is climbing the fastest on technical qualification priority.
Application:
Site-specific erosion mechanisms and access constraints dictate mat selection, with regulatory compliance intensity varying by infrastructure asset class.
- Erosion Control:Surface armor applications on disturbed soils and cut slopes deploy mats as alternatives to riprap or poured concrete where equipment access is limited. United States infrastructure developers favor these systems for EPA-compliant stormwater management on linear transportation corridors.
- Shoreline Protection:Wave energy dissipation and scour resistance at coastal and riparian interfaces require rapid-deployment fabric technology. Australian state environmental protection mandates accelerate specification of cementitious impregnated systems for emergency repair and climate adaptation projects.
- Slope Stabilization:Vegetated or hard-armored face protection on engineered embankments combines mat installation with soil bioengineering techniques.
- Embankment Reinforcement:Structural inclusion of mats within fill zones provides internal stability for steepened slopes and retaining structures.
- Channel Lining:Hydraulic armor for drainage conveyances resists flow velocities that exceed unprotected soil thresholds.
Erosion control absorbs the largest project volume; shoreline protection is gaining share fastest on climate resilience program funding.
End User:
Procurement authority and technical qualification requirements fragment the customer base across specification influencers and installation executors.
- Infrastructure Developers:Public and private asset owners set material qualification protocols and outcome-based performance criteria. Queensland and New South Wales transport authorities now specify erosion control outcomes rather than material quantities, concentrating contract awards among vertically integrated supply-placement firms.
- Civil Engineers:Design consultants translate site geotechnical conditions into mat specification parameters and installation detailing. Their template libraries default toward legacy concrete methods, requiring sustained technical education to displace established practice.
- Construction Contractors:Installation firms execute field placement and manage hydration quality under performance-risk contracting models.
- Environmental Agencies:Regulatory bodies enforce compliance with EPA, ECHA, and state-level protection mandates that shape product certification requirements.
- Industrial Fabricators:Specialty manufacturers integrate mats into precast or modular systems for factory-controlled quality environments.
Infrastructure developers control specification gatekeeping; civil engineers represent the steepest expansion trajectory as performance-based procurement spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA stormwater regulations anchor the dominant geography, with infrastructure resilience programs across multiple jurisdictions accelerating specification of erosion-resistant materials. National environmental mandates in the United States, Germany, and Australia concentrate procurement authority for channel lining and slope stabilization applications.
United States
Federal transportation agencies and state departments of transportation drive specification volume for channel lining contracts. EPA stormwater regulations mandate erosion-resistant materials for linear infrastructure corridors, tightening material qualification protocols before contract award. Texas and California transportation districts pilot embedded moisture sensors for real-time cure verification during cementitious mat hydration.
Germany
Transportation agencies in Bavaria and North Rhine-Westphalia pilot digital quality assurance workflows for embankment reinforcement projects. EU Green Deal sustainability criteria under REACH and CE marking frameworks favor low-carbon erosion control solutions, positioning polymer-modified mats for specification preference. German manufacturers accelerate bio-based polymer modifier development to preempt regulatory exclusion of legacy petrochemical additives.
Australia
Queensland and New South Wales transport authorities specify erosion control outcomes rather than material quantities, shifting risk to installation contractors under performance-based procurement. State-level environmental protection mandates accelerate specification of rapid-deployment shoreline protection systems. Sydney and Melbourne infrastructure programs concentrate contract awards among vertically integrated supply-placement firms.
United Kingdom
Environment Agency flood defense programs and Network Rail earthworks specifications drive demand for slope stabilization applications. UK implementation of EU-derived environmental standards maintains stringent material certification requirements post-Brexit. The Midlands and North England concentrate civil engineering contractor activity for transportation and water infrastructure projects.
Canada
Provincial transportation ministries in Ontario and British Columbia specify erosion control materials for highway embankment and shoreline protection contracts. Health Canada and Environment and Climate Change Canada coordinate on chemical substance assessments affecting polymer modifier formulations. The Greater Toronto Area anchors specification activity for municipal infrastructure resilience programs.
Geosynthetic Cementitious Composite Mats Market Competitive Landscape
Integrated geosynthetics manufacturers and specialized cementitious fabric developers split the market along capability lines. The vendor base concentrates among firms with proprietary formulation expertise and established field-proven performance records. Three archetypes dominate: heritage geosynthetics producers leveraging substrate manufacturing scale, cementitious coating specialists controlling application technology lock-in, and hybrid system integrators bundling geomembrane-to-mat offerings. Competitive dynamics center on specification database positioning and direct-to-contractor digital platform development.
Among heritage geosynthetics manufacturers, TenCate Geosynthetics and Solmax occupy positions representing substrate-scale and system-integration archetypes respectively. Concrete Canvas Ltd. exemplifies the cementitious fabric specialization vector. These three firms anchor the premium specification tier where proprietary equipment requirements and material qualification protocols create vendor stickiness.
| Leading Market Players |
|---|
| TenCate Geosynthetics |
| Solmax |
| Concrete Canvas Ltd. |
| GCP Applied Technologies |
| Milliken & Company |
| ACE Geosynthetics |
| Tensar International |
| Propex |
| Huesker Synthetic |
| Others |
Supply & Pricing Matrix
The Port of Rotterdam-Antwerp corridor shapes cost dynamics for geosynthetic cementitious composite mats moving from German manufacturing clusters to North Sea infrastructure projects, concentrating pricing power among suppliers with captive polymer modification capabilities while forcing smaller fabricators into commodity tiers.
Pricing Analysis
The customization-premium spread separates proprietary cementitious coating systems from standard woven mat configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA stormwater protocols and EU CE marking frameworks. Cost compression in the economy tier is intensifying because Portland cement price volatility exposes fixed-price infrastructure contractors to margin erosion. Municipal transportation departments exhibit highest price sensitivity due to constrained capital budgets, while private infrastructure developers absorb premium tiers for outcome-based performance contracting.
Supply Chain Analysis
Upstream feedstock flows center on polypropylene resin production in Germany, Belgium, and the Netherlands, with Portland cement sourcing concentrated in regional clinker facilities. Raw material dependencies include petroleum-derived geotextile substrates, modified cement slurries, and acrylic polymer additives. Single-source vulnerability in specialized spray application equipment creates vendor lock-in risks for installation contractors. Distribution runs through specification-driven direct-to-contractor channels and qualified distributor networks serving civil engineering procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrastructure spending cycles position the geosynthetic cementitious composite mats market for cyclical recovery, with EPA stormwater regulation enforcement waves driving replacement demand for aging erosion control assets.
For Market Incumbents: Insulate specification database positioning through accelerated bio-based polymer modifier R&D to preempt REACH regulatory exclusion of legacy petrochemical additives. Deepen backward integration into cementitious coating formulation to defend margin pools against Portland cement price volatility. Lock in qualified technician training partnerships to address installation certification scarcity.
For New Entrants and Emerging Players: Establish a beachhead in Australian state-level rapid-deployment shoreline protection contracts where performance-based procurement concentrates awards among new supply-placement integrators. Target hybrid mat configurations for freeze-thaw climate zones underserved by legacy woven suppliers. Deploy direct-to-contractor digital qualification portals to bypass entrenched distribution layers.
For Investors and Strategic Acquirers: EU Green Deal sustainability criteria reshapes the acquisition landscape toward polymer-modified mat specialists with REACH-compliant formulation pipelines. Long-term viability hinges on specification database positioning and embedded sensor integration capabilities. Watch for hydration monitoring technology adoption rates in German and Dutch transportation agency pilots as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modification | Captive supply of REACH-compliant additives protects margin pools from ECHA substance evaluation exclusions. |
| Embedded Sensor Technology Partnership | Moisture monitoring integration with German transportation agency pilots enables outcome-based contracting models. |
| Direct-to-Contractor Digital Platform | Specification database positioning reduces friction in Queensland and New South Wales infrastructure bidding workflows. |
| Bio-Based Formulation Development | Preemptive R&D investment addresses EU Green Deal low-carbon material preferences in European civil engineering. |
| Qualified Technician Certification Program | Installation training partnerships alleviate scarcity delays in complex embankment reinforcement projects. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across infrastructure developers, civil engineering consultants, installation contractors, and polymer modification chemists. Secondary validation drew from EPA stormwater compliance filings, EU ECHA substance registration databases, Australian state infrastructure procurement records, and transportation agency specification manuals. Bottom-up project pipeline analysis triangulated with top-down infrastructure spending forecasts across the analysis window.
Calibration against historical cementitious mat deployment volumes and polymer-modified coating adoption curves anchored the analytical framework. Segmentation dimensions modeled include substrate architecture, coating chemistry, application severity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and specification-driven procurement shift velocities. Forecast inputs incorporated EPA enforcement intensity projections and EU REACH substance evaluation timelines.
Stress conditions across Portland cement price volatility bands, qualified technician availability constraints, and multi-standard harmonization delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure spending continuity and regulatory enforcement persistence. Cross-checking against state transportation department capital improvement plans is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
High Pressure Laminate (HPL) Market
Composite Materials
Global Carbon Fiber Composite Heating Elements Market
Composite Materials
FRP Reactor Market
Composite Materials
Europe Composite Process Material Kits Market
Composite Materials
China Marine Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Global Molded FRP Grating Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market
Composite Materials
Structural Core Materials Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
High Performance Composites Market
Composite Materials
Asia-Pacific Polyphenylene Sulfide (PPS) Composites Market
Composite Materials
Europe Wood-Plastic Composite (WPC) Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Global Composite Materials Market
Composite Materials
Wind Turbine Blade Repair Material Market