
 Global Molded FRP Grating Market | 2026-2036
Global Molded FRP Grating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molded FRP Grating Market Foresight
Steel-reinforced concrete is restructuring walkway and platform economics across process industries as facility engineers prioritize lifecycle cost over first-cost procurement. Strongwell Corporation leverages deep pultrusion expertise to anchor North American specification standards. Fibergrate Composite Structures sustains coastal and offshore dominance through salt-spray-resistant resin formulations. Bedford Reinforced Plastics specializes in custom-molded geometries for food-safe washdown environments.
Molded FRP grating consists of interwoven fiberglass rovings saturated with thermoset resin, cured under heat and pressure to create a one-piece panel with integral 30-38% glass content and typical 25-38mm thickness, engineered to support concentrated loads while eliminating corrosion in chemically aggressive settings. Standard molded grating and square mesh variants occupy the volume core across water treatment and chemical processing installations where UV-stabilized vinyl ester resins command margin premiums over general-purpose polyester. T-bar grating and safety grating configurations lead specification growth in offshore marine platforms and elevated infrastructure walkways where slip resistance and open-area drainage drive code compliance.
FDA food-contact regulations, EPA corrosion-prevention mandates for chemical containment, and EU REACH chemical restrictions collectively shape resin selection, product certification, and market access thresholds for cross-border suppliers. ISO structural performance standards and ASTM E-84 flame spread classifications further segment procurement tiers between commodity distributors and engineered-solutions providers. Stakeholders must monitor evolving national building code adoptions of FRP-specific load tables as municipalities update infrastructure resilience standards.
Market Dynamics
Corrosion-driven infrastructure replacement cycles are restructuring capital allocation across municipal water systems and chemical processing facilities, with lifecycle cost modeling now overriding first-cost procurement in specification-grade purchasing decisions.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for hydrofluorocarbons accelerate material substitution toward thermoset composites in cooling tower and HVAC infrastructure across German and Dutch industrial clusters.
- Water treatment modernization:EPA corrosion-prevention mandates for chemical containment systems drive grating replacement in aging US municipal facilities, particularly in coastal zones with salt-laden atmospheres.
- Vinyl ester resin chemistry:Advanced formulations with UV stabilization and fire-retardant additives expand addressable applications into offshore marine platforms and elevated petrochemical walkways.
Market Restraints
- Raw material volatility:Styrene monomer and fiberglass roving prices fluctuate with energy costs, compressing margin visibility for molded panel producers without backward integration into resin synthesis.
- Supply concentration:North American pultrusion capacity clusters in Virginia and Tennessee, creating geographic vulnerability to regional weather disruptions and freight cost spikes.
- Steel price competitiveness:Galvanized steel grating maintains first-cost advantage in non-corrosive interior applications, limiting composite penetration in budget-constrained municipal segments.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for chemical processing and water infrastructure create specification-grade demand in Gujarat and Maharashtra state projects.
- Modular platform systems:Pre-engineered FRP mezzanine and walkway kits reduce field installation labor, opening distributor channels to smaller commercial contractors.
- ISO 14122 machinery safety standards:Updated guardrail and platform specifications in EU machinery directives favor open-mesh grating with documented slip resistance certification.
Industry Challenges
- Resin formulation expertise gap:Shortage of polymer chemists with thermoset composite experience delays product development cycles and regulatory submission timelines.
- ASTM E-84 certification backlog:Third-party flame spread testing queues extend go-to-market timelines for new vinyl ester formulations by four to six months.
- Legacy steel specification inertia:Municipal engineering departments retain load-table familiarity with metal grating, requiring extended technical education cycles to secure composite approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molded FRP Grating Market |
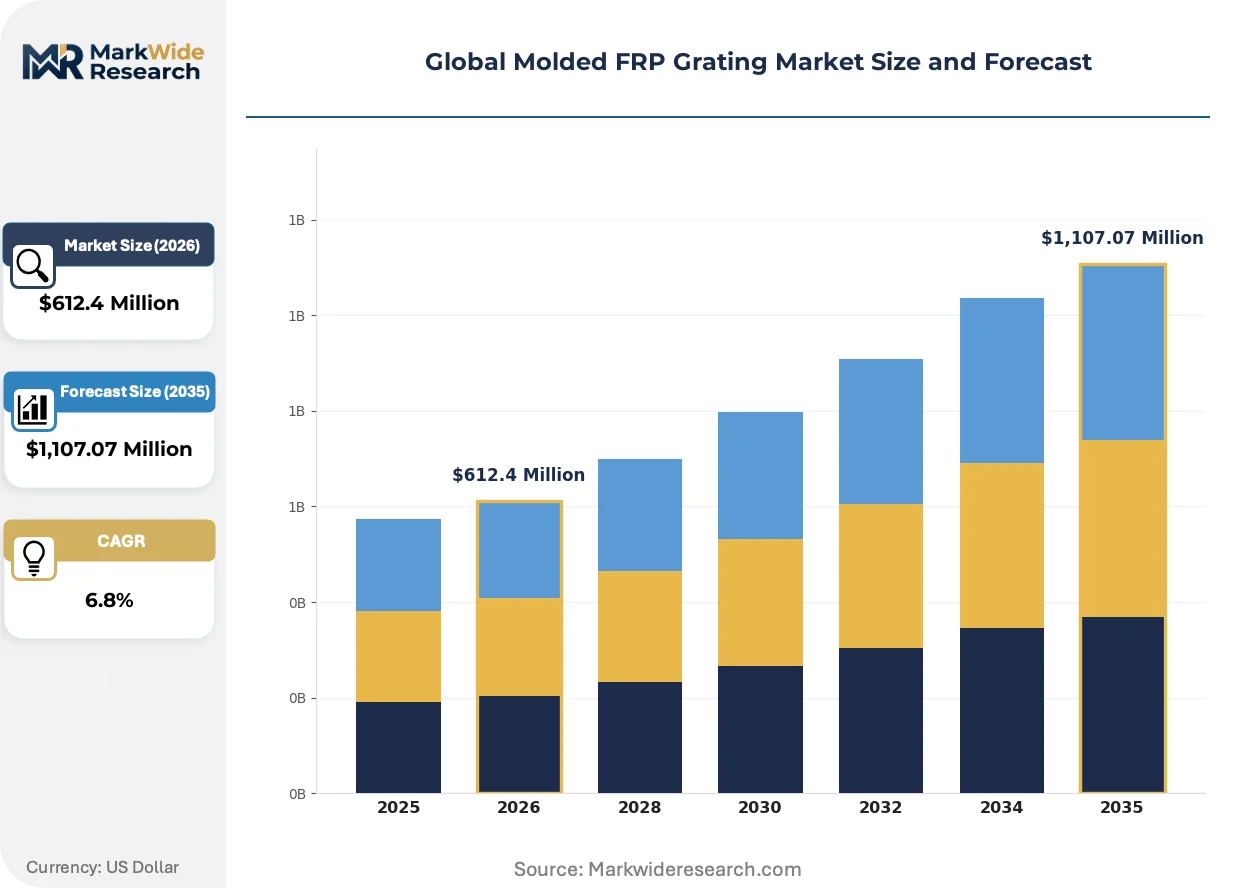
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Molded Grating, T-Bar Grating, Square Mesh Grating, Safety Grating, Pultruded Grating Application: Water Treatment, Chemical Processing, Food Production, Infrastructure, Marine Platforms End User: Construction Firms, Processing Plants, Marine Contractors, Food Manufacturers, Utilities Providers Installation Type: Flush Mount, Raised Floor, Stair Tread, Drain Covers, Walkways |
| Companies Covered | Strongwell Corporation, Fibergrate Composite Structures, Bedford Reinforced Plastics, Gebrüder MEISER GmbH, National Grating, AGC Matex, Liberty Pultrusions, McNICHOLS CO., Techno-Composites Domine GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molded FRP Grating Market Shifts & Advancements
Pultrusion and molding technologies are converging with digital design tools to compress development cycles, while regulatory pressure on embodied carbon intensifies material selection scrutiny across specification-grade procurement.
Photoinitiated resin curing is electrifying production economics for custom-molded geometries. The technology enables rapid mold cycling without thermal mass heating, cutting energy intensity by half in Bedford Reinforced Plastics' food-safe washdown product lines. Water treatment contractors in Germany and the Netherlands are specifying these panels for chlorine-contact chamber walkways where corrosion resistance must pair with rapid installation.
REACH chemical restrictions on styrene emissions are tightening manufacturing protocols across EU production facilities. ECHA registration requirements now mandate exposure monitoring and workplace ventilation upgrades that smaller molding operations struggle to fund. German industrial buyers are responding by consolidating procurement with Tier-1 suppliers possessing certified environmental management systems.
Lifecycle cost modeling is displacing first-cost bidding in municipal infrastructure RFPs. Engineering firms in coastal US states now embed 30-year maintenance projections into grating specifications, favoring vinyl ester composites over galvanized steel despite 40% upfront premiums. Florida and California water authorities have rewritten standard specifications to permit composite alternatives where salt corrosion accelerates steel degradation.
Global Molded FRP Grating Market Segmentation
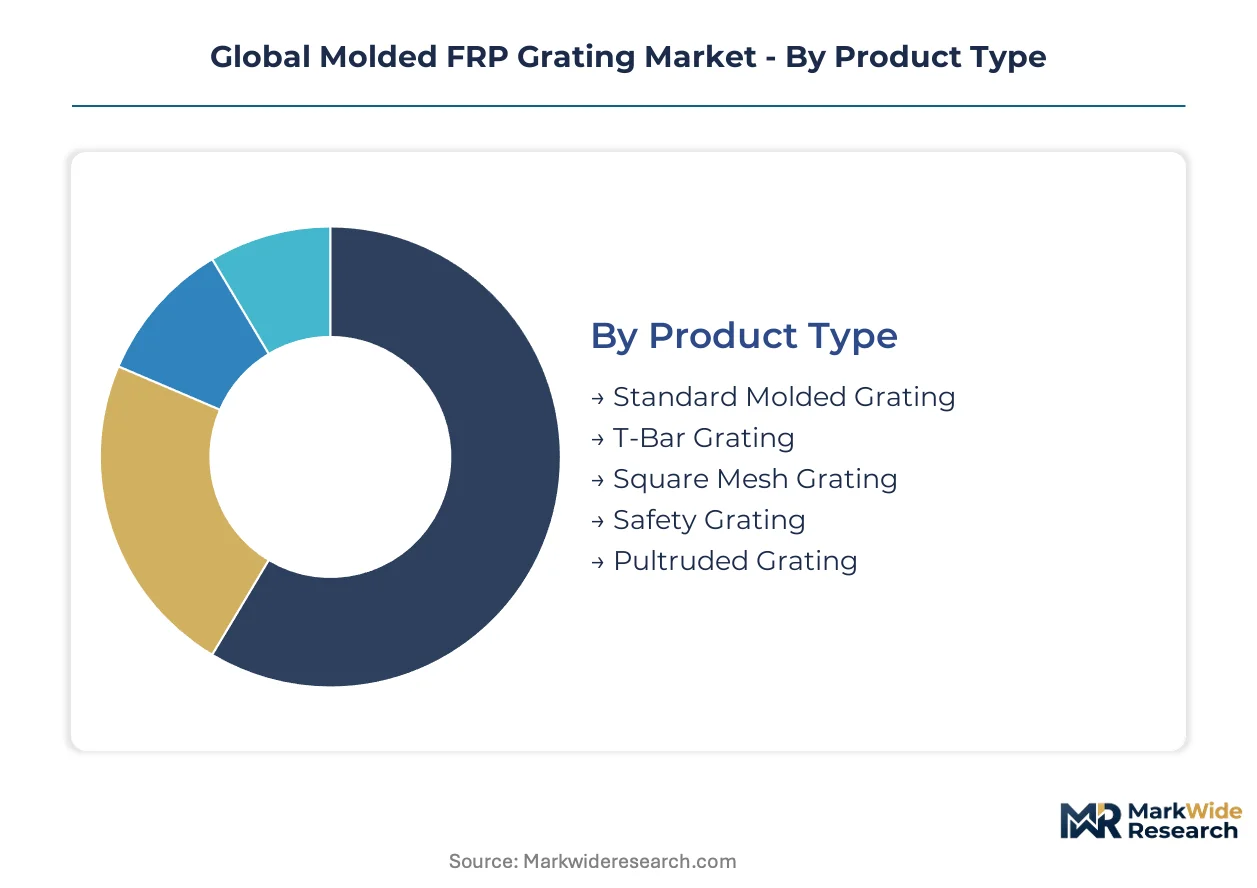
Molded FRP grating procurement decisions hinge on corrosion exposure severity, load-bearing requirements, and regulatory compliance tiers. Specification engineers weight lifecycle cost models against first-cost constraints differently across water treatment, chemical processing, and marine applications.
Product Type:
Load-bearing capacity and resin formulation flexibility drive buyer selection, with UV-stabilized vinyl ester commanding specification premiums in aggressive chemical environments.
- Standard Molded Grating:Interwoven fiberglass rovings saturated with thermoset resin cure under heat and pressure to create one-piece panels with 30-38% glass content. Municipal water treatment facilities in Germany and the Netherlands specify these for chlorine-contact chamber walkways where corrosion resistance must pair with rapid installation.
- T-Bar Grating:Integral load-bearing bars formed during molding provide concentrated load capacity with reduced panel weight. Offshore marine platforms in the North Sea and Gulf of Mexico specify T-bar configurations where slip resistance and open-area drainage satisfy code compliance for elevated walkways.
- Square Mesh Grating:Uniform 25-38mm mesh openings optimize drainage and ventilation in chemical containment areas.
- Safety Grating:Serrated or gritted surfaces enhance slip resistance in wet process environments.
- Pultruded Grating:Continuous fiber alignment delivers superior unidirectional strength for heavy equipment platforms.
Volume sits with Standard Molded Grating; growth tilts toward T-Bar Grating.
Application:
Corrosion severity and regulatory exposure duration reshape capital allocation priorities across facility types, with coastal infrastructure accelerating replacement cycles.
- Water Treatment:EPA corrosion-prevention mandates for chemical containment systems drive grating replacement in aging US municipal facilities, particularly in Florida and California where salt-laden atmospheres accelerate steel degradation.
- Chemical Processing:Process engineers specify vinyl ester formulations with fire-retardant additives for elevated petrochemical walkways. EU REACH restrictions on styrene emissions tighten manufacturing protocols, consolidating procurement with Tier-1 suppliers possessing certified environmental management systems.
- Food Production:FDA food-contact regulations mandate resin selection for washdown environments.
- Infrastructure:Municipal resilience standards update load tables to permit composite alternatives.
- Marine Platforms:Salt-spray-resistant formulations dominate offshore specification.
Water Treatment captures the largest installed base; Chemical Processing shows the steepest expansion trajectory.
End User:
Procurement sophistication varies by buyer technical capability, with engineering departments retaining steel load-table familiarity requiring extended education cycles.
- Processing Plants:Facility engineers prioritize lifecycle cost over first-cost procurement across petrochemical and specialty chemical operations. German industrial clusters leverage specification-grade procurement density to anchor vinyl ester volume.
- Marine Contractors:Salt-spray-resistant resin formulations sustain dominance in coastal and offshore project specifications.
- Construction Firms:Pre-engineered modular platform kits reduce field installation labor.
- Food Manufacturers:FDA compliance drives resin certification requirements.
- Utilities Providers:Municipal budget constraints limit composite penetration in non-corrosive interior applications.
Processing Plants anchor current volume; Marine Contractors are gaining share fastest.
Installation Type:
Field labor efficiency and retrofit compatibility determine specification, with modular systems opening distributor channels to smaller commercial contractors.
- Walkways:Elevated infrastructure applications span water treatment plants, chemical facilities, and offshore platforms where open-mesh drainage and slip resistance certification satisfy ISO 14122 machinery safety standards.
- Raised Floor:Chemical containment and equipment access platforms require concentrated load capacity with corrosion immunity.
- Flush Mount:Seamless surface integration suits interior commercial spaces.
- Stair Tread:Nosing and grit options enhance safety compliance.
- Drain Covers:Custom-molded geometries accommodate trench and sump configurations.
Walkways dominate specification frequency; Raised Floor applications climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment infrastructure replacement concentrates demand in Germany and the United States, while industrial cluster density in Gujarat and coastal corrosion severity in Florida reshape specification patterns across three continents.
Germany
Chlorine-contact chamber walkways and chemical processing platforms drive specification-grade procurement. The EU F-Gas Regulation accelerates material substitution in cooling tower infrastructure across North Rhine-Westphalia. Industrial buyers in the Ruhr Valley consolidate procurement with Tier-1 suppliers possessing certified environmental management systems.
United States
EPA corrosion-prevention mandates for chemical containment systems trigger grating replacement in aging municipal facilities. Florida and California water authorities rewrite standard specifications to permit composite alternatives where salt corrosion accelerates steel degradation. Gulf Coast petrochemical clusters specify vinyl ester formulations for elevated walkways.
India
PLI scheme incentives for chemical processing and water infrastructure create specification-grade demand in Gujarat and Maharashtra state projects. The country's national chemical regulator tightens workplace exposure protocols for styrene emissions. Dahej and Mundra industrial corridors anchor procurement consolidation among process industry engineers.
Netherlands
HVAC infrastructure modernization and cooling tower replacement cycles sustain vinyl ester volume. REACH chemical restrictions on styrene emissions tighten manufacturing protocols for Dutch fabricators. Rotterdam port industrial zones specify salt-spray-resistant formulations for offshore supply chain walkways.
Japan
Offshore marine platform specifications and machinery safety compliance sustain T-bar grating demand. METI industrial standards update load-table references for composite alternatives in petrochemical facilities. Chubu region process industry clusters prioritize lifecycle cost modeling over first-cost procurement.
Global Molded FRP Grating Market Competitive Landscape
Capacity expansion dominates the current landscape as producers respond to infrastructure replacement cycles across municipal water systems. The vendor base organizes around three strategic tiers: integrated resin-to-panel manufacturers, regional fabrication specialists, and specification-grade engineering houses. Backward integration into resin synthesis separates margin-stable producers from distributors exposed to raw material volatility. Geographic expansion into Indian industrial corridors and technology licensing for photoinitiated curing represent the two dominant competitive vectors.
Among North American fabricators, Strongwell Corporation and Fibergrate Composite Structures exemplify the specification-grade tier, while Bedford Reinforced Plastics occupies a position within the custom-molded specialization segment. Gebrüder MEISER GmbH represents the European integrated manufacturer archetype with captive distribution across German industrial clusters. These three anchors illustrate how competitive positioning stratifies between scale-driven standardization and application-specific engineering capability.
| Leading Market Players |
|---|
| Strongwell Corporation |
| Fibergrate Composite Structures |
| Bedford Reinforced Plastics |
| Gebrüder MEISER GmbH |
| National Grating |
| AGC Matex |
| Liberty Pultrusions |
| McNICHOLS CO. |
| Techno-Composites Domine GmbH |
| Others |
Supply & Pricing Matrix
Styrene monomer futures and fiberglass roving spot indices cascade through the molded FRP grating supply chain, compressing margin visibility for non-integrated producers while amplifying pricing power for resin-synthesis owners. The spread between general-purpose polyester and UV-stabilized vinyl ester formulations widens as energy costs feed into thermoset raw material premiums.
Pricing Analysis
Volume concentrates in standard molded grating while margins accrue to specification-grade vinyl ester tiers certified for offshore marine and chemical containment duty. Price differentiation rests on ASTM E-84 flame spread certification and ISO structural performance documentation, with uncertified commodity panels facing downward pressure from galvanized steel alternatives in budget-constrained municipal segments. Processing plants with lifecycle cost mandates exhibit lowest price sensitivity; small commercial contractors purchasing through distributor channels show highest elasticity.
Supply Chain Analysis
Polymer chemist shortages in Virginia and Tennessee pultrusion clusters constrain mold cycling rates and delay regulatory submission timelines for new formulations. Manufacturing concentrates in the United States, Germany, and China, with the supply chain drawing from styrene monomer, fiberglass roving, and photoinitiator additive inputs. Single-source vulnerability runs through concentrated North American resin synthesis capacity. Distribution runs through specification-grade engineering houses and regional fabrication specialists serving municipal water authorities and petrochemical facility engineers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded FRP grating market reads as a cost-of-compliance story where EU REACH chemical restrictions on styrene emissions erect barrier-to-entry moats for Tier-1 suppliers possessing certified environmental management systems.
For Market Incumbents: Anchor specification-grade procurement relationships by securing backward integration into vinyl ester resin synthesis, insulating margin structures from raw material volatility. Invest in photoinitiated curing technology licensing to compress mold cycling economics for food-safe washdown product lines. Defend against emerging modular platform kit competitors by controlling distributor channel certification training for ISO 14122 machinery safety compliance. For New Entrants and Emerging Players: Enter via Gujarat and Maharashtra industrial corridors under India's PLI scheme incentives for chemical processing infrastructure, where specification-grade demand outruns established supplier presence. Target pre-engineered FRP mezzanine kits for smaller commercial contractors underserved by incumbent engineering-house channels. Lead with rapid-installation value propositions backed by documented lifecycle cost models displacing first-cost steel specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated resin-to-panel manufacturers in German industrial clusters where EU F-Gas Regulation compliance investments strain smaller molding operations. Long-term viability centers on captive vinyl ester synthesis capacity and certified environmental management systems rather than pure-play fabrication assets. Watch for Florida and California water authority specification rewrites permitting composite alternatives as inflection signals accelerating municipal replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive vinyl ester supply insulates margin structures from styrene monomer volatility. |
| Photoinitiated Curing Technology Licensing | Rapid mold cycling without thermal mass heating halves energy intensity for food-safe lines. |
| ISO 14122 Certification Investment | Documented slip resistance certification satisfies updated EU machinery safety directives. |
| Modular Platform Kit Development | Pre-engineered kits reduce field labor and open distributor channels to commercial contractors. |
| Gujarat Industrial Corridor Expansion | PLI scheme incentives anchor specification-grade demand in Dahej and Mundra chemical clusters. |
Research Methodology
Trade association filings, customs import records, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with plant engineers, municipal procurement officers, resin formulation chemists, and distribution channel managers. Bottom-up volume estimates triangulated against top-down spending analyses across water treatment, chemical processing, and marine platform end uses.
Historical trendline analysis tracked replacement cycle timing and specification adoption rates across municipal infrastructure budgets. The analytical framework modeled product type, resin formulation tier, application severity, and regional regulatory cluster dimensions across the projection horizon. CAGRs derived from installed base turnover rates and lifecycle cost penetration curves, with inputs from EPA corrosion-prevention mandate implementation timelines and EU F-Gas Regulation phase-down schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained steel price competitiveness or accelerated REACH chemical restriction enforcement. Material deviation in Florida and California water authority specification rewrites, or in Indian PLI scheme disbursement pacing, warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Case Material Market
Composite Materials
FRP Tanks Market
Composite Materials
Aluminum Composite Materials Market
Composite Materials
Lithium Battery Copper Aluminum Composite Pole Market
Composite Materials
Geosynthetic Cementitious Composite Mats Market
Composite Materials
Polycarbonate Composites Market
Composite Materials
Pulp Moulding Tooling Market
Composite Materials
Carbon Composites Market
Composite Materials
Laminar Composites Market
Composite Materials
Plastic Composites Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Glass Fiber Reinforced Plastic (GFRP) Market
Composite Materials
Asia Pacific Bio Composites Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Structural Composites Market
Composite Materials
North America Molded FRP Grating Market