
 Carbon Dioxide Market | 2026-2036
Carbon Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Dioxide Market Intelligence
The adoption of large-scale project finance for carbon capture facilities is rewriting the competitive landscape for CO2 supply. This capital-intensive model favors large, established industrial gas suppliers. Linde plc leverages its extensive infrastructure to secure long-term offtake agreements from these new sources. Air Products and Chemicals, Inc. specializes in building and operating large-scale gasification and capture projects, controlling significant volume.
Carbon dioxide is a colorless, non-flammable gas that exists as a trace component in Earth's atmosphere. It is typically captured as a byproduct from industrial processes like ammonia production or sourced from natural wells and compressed into liquid or solid forms. Industrial grade CO2 constitutes the largest volume segment, serving applications from chemical manufacturing to water treatment. Higher-purity food grade and beverage grade products command premium pricing, while demand for enhanced oil recovery represents a significant application-specific market.
Purity and safety standards set by bodies like the U.S. Food and Drug Administration (FDA) and the European Chemicals Agency (ECHA) govern market access for specific grades. Additionally, ISO standards dictate the transportation and handling protocols for liquid and compressed gas forms. Future profitability will depend on a supplier's ability to manage a diversified portfolio of both traditional byproduct sources and new direct air or industrial capture streams.
Market Dynamics
The central structural force shaping the carbon dioxide market is the strategic pivot from viewing CO2 as an industrial byproduct to a valued commodity within a circular carbon economy, driven by global decarbonization policies and maturing capture technologies.
Growth Catalysts
- Policy Incentives:The United States' Inflation Reduction Act (IRA), through its 45Q tax credits, directly subsidizes carbon capture and sequestration projects, spurring significant investment in new CO2 supply infrastructure from industrial and power generation sources.
- Food and Beverage Demand:Consistent consumption in the food and beverage industry for applications like beverage carbonation and modified atmosphere packaging for food preservation provides a stable, high-volume demand base for food-grade CO2.
- CCUS Technology Maturation:Advances in carbon capture, utilization, and storage (CCUS) technologies are making it economically and technically feasible to capture CO2 from hard-to-abate sectors like cement and steel manufacturing, opening up vast new supply streams.
Market Restraints
- High Capital Costs:The immense capital investment required to engineer, procure, and construct large-scale carbon capture facilities and dedicated CO2 pipelines presents a significant barrier to entry, favoring large, well-capitalized corporations.
- Byproduct Supply Volatility:A substantial portion of the CO2 supply remains tied to the operational rates of ammonia and ethanol plants, making the market vulnerable to supply shocks if these host facilities reduce production or shut down.
- Substitution in Water Treatment:In municipal and industrial water treatment, alternative acids and pH control methods can substitute for carbon dioxide, limiting its market share in applications where cost is the primary selection criterion.
Strategic Opportunities
- Sustainable Aviation Fuel Feedstock:The use of captured CO2 as a primary feedstock for producing e-fuels and sustainable aviation fuels (SAFs) represents a major future demand vector, linking the CO2 market directly to aviation decarbonization goals.
- Expansion in Southeast Asia:Rapid industrialization and growth in the food processing sector across Southeast Asian nations present an underpenetrated market for both industrial and food-grade carbon dioxide applications.
- EU Regulatory Tailwinds:The European Union's Green Deal and associated policies like the Carbon Border Adjustment Mechanism (CBAM) create strong incentives for heavy industries to capture their CO2 emissions, potentially creating new regional supply hubs.
Industry Challenges
- Transportation and Logistics:Developing an efficient and cost-effective logistics network for transporting large volumes of captured CO2 from diverse sources to utilization or sequestration sites via pipeline, rail, or cryogenic tanker remains a complex operational hurdle.
- Purity and Certification:Ensuring consistent CO2 purity from novel sources like direct air capture to meet stringent food-grade standards set by bodies like the FDA or beverage-grade specifications requires sophisticated and costly purification and verification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Dioxide Market |
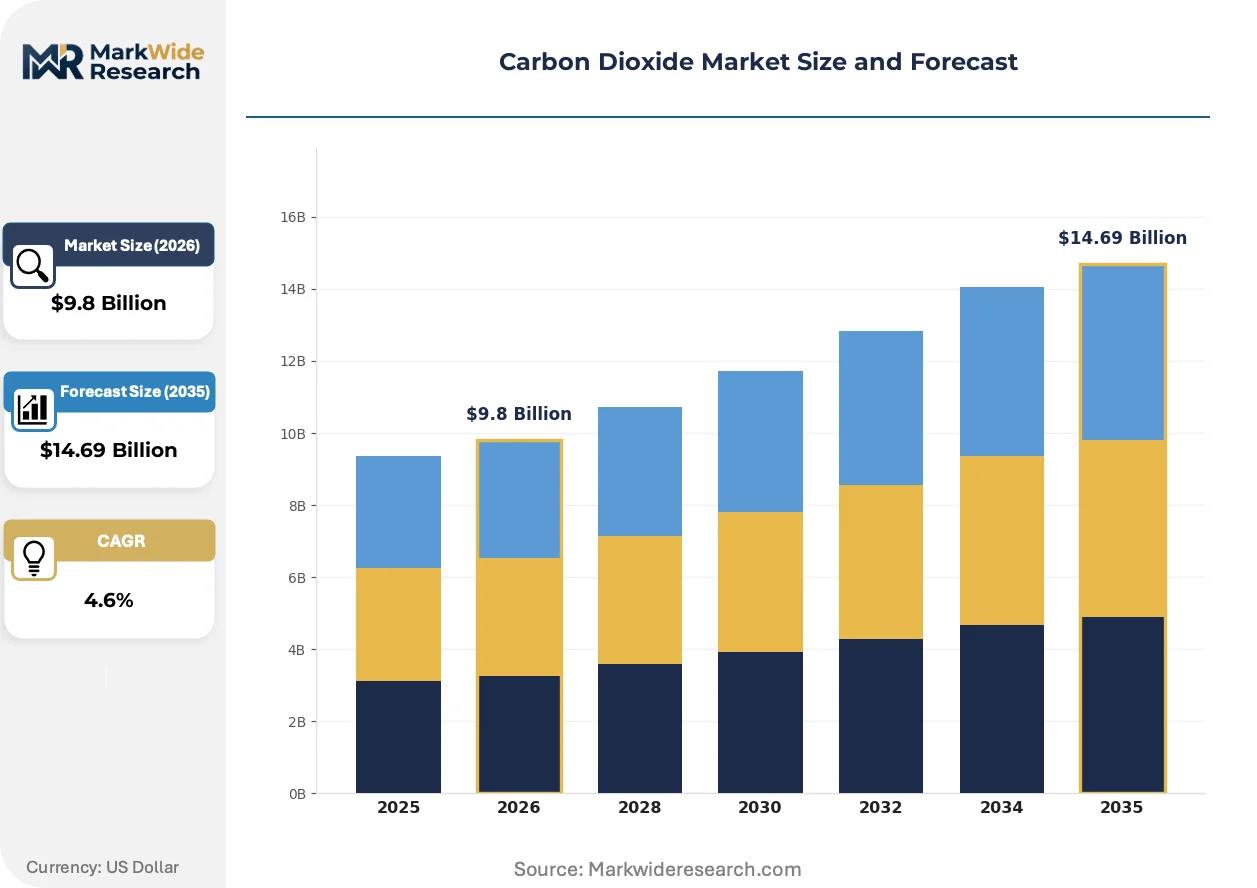
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Industrial Grade, Medical Grade, Beverage Grade, Specialty Grade Application: Enhanced Oil Recovery, Water Treatment, Fire Extinguishers, Refrigerants, Chemical Manufacturing Supply Form: Compressed Gas, Liquid, Dry Ice, Solid Pellet End User Industry: Oil & Gas Sector, Food & Beverage Plants, Pharmaceutical Facilities, Agriculture Producers, Metal Fabricators |
| Companies Covered | Linde plc, Air Products and Chemicals, Inc., Air Liquide, The Messer Group GmbH, Matheson Tri-Gas, Inc., SOL Spa, Universal Industrial Gases, Inc., Sicgil India Limited, India Glycols Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Dioxide Market Strategic Shifts & Innovations
A fundamental re-evaluation of carbon dioxide's role is underway, shifting its perception from a waste product to a critical element in decarbonization strategies and circular economic models. This transition is defined by innovations in sourcing, new regulatory frameworks, and evolving customer expectations for sustainability.
Direct Air Capture (DAC) technologies function by chemically or physically extracting carbon dioxide directly from the ambient atmosphere. Early adoption is being driven by corporations in the technology and finance sectors seeking high-integrity carbon removal credits. As a result, the CO2 supply chain is migrating from a historical dependency on geographically fixed industrial byproduct sources toward a more distributed and potentially scalable atmospheric sourcing model.
The European Union's F-Gas Regulation mandates a progressive phase-down of synthetic refrigerants like hydrofluorocarbons (HFCs). This policy creates a direct industrial consequence, accelerating demand for CO2 (R-744) as a natural and climate-friendly refrigerant. The commercial refrigeration and retail food sectors across Europe are most affected, now prioritizing investment in CO2-based cooling systems to achieve regulatory compliance.
Buyers in the food, beverage, and consumer goods sectors are increasingly demanding transparency and certification for the origin of their CO2 supply. This behavioral shift disrupts traditional commodity purchasing, favoring source-verified contracts that specify renewably-sourced or captured CO2. This trend is most prominent in North America and Western Europe, where consumer and investor pressure for complete supply chain decarbonization is most intense.
Carbon Dioxide Market Segmentation
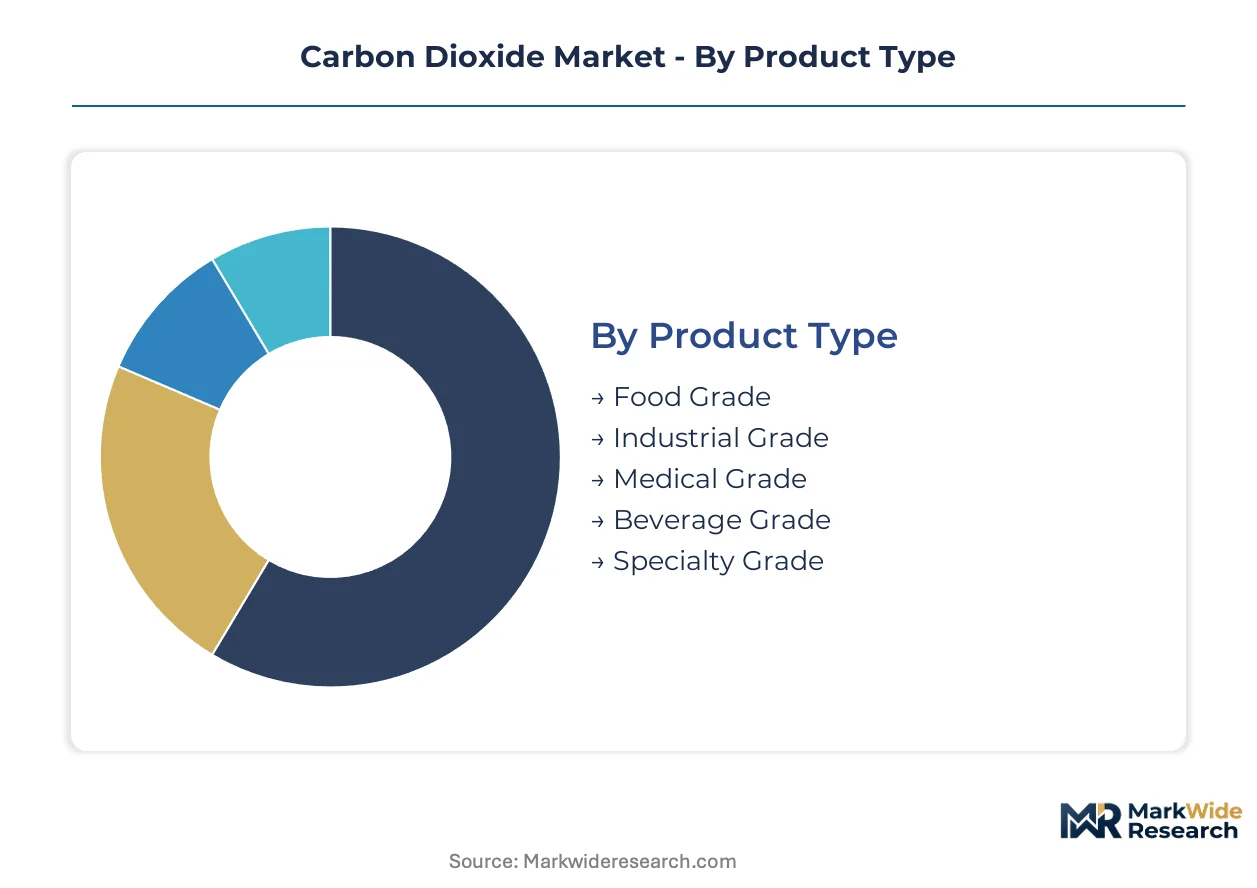
Segmentation analysis provides a granular understanding of the carbon dioxide market, revealing how diverse product specifications, application requirements, supply forms, and end-user industries shape its competitive dynamics and value chain complexities. This detailed breakdown highlights areas of concentrated demand and emerging opportunities.
Product Type:
The product type segmentation reveals a spectrum of market maturity, from established industrial uses to specialized high-purity applications.
- Industrial Grade:Industrial grade CO2 typically possesses a purity level between 99% and 99.9%, suitable for large-scale processes. Demand concentrates in chemical manufacturing and metal fabrication, driven by its role as a feedstock and inerting agent.
- Food Grade:Food grade CO2 adheres to stringent purity standards, often exceeding 99.99%, ensuring safety for human consumption. Beverage carbonation in North America and food preservation in Europe drive substantial consumption, emphasizing quality and safety.
- Beverage Grade:Beverage grade CO2 meets specific purity and organoleptic requirements for carbonated drinks.
- Medical Grade:Medical grade CO2 adheres to pharmaceutical standards, used in surgical procedures and respiratory therapies.
- Specialty Grade:Specialty grade CO2 includes ultra-high purity or isotopic variants for research and advanced manufacturing.
Industrial Grade retains volume leadership; Food Grade holds the steepest expansion curve.
Application:
Application analysis highlights the diverse functional roles of carbon dioxide across various industrial processes.
- Enhanced Oil Recovery:EOR utilizes CO2 injection to reduce crude oil viscosity and increase reservoir pressure, improving extraction efficiency. Demand concentrates in mature oilfields within the United States and the Middle East, driven by the need to maximize existing asset output.
- Refrigerants:CO2 (R-744) functions as a natural refrigerant with low global warming potential, suitable for commercial and industrial cooling systems. European commercial refrigeration and retail food sectors increasingly adopt CO2-based systems due to F-Gas Regulation compliance.
- Water Treatment:Water treatment applications use CO2 for pH control and alkalinity adjustment in municipal and industrial processes.
- Chemical Manufacturing:Chemical manufacturing employs CO2 as a feedstock for producing urea, methanol, and other organic compounds.
- Fire Extinguishers:Fire extinguishers utilize CO2 as a non-conductive, non-damaging extinguishing agent for electrical and flammable liquid fires.
The largest application segment remains Enhanced Oil Recovery, while Refrigerants demonstrate significant growth potential.
Supply Form:
The supply form segmentation reflects the logistical and storage requirements dictated by end-use applications.
- Liquid:Liquid CO2 is stored under pressure at moderate temperatures, offering a dense and efficient transport solution. Food and beverage carbonation and chemical manufacturing in industrial hubs drive demand for bulk liquid deliveries.
- Compressed Gas:Compressed gas CO2 is stored in cylinders at high pressure, suitable for smaller volume applications and specialized uses. Demand concentrates in welding, laboratory applications, and portable fire suppression systems across diverse industrial sectors.
- Dry Ice:Dry ice, solid CO2, provides cryogenic cooling for perishable goods transport and specialized cleaning.
- Solid Pellet:Solid pellets of CO2 are used for blast cleaning, cooling, and in some food preservation applications.
Liquid dominates the market in terms of volume, with Dry Ice showing considerable expansion.
End User Industry:
End user industry analysis illustrates the diverse economic sectors reliant on carbon dioxide for their operations.
- Food & Beverage Plants:These facilities use CO2 for beverage carbonation, modified atmosphere packaging, and chilling processes. Consistent consumer demand for carbonated drinks and preserved foods in North America and Europe underpins stable consumption.
- Oil & Gas Sector:The oil and gas sector primarily uses CO2 for enhanced oil recovery and well stimulation. Demand stems from mature oilfields in the United States and the Middle East seeking to extend production lifespans.
- Pharmaceutical Facilities:Pharmaceutical facilities employ CO2 in controlled atmosphere environments, drug synthesis, and sterile packaging.
- Agriculture Producers:Agriculture producers use CO2 for greenhouse enrichment to boost plant growth and crop yields.
- Metal Fabricators:Metal fabricators utilize CO2 as a shielding gas in welding processes and for inerting applications.
The Oil & Gas Sector segment holds the largest share, while Agriculture Producers are poised for accelerated growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry exists between developed markets like the United States and emerging industrial hubs across Southeast Asia. Mature oilfields in the United States and the Middle East drive demand for enhanced oil recovery, while rapid industrialization in Asian nations creates new opportunities for industrial and food-grade carbon dioxide. Policy incentives and technological advancements further shape regional market dynamics.
United States
Enhanced oil recovery (EOR) and beverage carbonation remain significant demand drivers in the United States. The Inflation Reduction Act (IRA) provides substantial 45Q tax credits, spurring investment in carbon capture and sequestration projects. Industrial clusters in Texas and Louisiana are seeing new CO2 pipeline infrastructure development to support EOR and emerging CCUS hubs.
Germany
Industrial manufacturing and the food and beverage sector underpin demand for carbon dioxide in Germany. The European Union's F-Gas Regulation accelerates the adoption of CO2 (R-744) as a natural refrigerant in commercial applications. The Rhine-Ruhr region, with its dense industrial base, is a focal point for both CO2 supply and utilization in chemical processes.
China
Chemical manufacturing and industrial processes drive high-volume carbon dioxide consumption across China. The government's dual carbon goals provide long-term incentives for industries to explore carbon capture and utilization technologies. Major industrial zones in the Yangtze River Delta actively seek efficient CO2 supply for their expanding manufacturing operations.
India
Rapid expansion in the food and beverage industry, alongside chemical production, fuels carbon dioxide demand in India. The PLI scheme for food processing encourages investment in facilities requiring CO2 for preservation and carbonation. Industrial corridors in Maharashtra and Gujarat are experiencing increased activity for both industrial and food-grade gas distribution.
United Arab Emirates
The oil and gas sector, particularly enhanced oil recovery, represents the primary demand for carbon dioxide in the United Arab Emirates. Significant investments in CCUS projects align with national decarbonization strategies. Abu Dhabi's industrial zones are developing large-scale carbon capture facilities to supply CO2 for EOR and other industrial applications.
Carbon Dioxide Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the carbon dioxide supply chain. The market structure is moderately consolidated among large industrial gas suppliers, who leverage extensive infrastructure and project finance capabilities. Strategic archetypes include integrated gas solution providers and specialized CCUS project developers. Long-term offtake agreements and capacity expansion are dominant competitive moves.
Within the integrated gas solutions provider archetype, Linde plc, Air Products and Chemicals, Inc., and Air Liquide exemplify the industry's focus on extensive infrastructure and diversified service portfolios. These global industrial gas companies occupy a position of scale, often securing long-term contracts for both traditional byproduct sources and new capture streams. Their operational reach allows them to manage complex logistics networks for various grades of carbon dioxide.
| Leading Market Players |
|---|
| Linde plc |
| Air Products and Chemicals, Inc. |
| Air Liquide |
| The Messer Group GmbH |
| Matheson Tri-Gas, Inc. |
| SOL Spa |
| Universal Industrial Gases, Inc. |
| Sicgil India Limited |
| India Glycols Limited |
| Others |
Cost & Logistics Intelligence
The complex network of CO2 pipelines and cryogenic tanker routes across North America dictates regional cost structures, influencing both supply concentration and downstream price differentiation for industrial and food-grade products. Transportation costs represent a significant component of the final delivered price, particularly for remote end-users.
Pricing Analysis
Industrial OEM buyers anchor long-term contract-based pricing for large volume CO2, often with indexed adjustments for energy costs. Price differentiation stems from purity level, with medical grade commanding the highest premium, and geographic delivery costs impacting final prices. Pricing softness reflects the increasing availability of byproduct CO2 from new capture facilities. The food and beverage sector exhibits moderate price sensitivity, while EOR applications are least sensitive due to their high value add.
Supply Chain Analysis
Upstream CO2 feedstock primarily originates as a byproduct from ammonia and ethanol production plants in the United States and China. Natural wells also contribute significantly in regions like the Middle East. The market relies on consistent operations of these host facilities, creating single-source vulnerability if production rates decline. Distribution largely runs through established industrial gas companies managing extensive pipeline networks and bulk liquid deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon dioxide market offers significant service-attach opportunities beyond commodity supply. Comprehensive engineering, procurement, and construction (EPC) services for carbon capture facilities represent a recurring-revenue layer expanding faster than CO2 sales volume.
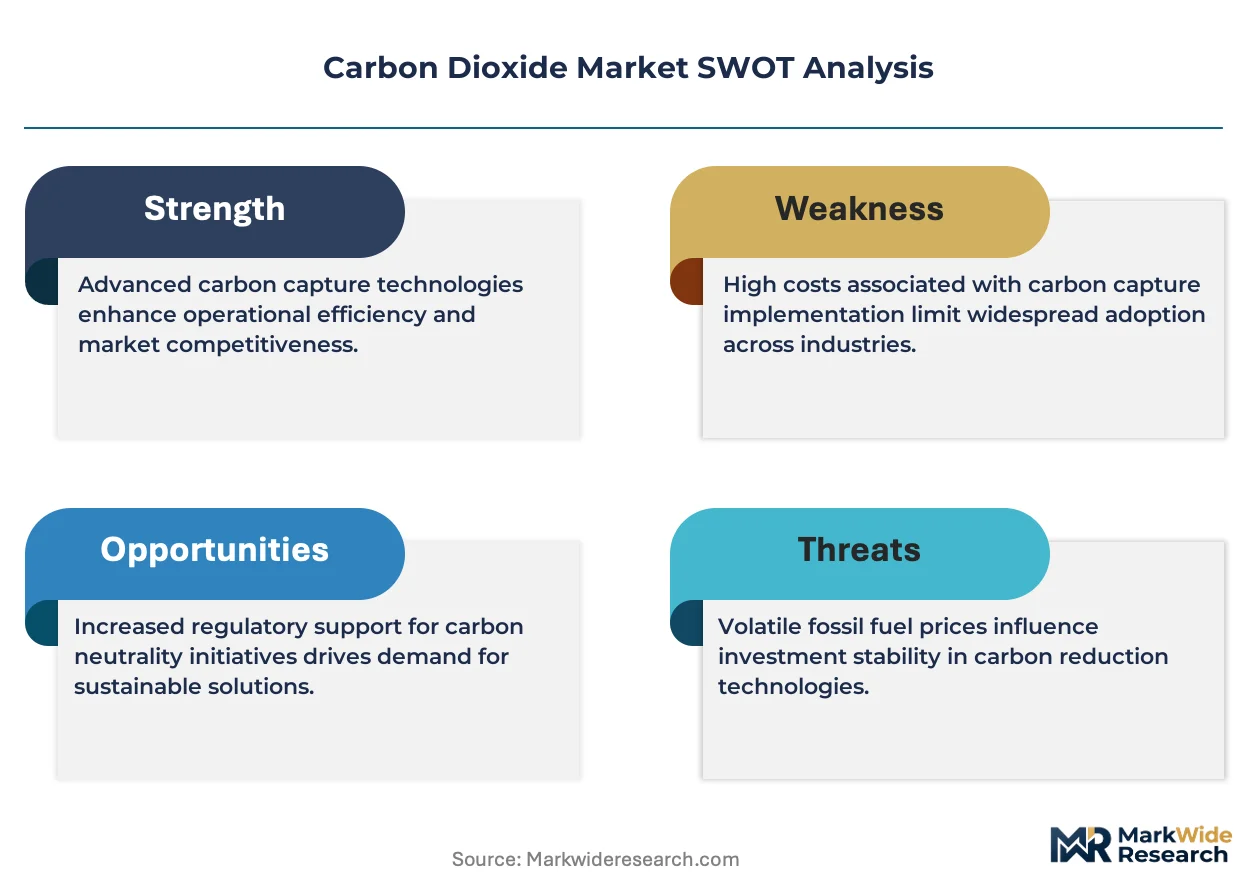
For Market Incumbents: Build infrastructure moats through strategic pipeline development and long-term offtake agreements. Consolidate regional supply points to mitigate byproduct supply volatility, a significant threat to consistent volume. Invest in advanced purification technologies to meet stringent food-grade standards, leveraging existing channel control for distribution.
For New Entrants and Emerging Players: Underpenetrated industrial clusters in Southeast Asia represent a prime entry point for specialized CO2 suppliers. Target small to mid-sized food processing plants requiring consistent food-grade CO2, a penetrable segment. A go-to-market angle could involve offering integrated capture-and-supply solutions for localized industrial emitters.
For Investors and Strategic Acquirers: Vertically integrated CCUS project developers with proprietary capture technologies offer long-term viability for patient capital. These firms can benefit from sustained policy incentives like the US 45Q tax credits over the coming decade. Watch for successful commercial-scale deployment of direct air capture (DAC) facilities as an inflection indicator for broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures long-term supply for EOR and food & beverage plants in key industrial zones. |
| Long-term Supply Agreement | Stabilizes revenue streams and mitigates byproduct supply volatility for major consumers. |
| Green Manufacturing Transition | Positions companies to meet EU Green Deal and CBAM requirements for captured CO2. |
| Joint Venture | Combines capital and expertise for large-scale carbon capture and sequestration projects. |
| Acquisition of Specialist Firm | Integrates advanced purification or DAC technologies into existing industrial gas portfolios. |
Research Approach
Cross-validation between primary interviews and secondary market reports anchors the qualitative findings of this study. Interviews with plant managers, procurement leads at food & beverage companies, CCUS technology developers, and logistics specialists provided granular insights. Secondary validation drew from industry association reports, government regulatory filings, and trade statistics. A combination of bottom-up data aggregation and top-down market sizing ensured robust analysis.
The calibration approach integrates historical data trends with projected technological advancements over the projection horizon. Segmentation dimensions modeled include product type, application, supply form, end-user industry, and regional policy environment. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included projected industrial output in emerging economies and anticipated carbon capture capacity additions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large industrial gas suppliers or new CCUS pure-plays would shift outcomes. Assumptions regarding policy stability and technology maturation underpin these projections. Cross-checking against IEA and IPCC reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Footprint Management Market