
 Carbon Credit Market | 2026-2036
Carbon Credit Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Credit Market Analytics
Aviation sector participation is broadening as airlines face mounting pressure to neutralize Scope 3 emissions through verified offset purchases. Intercontinental Exchange leverages its commodity exchange infrastructure to anchor liquidity in compliance credit futures. Tesla extends its carbon credit trading expertise from regulatory pools into voluntary markets. Xpansiv competes through its CBL spot exchange, which specializes in standardized, digitally traceable environmental commodities.
Carbon credits represent transferable certificates that certify the removal or avoidance of one metric ton of carbon dioxide equivalent, typically verified through third-party standards such as Verra's Verified Carbon Standard or Gold Standard methodologies. Their primary commercial purpose is to enable entities to meet regulatory caps or voluntary climate commitments while channeling capital into emission reduction projects. Voluntary credits now attract premium pricing as corporations pursue science-based targets, while compliance instruments remain tethered to cap-and-trade systems with stricter delivery obligations. Blockchain-based registries within the technology segment are gaining traction by reducing double-counting risks and accelerating settlement cycles.
The European Commission enforces the EU Emissions Trading System and Carbon Border Adjustment Mechanism, which collectively compel importers to surrender equivalent credits or face border levies. California's Air Resources Board operates the Western Climate Initiative cap-and-trade program, creating sustained demand for compliance-grade offsets from domestic and linked jurisdictions. Verra and Gold Standard function as de facto gatekeepers, with their methodologies determining which projects qualify for premium credit issuance. Stakeholders must monitor evolving integrity standards, as the Integrity Council for Voluntary Carbon Markets prepares to apply its Core Carbon Principles across major registries.
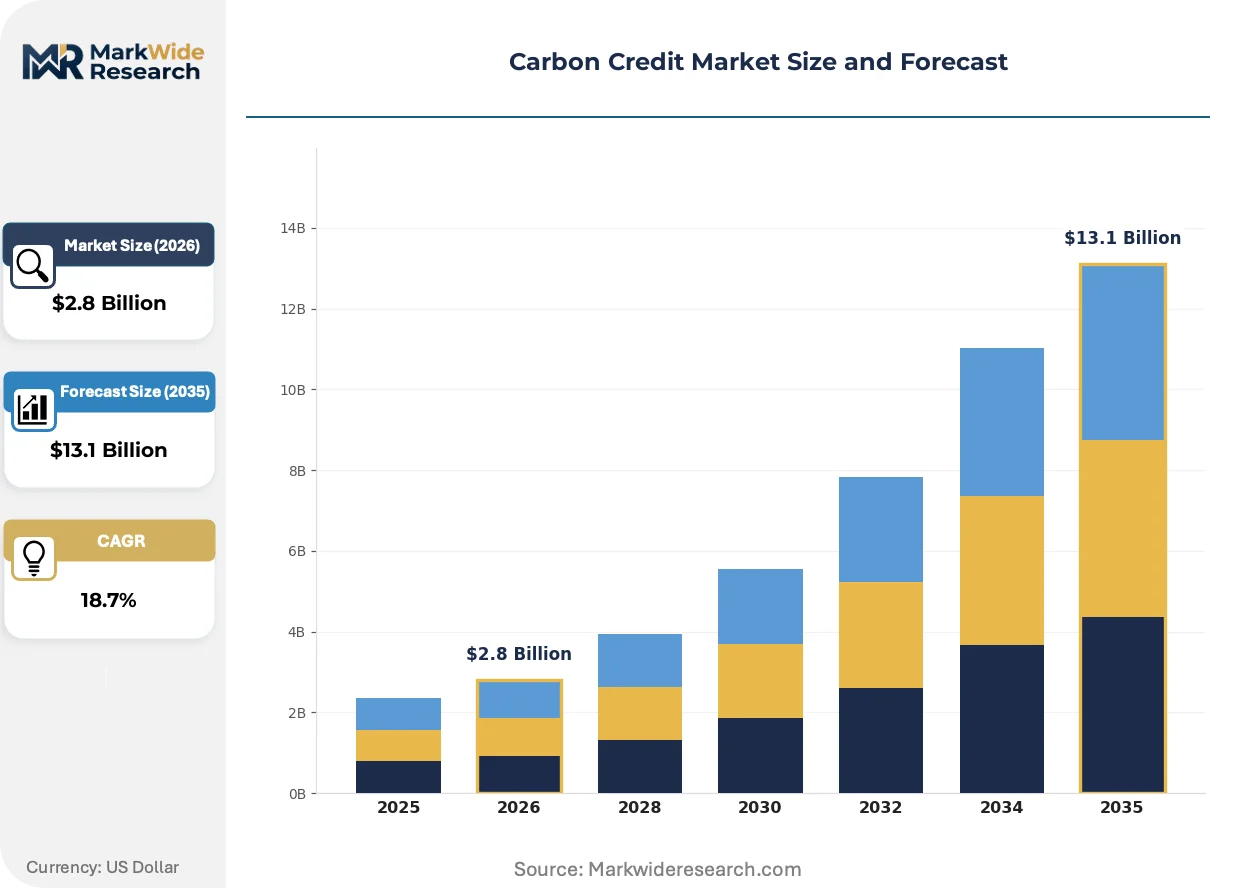
Market Dynamics
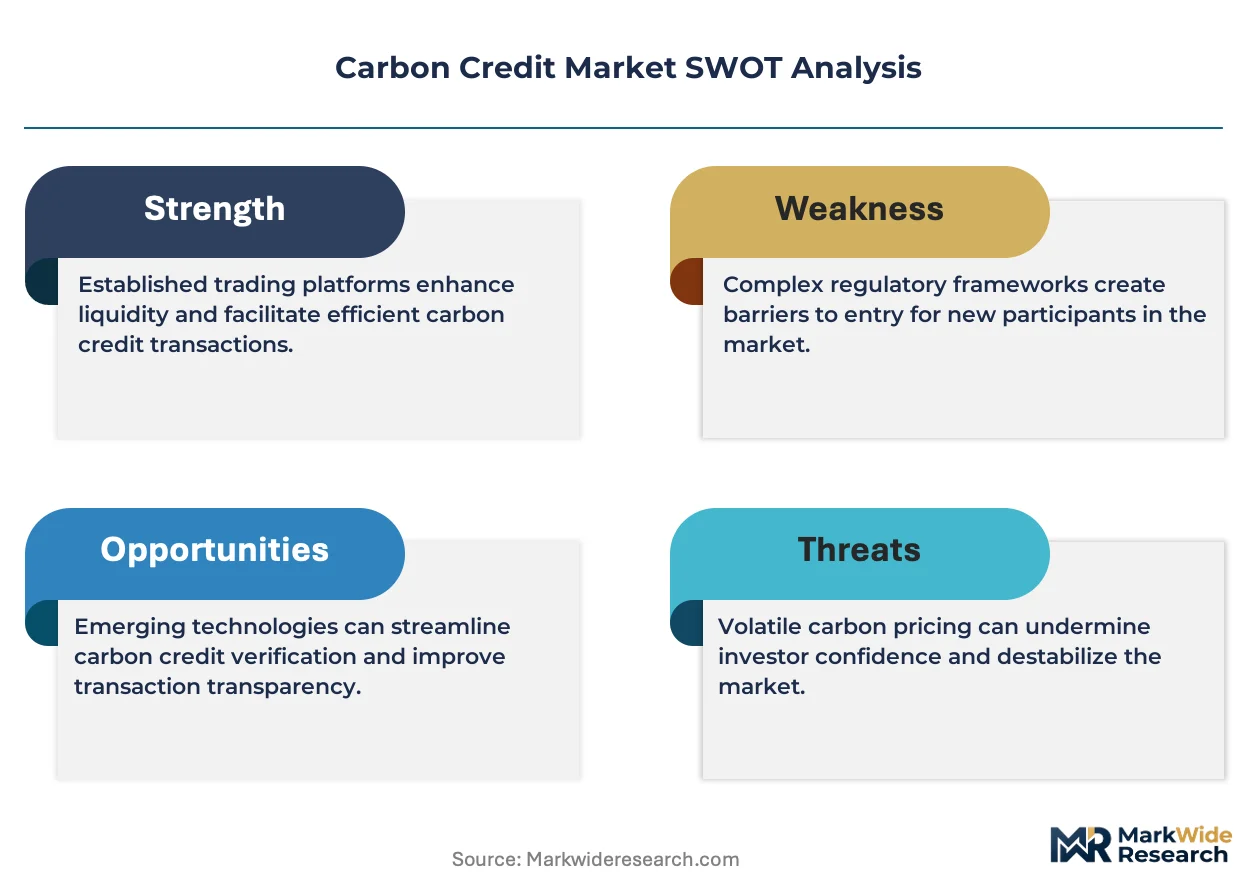
The carbon credit market is bifurcating around integrity standards as the Integrity Council for Voluntary Carbon Markets deploys its Core Carbon Principles across major registries, forcing project developers to upgrade verification protocols or face exclusion from premium pricing tiers.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers into the European Union must surrender equivalent credits or pay border levies, compelling cross-border supply chains to secure compliance-grade offsets preemptively.
- Aviation sector net-zero commitments:Airlines under pressure to neutralize Scope 3 emissions are accelerating procurement of verified offsets through long-term offtake agreements with reforestation and peatland restoration projects.
- Blockchain-based registries:Distributed ledger technology is reducing double-counting risks and compressing settlement cycles, attracting institutional capital previously deterred by opacity in voluntary markets.
Market Restraints
- Verification cost inflation:Third-party validation under Verra's Verified Carbon Standard and Gold Standard methodologies now consumes 15-25% of project revenue, squeezing margins for smaller developers.
- Supply concentration in tropical jurisdictions:Brazil and Indonesia host disproportionate volumes of high-quality reforestation and peatland credits, exposing buyers to sovereign risk and localized climate events.
- Methodological fragmentation:Competing standards for permanence and additionality create arbitrage complexity, forcing corporates to maintain multiple registry relationships.
Strategic Opportunities
- Blue carbon ecosystems:Mangrove and seagrass restoration projects in Southeast Asia offer co-benefits for coastal resilience and biodiversity, commanding premium pricing from ocean-focused corporate buyers.
- Integration of satellite monitoring with ground-truthing:Converging remote sensing and IoT sensor networks enables real-time verification of forest carbon stocks, reducing monitoring lag and insurance costs.
- California's cap-and-trade linkage expansion:The Western Climate Initiative is exploring connections with additional North American jurisdictions, promising liquidity expansion for compliance-grade offsets.
Industry Challenges
- Geospatial analytics talent scarcity:Project developers struggle to hire specialists capable of integrating satellite imagery, machine learning, and field data for robust carbon accounting.
- Legacy registry system integration:Established platforms require expensive API overhauls to interface with blockchain-based settlement infrastructure, delaying technology adoption.
- Permanence risk quantification:Insurers and ratings agencies lack standardized frameworks for pricing reversal risk in nature-based solutions, constraining project finance availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Credit Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.1 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Voluntary, Compliance, Auctioned, Project-Based Application: Renewable Energy, Emission Reduction, Carbon Footprint, Offsetting End User: Corporations, Governments, NGOs, Investors Technology: Blockchain, Satellite Monitoring, Data Analytics, Emission Tracking |
| Companies Covered | Tesla, Intercontinental Exchange, Xpansiv, Climate Impact X, South Pole, ClimatePartner, Verra, Gold Standard, Indigo Ag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Credit Market Evolving Landscape
Digital infrastructure is compressing transaction friction while regulatory tightening separates premium-grade credits from commodity offsets. Verification automation and buyer-side due diligence platforms are emerging as competitive differentiators.
Blockchain-based settlement infrastructure is decentralizing registry functions previously concentrated in centralized databases. Major commodity exchanges and fintech platforms are adopting distributed ledger protocols to enable atomic settlement of credit transfers. This architecture reduces counterparty exposure and enables fractional ownership structures for institutional portfolios.
The EU Emissions Trading System and Carbon Border Adjustment Mechanism are tightening delivery obligations for importers. Industrial emitters must now source compliance-grade credits with stricter permanence guarantees or face escalating border levies. Steel and cement producers with significant import exposure are establishing dedicated carbon procurement functions to manage surrender obligations.
Corporate buyers are unbundling credit procurement from sustainability consulting relationships. Large emitters are building in-house carbon desks with direct registry access, bypassing intermediaries that previously bundled advisory and transaction services. This disintermediation is most visible among Fortune 500 manufacturers with science-based targets requiring multi-year offset portfolios.
Carbon Credit Market Segmentation
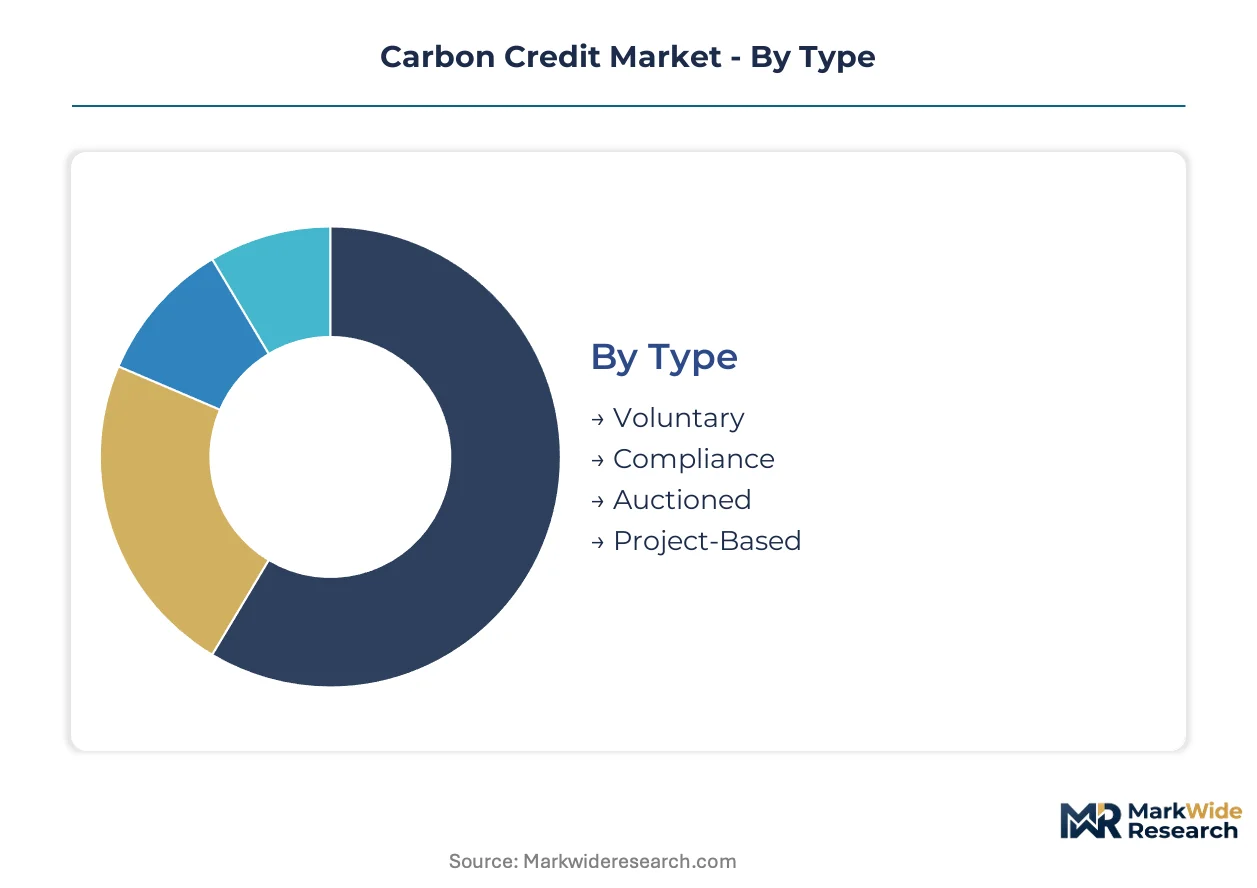
Carbon credit segmentation determines which verification standards apply, where liquidity concentrates, and how procurement strategies vary across buyer types. Distinct regulatory and voluntary pathways create fundamentally different pricing dynamics and settlement requirements for each segment.
Type:
Certification burden varies sharply across type segments, with compliance instruments demanding surrender-grade verification while voluntary credits operate under lighter third-party standards.
- Voluntary:Credits purchased outside regulatory mandates, typically verified through Verra's Verified Carbon Standard or Gold Standard methodologies. Demand concentrates among Fortune 500 corporations with science-based targets, driven by reputational risk management and supply chain pressure from institutional investors.
- Compliance:Instruments tied to cap-and-trade systems such as the EU Emissions Trading System or California's Western Climate Initiative. Procurement concentrates among steel and cement importers facing EU Carbon Border Adjustment Mechanism obligations, with surrender deadlines creating inflexible delivery requirements.
- Auctioned:Primary market credits distributed through government allocation rounds or exchange-hosted sales. Governments in linked jurisdictions such as Quebec and Ontario participate through Western Climate Initiative coordinated auctions.
- Project-Based:Direct offtake agreements between developers and end-users, bypassing spot market intermediation. Long-term contracting dominates in Brazil's reforestation sector and Indonesia's peatland restoration initiatives.
Compliance credits sit at the top of the volume ranking, with voluntary credits climbing the fastest as corporate net-zero commitments accelerate procurement outside regulatory frameworks.
Application:
Application segments map directly to project methodology eligibility and the permanence guarantees required by different buyer risk profiles.
- Renewable Energy:Credits from wind, solar, and hydro projects displacing fossil generation, verified through standardized grid-emission factors. Demand concentrates in India and China where renewable capacity expansion outpaces grid decarbonization, with buyers attracted by lower permanence risk relative to nature-based solutions.
- Emission Reduction:Industrial efficiency and methane capture projects reducing baseline emissions below business-as-usual trajectories. Procurement clusters among oil and gas majors facing Scope 1 reduction targets, with EPA compliance pathways in the US and MEE oversight in China shaping verification requirements.
- Carbon Footprint:Credits applied to product-level lifecycle assessments and corporate inventory neutralization. Consumer goods manufacturers with complex supply chains drive demand for this application segment.
- Offsetting:Direct retirement of credits against residual emissions after reduction efforts. Aviation sector participants under ICAO's Carbon Offsetting and Reduction Scheme for International Aviation dominate this application.
Renewable Energy commands the largest transaction volume, with Emission Reduction expanding most quickly as methane regulations tighten across North American and European jurisdictions.
End User:
End user categories determine contract structure, with institutional investors requiring securitization features absent from corporate procurement.
- Corporations:Buyers seeking to neutralize Scope 1-3 emissions or meet supplier requirements from downstream customers. Procurement concentrates among technology and financial services firms with net-zero commitments, with in-house carbon desks displacing intermediary relationships.
- Governments:Sovereign purchasers securing credits for Nationally Determined Contribution fulfillment or international climate finance obligations. Brazil and Indonesia governments participate as both sellers and strategic buyers in this segment.
- NGOs:Conservation organizations acquiring credits for retirement rather than resale, prioritizing co-benefits for biodiversity and community livelihoods.
- Investors:Asset managers and commodity funds treating credits as alternative investments or inflation hedges. Blockchain-based settlement infrastructure enables fractional ownership structures for this end user category.
Corporations generate the deepest liquidity pool, with Investors gaining share fastest as institutional capital allocates to environmental commodities.
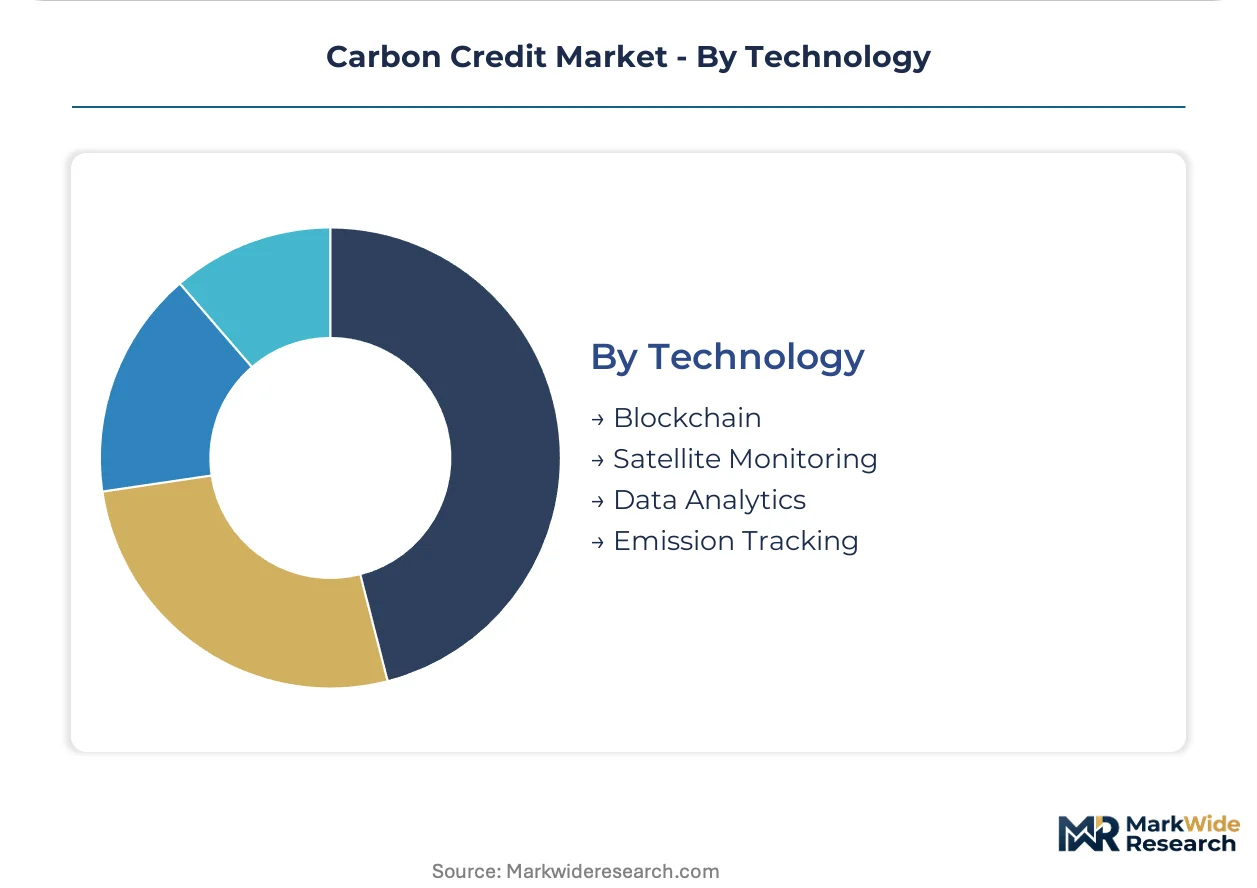
Technology:
Technology segments determine verification cost structure and the speed of credit issuance from project registration.
- Blockchain:Distributed ledger infrastructure for registry functions, settlement, and provenance tracking. Demand concentrates among fintech platforms and commodity exchanges seeking to reduce counterparty exposure and enable atomic settlement.
- Satellite Monitoring:Remote sensing for forest carbon stock verification and reversal detection. Project developers in Brazil and Indonesia adopt this technology to compress monitoring lag and satisfy buyer due diligence requirements.
- Data Analytics:Machine learning integration of multiple data streams for carbon accounting automation. Specialist talent scarcity constrains adoption among smaller developers.
- Emission Tracking:IoT sensor networks and continuous monitoring systems for industrial and fugitive emission quantification. Oil and gas operators deploy this technology for methane detection and regulatory compliance.
Satellite Monitoring leads technology adoption by transaction volume, with Blockchain scaling fastest as major registries pilot distributed ledger migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping project development geography as developers migrate toward jurisdictions with lower verification costs and favorable land-tenure frameworks. Brazil and Indonesia attract disproportionate capital flows due to cost-of-compliance gaps versus North American and European alternatives.
United States
California's Air Resources Board operates the Western Climate Initiative cap-and-trade program, generating sustained demand for compliance-grade offsets from linked jurisdictions. The EPA oversees methane regulations that tighten emission reduction verification requirements for oil and gas operators. Corporate procurement concentrates in Houston and Denver, where energy majors maintain dedicated carbon desks for offset portfolio management.
Brazil
Reforestation project developers leverage the country's vast degraded pastureland to generate Verified Carbon Standard credits at scale. The national climate authority implements frameworks for Nationally Determined Contribution fulfillment that channel international finance into Amazon restoration. São Paulo anchors the domestic carbon services ecosystem, hosting verification specialists and legal advisory firms serving project developers.
Indonesia
Peatland restoration initiatives command premium pricing due to exceptional carbon density and co-benefits for biodiversity conservation. The Ministry of Environment and Forestry administers licensing frameworks that determine project eligibility for international credit issuance. Kalimantan and Sumatra host concentrated development activity, with plantation companies repurposing drained peatlands for carbon-focused land use.
Germany
Industrial emitters facing EU Carbon Border Adjustment Mechanism obligations secure compliance credits through Frankfurt-based commodity trading infrastructure. The Federal Environment Agency enforces national climate targets that compel steel and cement producers to maintain offset reserves. The Rhine-Ruhr industrial corridor drives concentrated demand as manufacturers prepare for phased CBAM implementation.
Singapore
Financial institutions and commodity traders establish regional carbon desks to intermediate flows between Southeast Asian project developers and Northeast Asian buyers. The Monetary Authority of Singapore pilots regulatory frameworks for carbon credit trading and derivatives clearing. The city-state's exchange infrastructure attracts listings from Indonesian and Malaysian project developers seeking Asian liquidity pools.
Carbon Credit Market Competitive Landscape
Strategic partnerships dominate the current landscape as exchanges, registries, and project developers forge vertical alliances to secure supply and distribution channels. The vendor base clusters around three functional tiers: commodity exchanges providing liquidity infrastructure, standard-setting bodies controlling verification protocols, and project developers originating credits. Competitive positioning hinges on registry relationships, technology integration capabilities, and geographic sourcing networks. M&A activity and technology licensing represent the primary expansion vectors as participants seek to compress settlement cycles and reduce counterparty exposure.
Within the exchange infrastructure tier, Intercontinental Exchange leverages its commodity trading heritage to anchor liquidity in compliance credit futures, while Xpansiv occupies a position in spot market digitization through its CBL platform. Tesla exemplifies the corporate-producer archetype, converting regulatory credit expertise into voluntary market participation. These three entities represent contrasting strategic postures: incumbent exchange infrastructure, fintech-enabled spot market innovation, and vertically integrated corporate origination.
| Leading Market Players |
|---|
| Tesla |
| Intercontinental Exchange |
| Xpansiv |
| Climate Impact X |
| South Pole |
| ClimatePartner |
| Verra |
| Gold Standard |
| Indigo Ag |
| Others |
Value Network & Pricing Analysis
EU Allowance futures pricing on the Intercontinental Exchange serves as the primary benchmark cascading through voluntary credit markets, compressing margins for project developers in Brazil and Indonesia while elevating premium tiers for Core Carbon Principles-aligned issuances.
Pricing Analysis
Direct-to-corporate offtake agreements command thinner margins than exchange-mediated spot transactions, with project developers capturing 60-75% of final credit value versus 40-50% through intermediary channels. Price differentiation hinges on certification tier under Verra's Verified Carbon Standard and permanence guarantee strength, with compliance-grade instruments from Western Climate Initiative jurisdictions sustaining premium multiples over voluntary alternatives. Cost compression in the project-based segment intensifies as verification expenses consume larger revenue shares, squeezing smaller developers unable to amortize validation costs across large credit volumes. Corporate buyers with science-based targets exhibit lowest price sensitivity, while commodity traders and speculative investors drive hardest bargain pressure on spot market liquidity.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian reforestation developers supplying 35-40% of nature-based voluntary credits, exposing buyers to concentrated sovereign risk and localized climate disruption. Raw material inputs center on degraded pastureland acquisition costs, seedling nursery capacity, and third-party verification labor pools concentrated in São Paulo and Jakarta. Supply chain risk manifests through regulatory restriction as Indonesia's Ministry of Environment and Forestry tightens licensing frameworks for peatland conversion projects. Distribution runs through Singapore-based commodity traders intermediating flows between Southeast Asian originators and Northeast Asian corporate buyers, with blockchain-enabled settlement infrastructure emerging as parallel channel for institutional investor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon credit market functions as a regulatory compounder where EU Carbon Border Adjustment Mechanism phase-in creates structurally expanding compliance demand that voluntary markets increasingly shadow.
For Market Incumbents: Cement registry relationships with Verra and Gold Standard through accelerated methodology investment ahead of Integrity Council for Voluntary Carbon Markets enforcement, insulating premium pricing tiers from exclusion risk. Acquire satellite monitoring capabilities or secure exclusive partnerships with geospatial analytics providers to compress verification timelines and defend margin position against fintech-enabled challengers. Prioritize long-term offtake contracting with aviation sector buyers facing ICAO CORSIA surrender obligations, locking in volume commitments before new entrant competition intensifies. For New Entrants and Emerging Players: Blockchain-native settlement infrastructure offers the most penetrable wedge for institutional investor segments previously deterred by registry opacity and settlement friction. Target blue carbon ecosystems in Southeast Asian jurisdictions where mangrove restoration methodologies remain underdeveloped relative to terrestrial forestry, enabling first-mover premium capture before standardized protocols commoditize pricing. Pursue direct registry API integration rather than intermediary relationships, disintermediating established advisory bundlers through technology-enabled self-service procurement platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated project developers controlling land tenure, verification relationships, and direct buyer access across multiple jurisdictions. Long-term viability rests on permanence risk quantification capabilities that unlock project finance availability and insurance market development. Monitor California Air Resources Board linkage expansion announcements as inflection signal for Western Climate Initiative liquidity multiplication and compliance-grade offset demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Registry Technology Migration | Distributed ledger adoption by Verra and Gold Standard reduces settlement cycles and counterparty exposure for institutional portfolios. |
| Blue Carbon Methodology Development | Mangrove and seagrass protocol expansion unlocks premium pricing from ocean-focused corporate buyers with science-based targets. |
| Aviation Sector Offtake Contracting | Long-term agreements with airlines facing ICAO CORSIA obligations secure volume commitments and pricing visibility. |
| Satellite-Ground Verification Integration | Remote sensing and IoT convergence compresses monitoring lag and reduces insurance costs for nature-based solutions. |
| California Linkage Expansion Participation | Western Climate Initiative jurisdiction additions multiply liquidity pools for compliance-grade offset trading. |
Research Methodology
Bottom-up corporate procurement modeling reconciled against top-down project development tracking forms the analytical core, combining structured interviews with carbon desk heads at Fortune 500 manufacturers, verification specialists at Verra and Gold Standard, and commodity traders at Singapore-based intermediaries with secondary validation from EU ETS auction data, California Air Resources Board compliance reports, and Intercontinental Exchange futures volume disclosures.
Historical trendline analysis across credit issuance volumes, retirement patterns, and price discovery mechanisms informs projection framework construction, with segmentation modeling across voluntary versus compliance type, renewable energy versus nature-based application, and blockchain versus legacy registry technology. CAGRs derive from regression analysis of credit demand elasticities against regulatory milestone implementation schedules and corporate net-zero commitment trajectories, incorporating aviation sector procurement forecasts and EU Carbon Border Adjustment Mechanism coverage expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Integrity Council for Voluntary Carbon Markets enforcement stringency, permanence risk quantification breakthroughs, and sovereign regulatory shifts in Brazil and Indonesia. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Track Carbon Footprint App Market