
 Carbon Capture and Sequestration Market | 2026-2036
Carbon Capture and Sequestration Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Capture and Sequestration Market Analysis
The US Gulf Coast is fragmenting as multiple developers race to capture industrial CO2 streams from existing refineries and chemical plants. ExxonMobil anchors its position through control of the Houston-area pipeline network and planned storage hub development. Shell competes by leveraging its integrated gas processing expertise and offshore saline aquifer access in the North Sea.
Carbon capture and sequestration encompasses engineered systems that separate CO2 from industrial flue gas or ambient air, compress it to supercritical phase, and inject it into deep geological formations for permanent storage at depths typically exceeding 800 meters. Absorption technology using amine solvents dominates current deployment due to proven scalability in natural gas processing and power plant retrofit applications. Enhanced oil recovery remains the largest application segment by revenue, though direct air capture installations are attracting capital as off-take agreements for permanent geological storage multiply.
The US EPA Underground Injection Control program and the EU CCS Directive establish permitting frameworks that determine project viability timelines and liability structures. EPA Class VI well standards for CO2 injection are forcing developers to front-load site characterization costs, while the EU's F-Gas Regulation and national storage licensing regimes shape cross-border transport economics. Stakeholders must monitor how 45Q credit transferability rules and EU Innovation Fund disbursement pacing affect project finance structures.
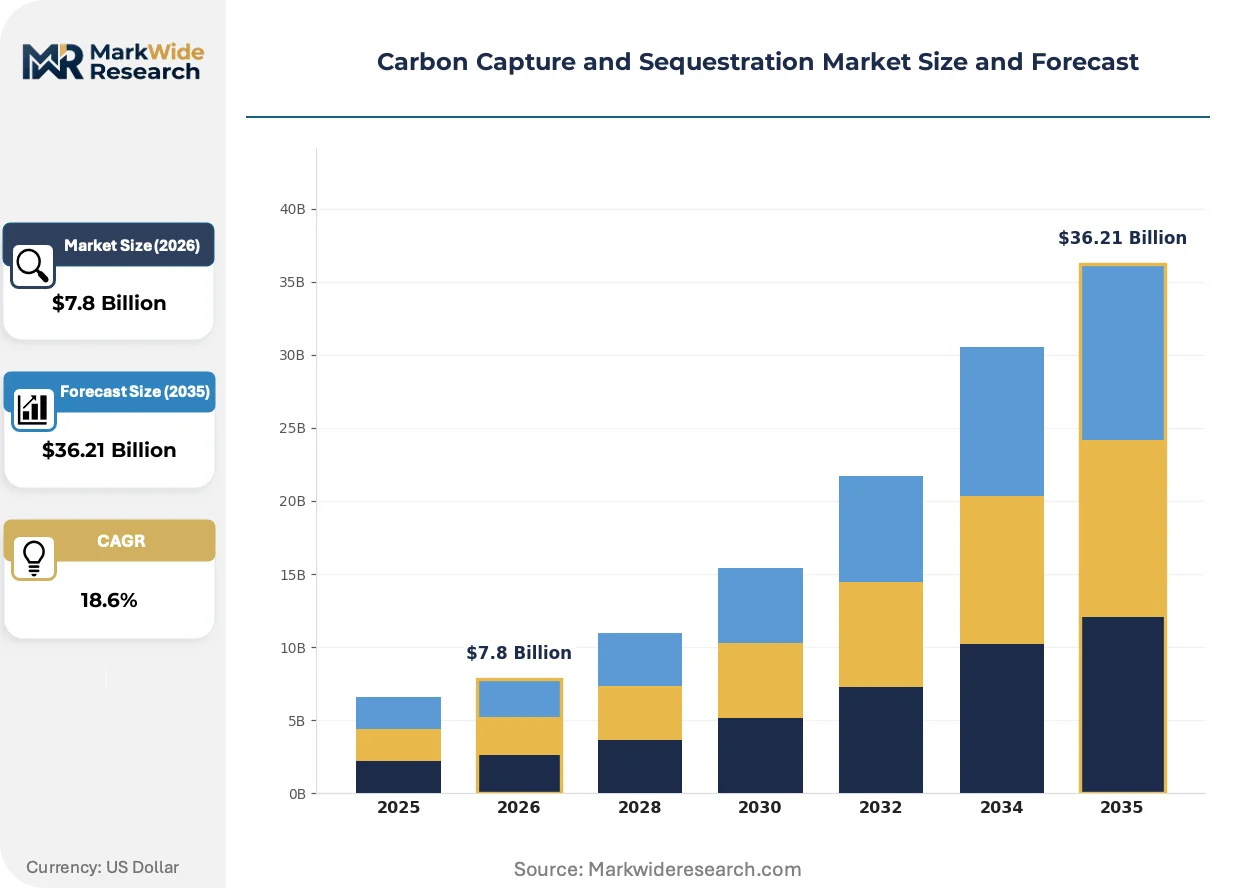
Market Dynamics
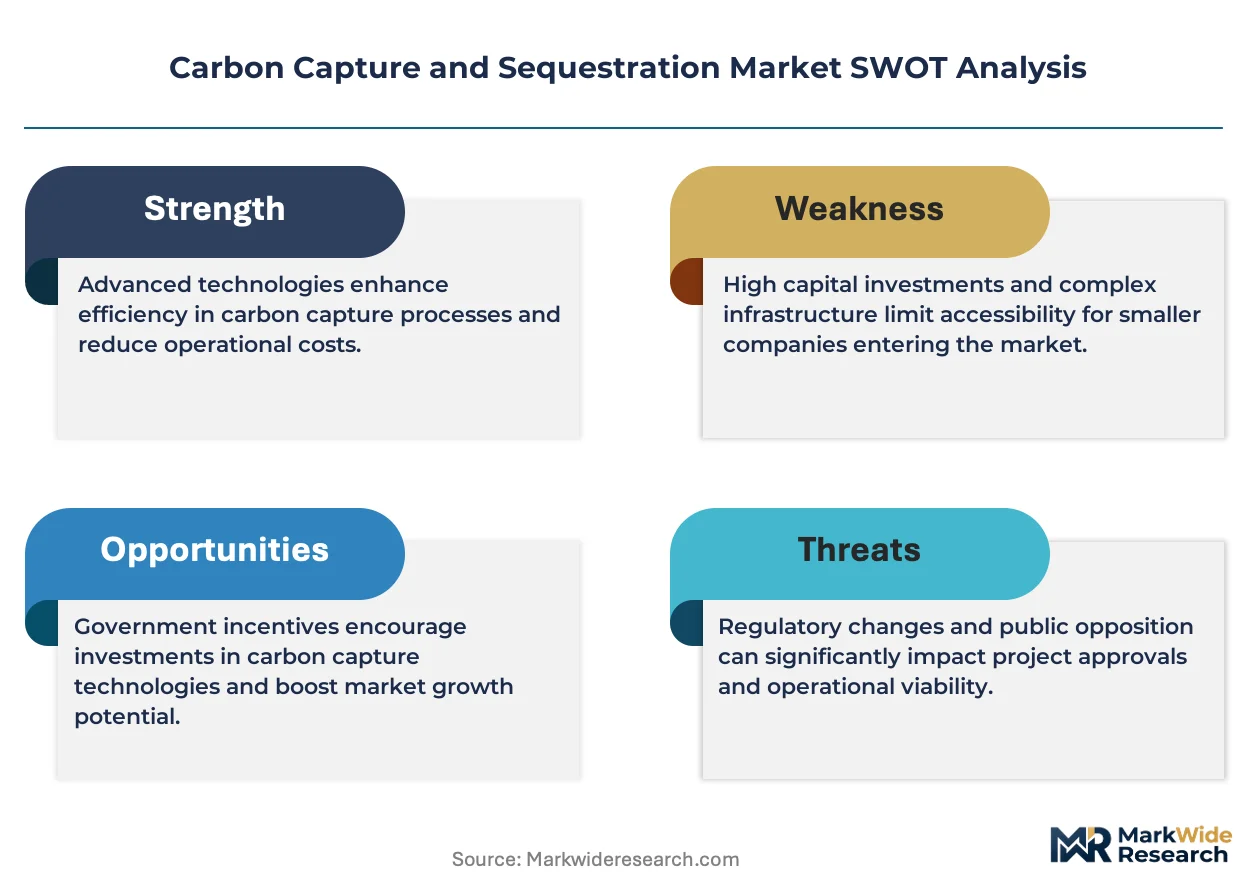
The US Inflation Reduction Act's 45Q tax credit expansion and the EU Carbon Border Adjustment Mechanism are restructuring project finance timelines, forcing developers to front-load capital commitments while long-dated storage liability frameworks remain unresolved.
Growth Catalysts
- Enhanced oil recovery demand:Permian Basin operators seek CO2 offtake for tertiary recovery, creating immediate revenue streams for capture facilities before permanent sequestration economics mature.
- EU Innovation Fund disbursements:The European Commission's €38 billion climate technology allocation is de-risking first-of-a-kind capture installations at cement and steel plants.
- Post-combustion amine absorption:Proven retrofit compatibility with existing coal and natural gas power plants accelerates deployment without requiring greenfield construction.
Market Restraints
- EPA Class VI well characterization costs:Extensive seismic surveys and groundwater monitoring requirements for underground injection control permits extend pre-construction timelines by 24-36 months.
- Steel and specialty alloy input volatility:Supercritical CO2 pipeline construction depends on chromium-molybdenum steel grades subject to mining supply concentration in South Africa and Kazakhstan.
- Direct air capture energy intensity:Solid sorbent and liquid solvent DAC systems require 5-7 GJ per tonne CO2, constraining deployment to regions with abundant low-cost renewable electricity.
Strategic Opportunities
- Industrial clusters in Rotterdam and Antwerp:Dense concentrations of refineries, chemical plants, and cement kilns enable shared pipeline infrastructure and economies of scale in the EU's northwestern port corridor.
- 45Q credit transferability to investment tax credit electors:The IRA's provision allowing carbon capture developers to monetize credits through third-party tax equity partnerships unlocks project finance for non-integrated pure-play developers.
- Offshore saline aquifer access:North Sea depleted oil and gas fields offer 20+ gigatonne storage capacity with existing platform infrastructure repurposable for injection operations.
Industry Challenges
- Geological reservoir engineer scarcity:Specialized expertise in CO2 plume migration modeling and caprock integrity assessment is concentrated among petroleum industry veterans approaching retirement.
- Long-term stewardship liability fragmentation:Unclear allocation of post-injection monitoring costs between private operators and state governments complicates project offtake negotiations.
- Amine solvent degradation management:Thermal and oxidative breakdown of monoethanolamine requires continuous reclamation unit operation, adding operational complexity to capture facility staffing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Capture and Sequestration Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $36.21 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Absorption, Adsorption, Membrane Separation, Cryogenic Distillation End User: Power Generation, Oil & Gas, Manufacturing, Chemical Processing Application: Enhanced Oil Recovery, Industrial Emission Reduction, Bioenergy, Direct Air Capture Deployment: Onshore, Offshore, Industrial Sites, Urban Areas |
| Companies Covered | ExxonMobil, Shell, Chevron, Fluor Corporation, Linde plc, Equinor, TotalEnergies, Aker Solutions, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Capture and Sequestration Market Emerging Trajectories
Technology developers are racing to compress energy penalties and equipment footprints as project developers face pressure to deliver bankable cost structures before tax credit windows narrow.
Solid sorbent direct air capture systems are migrating from pilot demonstrations to modular commercial units. Climeworks and Carbon Engineering offtake agreements with Microsoft, Shopify, and Swiss Re validate corporate voluntary demand. The technology is migrating from bespoke engineering to standardized skid-mounted designs that reduce installation labor and enable factory production economies.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants is reshaping solvent selection for low-temperature capture processes. Equipment manufacturers are accelerating ammonia and transcritical CO2 refrigeration cycle adoption for liquefaction stages. Chemical processors in Germany and the Netherlands face compressed compliance timelines driving near-term retrofit investments.
Corporate buyers are consolidating offtake contracting around permanent geological storage with third-party verification. Technology-agnostic procurement teams at Stripe, Alphabet, and Meta are displacing enhanced oil recovery-linked credits with saline aquifer injection requirements. This preference shift concentrates developer attention on Class VI permit-ready sites in Texas, Louisiana, and the UK North Sea.
Carbon Capture and Sequestration Market Segmentation
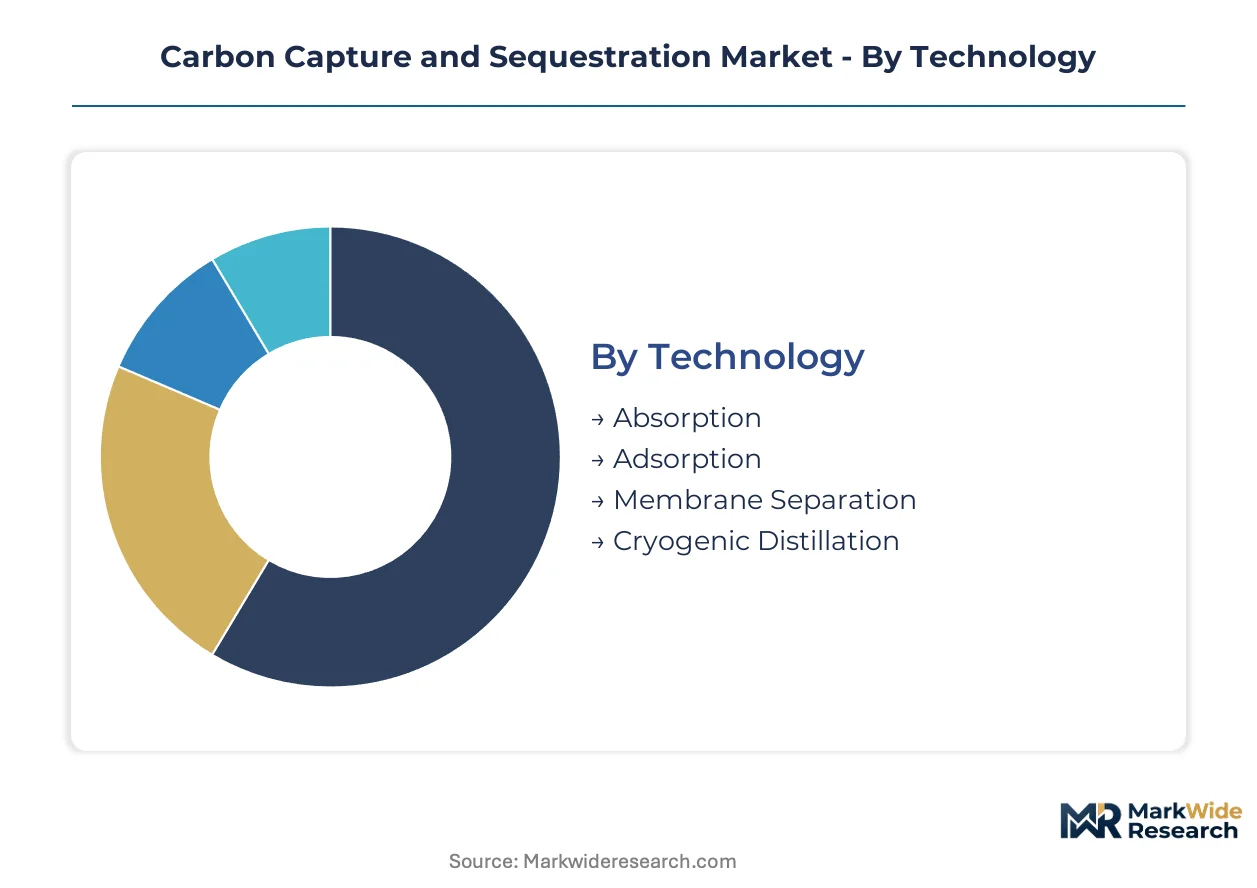
Technology selection determines capital intensity and operational staffing models across CCS installations. End-user concentration in petrochemical corridors and power generation basins shapes regional deployment patterns. Application economics vary sharply between revenue-generating enhanced oil recovery and cost-center permanent sequestration.
Technology:
After-sales service intensity concentrates in amine solvent management and membrane replacement cycles, creating recurring revenue streams for technology licensors.
- Absorption:Amine-based liquid solvents chemically bind CO2 from flue gas streams through reversible temperature-swing regeneration. Demand clusters at coal and natural gas power plants across the US Midwest and Poland where retrofit compatibility avoids greenfield construction delays. Thermal energy requirements for solvent regeneration represent the dominant operational cost driver.
- Adsorption:Solid sorbent materials capture CO2 through pressure or temperature swing cycles with lower energy penalties than amine systems. Deployment concentrates in direct air capture facilities in Iceland and the US Southwest where abundant geothermal or solar resources offset electricity costs. Modular skid-mounted designs enable factory production economies and rapid site installation.
- Membrane Separation:Polymeric or inorganic membranes filter CO2 based on molecular size and solubility differentials.
- Cryogenic Distillation:Low-temperature liquefaction separates CO2 from gas streams through phase change.
Absorption holds the largest share; momentum sits with adsorption.
End User:
Capital deployment timelines stretch longest for power generators facing regulatory compliance deadlines versus industrial emitters with shorter investment horizons.
- Power Generation:Coal and natural gas plants deploy post-combustion capture to meet emissions mandates while preserving baseload capacity. Concentration in Germany, the UK, and Texas reflects carbon pricing exposure and 45Q credit eligibility. Retrofit economics depend on remaining plant operational life and regional electricity market structures.
- Oil & Gas:Upstream operators and refineries capture CO2 for enhanced oil recovery or compliance with venting regulations. The US Permian Basin and North Sea offshore platforms anchor demand where existing infrastructure reduces transport costs. Integrated operators leverage pipeline networks to monetize captured streams through tertiary recovery.
- Manufacturing:Cement and steel producers face process emission challenges requiring capture integration at kiln and blast furnace sites.
- Chemical Processing:Ammonia and ethanol plants generate concentrated CO2 streams offering lower capture costs than dilute flue gas applications.
Oil & Gas dominates current deployment; Manufacturing is climbing the fastest as cement and steel decarbonization mandates tighten.
Application:
Revenue model differentiation separates immediate offtake payments from long-dated carbon credit monetization, structuring project finance risk profiles.
- Enhanced Oil Recovery:CO2 injection into depleted reservoirs displaces residual crude oil through miscible flooding. The Permian Basin and West Texas dominate activity where pipeline infrastructure connects capture sources to oilfields. Oil price volatility directly impacts project returns and offtake contract pricing.
- Industrial Emission Reduction:Capture systems installed at cement kilns, steel mills, and chemical plants abate process and combustion emissions. EU Innovation Fund disbursements are de-risking first-of-a-kind installations in the Netherlands and Belgium. Corporate net-zero commitments drive voluntary procurement beyond regulatory minimums.
- Bioenergy:Carbon-negative power generation combines biomass combustion with capture and permanent storage.
- Direct Air Capture:Ambient air processing removes legacy atmospheric CO2 independent of emission source location.
Enhanced Oil Recovery retains the largest installed base; Direct Air Capture is gaining share fastest as corporate voluntary demand scales.
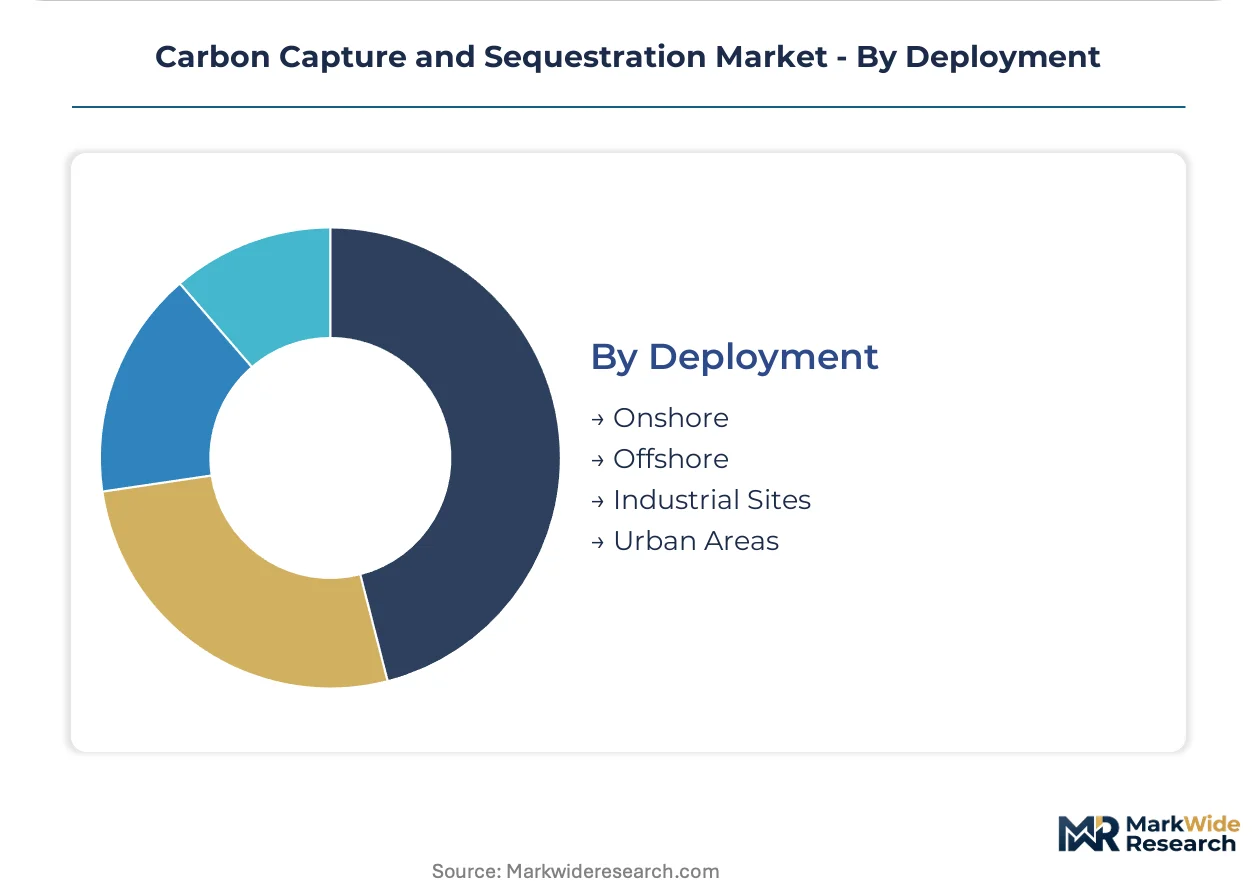
Deployment:
Site geology and existing infrastructure availability determine whether developers pursue centralized hub models or distributed capture configurations.
- Onshore:Saline aquifer injection in Texas, Louisiana, and North Dakota offers gigatonne-scale storage capacity with established EPA Class VI permitting pathways. Proximity to industrial emission sources minimizes pipeline transport costs. Land access and pore space ownership negotiations extend pre-construction timelines.
- Offshore:Depleted oil and gas fields in the UK and Norwegian North Sea provide 20+ gigatonne storage with repurposable platform infrastructure. Existing subsea pipeline networks reduce capital requirements for transport. National storage licensing regimes in the UK and Denmark shape cross-border project economics.
- Industrial Sites:Co-located capture and utilization at refineries and chemical plants eliminates intermediate transport infrastructure.
- Urban Areas:Direct air capture installations near demand centers minimize CO2 distribution costs for utilization applications.
Onshore holds the largest share; Offshore is expanding most quickly as North Sea regulatory frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline infrastructure and saline aquifer geology concentrate capture and storage investment in the United States, Norway, and the United Kingdom, with industrial cluster development accelerating in the Netherlands and Canada.
United States
The EPA Class VI permitting framework governs underground injection control, with 45Q tax credit transferability enabling third-party project finance. The Gulf Coast petrochemical corridor anchors deployment, where ExxonMobil controls Houston-area CO2 pipeline networks and plans regional storage hub development.
Norway
Equinor leverages depleted North Sea oil and gas fields for 20+ gigatonne saline aquifer storage capacity. The government's Longship project provides capital support for capture facilities at cement and waste-to-energy plants near Oslo, with existing offshore infrastructure repurposable for injection operations.
United Kingdom
The UK storage licensing regime under the Energy Act 2008 shapes cross-border transport economics with EU member states. Industrial clusters at Teesside and Humber combine steel, cement, and power generation emissions for shared pipeline infrastructure, with Harbour Energy advancing offshore saline aquifer projects.
Netherlands
The Rotterdam and Antwerp port corridor enables shared CO2 infrastructure among dense refinery, chemical, and cement concentrations. Porthos project commitments from Air Liquide, ExxonMobil, and Shell target depleted North Sea gas fields, with EU Innovation Fund disbursements de-risking first-of-a-kind installations.
Canada
Alberta's carbon pricing compliance system and 45Q-equivalent tax incentives attract capital to the Edmonton industrial heartland. The Alberta Carbon Trunk Line connects fertilizer and refinery capture sources to depleted oilfields, with Pembina Pipeline expanding capacity for permanent saline aquifer storage.
Carbon Capture and Sequestration Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in solvent supply, membrane fabrication, and compression equipment. Market structure consolidates around integrated oil and gas majors with captive pipeline networks, while technology licensors and engineering contractors compete for project execution mandates. Three archetypes dominate: network-owning storage operators, capture technology licensors, and engineering-procurement-construction specialists. Competitive moves concentrate on pipeline network expansion and offshore storage licensing to lock in offtake volumes before rival hub development.
Among North American integrated majors, ExxonMobil anchors the storage hub archetype through Houston-area pipeline control, while Chevron occupies a comparable position in Permian Basin CO2 offtake markets. European state-affiliated operators exemplify the offshore saline aquifer strategy, with Equinor representing Norwegian North Sea storage development and TotalEnergies situating within French industrial cluster capture initiatives.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| Chevron |
| Fluor Corporation |
| Linde plc |
| Equinor |
| TotalEnergies |
| Aker Solutions |
| Mitsubishi Heavy Industries |
| Others |
Supply Flow & Price Mechanics
Chromium-molybdenum steel supply concentration in South Africa and Kazakhstan determines both the capital cost spread between onshore and offshore project tiers and the geographic clustering of pipeline fabrication capacity. This single-source dependency for supercritical CO2-rated metallurgy compresses margins on transport infrastructure while pushing developers toward integrated hub models that minimize high-grade steel exposure.
Pricing Analysis
The US Inflation Reduction Act's 45Q tax credit transferability rules dictate the pricing tier structure across capture facility development. Project economics stratify across premium, standard, and economy tiers based on storage site permitting maturity and pipeline network access proximity. Cost compression in the standard tier is intensifying because EPA Class VI well characterization timelines extend pre-construction capital lockup periods. Corporate offtake buyers from the technology sector exhibit the lowest price sensitivity due to voluntary carbon removal procurement mandates, while independent power generators face acute margin pressure from compliance-driven retrofit requirements.
Supply Chain Analysis
Extended payment terms from EPC contractors to amine solvent suppliers are becoming standard as project finance structures stretch construction milestones. Manufacturing concentration for specialized compression equipment rests on Germany, Japan, and the United States. Raw material dependencies include monoethanolamine chemical feedstocks, supercritical CO2-rated pipeline steel, and high-pressure injection well casing grades. Tariff exposure on South African chromium imports presents structural risk for North American pipeline developers. Distribution runs through integrated oil and gas majors with captive CO2 transport networks rather than open-access third-party infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon capture and sequestration market sits at a platform-economics inflection where pipeline network interoperability and shared storage hub access determine competitive viability. ExxonMobil's Houston-area CO2 transport system exemplifies how captive infrastructure creates ecosystem lock-in that reshapes developer consolidation patterns.
For Market Incumbents: Pre-empt emerging pure-play capture technology licensors by securing Class VI permit-ready saline aquifer sites ahead of 45Q credit transferability rule finalization. Anchor defensive positioning through backward integration into amine solvent reclamation services, neutralizing the operational complexity threat from solvent degradation management. Control of injection well workover capacity represents the priority lever for locking in long-term offtake relationships. For New Entrants and Emerging Players: Louisiana's industrial corridor along the Mississippi River offers the most penetrable geography for modular direct air capture deployment, given existing EPA Class VI permitting precedents and proximity to Gulf Coast saline aquifer geology. Target voluntary corporate procurement from technology sector buyers with permanent geological storage requirements rather than enhanced oil recovery-linked offtake. A go-to-market angle centered on third-party verification and retirement registry integration bypasses incumbent pipeline dependency. For Investors and Strategic Acquirers: The market sits at a capital-deployment phase that favors engineering-procurement-construction specialists with captive geological characterization capabilities. Long-term viability over the next decade hinges on exposure to industrial cluster hub development rather than standalone power plant retrofit economics. Acquisition targets should screen for Class VI permit application depth and subsurface plume modeling expertise. The signal to watch is EU Innovation Fund disbursement pacing relative to national storage licensing timeline convergence in the North Sea.| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Network Expansion | ExxonMobil's Houston corridor control locks in Gulf Coast capture source commitments before rival hub development. |
| Offshore Storage Licensing | Equinor's North Sea saline aquifer access anchors 20+ gigatonne capacity with repurposable platform infrastructure. |
| Amine Solvent Reclamation Integration | Shell's gas processing expertise reduces operational complexity from thermal and oxidative breakdown management. |
| Direct Air Capture Modularization | Climeworks' skid-mounted designs enable factory production economies and rapid site installation for corporate buyers. |
| Industrial Cluster Hub Development | Porthos project commitments from Air Liquide and Shell target Rotterdam-Antwerp shared infrastructure economies. |
Methodological Framework
Operator-level perspectives from capture facility project developers, EPA Underground Injection Control permit consultants, saline aquifer geologists, EPC contractors, and corporate carbon procurement officers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA Class VI permitting databases, EU Innovation Fund disbursement records, FERC interstate pipeline filings, and IEA carbon capture project tracking. Bottom-up installation cost modeling and top-down policy incentive triangulation produced convergent market sizing across the analysis window.
Scenario-bracketing around 45Q credit transferability final rules and EU Carbon Border Adjustment Mechanism phase-in timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include capture technology type, end-user industry concentration, application revenue model, and deployment geology classification. CAGRs derived from policy incentive elasticity analysis and industrial emission compliance deadline clustering. Industry-specific forecast inputs incorporated amine solvent energy penalty trajectories and direct air capture module learning curve assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play technology licensors or national oil company storage hub consolidation would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
Carbon Capture and Utilization Market
Environment & Sustainability
Global RO Water Purifier Market
Environment & Sustainability
Home Water Softener System Market
Environment & Sustainability
GCC Pneumatic Waste Management System Market
Environment & Sustainability
Primary Water and Wastewater Treatment Equipment Market
Environment & Sustainability
Environmental Monitoring (Surface Water) Market
Environment & Sustainability
Compostable Straws Market
Environment & Sustainability
Qatar Waste Management Market
Environment & Sustainability
Air Pollution Control Systems Market
Environment & Sustainability
Carbon Monoxide Analyzers Market
Environment & Sustainability
North America Green Cement Market
Environment & Sustainability
Singapore Air Purifier Market
Environment & Sustainability
Europe Industrial Air Quality Control Systems Market
Environment & Sustainability
North America Emission Monitoring System Market
Environment & Sustainability
Asia Pacific Air Quality Monitoring Market
Environment & Sustainability
Indoor Air Quality Service Market