
 Track Carbon Footprint App Market | 2026-2036
Track Carbon Footprint App Market Size, Share, and Industry Trends Forecast 2026-2036
Track Carbon Footprint App Market Insights
European software development capacity is rebalancing toward climate-tech infrastructure as regulatory pressure intensifies across the continent. Capture leverages its API-first architecture to anchor enterprise clients seeking embedded emissions data. Joro differentiates through consumer-facing behavioral nudges that sustain engagement beyond initial download spikes. Karbon-X specializes in blockchain-verified offsets, occupying a narrow but defensible niche in voluntary carbon markets.
Track carbon footprint apps are digital platforms that aggregate activity data from payment systems, utility APIs, GPS traces, and IoT sensors to calculate greenhouse gas equivalents using emission factors databases such as DEFRA or EPA standards. Their primary commercial purpose is converting fragmented behavioral or operational data into audit-ready carbon inventories for disclosure, reduction planning, or offset procurement. Business Monitoring applications dominate current revenue as corporates face mandatory Scope 3 disclosure, while Real-time Tracking features represent the fastest-growing capability layer as sensor costs decline. The User Segment split reveals Corporates generating the deepest margin pools through annual contracts, whereas Individuals provide volume expansion through freemium conversion funnels.
The EU Green Deal and CSRD framework mandate granular emissions disclosure across supply chains, directly expanding addressable demand for automated calculation tools. The EPA in the United States and the UK's Environment Agency are tightening reporting thresholds for large enterprises, compressing timelines for manual spreadsheet-based compliance. Stakeholders must monitor whether emerging GHG Protocol updates will force interoperability standards that favor platforms with open data architectures over walled-garden competitors.
Market Dynamics
Enterprise sustainability departments are embedding carbon accounting into procurement workflows as CSRD disclosure mandates force automated Scope 3 tracking across supplier networks.
Growth Catalysts
- CSRD Framework:The EU's Corporate Sustainability Reporting Directive mandates granular emissions disclosure, compelling industrial exporters to adopt automated calculation tools for supply chain compliance.
- Scope 3 Contractualization:Procurement teams in Germany and France are inserting emissions tracking clauses into supplier agreements, creating recurring demand for API-first carbon platforms.
- IoT Sensor Cost Decline:Real-time emissions monitoring hardware prices are dropping, enabling manufacturing facilities to deploy continuous carbon tracking without capital-intensive infrastructure overhauls.
Market Restraints
- Emission Factor Database Fragmentation:Inconsistent DEFRA, EPA, and GHG Protocol standards force platforms to maintain multiple calculation engines, inflating development costs.
- Voluntary Offset Market Volatility:Blockchain-verified credit prices fluctuate with speculative trading, destabilizing revenue models for apps dependent on offset transaction fees.
- Legacy ERP Integration Friction:SAP and Oracle systems in industrial enterprises resist API connectivity, extending implementation timelines and diluting subscription economics.
Strategic Opportunities
- India Manufacturing Export Corridor:The country's Bureau of Energy Efficiency is tightening factory emission norms, creating first-mover advantage for platforms localizing DEFRA-equivalent standards.
- Aviation Supply Chain:Airlines and cargo operators face ICAO CORSIA compliance deadlines, opening specialized modules for jet fuel lifecycle tracking.
- Embedded Finance Convergence:Payment-integrated carbon apps are partnering with neobanks to automate transaction-level footprint calculations at point-of-sale.
Industry Challenges
- Carbon Accounting Talent Scarcity:Platforms struggle to hire engineers fluent in both software architecture and GHG Protocol technical guidance, slowing product iteration cycles.
- Interoperability Certification Delays:Pending updates to ISO 14064-1 create uncertainty around audit-ready data formats, freezing enterprise procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Track Carbon Footprint App Market |
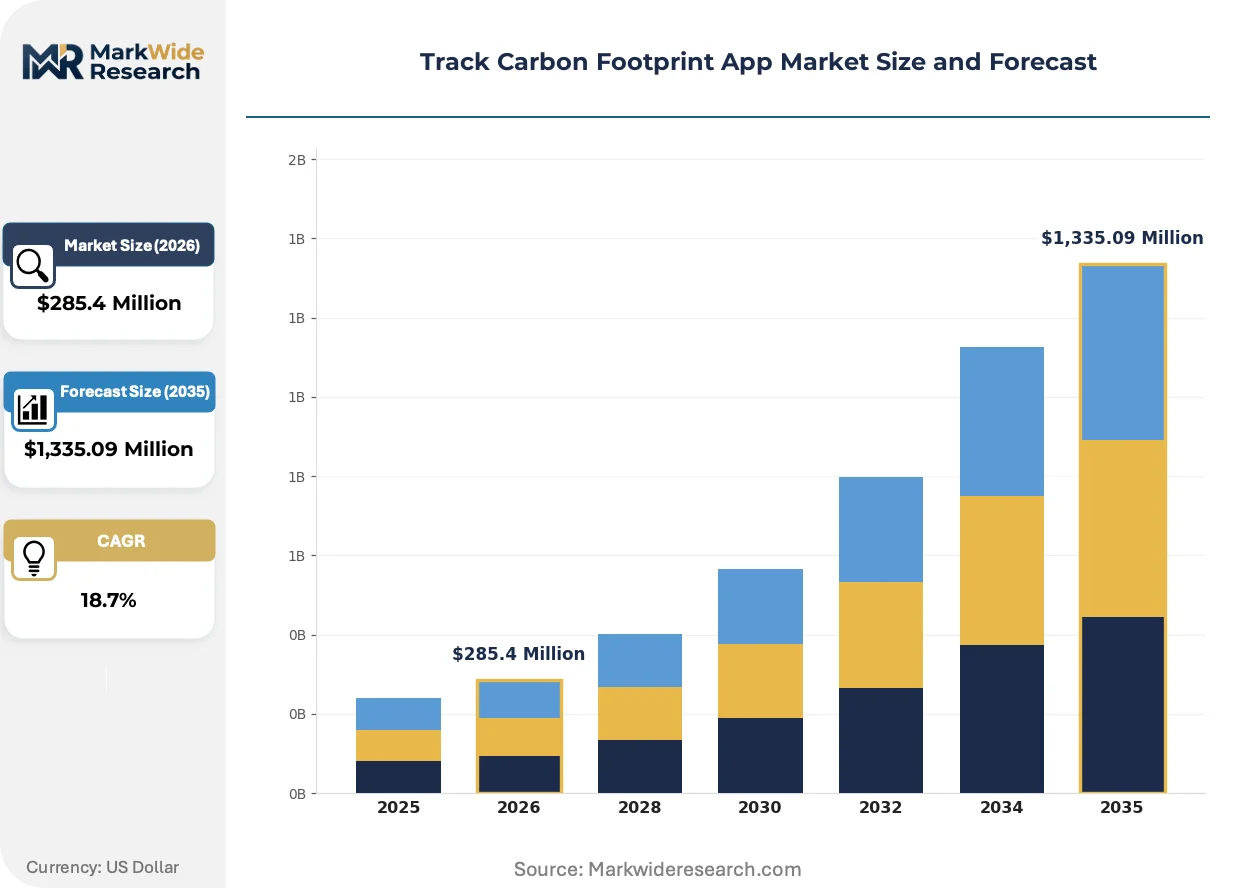
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Personal Use, Business Monitoring, Environmental Reporting, Education Platform: Mobile, Web, Desktop, IoT User Segment: Individuals, Corporates, Non-profits, Educational Institutions Feature Set: Real-time Tracking, Emission Calculators, Reporting Tools, Community Engagement |
| Companies Covered | Capture, Karbon-X, Joro, Decarbon, LiveGreen, Commons, Aerial, Sense, Klima, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Track Carbon Footprint App Market Trends and Innovations
Automated emissions calculation is migrating from retrospective annual reporting to continuous operational intelligence, compressing disclosure cycles and embedding carbon data into daily business decisions.
API-first architectures are overtaking monolithic carbon platforms as enterprise clients demand embedded emissions data within existing procurement and ERP workflows. Sustainability software vendors in Germany and the Netherlands are prioritizing modular integration over standalone dashboards. This shift is compressing margins for walled-garden competitors while rewarding open-data platforms with multi-year enterprise contracts.
The EU Green Deal's F-Gas Regulation and expanding CSRD scope are tightening enforcement timelines for industrial emitters. Chemical manufacturers and automotive suppliers face compressed compliance windows that manual spreadsheet systems cannot satisfy. German industrial clusters are responding by consolidating vendor relationships around platforms with pre-certified calculation methodologies.
Buyer concentration among enterprise sustainability departments is fragmenting decision authority across procurement, legal, and operations functions. Annual contract renewals now require cross-functional sign-off that delays subscription expansions. This pattern is most visible in French and Italian manufacturing conglomerates where Scope 3 liability concerns have elevated legal team involvement in software selection.
Track Carbon Footprint App Market Segmentation
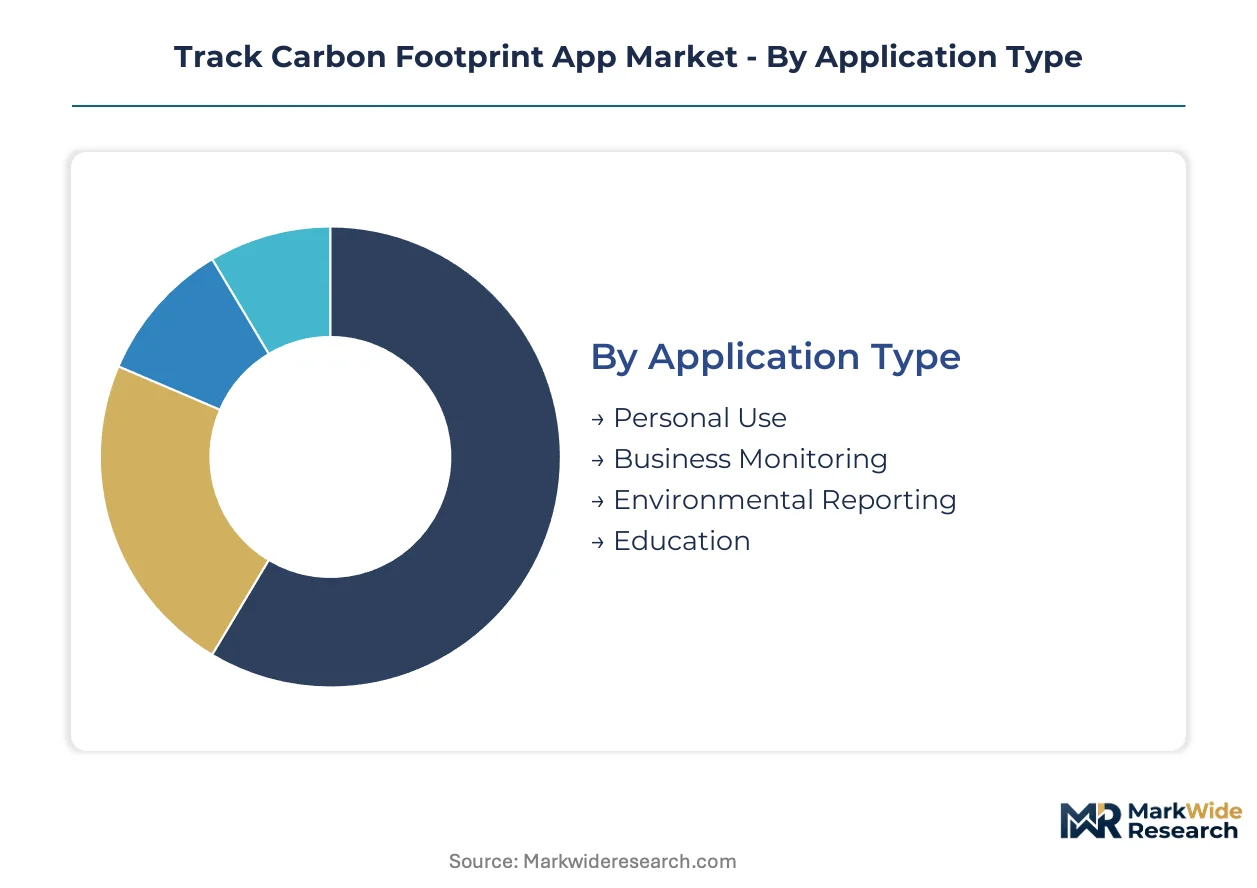
Carbon accounting platforms serve fundamentally different user workflows across personal behavioral change, enterprise compliance automation, and educational engagement. Segmentation reveals where margin pools concentrate versus where volume expansion occurs through freemium conversion mechanics.
Application Type:
Procurement teams prioritize audit-ready outputs over interface sophistication when selecting carbon tools for contractual supplier management.
- Personal Use:Consumer-facing apps aggregate payment data, GPS traces, and utility APIs to calculate household-level footprints using DEFRA emission factors. German and French retail banks embed these calculations into mobile banking interfaces to sustain daily engagement beyond initial download spikes.
- Business Monitoring:Enterprise platforms automate Scope 3 inventory compilation across supplier networks, converting fragmented procurement data into CSRD-compliant disclosure formats. German industrial exporters facing the tightest EU compliance deadlines generate the deepest annual contract margins in this segment.
- Environmental Reporting:Specialized modules format emissions data for regulatory submission to the EPA, the UK's Environment Agency, and EU member state authorities. These tools emphasize calculation methodology transparency for third-party audit verification.
- Education:Classroom-oriented platforms gamify carbon literacy through simulated footprint scenarios and offset procurement exercises. University sustainability programs in the Netherlands and Denmark deploy these for curriculum integration.
Volume sits with Personal Use applications; growth tilts toward Business Monitoring as CSRD mandates expand across EU supply chains.
Platform:
Deployment architecture determines integration depth with existing enterprise systems and sensor infrastructure.
- Mobile:Native iOS and Android applications dominate consumer adoption, leveraging always-available GPS and payment notification access for continuous behavioral monitoring. Neobank partnerships in Germany embed carbon calculations at point-of-sale transaction moments.
- Web:Browser-based dashboards serve procurement teams requiring multi-user access to supplier emissions data without device-specific installation barriers. SAP and Oracle ERP connectors extend implementation timelines but anchor long-term enterprise retention.
- Desktop:On-premise installations persist in defense and critical infrastructure sectors with air-gapped security requirements. These deployments carry higher professional services revenue attachment.
- IoT:Continuous emissions monitoring hardware integrates directly with manufacturing control systems, dropping sensor costs enabling real-time carbon tracking without capital-intensive infrastructure overhauls. Chemical manufacturers in Germany's industrial clusters lead adoption here.
Mobile captures individual user volume; IoT platforms are expanding most quickly as manufacturing facilities deploy continuous monitoring.
User Segment:
Contract value and renewal predictability vary dramatically across organizational buyer types and their regulatory exposure.
- Individuals:Freemium acquisition with premium conversion through offset marketplace transaction fees. Voluntary carbon credit price volatility destabilizes revenue models dependent on this segment.
- Corporates:Multi-year subscriptions with annual recurring revenue anchored by CSRD disclosure mandates and Scope 3 liability concerns elevating legal team involvement in software selection. French and Italian manufacturing conglomerates show the most complex cross-functional procurement processes.
- Non-profits:Grant-funded deployments with limited expansion budgets; sustainability NGOs prioritize open-data architectures for methodology transparency.
- Educational Institutions:Department-level purchasing with semester-aligned procurement cycles; university sustainability offices drive adoption for student engagement metrics.
Corporates anchor revenue concentration; educational institutions provide volume expansion through curriculum standardization.
Feature Set:
Capability layering determines competitive differentiation between retrospective reporting tools and predictive optimization platforms.
- Real-time Tracking:Continuous data ingestion from IoT sensors and utility APIs enables operational intervention before emissions accrue rather than retrospective annual accounting. Manufacturing facilities in Germany deploy these for compressed compliance windows.
- Emission Calculators:Core calculation engines applying DEFRA, EPA, or GHG Protocol emission factors to activity data; platforms must maintain multiple engines due to database fragmentation across jurisdictions.
- Reporting Tools:Automated formatting for regulatory submission and third-party audit verification; pending ISO 14064-1 updates create uncertainty around audit-ready data formats.
- Community Engagement:Social features sustaining behavioral adherence through peer comparison and collective challenge mechanics; consumer apps leverage these to reduce churn beyond initial download spikes.
Reporting Tools carry the highest procurement priority for compliance-driven buyers; Real-time Tracking features gain share fastest as sensor infrastructure proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial data infrastructure anchors European carbon accounting software demand, with emissions disclosure mandates radiating compliance requirements across supplier networks in neighboring economies.
Germany
Industrial exporters in the Ruhr and Baden-Württemberg clusters drive enterprise software procurement as CSRD disclosure deadlines compress. The KBA enforces transport emissions reporting that feeds into corporate carbon inventories. Stuttgart automotive suppliers deploy API-first platforms to automate Scope 3 data collection from tier-2 component manufacturers.
United States
Enterprise procurement teams embed emissions tracking into supplier contracts as EPA reporting thresholds tighten for large facilities. The Inflation Reduction Act funds industrial decarbonization programs that require continuous monitoring infrastructure. Houston petrochemical complexes and Detroit automotive plants anchor demand for real-time carbon tracking integrations.
France
Manufacturing conglomerates in Île-de-France elevate legal team involvement in software selection due to Scope 3 liability exposure. The ANSM and CNIL impose data governance requirements on environmental reporting platforms. Lyon chemical manufacturers consolidate vendor relationships around pre-certified calculation methodologies.
United Kingdom
Financial services firms in the City of London integrate carbon accounting into ESG disclosure workflows ahead of Environment Agency enforcement timelines. The UK's departure from EU frameworks creates parallel compliance obligations for exporters. Manchester industrial clusters adopt automated tools to satisfy dual regulatory reporting requirements.
India
Manufacturing exporters in Maharashtra and Gujarat face tightening factory emission norms from the Bureau of Energy Efficiency. The PLI scheme for clean technology adoption subsidizes sensor deployment for continuous monitoring. Bangalore software vendors localize DEFRA-equivalent standards to capture first-mover advantage in compliance automation.
Track Carbon Footprint App Market Competitive Landscape
Global majors compete with regional champions across API architecture and certification depth, creating a tiered structure where open-data platforms capture multi-year enterprise contracts while walled-garden competitors defend consumer subscription bases. The vendor set clusters around three archetypes: API-first infrastructure providers, behavioral engagement specialists, and blockchain-verified offset marketplaces. M&A activity concentrates on sensor data aggregators and emission factor database licensors, while strategic partnerships between carbon platforms and ERP vendors dominate competitive positioning.
Within the API-first infrastructure tier, Capture and Decarbon represent modular integration approaches that embed emissions data directly into procurement workflows. Joro occupies a distinct position among consumer-facing platforms, sustaining engagement through behavioral nudge mechanics rather than compliance automation. Karbon-X exemplifies the narrow but defensible niche of blockchain-verified voluntary carbon markets, where speculative credit price volatility demands specialized transaction infrastructure.
| Leading Market Players |
|---|
| Capture |
| Karbon-X |
| Joro |
| Decarbon |
| LiveGreen |
| Commons |
| Aerial |
| Sense |
| Klima |
| Others |
Pricing and Supply Chain Analysis
API-first platform architectures are displacing monolithic carbon accounting suites, compressing development cost structures while concentrating procurement leverage among enterprise buyers demanding embedded emissions data within existing ERP workflows. This technology shift simultaneously erodes pricing power for walled-garden competitors and rewards modular providers with multi-year contract anchoring.
Pricing Analysis
Professional services bundling separates implementation-heavy enterprise deployments from stripped-down SaaS tiers targeting mid-market procurement teams. Subscription pricing stratifies across premium API-embedded tiers, standard dashboard-access levels, and economy self-serve modules. Price differentiation rests on ISO 14064-1 certification status and pre-built SAP connector availability. Cost compression in the economy tier intensifies as open-source emission factor databases commoditize basic calculation engines. Individual consumers exhibit highest price sensitivity, while German automotive suppliers facing CSRD deadlines show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements for emission factor databases force platforms to maintain parallel DEFRA, EPA, and GHG Protocol calculation engines, inflating R&D overhead. Software development capacity concentrates in Germany, the Netherlands, and India, with Bangalore vendors localizing compliance standards for export manufacturing clients. Raw material dependencies span cloud compute infrastructure, IoT sensor hardware, and blockchain verification nodes. Single-source vulnerability runs through concentrated cloud hyperscaler regions. Distribution feeds from direct enterprise sales teams supplemented by neobank partnerships for consumer-facing modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated carbon accounting is displacing manual spreadsheet-based compliance as CSRD mandates compress disclosure timelines beyond human processing capacity. This technology transition rewards platforms with pre-certified methodologies and open API architectures.
For Market Incumbents: Deploy certification-first positioning to anchor enterprise retention as ISO 14064-1 updates create audit-format uncertainty. Prioritize backward integration into emission factor database licensing to reduce dependency on fragmented public standards. Expand professional services capacity in Stuttgart and Lyon industrial clusters where cross-functional procurement processes extend implementation timelines. For New Entrants and Emerging Players: CSRD in Germany opens a window for specialized Scope 3 supplier onboarding modules targeting mid-tier automotive component manufacturers. Capture first-mover position in India's Bureau of Energy Efficiency compliance corridor by localizing DEFRA-equivalent calculation standards. Pursue neobank partnership channels for consumer acquisition rather than direct app store competition against established behavioral engagement platforms. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP vendors seeking embedded sustainability data layers. Long-term viability favors platforms with open-data architectures over walled-garden competitors as interoperability mandates crystallize. Watch for GHG Protocol updates forcing calculation engine standardization as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedded emissions data flows directly into SAP procurement workflows, anchoring multi-year enterprise contracts. |
| Emission Factor Database Licensing | Proprietary access to DEFRA-equivalent standards creates moats against open-source commoditization pressures. |
| Neobank Distribution Partnership | Point-of-sale carbon calculations at German retail banks sustain consumer engagement beyond download spikes. |
| IoT Sensor Hardware Integration | Continuous manufacturing monitoring enables real-time intervention before emissions accrue. |
| Regulatory Certification Investment | Pre-certified ISO 14064-1 methodologies freeze procurement decisions in favor of compliant vendors. |
Research Methodology
Multi-period observation of CSRD implementation timelines, IoT sensor cost curves, and API adoption rates anchored the trend analysis, supplemented by interviews with sustainability software CTOs, enterprise procurement officers, ERP integration specialists, and neobank product managers. Secondary validation drew from SEC filings of carbon accounting platforms, EU regulatory disclosure databases, hyperscaler cloud infrastructure reports, and customs data on emissions monitoring hardware trade. Bottom-up segment sizing triangulated against top-down regulatory mandate penetration estimates.
Input-output matrices modeled deployment architecture, user segment contract values, and feature set adoption velocities across the projection horizon. Segmentation dimensions spanned application type, platform deployment model, organization size tier, and regional regulatory framework cluster. CAGRs derived from fitted adoption curves calibrated to disclosed enterprise contract values and freemium conversion benchmarks. Forecast inputs included sensor hardware cost decline trajectories and CSRD enforcement timeline acceleration scenarios.
The model assumes a particular technology adoption path; alternative pathways for blockchain-verified offset integration would alter the outlook if voluntary carbon market liquidity collapses. Forecasts reflect documented assumptions around regulatory enforcement intensity and enterprise procurement cycle durations. Deviation in GHG Protocol interoperability standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Europe Green Carbon Market