
 Europe Green Carbon Market | 2026-2036
Europe Green Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Green Carbon Market Analytics
The EU Carbon Border Adjustment Mechanism is decoupling carbon cost exposure from traditional EU-only emissions trading scope. Ørsted leverages its offshore wind dominance to anchor premium voluntary carbon credit origination in North Sea markets. Statkraft competes through hydropower-backed certificate streams that sustain baseload reliability claims for corporate buyers. Vattenfall differentiates via integrated utility-scale renewable generation paired with direct power purchase agreements.
Europe green carbon encompasses tradeable environmental commodities—including carbon credits, renewable energy certificates, and verified offsets—issued under EU-approved standards with quantified CO2-equivalent reduction metrics and third-party validation protocols. These instruments serve primary industrial and commercial purposes in compliance offsetting, scope emissions neutralization, and supply chain decarbonization reporting. Carbon credits command the deepest liquidity pools among product type segments, while blockchain-enabled verification infrastructure represents the fastest-expanding technology dimension due to traceability demands from corporate end users. Renewable energy certificates maintain mature pricing benchmarks across Nordic and German exchanges, though bioenergy-linked offsets are capturing widening margin pools as hard-to-abate sectors seek negative emissions claims.
EU Green Deal implementation through ETS phase revisions and the CSRD disclosure mandate is tightening product standard requirements for environmental commodity eligibility. ECHA oversight of voluntary offset certification schemes and national regulator enforcement by Germany's Federal Environment Agency are reshaping market access conditions across member states. Stakeholders must monitor evolving MRV protocol harmonization between EU institutions and emerging national carbon accounting frameworks to anticipate certificate fungibility constraints.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is decoupling carbon cost exposure from traditional EU-only emissions trading scope, forcing importers and domestic producers to restructure sourcing strategies around verified offset eligibility.
Growth Catalysts
- EU Green Deal ETS Phase Revisions:Tightening emissions caps under the EU Green Deal are compelling steel and cement manufacturers to accelerate verified credit purchases ahead of compliance deadlines.
- Corporate Scope 3 Reporting Mandates:CSRD disclosure requirements are expanding voluntary carbon credit demand from supply chain managers seeking auditable neutralization claims.
- North Sea Offshore Wind Cluster:Concentrated renewable generation capacity across Denmark, Germany, and the Netherlands is anchoring premium voluntary credit origination with high additionality scores.
Market Restraints
- Input Cost Volatility in Biomass Feedstocks:Agricultural residue and forestry waste prices fluctuate with harvest cycles, compressing margins for bioenergy-linked offset developers.
- Supply Concentration in Nordic Verification:Overreliance on Swedish and Norwegian certification bodies creates bottleneck risk for project validation timelines.
- Regulatory Friction from ECHA Scheme Oversight:Evolving ECHA protocols for voluntary offset eligibility are delaying project registration and increasing compliance overhead.
Strategic Opportunities
- Eastern European Project Development:Poland and Romania host underexploited landfill gas and afforestation sites with lower land acquisition costs than Western European alternatives.
- Blockchain-Enabled Verification Convergence:Distributed ledger technology paired with satellite monitoring is creating immutable traceability layers that command buyer premiums.
- Industrial Heat Decarbonization Applications:Hard-to-abate sectors including glass and chemicals manufacturing are emerging as high-willingness purchasers of technology-specific carbon removal credits.
Industry Challenges
- Specialized MRV Talent Scarcity:Shortages of certified monitoring, reporting, and verification professionals are extending project development timelines and inflating personnel costs.
- Legacy IT Integration Complexity:Enterprise carbon accounting platforms require costly reconfiguration to interface with blockchain-based certificate registries and automated retirement systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Green Carbon Market |
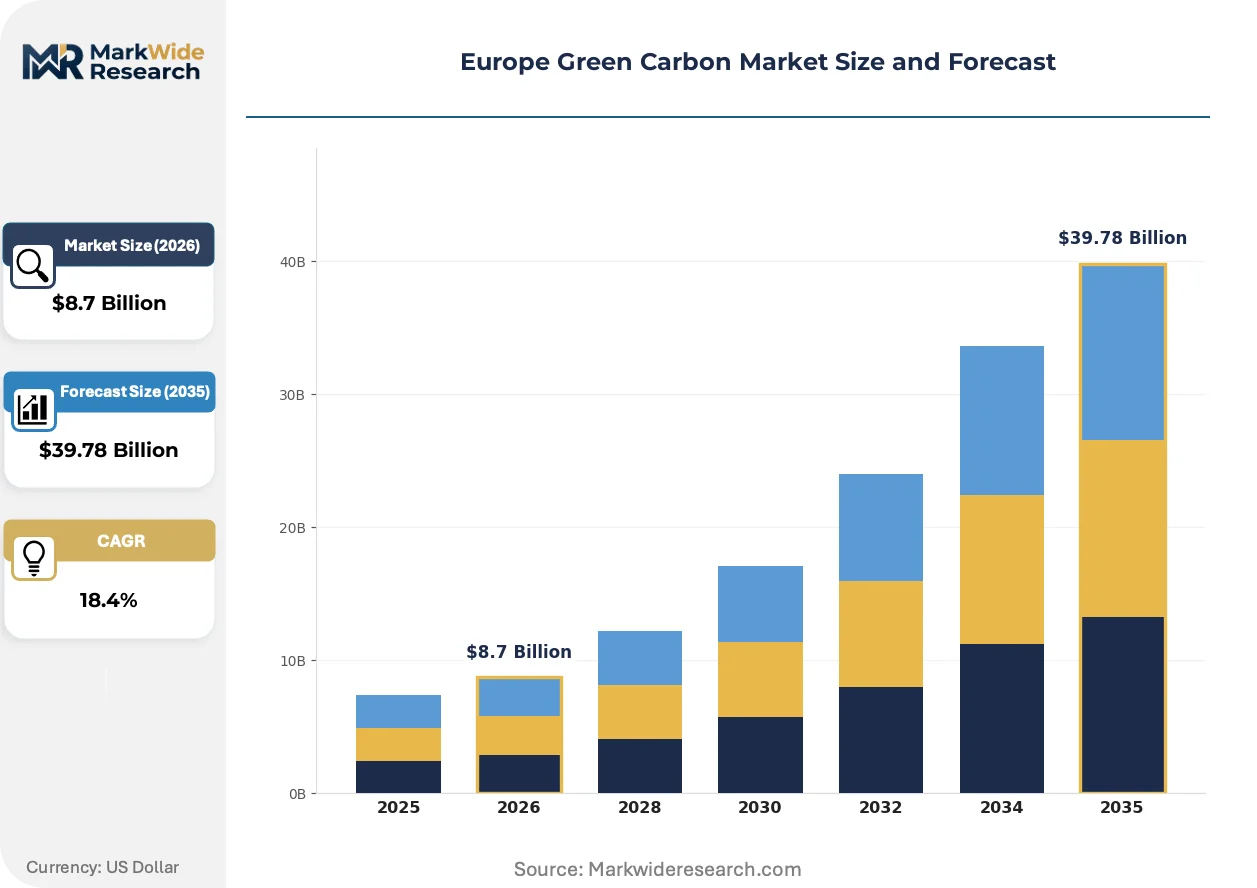
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Credits, Renewable Energy Certificates, Offsets, Environmental Commodities Technology: Blockchain, Carbon Capture, Renewable Energy, Bioenergy End User: Corporations, Government Agencies, NGOs, Energy Producers Deployment: On-Premise, Cloud-Based, Hybrid, Distributed |
| Companies Covered | Enel X, Vattenfall, Statkraft, ENGIE, Iberdrola, ACCIONA, Fortum, Ørsted, STX Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Green Carbon Market Evolving Landscape
Technology convergence between remote sensing and distributed ledger infrastructure is compressing verification cycles and enabling real-time credit retirement. Regulatory layering across EU institutions and member state agencies is fragmenting certification standards.
Blockchain-enabled verification infrastructure is automating the reconciliation of satellite-derived emission reduction data with smart contract-based certificate issuance. Major industrial buyers in steel and cement are piloting these systems to eliminate manual audit delays. The technology is automating trust mechanisms that previously required multi-month third-party validation processes, shrinking settlement windows from quarters to days.
CSRD disclosure mandates are forcing listed companies to source only EU-approved certification schemes with quantified CO2-equivalent metrics and third-party validation protocols. This regulatory tightening is disqualifying older voluntary standards and consolidating market share among ECHA-recognized bodies. German and Dutch corporate procurement teams are responding by pre-qualifying suppliers against emerging CSRD-aligned eligibility criteria ahead of full enforcement.
Corporate buyers are consolidating carbon credit procurement through direct power purchase agreements bundled with renewable energy certificates and offsets from single offtakers. This bundled contracting model is displacing spot-market credit purchases and spot REC acquisitions among large industrials. The shift is most visible across the Nordic corporate cluster, where Sweden's manufacturing sector leads in negotiating integrated decarbonization supply contracts spanning electricity, heat, and embodied emissions.
Europe Green Carbon Market Segmentation
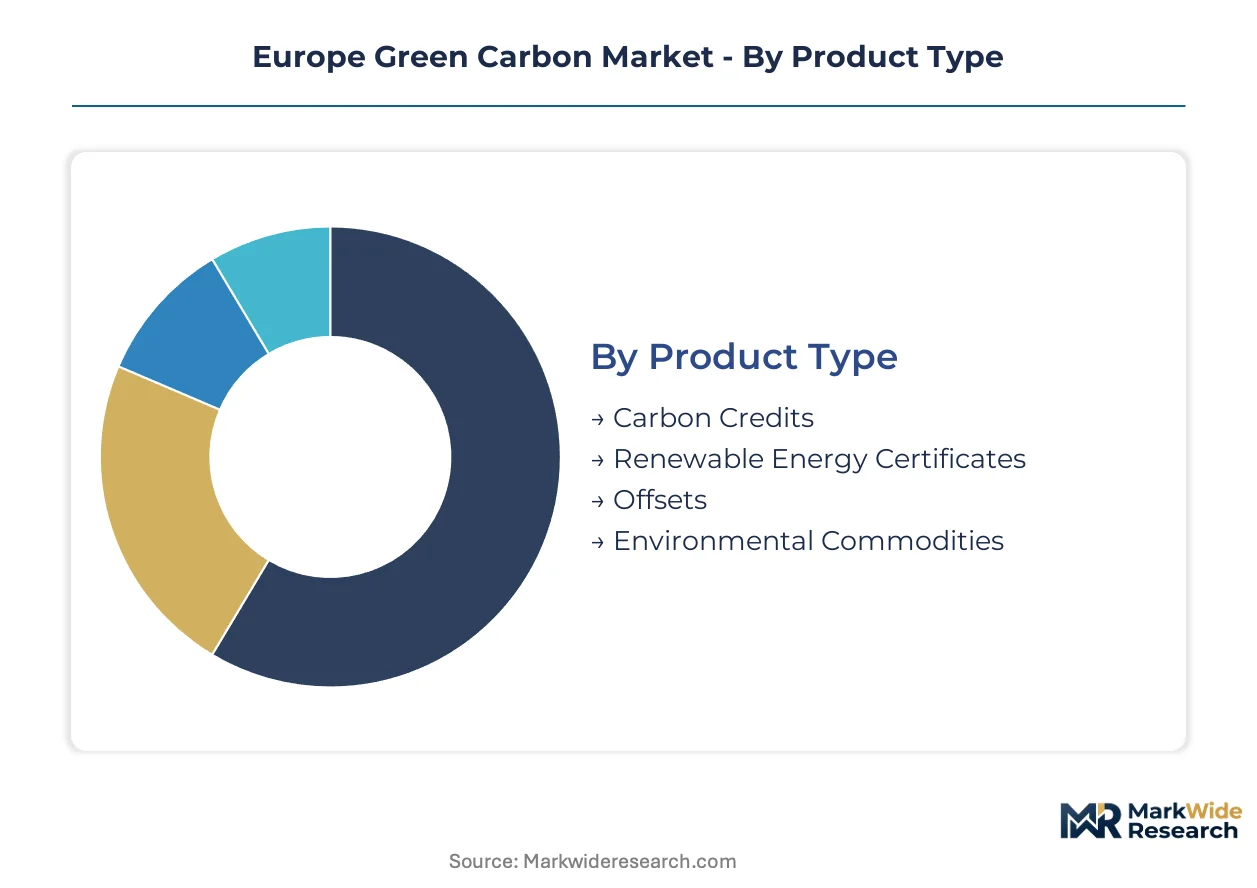
Segmentation in the Europe Green Carbon Market reveals how environmental commodities layer across compliance, voluntary, and technology-enabled use cases. Understanding these dimensions exposes where procurement budgets concentrate and which verification infrastructures command pricing premiums.
Product Type:
Standalone environmental commodities trade independently of underlying asset ownership, while embedded instruments tie directly to generation or removal projects. This distinction shapes liquidity, pricing transparency, and buyer due diligence requirements across European exchanges.
- Carbon Credits:Tradeable instruments representing one tonne of CO2-equivalent reduction or removal, verified under EU-approved standards. German steelmakers and Dutch cement manufacturers dominate procurement volumes as EU ETS phase revisions tighten compliance deadlines.
- Renewable Energy Certificates:Documentary proof of electricity generation from renewable sources, decoupled from physical power delivery. Nordic corporate buyers in Sweden, Norway, and Denmark sustain mature pricing benchmarks through bundled power purchase agreements.
- Offsets:Verified emission reduction claims from projects outside regulated cap-and-trade systems. Agricultural residue and forestry waste feedstock volatility compresses margins for bioenergy-linked offset developers.
- Environmental Commodities:Broader category encompassing bundled instruments and emerging nature-based certificates. ECHA oversight of voluntary certification schemes is reshaping eligibility criteria and market access conditions.
Carbon Credits lead volumes today; Environmental Commodities are gaining share fastest as bundled contracting displaces spot-market purchasing.
Technology:
Technology segmentation tracks how verification, generation, and removal methods differentiate on cost structure, scalability, and regulatory recognition. Maturity varies sharply—some approaches face MRV talent scarcity while others confront legacy IT integration complexity.
- Blockchain:Distributed ledger infrastructure automating certificate issuance, transfer, and retirement through smart contracts. Satellite-derived data reconciliation shrinks settlement windows from quarters to days for piloting steel and cement buyers.
- Carbon Capture:Engineered removal technologies with direct air capture and point-source applications. Hard-to-abate sectors including glass and chemicals manufacturing emerge as high-willingness purchasers of technology-specific removal credits.
- Renewable Energy:Wind, solar, and hydropower generation anchoring certificate origination. Ørsted's offshore wind dominance in North Sea markets and Statkraft's hydropower-backed streams sustain baseload reliability claims.
- Bioenergy:Biomass and biogas systems with carbon removal potential through BECCS configurations. Eastern European project developers in Poland and Romania exploit lower land acquisition costs for landfill gas and afforestation sites.
Renewable Energy leads volumes today; Blockchain is expanding most quickly as traceability demands intensify from corporate end users.
End User:
Buyer segmentation distinguishes between compliance-obligated entities, voluntary purchasers, and intermediaries with diverging risk tolerances and procurement sophistication. CSRD disclosure mandates are tightening pre-qualification criteria across all categories.
- Corporations:Industrial and commercial entities sourcing credits for compliance offsetting, scope emissions neutralization, and supply chain decarbonization reporting. German and Dutch procurement teams pre-qualify suppliers against emerging CSRD-aligned eligibility criteria.
- Government Agencies:Public sector buyers procuring offsets for operational emissions and program administration. National regulator enforcement by Germany's Federal Environment Agency shapes procurement standards.
- NGOs:Non-governmental organizations facilitating carbon finance and project development in underserved geographies. These actors bridge verification capacity gaps in Eastern European markets.
- Energy Producers:Utilities and independent generators monetizing environmental attributes alongside electricity sales. Vattenfall differentiates through integrated utility-scale renewable generation paired with direct power purchase agreements.
Corporations lead volumes today; Energy Producers are climbing the fastest as bundled contracting consolidates procurement channels.
Deployment:
Infrastructure segmentation captures how certificate registries, MRV systems, and trading platforms distribute across physical and cloud architectures. This shapes interoperability with enterprise carbon accounting platforms and automated retirement systems.
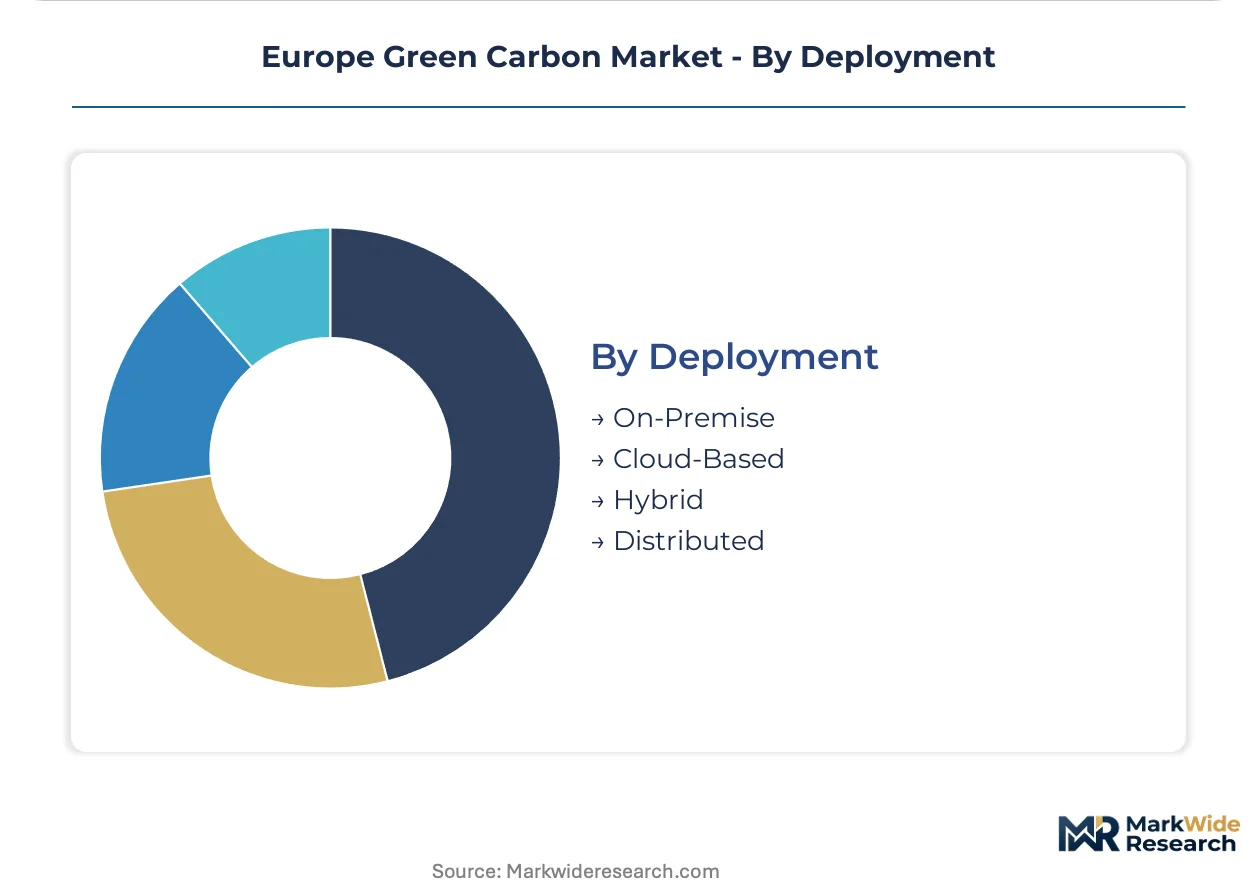
- On-Premise:Locally hosted registry and verification systems maintained by established certification bodies. Overreliance on Swedish and Norwegian validation creates bottleneck risk for project registration timelines.
- Cloud-Based:Scalable infrastructure enabling real-time data ingestion from remote sensing and IoT monitoring networks. Satellite monitoring convergence commands buyer premiums through immutable traceability layers.
- Hybrid:Mixed architectures combining localized verification with cloud-based trading and retirement. This configuration balances regulatory data residency requirements against scalability needs.
- Distributed:Fully decentralized systems leveraging peer-to-peer validation and blockchain-native settlement. Emerging protocols challenge incumbent registry operators on cost and speed dimensions.
On-Premise leads volumes today; Cloud-Based is gaining share fastest as enterprise carbon accounting platforms demand API-native integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized monitoring, reporting, and verification professionals cluster around North Sea offshore wind developments and Nordic hydropower corridors. These talent concentrations anchor project origination capacity and certification throughput across the region's most active environmental commodity markets.
Germany
Federal Environment Agency enforcement tightens eligibility criteria for voluntary offset schemes entering compliance markets. Steelmakers in the Ruhr industrial basin accelerate credit purchases ahead of EU ETS phase deadlines. Berlin-based procurement teams pre-qualify suppliers against emerging CSRD-aligned standards before full mandate enforcement.
Netherlands
Rotterdam port operators restructure import sourcing around Carbon Border Adjustment Mechanism compliance requirements. Cement manufacturers dominate verified credit procurement volumes as domestic production faces intensifying carbon cost exposure. The North Sea offshore wind cluster anchors premium voluntary credit origination with high additionality scores.
Sweden
Manufacturing sector buyers lead negotiated integrated decarbonization supply contracts spanning electricity, heat, and embodied emissions. National certification bodies concentrate project validation capacity, creating potential bottleneck risk for timeline-sensitive developers. Stockholm-corridor corporate procurement sustains mature renewable energy certificate pricing benchmarks.
Denmark
Ørsted leverages offshore wind dominance to anchor premium voluntary carbon credit origination in regional markets. Copenhagen-based energy traders bundle power purchase agreements with environmental commodities for industrial offtakers. Danish project developers exploit lower North Sea installation costs compared to alternative European sites.
Poland
Landfill gas and afforestation project developers exploit lower land acquisition costs than Western European alternatives. National carbon accounting frameworks diverge from EU MRV protocol harmonization, creating certificate fungibility constraints. Warsaw-based intermediaries bridge verification capacity gaps for emerging project pipelines.
Europe Green Carbon Market Competitive Landscape
The competitive structure tilts toward integrated utility-scale generators with captive renewable portfolios and direct corporate offtake relationships. Market concentration favors players combining generation assets with environmental commodity origination capabilities. Three archetypes dominate: state-affiliated energy majors with Nordic hydropower dominance, offshore wind specialists with North Sea installation scale, and trading houses with bundled procurement platforms. Capacity expansion into Eastern European project development and strategic partnerships for blockchain-enabled verification infrastructure represent the primary competitive moves reshaping positioning.
Within the state-affiliated energy major tier, Vattenfall and Statkraft occupy positions combining generation scale with corporate procurement channel control. Ørsted represents the offshore wind specialist archetype, anchoring premium voluntary credit origination through North Sea asset concentration. Among trading-oriented intermediaries, STX Group exemplifies the bundled contracting model displacing spot-market transactions. These three players collectively illustrate how vertical integration into generation, certification, and offtake negotiation creates defensive positioning against regulatory tightening and margin compression in standardized credit categories.
| Leading Market Players |
|---|
| Enel X |
| Vattenfall |
| Statkraft |
| ENGIE |
| Iberdrola |
| ACCIONA |
| Fortum |
| Ørsted |
| STX Group |
| Others |
Value Network & Pricing Analysis
Backward integration into captive renewable generation anchors both supply security and pricing power for Nordic utilities competing against trading-house intermediaries. German steelmakers and Dutch cement manufacturers face divergent cost structures depending on whether they source through bundled power purchase agreements or spot-market credit acquisitions.
Pricing Analysis
Bundled contracting of electricity, renewable energy certificates, and carbon offsets commands premium positioning over unbundled spot-market transactions. Pricing stratifies across premium, standard, and economy tiers based on certification grade—ECHA-recognized schemes with CSRD alignment versus legacy voluntary standards—and volume scale of offtake agreements. Cost compression in standard-tier credits is intensifying because blockchain-enabled verification infrastructure is automating previously labor-intensive MRV processes. Corporate procurement teams in Germany and the Netherlands exhibit highest price sensitivity due to compliance deadline pressures, while Nordic manufacturing buyers demonstrate lowest sensitivity given bundled contract security.
Supply Chain Analysis
Logistics and freight costs for biomass feedstock transport from Eastern European collection points to Western European processing facilities are compressing developer margins. Supply concentration centers on Sweden, Norway, and Denmark for certification body capacity; Germany and the Netherlands for corporate offtake demand; and Poland and Romania for project origination. Raw material dependencies include agricultural residue, forestry waste, and landfill gas capture equipment. Single-source vulnerability in Nordic verification creates bottleneck risk for timeline-sensitive developers. Distribution runs through direct power purchase agreements with integrated utilities, displacing spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the Europe Green Carbon Market rests on blockchain-enabled verification cost reduction and the shift toward premium-tier bundled contracts with CSRD-aligned certification.
For Market Incumbents: Anchor defensive positioning through exclusive offtake relationships with hard-to-abate sectors including glass and chemicals manufacturing. Deepen backward integration into Eastern European project development in Poland and Romania to secure lower-cost feedstock supply. Certification investment in ECHA-recognized schemes with CSRD alignment represents the critical lever against regulatory disqualification of legacy standards. For New Entrants and Emerging Players: Capture white-space opportunity in cloud-based MRV infrastructure serving enterprise carbon accounting platforms requiring API-native integration. Poland and Romania present the most penetrable geographies given lower land acquisition costs and underexploited landfill gas and afforestation sites. A technology-specific go-to-market angle pairing satellite monitoring with distributed ledger verification commands buyer premiums through immutable traceability claims. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented project developers lack captive offtake channels and certification body relationships. Long-term viability favors integrated players combining generation assets with environmental commodity origination capabilities. The acquisition target archetype comprises Eastern European project pipelines with ECHA-aligned certification progress. Blockchain-verification adoption rates among German and Dutch corporate buyers signal inflection toward premium-tier pricing capture.| Strategic Initiative | Industry Significance |
|---|---|
| Eastern European Project Development | Poland and Romania landfill gas sites exploit lower land acquisition costs than Western alternatives. |
| Blockchain-Enabled Verification Infrastructure | Smart contract automation shrinks settlement windows from quarters to days for steel buyers. |
| CSRD-Aligned Certification Investment | ECHA-recognized schemes secure eligibility as legacy standards face regulatory disqualification. |
| Bundled Power Purchase Agreements | Integrated contracts spanning electricity, heat, and embodied emissions displace spot-market purchasing. |
| Direct Corporate Offtake Relationships | Exclusive supply contracts with hard-to-abate sectors lock in premium pricing tiers. |
Research Methodology
Coverage spans Western Europe and Eastern Europe, with primary inputs from each regional cluster combining structured interviews with utility planning officers, corporate sustainability directors, certification body validation leads, and blockchain infrastructure developers. Secondary validation draws from EU ETS registry data, ECHA scheme documentation, CSRD implementation guidance, and national carbon accounting framework disclosures. Bottom-up project pipeline assessment and top-down regulatory impact modeling enable triangulation across data sources.
Rate-of-change decomposition separates volume expansion from price evolution across the analysis window. Segmentation dimensions modeled include product type, verification technology, end-user category, and deployment architecture. CAGRs derive from regression against EU Green Deal implementation milestones, ETS phase revision schedules, and CSRD enforcement timelines. Industry-specific forecast inputs incorporate offshore wind capacity buildout trajectories in the North Sea and hydropower generation baselines across Nordic corridors.
Regulatory timeline acceleration, feedstock price volatility, and MRV talent scarcity are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding ECHA protocol harmonization and corporate procurement pre-qualification behavior. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Carbon Dioxide Market