
 Europe Carbon Dioxide Market | 2026-2036
Europe Carbon Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Carbon Dioxide Market Analytics
CE marking for food-grade industrial gases is collapsing the supplier base as smaller distributors fail to meet purity documentation and traceability mandates. Linde plc leverages its pipeline network across the Rhine-Ruhr industrial belt to sustain bulk delivery contracts with chemical manufacturers. Air Liquide S.A. anchors its position through on-site production agreements at major beverage bottling facilities in France and Benelux.
Carbon dioxide is a colorless, odorless gas with a concentration of 99.9% purity required for food and beverage applications, produced via steam methane reforming, fermentation of agricultural biomass, or capture from ammonia and ethylene oxide plants. Its primary industrial purpose spans inerting, pressurization, pH control in water treatment, and as a supercritical solvent in extraction processes. Fermentation-derived CO2 captures expanding margin pools as breweries and bioethanol plants monetize waste streams under EU emissions trading incentives. Enhanced oil recovery in the North Sea basin competes with chemical processes for high-volume offtake, though greenhouse cultivation in the Netherlands and Spain is scaling fastest among emerging demand segments.
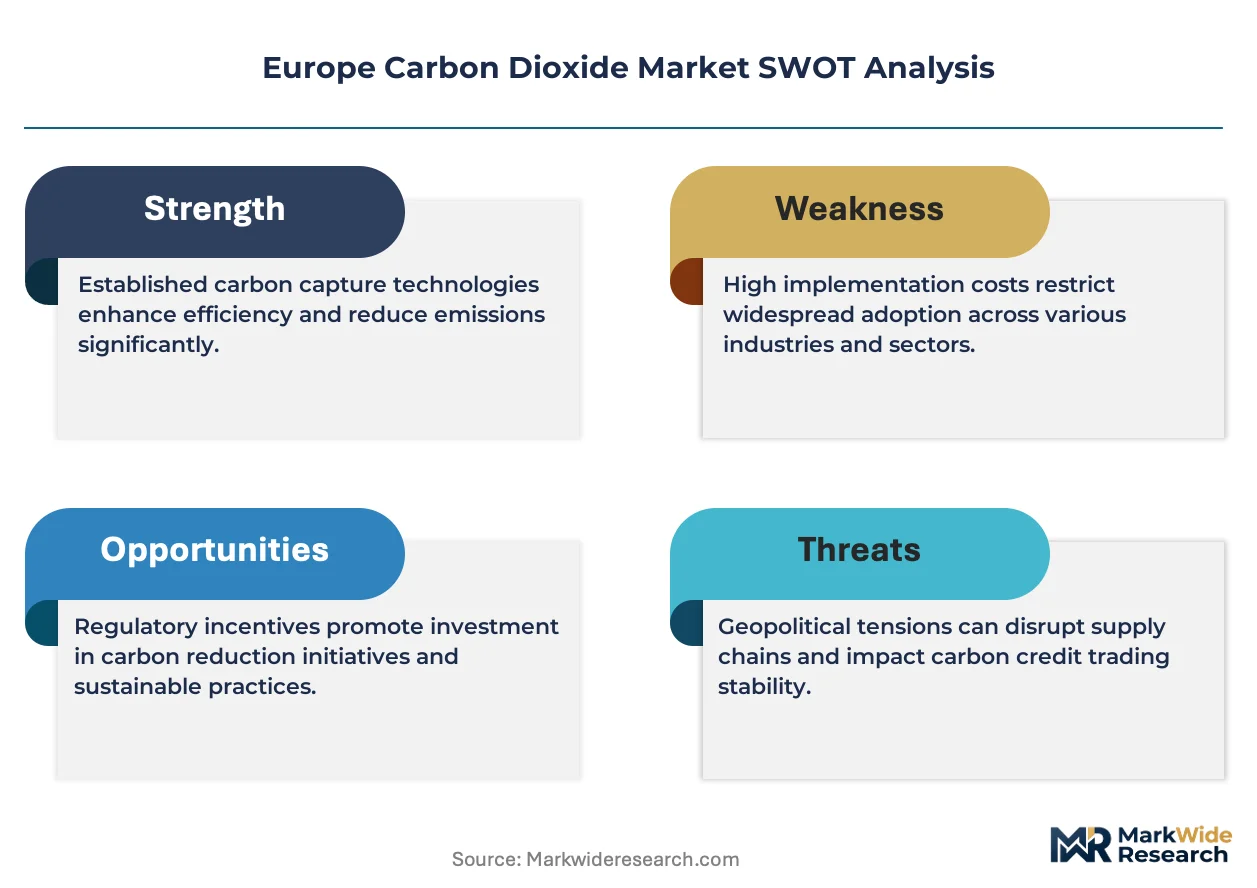
The EU Green Deal and F-Gas Regulation shape product standards by mandating lifecycle emissions disclosure and penalizing fossil-derived CO2 in certain end uses, while ECHA REACH compliance adds registration burdens for importers. Germany's Federal Environment Agency enforces national allocation plans that tighten free carbon allowances for steam methane reforming operators. Buyers must monitor how the EU Carbon Border Adjustment Mechanism redefines cost structures for imported CO2 and whether national biomethane strategies expand fermentation feedstock availability.
Market Dynamics
CE marking mandates for food-grade industrial gases are compressing the supplier base across Europe, forcing distributors to invest in purity documentation systems or exit the market entirely.
Growth Catalysts
- F-Gas Regulation phase-down:The EU F-Gas Regulation is accelerating demand for recovered CO2 streams as synthetic refrigerant alternatives face supply constraints.
- Greenhouse cultivation expansion:Controlled-environment agriculture in the Netherlands and Spain is scaling CO2 enrichment systems for year-round vegetable production.
- Biomass fermentation monetization:Bioethanol plants and breweries across Germany and France are capturing waste CO2 under EU emissions trading incentives.
Market Restraints
- Natural gas price volatility:Steam methane reforming feedstock costs swing with TTF benchmark fluctuations, squeezing margins for merchant CO2 producers.
- Rhine-Ruhr supply concentration:Pipeline-dependent bulk delivery locks smaller buyers into Linde plc's network with limited alternative sourcing.
- Ammonia plant sourcing dependence:Merchant CO2 supply ties to fertilizer production cycles, creating seasonal availability gaps.
Strategic Opportunities
- Direct air capture integration:Emerging DAC facilities in Iceland and Norway could supply fossil-independent CO2 for EU chemical processes.
- Carbon Border Adjustment Mechanism positioning:Early certification of low-carbon CO2 streams creates preference for EU-sourced material over imports.
- Modular on-site generation:Small-scale electrolysis-coupled CO2 systems serve remote beverage bottlers outside pipeline corridors.
Industry Challenges
- CE marking documentation burden:Food-grade certification requires batch-level traceability systems that strain mid-tier distributor IT infrastructure.
- Cross-border transport licensing:ADR regulations for pressurized gas tankers create friction for spot market transactions between member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Carbon Dioxide Market |
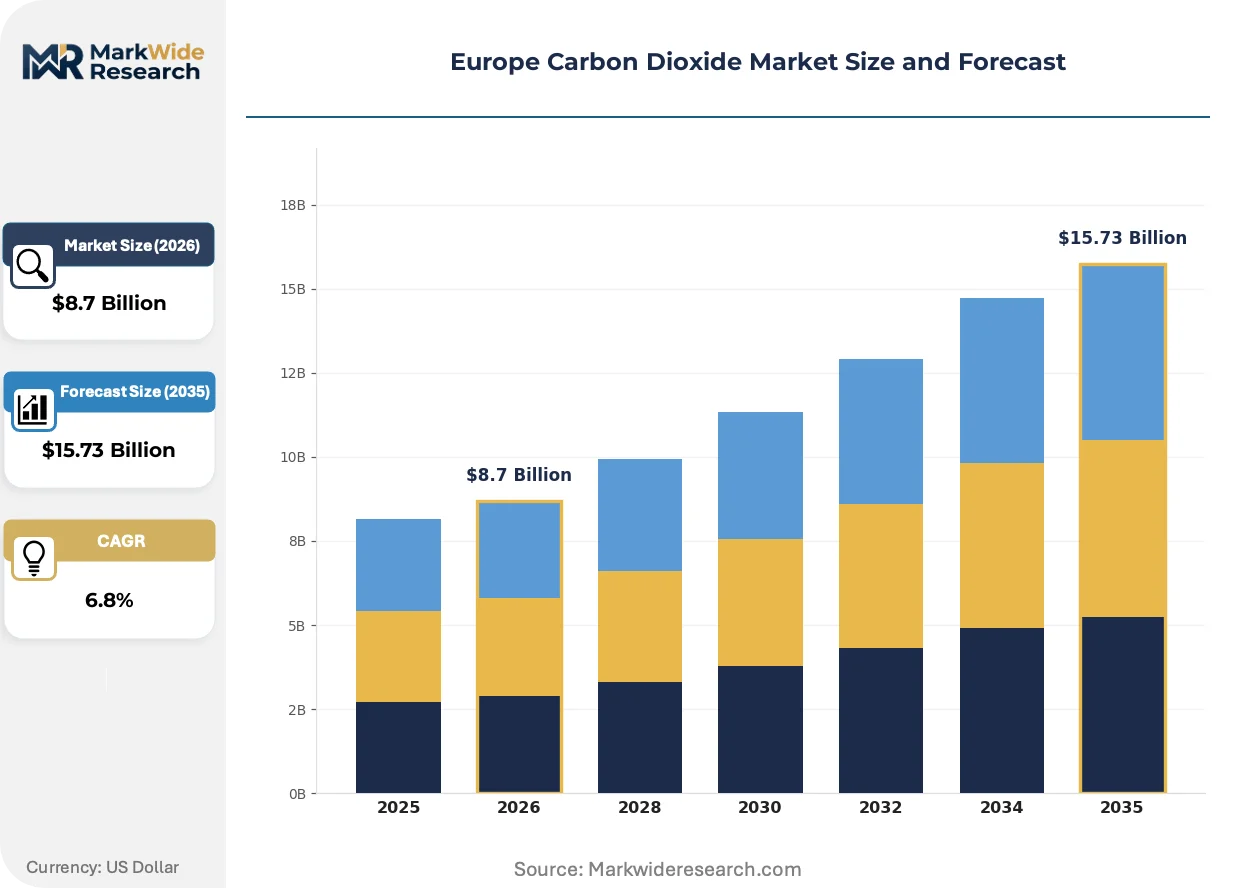
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Gasification, Fermentation, Biomass Conversion End User: Food & Beverage, Oil & Gas, Chemical Manufacturing, Metal Fabrication Application: Carbonated Drinks, Enhanced Oil Recovery, Greenhouse Cultivation, Chemical Processes Distribution Channel: Direct Sales, Wholesale Distribution, Online Sales, Retail |
| Companies Covered | Air Liquide S.A., Ellenbarrie Industrial Gases Limited, Linde plc, The Linde Group, Acail Gas, SOL Group, Taiyo Nippon Sanso Corporation, The Messer Group GmbH, Messer SE & Co. KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Carbon Dioxide Market Evolving Landscape
Carbon dioxide sourcing is bifurcating between pipeline bulk for industrial clusters and distributed on-site generation for remote demand nodes, reshaping capital deployment across the value chain.
Membrane separation technology for biogas upgrading is fragmenting the traditional CO2 supply architecture. Agricultural anaerobic digesters in Denmark and the Netherlands are installing selective permeation systems to isolate food-grade CO2 from methane streams. Small-scale biogas operators now compete with reforming giants for regional beverage contracts, compressing pricing power in rural supply zones.
The EU Green Deal's lifecycle emissions disclosure mandate is forcing product-level carbon accounting. Industrial gas distributors must now document Scope 3 footprints for every CO2 batch sold into chemical and food applications. German chemical manufacturers are responding by demanding certified renewable-origin certificates, shifting procurement criteria from purity grades to emissions intensity scores.
Spot market purchasing is displacing annual take-or-pay contracts among mid-sized greenhouse operators. Dutch horticulture cooperatives are aggregating demand through digital procurement platforms, bypassing traditional distributor relationships. This aggregation model concentrates buyer power in the Benelux corridor while fragmenting supplier access to price-sensitive volume.
Europe Carbon Dioxide Market Segmentation
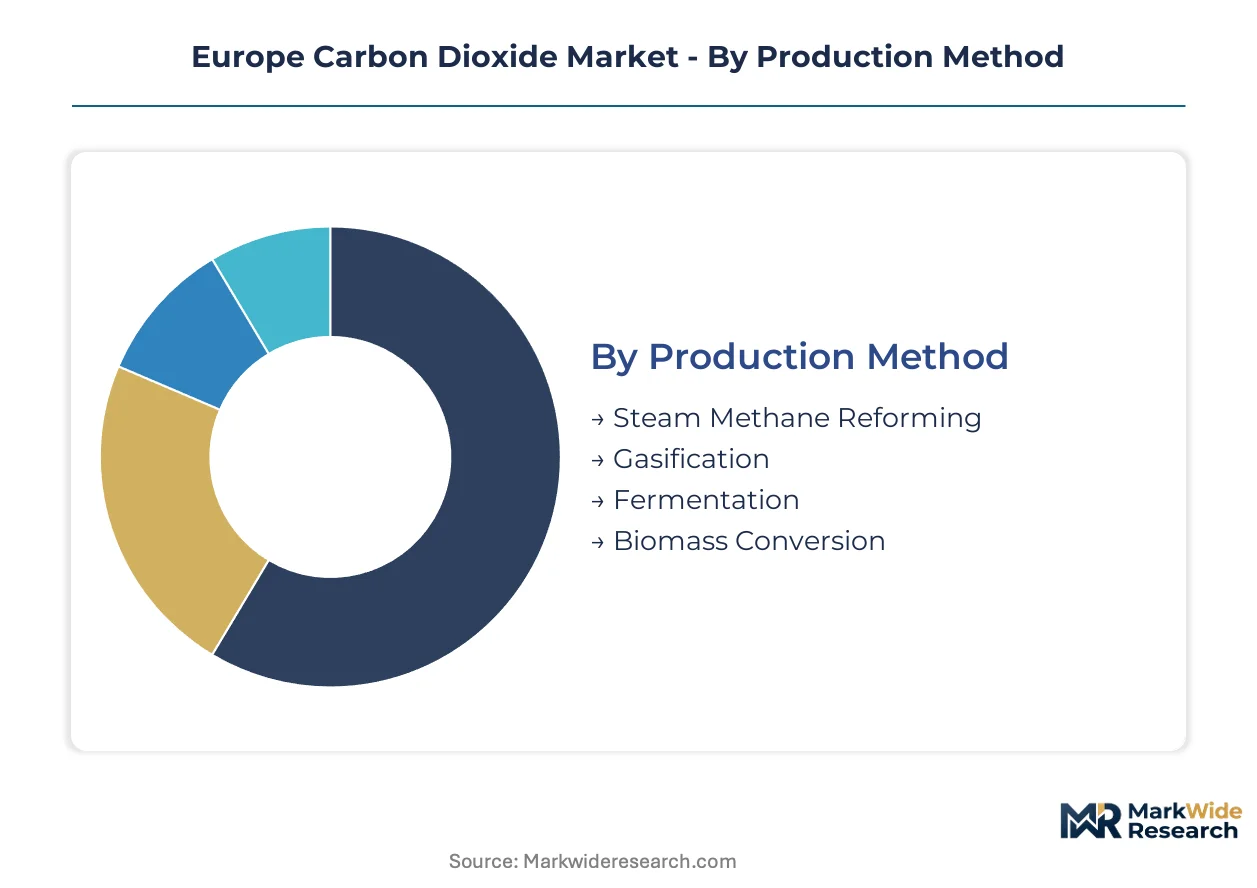
CO2 sourcing strategies diverge sharply across production methods and end-use applications, with regulatory pressure on carbon intensity forcing buyers to requalify suppliers against EU Green Deal disclosure mandates. Segmentation reveals where biomass-derived streams can command premium positioning against conventional reforming output.
Production Method:
Fermentation-derived CO2 faces the weakest substitution threat as EU emissions trading incentives lock in brewery and bioethanol plant offtake, while steam methane reforming confronts rising carbon cost exposure under Germany's national allocation plans.
- Steam Methane Reforming:Natural gas feedstock conversion yields high-purity CO2 at industrial scale, with output tied to hydrogen and ammonia production cycles. German chemical corridor demand from BASF and Rhine-Ruhr clusters absorbs the bulk of merchant supply, though TTF price volatility squeezes producer margins and seasonal fertilizer turnarounds create availability gaps.
- Fermentation:Brewery and bioethanol waste stream capture delivers food-grade CO2 with negative emissions credentials under EU ETS frameworks. French bioethanol plants and German brewing facilities are monetizing vented CO2 through purification upgrades, capturing margin pools that reforming cannot match as carbon border adjustments phase in.
- Gasification:Coal and petroleum coke feedstock conversion produces syngas-derived CO2 for chemical synthesis applications, concentrated in Polish and Czech industrial zones with legacy asset bases.
- Biomass Conversion:Agricultural residue and energy crop processing generates renewable CO2 streams eligible for EU renewable energy directive compliance, scaling in Denmark and the Netherlands through anaerobic digester coupling.
Steam methane reforming retains volume leadership; fermentation holds the steepest expansion curve.
End User:
Margin structures vary dramatically by customer sophistication, with chemical manufacturers demanding certified lifecycle documentation while metal fabricators prioritize spot price competitiveness.
- Food & Beverage:Carbonated drink bottlers and cold-chain operators require 99.9% purity with full CE marking traceability. Benelux beverage facilities are consolidating procurement through on-site production agreements, bypassing traditional merchant supply.
- Chemical Manufacturing:BASF and German chemical corridor operators consume bulk CO2 for urea, methanol, and specialty chemical synthesis, with procurement shifting toward certified renewable-origin certificates.
- Oil & Gas:North Sea enhanced oil recovery operations compete with chemical processes for high-volume offtake, though greenhouse gas storage mandates are compressing project economics.
- Metal Fabrication:Shielding gas and laser cutting applications in Italian and Spanish manufacturing zones source lower-grade CO2 through wholesale distributors with limited purity documentation requirements.
Chemical manufacturing commands the largest contract values; food and beverage is climbing fastest on carbon-accounting premiums.
Application:
Volume concentration in mature applications is fragmenting as Dutch and Spanish greenhouse operators aggregate demand through digital platforms.
- Carbonated Drinks:Pressurization and dissolution for beverage carbonation demands food-grade certification with batch-level purity documentation. German and French bottlers are installing on-site generation to escape Rhine-Ruhr pipeline dependency.
- Enhanced Oil Recovery:Injection into depleted North Sea reservoirs for tertiary extraction competes with chemical feedstock demand, though CCS project pipelines are redirecting CO2 toward permanent storage.
- Greenhouse Cultivation:CO2 enrichment for year-round vegetable production in Dutch and Spanish controlled-environment agriculture is scaling fastest among demand segments, with cooperatives bypassing traditional distributors.
- Chemical Processes:pH control, inerting, and supercritical solvent extraction across German and Italian chemical manufacturing absorbs steady merchant volumes.
Enhanced oil recovery dominates absolute consumption; greenhouse cultivation is gaining share fastest on horticulture automation.
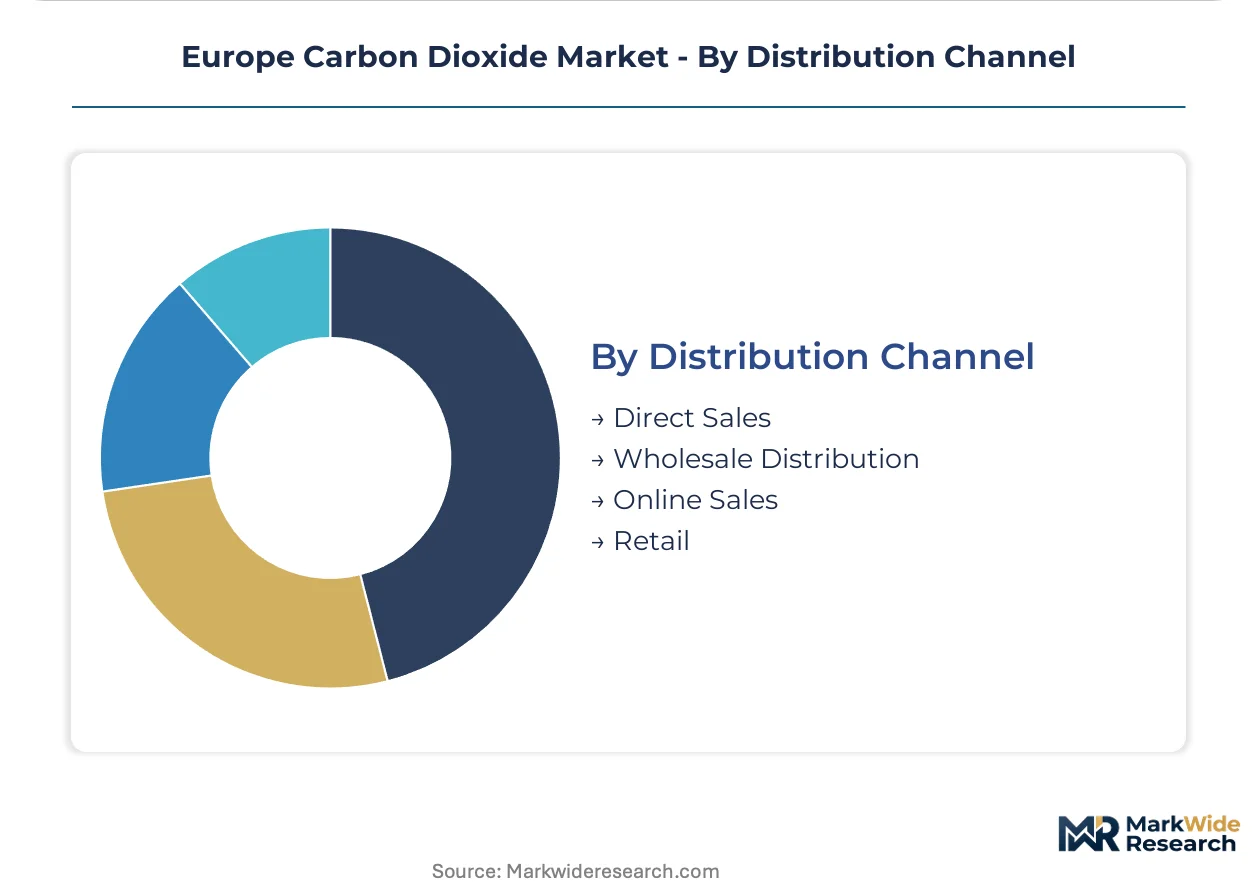
Distribution Channel:
Channel selection tracks buyer scale and pipeline proximity, with bulk contracts concentrating in industrial clusters and remote nodes driving modular on-site adoption.
- Direct Sales:Pipeline-connected bulk delivery to Rhine-Ruhr chemical manufacturers and North Sea EOR installations locks in Linde plc network relationships with limited spot market access.
- Wholesale Distribution:Mid-tier beverage bottlers and metal fabricators in Italy and Spain source through regional distributors facing CE marking documentation burdens.
- Online Sales:Digital procurement platforms are aggregating Dutch greenhouse cooperative demand, fragmenting supplier pricing power in rural Benelux supply zones.
- Retail:Small-volume cylinder sales to welding shops and hospitality operators in fragmented Southern European markets.
Direct sales captures the contract value pool; online sales is expanding most quickly on platform aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical manufacturers and beverage bottlers concentrate demand in industrial clusters across the continent, with regulatory pressure from Brussels reshaping procurement criteria toward certified low-carbon sourcing.
Germany
BASF and Rhine-Ruhr chemical corridor operators anchor bulk CO2 offtake for urea and methanol synthesis. The Federal Environment Agency enforces national allocation plans that tighten free carbon allowances for steam methane reforming operators. Pipeline networks from Linde plc dominate bulk delivery to North Rhine-Westphalia manufacturing zones.
France
Benelux beverage bottlers and Paris-region food processors drive food-grade CO2 demand with stringent CE marking requirements. The F-Gas Regulation accelerates phase-down of synthetic refrigerants, pushing cold-chain operators toward recovered CO2 streams. Bioethanol plants in the Grand Est region monetize fermentation-derived CO2 under EU emissions trading incentives.
Netherlands
Dutch horticulture cooperatives scale controlled-environment agriculture with CO2 enrichment systems for year-round vegetable production. ECHA REACH compliance adds registration burdens for imported CO2, favoring domestic biomass conversion from anaerobic digesters. Rotterdam industrial clusters compete with greenhouse operators for regional supply.
Spain
Almería and Murcia greenhouse complexes represent the fastest-expanding demand segment for agricultural CO2 enrichment. Metal fabricators in Catalonia and the Basque Country source shielding gas through wholesale distributors with limited purity documentation. The EU Green Deal lifecycle disclosure mandate forces Spanish chemical processors to requalify suppliers.
Italy
Carbonated drink bottlers in Lombardy and Emilia-Romagna expand production lines requiring 99.9% purity certification. CE marking mandates compress the supplier base as mid-tier distributors fail to meet traceability requirements. Milan-Turin industrial zones anchor metal fabrication demand for lower-grade CO2 applications.
Europe Carbon Dioxide Market Competitive Landscape
Player mix skews toward integrated industrial gas conglomerates with pipeline infrastructure and captive reforming assets. Consolidation around Rhine-Ruhr bulk delivery networks limits spot market access for smaller buyers. Three archetypes dominate: pipeline-integrated majors, fermentation-coupled regional specialists, and modular on-site system providers. Competitive moves center on strategic partnerships with bioethanol producers and capacity expansion into greenhouse cultivation corridors.
Within the integrated industrial gas tier, Linde plc and Air Liquide S.A. exemplify pipeline-dependent market presence, while The Messer Group GmbH occupies a position among mid-scale European specialists. Taiyo Nippon Sanso Corporation represents Japanese-origin industrial gas capability with European operational footprint. These anchors illustrate how geographic infrastructure control and fermentation feedstock access determine competitive positioning under tightening EU carbon accounting rules.
| Leading Market Players |
|---|
| Air Liquide S.A. |
| Ellenbarrie Industrial Gases Limited |
| Linde plc |
| The Linde Group |
| Acail Gas |
| SOL Group |
| Taiyo Nippon Sanso Corporation |
| The Messer Group GmbH |
| Messer SE & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Seven-day inventory buffers at Rhine-Ruhr chemical clusters compress spot market liquidity and amplify Linde plc's pricing power over bulk contract renewals. This lead-time concentration locks smaller buyers into pipeline-dependent sourcing while fermentation-derived CO2 from Benelux bioethanol plants commands carbon-accounting premiums.
Pricing Analysis
Cost-plus contracts indexed to TTF natural gas benchmarks dominate steam methane reforming supply, with quarterly adjustment clauses passing feedstock volatility through to German chemical manufacturers. Pricing stratifies across food-grade CE-marked certification, industrial purity grades, and uncertified metal fabrication supply, with carbon intensity scores emerging as a price differentiation driver under EU Green Deal disclosure mandates. Cost compression in reforming-derived volumes is intensifying because German national allocation plans are tightening free carbon allowances. Greenhouse cooperatives in the Netherlands exhibit highest price sensitivity through digital platform aggregation, while North Sea enhanced oil recovery operators show lowest sensitivity due to project-specific long-term offtake structures.
Supply Chain Analysis
Rhine-Ruhr pipeline corridors constitute the primary chokepoint, with Linde plc's bulk delivery network controlling merchant CO2 flows to North Rhine-Westphalia chemical manufacturers. Supply concentrates in Germany, the Netherlands, and France, with raw material dependencies on natural gas feedstock, agricultural biomass for fermentation, and ammonia plant byproduct streams. Single-source vulnerability runs through ammonia production cycles that create seasonal availability gaps during fertilizer turnarounds. Distribution runs through pipeline bulk for industrial clusters, wholesale distributors for mid-tier beverage bottlers, and modular on-site generation for remote greenhouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: CE marking mandates and EU Green Deal disclosure requirements erect compliance barriers that smaller distributors cannot scale, cementing incumbent positions.
For Market Incumbents: Secure fermentation feedstock partnerships with Grand Est bioethanol plants and Rhine-Ruhr brewing facilities to lock in negative-emissions supply streams before carbon border adjustments phase in. Expand pipeline capacity into Dutch horticulture corridors to capture greenhouse cultivation growth outside traditional chemical offtake. Defend against modular on-site generation threats by offering carbon-accounting certification services that distributed systems cannot replicate. For New Entrants and Emerging Players: Differentiate on fossil-independent sourcing by deploying direct air capture or biogas upgrading technology to serve chemical manufacturers demanding renewable-origin certificates. Target Spanish Almería greenhouse complexes and Italian Lombardy beverage bottlers as penetrable segments where pipeline infrastructure remains underdeveloped. Pursue cooperative procurement platforms in Benelux horticulture as the go-to-market angle, aggregating fragmented demand to achieve minimum viable scale. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to monetize captive CO2 production assets as standalone industrial gas operations. Long-term viability hinges on positioning for EU emissions trading framework evolution and biomethane strategy expansion across member states. Monitor German Federal Environment Agency allocation plan revisions as the signal indicating when fermentation-derived supply will achieve structural cost advantage over reforming output.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Captures negative-emissions margin pools from Grand Est bioethanol plants under EU ETS incentives. |
| CE Marking Certification Investment | Collapses competitor base by forcing mid-tier distributors out of food-grade supply. |
| Pipeline Expansion into Greenhouse Corridors | Locks in Dutch and Spanish horticulture demand before modular on-site systems achieve scale. |
| Carbon Border Adjustment Mechanism Positioning | Creates preference for EU-sourced low-carbon CO2 over imported reforming output. |
| Digital Procurement Platform Development | Aggregates fragmented Benelux greenhouse demand to concentrate buyer negotiating power. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with industrial gas procurement managers, bioethanol plant operations directors, Dutch horticulture cooperative buyers, and ECHA regulatory affairs specialists; and secondary validation through customs trade data, Cefic chemical industry reports, EU ETS transaction registries, and SEC filings from listed industrial gas conglomerates. Bottom-up volume estimates from production facility capacities triangulated against top-down demand segmentation from end-use application analysis.
Across the analysis window, the forecasting framework modeled production method splits, end-user industry concentrations, application demand trajectories, and distribution channel evolution. CAGRs derived from weighted average growth assumptions across fermentation expansion rates, reforming capacity constraints, and greenhouse cultivation automation adoption. Industry-specific inputs included TTF natural gas price band scenarios and EU national allocation plan tightening schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation trajectory or biomethane feedstock availability expansion would require recalibration. Forecasts reflect documented assumptions regarding carbon border adjustment phase-in timing and F-Gas Regulation enforcement intensity. Practitioners should keep alternative scenarios live as German Federal Environment Agency allocation plan revisions and Dutch anaerobic digester capacity buildouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Verification Market