
 Asia-Pacific Carbon Footprint Management Market | 2026-2036
Asia-Pacific Carbon Footprint Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Carbon Footprint Management Market Analytics
Cloud-native emissions accounting is fragmenting legacy enterprise software architectures across Asia-Pacific industrial corridors. Schneider Electric SE leverages its energy management heritage to anchor carbon tracking within factory automation deployments. SAP SE sustains platform dominance by embedding Scope 1-3 calculations directly into ERP workflows. IBM Corporation competes through AI-powered supply chain decarbonization tools that process multi-tier supplier data.
Carbon footprint management encompasses the measurement, reporting, and reduction of greenhouse gas emissions across organizational operations and value chains, typically quantified in CO2-equivalent units using ISO 14064-1 protocols and GHG Protocol Corporate Standards. The practice serves industrial and commercial entities seeking to satisfy investor ESG mandates, regulatory disclosure rules, and supply chain qualification criteria. Software solutions lead the service type dimension, capturing recurring revenue from enterprise clients requiring real-time emissions dashboards and automated regulatory filings. Cloud-based technology deployment outpaces on-premises installation as manufacturers and retailers prioritize scalable infrastructure with lower upfront capital commitment. Energy management applications command the largest application share, though carbon reporting functionality is accelerating fastest as jurisdictions across the region mandate standardized disclosure formats.
China's MEE enforces dual carbon compliance timelines that compel state-owned enterprises to deploy certified emissions monitoring systems. Australia's Clean Energy Regulator and Japan's METI administer parallel disclosure frameworks that shape product certification requirements and market access conditions for platform vendors. South Korea's MFDS-aligned green taxonomy and India's BIS energy efficiency labeling extend this regulatory mosaic. Stakeholders must monitor divergence between national carbon accounting standards and emerging cross-border disclosure mechanisms to anticipate integration costs and certification gaps.
Market Dynamics
China's dual carbon enforcement timeline compresses enterprise software procurement cycles as state-owned manufacturers face mandatory Scope 3 disclosure deadlines. The region's regulatory fragmentation forces platform vendors to engineer multi-jurisdictional compliance architectures simultaneously.
Growth Catalysts
- Japan's METI Guidelines:Corporate net-zero commitments in automotive and electronics sectors drive premium carbon accounting software procurement with real-time dashboard requirements.
- Scope 3 Mandates:Tier-1 manufacturers across Asia-Pacific industrial corridors compel supplier network digitization, expanding addressable market for multi-tier emissions tracking platforms.
- Cloud Infrastructure:Scalable SaaS deployment models reduce upfront capital barriers for mid-market manufacturers in South Korea and Southeast Asia.
Market Restraints
- Standard Divergence:China's GB carbon accounting protocols diverge from Australia's NGER measurement frameworks, forcing vendors to maintain parallel certification pathways.
- Data Silo Fragmentation:Legacy ERP systems in Japanese heavy industry resist API integration with modern emissions tracking platforms.
- Specialized Talent Scarcity:Shortage of certified carbon accountants capable of reconciling ISO 14064-1 with national disclosure formats constrains implementation velocity.
Strategic Opportunities
- India's BIS Energy Labeling:Mandatory efficiency disclosure for industrial equipment creates entry point for integrated carbon-energy management platforms.
- Blockchain Verification:Immutable supplier emissions attestation addresses Scope 3 audit trail gaps in complex electronics supply chains.
- Vietnam Manufacturing Corridor:Underpenetrated export-oriented textile and footwear producers face EU CBAM exposure, requiring rapid compliance infrastructure deployment.
Industry Challenges
- Multi-Tier Data Integration:SME suppliers lack standardized EDI capabilities, forcing manual emissions data collection across three-to-four-tier supply networks.
- Retrofit Complexity:Brownfield industrial facilities require sensor hardware installation alongside software deployment, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Carbon Footprint Management Market |
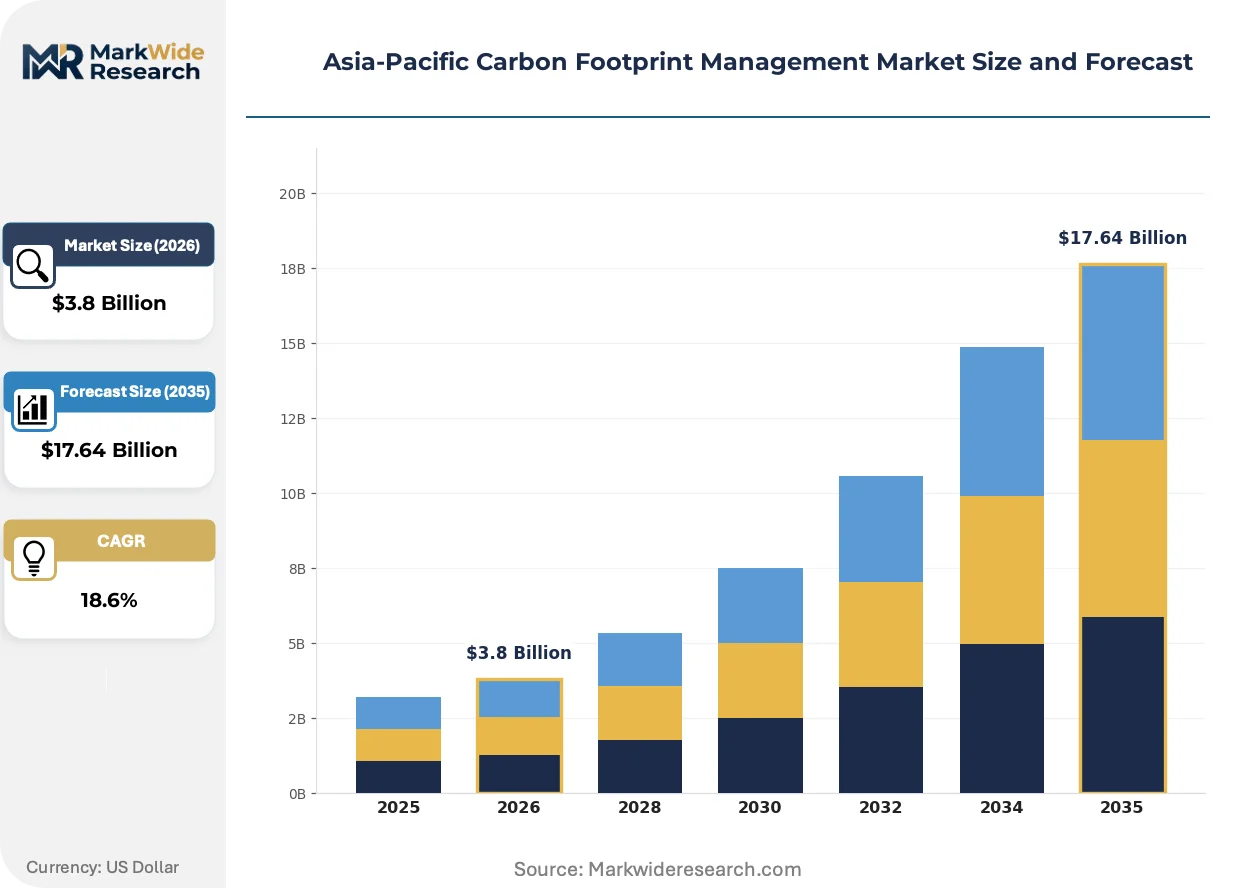
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Software, Implementation, Training End User: Manufacturers, Retailers, Government, Transportation Application: Energy Management, Carbon Reporting, Compliance, Incident Management Technology: Cloud-Based, On-Premises, Mobile Applications, IoT Solutions |
| Companies Covered | Schneider Electric SE, SAP SE, IBM Corporation, Salesforce, Inc., ENGIE, Dakota Software Corporation, IsoMetrix, Intelex Technologies, ULC, Wolters Kluwer NV, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Carbon Footprint Management Market Evolving Landscape
Artificial intelligence and edge computing architectures are compressing emissions measurement latency from monthly reporting cycles to real-time operational feedback. Platform vendors engineer predictive carbon forecasting modules that anticipate regulatory threshold breaches before they crystallize.
Edge-native sensor networks is hybridizing factory-floor energy monitoring with automated carbon intensity calculations. Steel and cement producers in China's Shandong and Jiangsu provinces deploy these systems to satisfy MEE continuous emissions monitoring mandates. The convergence eliminates batch-mode data reconciliation, collapsing reporting lag from weeks to minutes.
Australia's mandatory climate-related financial disclosure regime forces ASX-listed entities to publish audited Scope 1-3 inventories from fiscal year 2024-25. Mining and energy majors accelerate procurement of TGA-aligned assurance platforms to satisfy auditor scrutiny. The disclosure standard propagates through supplier qualification criteria, compelling mid-tier service providers to adopt certified tracking infrastructure.
Buyer procurement committees now embed carbon performance clauses directly into vendor selection scorecards, displacing price-only evaluation frameworks. Japanese automotive assemblers weight supplier emissions transparency at 15-20 percent of contract award criteria. The practice concentrates most visibly in battery supply chain qualification, where cathode material provenance documentation determines market access.
Asia-Pacific Carbon Footprint Management Market Segmentation
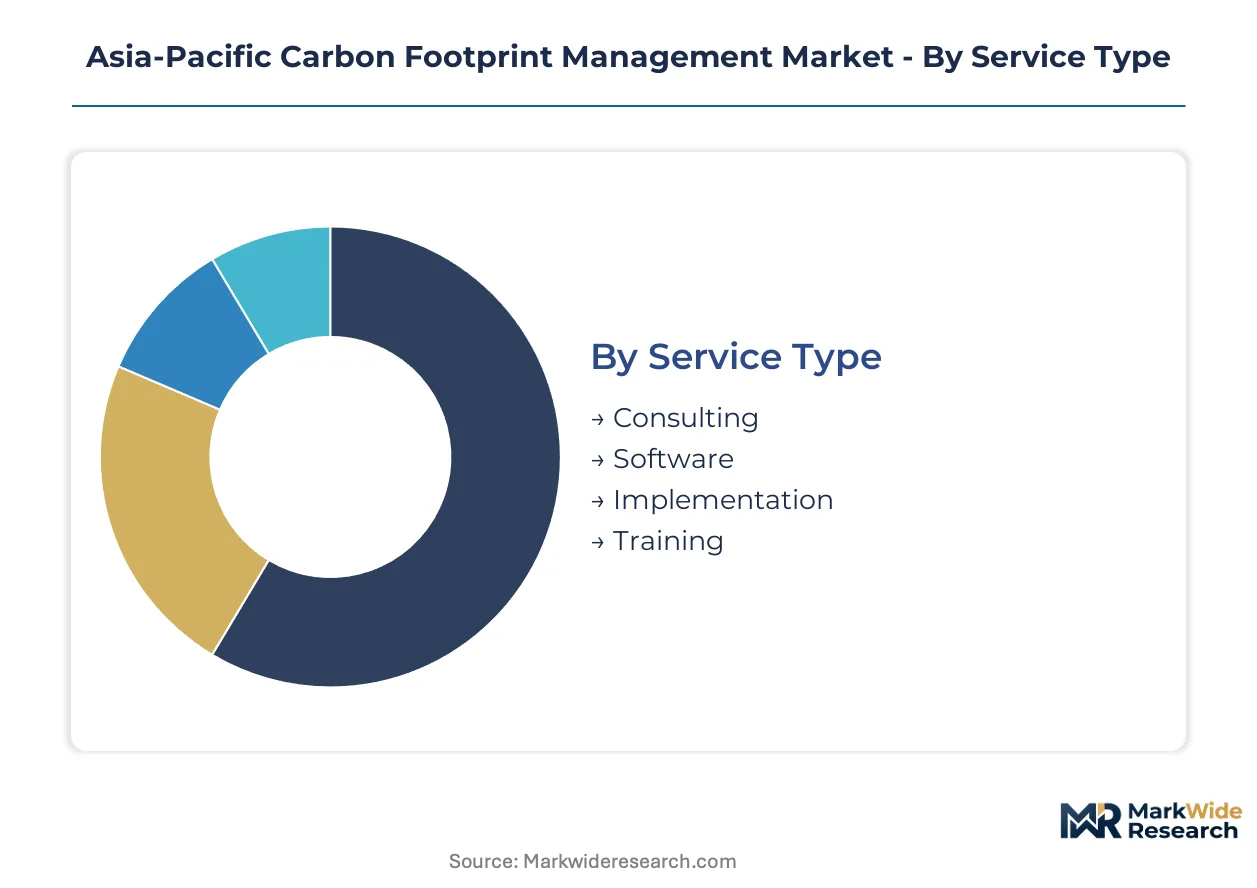
Carbon footprint management platforms fragment across service delivery modes, deployment architectures, and regulatory use cases. Each segmentation axis reveals distinct procurement patterns across Asia-Pacific industrial corridors.
Service Type:
Mature consulting offerings coexist with emerging software-as-a-service models as enterprises shift from advisory to embedded emissions infrastructure.
- Software:Cloud-native platforms automate Scope 1-3 calculations using ISO 14064-1 protocols and GHG Protocol Corporate Standards. Japanese automotive assemblers and Australian mining majors procure real-time dashboards with automated regulatory filing modules. Software handles the majority of throughput; Implementation is the fastest mover on share.
- Consulting:Advisory services span emissions baseline establishment, reduction pathway design, and third-party verification preparation. China's state-owned enterprises engage Big Four firms to navigate MEE dual carbon compliance timelines. Consulting contracts concentrate in heavy industry where brownfield complexity demands bespoke methodology.
- Implementation:System integration services deploy sensor hardware, API connections to legacy ERP, and multi-tier supplier data onboarding. South Korean electronics manufacturers drive demand for rapid deployment teams capable of bridging IT-OT convergence.
- Training:Certification programs develop internal carbon accounting competency to satisfy auditor scrutiny under Australia's TGA-aligned assurance frameworks. Shortage of certified practitioners constrains program scaling.
Software commands recurring revenue premiums; Implementation contracts expand most quickly as retrofit demand accelerates.
End User:
Procurement authority concentrates in manufacturing supply chains where Scope 3 disclosure mandates cascade through tiered supplier networks.
- Manufacturers:Steel, cement, and electronics producers deploy integrated energy-carbon platforms to satisfy China's MEE continuous monitoring mandates and Japan's METI disclosure guidelines. Factory automation heritage vendors anchor carbon tracking within SCADA deployments. Manufacturers absorb the majority of platform investment; Transportation is climbing the fastest on procurement priority lists.
- Retailers:Consumer goods distributors track product-level carbon intensity to satisfy EU CBAM exposure and ESG investor mandates. Australian supermarket chains weight supplier emissions transparency in vendor scorecards.
- Government:National regulators procure verification infrastructure and public disclosure platforms. India's BIS energy efficiency labeling expansion drives public-sector platform procurement.
- Transportation:Aviation and maritime carriers face accelerating fuel reporting requirements under emerging regional frameworks. Fleet telematics integration with carbon intensity calculations represents nascent procurement category.
Manufacturing dominates current deployment; Transportation procurement is expanding most steeply as fuel disclosure rules tighten.
Application:
Functional priority shifts from operational efficiency to audit-ready compliance documentation as mandatory disclosure regimes proliferate.
- Energy Management:Real-time monitoring of electricity, fuel, and process heat consumption with automated carbon intensity conversion. China's Shandong and Jiangsu province steel producers deploy edge-native sensor networks to collapse reporting lag from weeks to minutes. Energy Management retains the largest installed base; Carbon Reporting is gaining share fastest.
- Carbon Reporting:Standardized disclosure generation aligned with jurisdiction-specific formats including Australia's NGER and Japan's METI guidelines. ASX-listed entities accelerate procurement of TGA-aligned assurance platforms.
- Compliance:Threshold monitoring and automated alert systems for regulatory breach prevention. State-owned enterprises under China's dual carbon timeline prioritize predictive forecasting modules.
- Incident Management:Emissions anomaly detection and corrective action workflow automation. Cement producers deploy these capabilities to manage continuous emissions monitoring system alerts.
Energy Management anchors current deployment; Carbon Reporting functionality is expanding most rapidly as mandatory disclosure deadlines approach.
Technology:
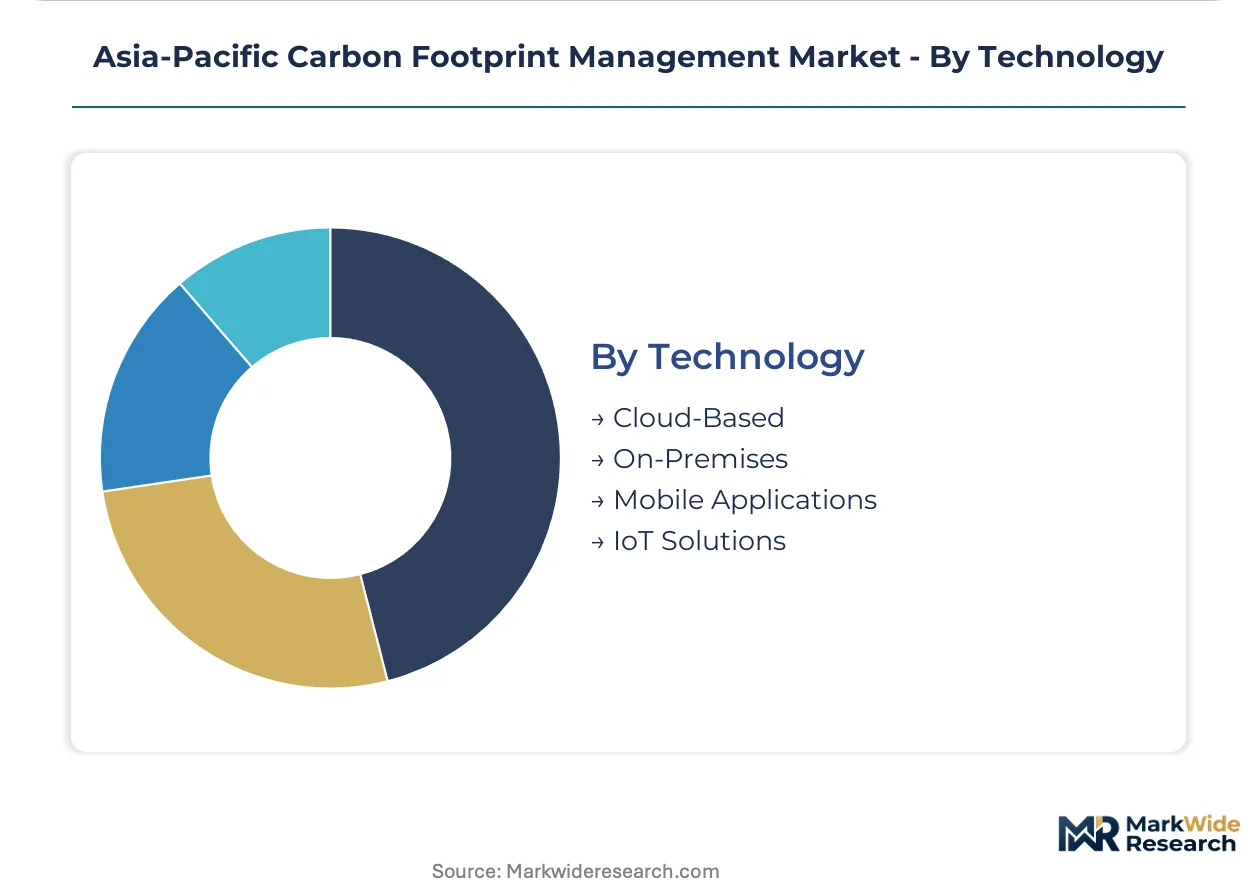
Deployment architecture preference shifts decisively toward scalable infrastructure with minimal upfront capital commitment.
- Cloud-Based:Multi-tenant SaaS platforms with API ecosystems for ERP and supplier network integration. South Korean and Southeast Asian mid-market manufacturers prioritize subscription models over capital expenditure. Cloud-Based infrastructure dominates new procurement; IoT Solutions is expanding most quickly at the edge.
- On-Premises:Air-gapped installations for defense-sensitive or data sovereignty-constrained operations. Japanese heavy industry maintains legacy preferences though hybrid architectures are displacing pure on-site deployment.
- Mobile Applications:Field technician access to emissions dashboards and supplier data capture interfaces. Mining operations across Australia's Pilbara region deploy ruggedized devices for remote asset monitoring.
- IoT Solutions:Edge-native sensor networks with embedded carbon calculation logic. Steel and cement producers in China's industrial clusters deploy these systems to satisfy MEE continuous monitoring mandates with minute-level latency.
Cloud-Based platforms capture the majority of new contracts; IoT Solutions at the factory edge is expanding most steeply as real-time monitoring mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon accounting platform procurement concentrates in export-oriented manufacturing corridors where Scope 3 disclosure mandates cascade from European and North American buyers. State-owned enterprises and tier-1 suppliers dominate software licensing volumes across the region.
China
Steel and cement producers in Shandong and Jiangsu provinces deploy edge-native sensor networks to satisfy MEE continuous emissions monitoring mandates. The dual carbon enforcement timeline compresses procurement cycles for state-owned manufacturers facing mandatory Scope 3 deadlines. Real-time carbon intensity calculations now operate at minute-level latency in industrial clusters.
Japan
Automotive assemblers weight supplier emissions transparency at 15-20 percent of contract award criteria under METI guidelines. Electronics manufacturers drive premium software procurement with real-time dashboard requirements. Corporate net-zero commitments in the Kanto and Kansai industrial corridors anchor regional demand for certified tracking infrastructure.
Australia
ASX-listed mining and energy majors accelerate procurement of TGA-aligned assurance platforms to satisfy mandatory climate-related financial disclosure rules from fiscal year 2024-25. The Clean Energy Regulator administers parallel disclosure frameworks that shape product certification requirements. Disclosure standards propagate through supplier qualification criteria across the Pilbara mining region.
South Korea
Electronics manufacturers drive demand for rapid deployment teams capable of bridging IT-OT convergence in carbon accounting integration. The MFDS-aligned green taxonomy shapes enterprise investment in emissions tracking infrastructure. Mid-market manufacturers in the Seoul Capital Area prioritize scalable SaaS deployment models over capital expenditure.
India
Mandatory BIS energy efficiency labeling for industrial equipment creates entry points for integrated carbon-energy management platforms. State-owned enterprises engage consulting firms to navigate complex disclosure requirements. The Delhi-NCR and Maharashtra industrial corridors concentrate early procurement of cloud-native emissions accounting systems.
Asia-Pacific Carbon Footprint Management Market Competitive Landscape
On the supply side, the industry is consolidating around platform vendors with embedded ERP integration capabilities and energy management heritage. Three strategic archetypes dominate: factory automation heritage players anchoring carbon tracking within SCADA deployments, enterprise software providers embedding Scope 1-3 calculations into existing workflows, and AI-powered supply chain specialists processing multi-tier supplier data. Competitive moves concentrate on API ecosystem expansion and multi-jurisdictional compliance architecture engineering.
Among Europe-based industrial technology conglomerates, Schneider Electric SE exemplifies the factory automation heritage archetype, while SAP SE occupies a position within the enterprise software tier. IBM Corporation represents the AI-powered supply chain specialization vector. These three anchors demonstrate how carbon accounting functionality converges with established operational technology and information technology infrastructure rather than displacing it.
| Leading Market Players |
|---|
| Schneider Electric SE |
| SAP SE |
| IBM Corporation |
| Salesforce, Inc. |
| ENGIE |
| Dakota Software Corporation |
| IsoMetrix |
| Intelex Technologies, ULC |
| Wolters Kluwer NV |
| Others |
Value Network & Pricing Analysis
The Shanghai-Singapore maritime corridor's freight cost volatility compresses margin structures for carbon accounting platform vendors sourcing sensor hardware from East Asian electronics clusters. Supply concentration in China's Jiangsu and Guangdong provinces amplifies pricing power for edge-native IoT component suppliers, while downstream buyers in Australia's mining sector and Japan's automotive industry absorb tiered SaaS subscription premiums based on API integration complexity.
Pricing Analysis
Technology-generation pricing gaps separate cloud-native SaaS platforms from legacy on-premises installations and emerging edge-AI carbon tracking modules. The dominant pricing structure runs through three-tier SaaS subscriptions calibrated to data volume tiers and regulatory filing automation depth. Price differentiation centers on ISO 14064-1 certification level and real-time dashboard customization scope. Cost compression in the mid-market tier intensifies as South Korean and Southeast Asian manufacturers demand scalable deployment without enterprise capital commitment. Mid-market manufacturers in India's industrial corridors exhibit the highest price sensitivity, while Japanese automotive assemblers prioritize audit-ready compliance functionality over cost optimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for carbon accounting hardware vendors assembling edge sensor networks. Component sourcing concentrates in China, South Korea, and Taiwan for semiconductor modules, precision sensors, and industrial-grade connectivity hardware. Raw material dependencies rest on rare earth elements for sensor magnetics, high-purity silicon for edge computing chips, and lithium-ion cells for remote monitoring deployments. Single-source vulnerability in advanced sensor fabrication creates chokepoint exposure when MEE mandates accelerate procurement timelines. Distribution runs through direct enterprise sales teams for large manufacturers and regional systems integrators for mid-market penetration across Southeast Asian industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent carbon accounting platforms face substitution pressure from vertically integrated factory automation vendors embedding emissions tracking within SCADA deployments at marginal cost. Defense of recurring revenue streams requires strategic repositioning against this bundled-service threat.
For Market Incumbents: Pre-empt displacement by factory automation heritage players through API ecosystem expansion that locks ERP integration depth SAP and IBM currently command. Invest in ISO 14064-1 auditor certification programs to create switching costs against Schneider Electric's energy management bundling. Vertical integration into edge sensor hardware manufacturing in South Korea reduces dependency on Chinese component suppliers and accelerates deployment velocity for Australia's TGA-aligned assurance deadlines.
For New Entrants and Emerging Players: Build out blockchain-verified supplier emissions attestation services targeting Vietnam's textile and footwear export corridor facing EU CBAM exposure. Vietnam's manufacturing clusters represent the most penetrable geography due to compliance infrastructure gaps and limited incumbent presence. A channel partnership model with regional freight forwarders and customs brokers provides low-cost customer acquisition leverage against direct enterprise sales approaches.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors AI-powered supply chain specialists with demonstrated multi-tier data integration capabilities over pure-play carbon accounting software. Long-term viability in this market hinges on sustained regulatory fragmentation across Asia-Pacific jurisdictions that prevents platform commoditization. Acquisition targets should demonstrate established API connections to legacy Japanese ERP systems and METI-aligned disclosure automation. The signal to watch is consolidation velocity among Australia's mining sector procurement committees as mandatory climate disclosure deadlines approach.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Deepens ERP integration moats against Schneider Electric's factory automation bundling in Japanese automotive supply chains. |
| Edge Sensor Hardware Integration | Accelerates deployment timelines for China's MEE continuous monitoring mandates in Shandong steel clusters. |
| Blockchain Verification Partnership | Addresses Scope 3 audit trail gaps in Vietnam's electronics export corridor facing EU CBAM compliance pressure. |
| Auditor Certification Programs | Creates switching costs under Australia's TGA-aligned assurance frameworks for ASX-listed mining majors. |
| Regional Systems Integrator Network | Penetrates mid-market manufacturers in South Korea's Seoul Capital Area through localized deployment expertise. |
Research Methodology
Operator-level perspectives from sustainability officers at tier-1 manufacturers, carbon accounting software procurement leads, MEE compliance consultants, and TGA-aligned assurance auditors anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed industrial technology vendors, MEE enforcement bulletins, METI disclosure guideline updates, and customs data on carbon tracking hardware imports. Bottom-up triangulation across deployment volume estimates and top-down cross-checks against enterprise software spending patterns ensured methodological rigor.
Scenario-bracketing framed the analytical approach across the analysis window, with sensitivity testing for regulatory acceleration scenarios in China and compliance deadline shifts in Australia. Segmentation dimensions modeled include service delivery mode, deployment architecture, end-user industry vertical, and regional regulatory cluster complexity. CAGRs derived from fitted growth curves applied to disclosed customer acquisition metrics and expansion revenue rates reported by platform vendors. Industry-specific forecast inputs incorporated MEE dual carbon enforcement timeline probability assessments and METI guideline revision tracking.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by factory automation heritage vendors or sudden regulatory harmonization across Asia-Pacific jurisdictions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Market