
 Carbon Capture and Utilization Market | 2026-2036
Carbon Capture and Utilization Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Capture and Utilization Market Insights
The EU Green Deal's industrial decarbonization targets is broadening the addressable base for carbon capture and utilization systems across European heavy industry. Linde plc leverages its cryogenic gas separation expertise to anchor large-scale project development in refining and chemicals corridors. Shell plc competes through integrated carbon management platforms that extend from capture through transport and storage or utilization endpoints. Mitsubishi Heavy Industries, Ltd. dominates amine-based absorption system deliveries to power generation and cement clients across Asia and Europe.
Carbon capture and utilization encompasses engineered systems that separate CO2 from industrial flue streams or ambient air through chemical absorption, solid adsorption, membrane separation, or cryogenic distillation, then compress and purify the captured stream for downstream use in enhanced oil recovery, synthetic fuel synthesis, chemical feedstock production, or permanent geological sequestration. Absorption technology leads installed capacity due to decades of operational maturity in natural gas processing and ammonia production, while membrane separation represents the fastest-growing segment as polymer and inorganic membrane materials improve selectivity and reduce pressure-drop penalties in modular deployment configurations. Synthetic fuels command attention as the product type with concentrated margin pools, given aviation and maritime offtake agreements that price low-carbon drop-in fuels at substantial premiums over conventional kerosene and bunker fuel.
The European Commission's F-Gas Regulation and REACH framework shape equipment standards and chemical handling protocols for capture solvents and refrigerants used in cryogenic systems, while the EPA in the United States enforces New Source Performance Standards that mandate CO2 monitoring and control at new power generation and industrial facilities. Japan's METI coordinates national CCUS roadmaps that align demonstration project funding with JIS equipment certification requirements for domestic suppliers. Stakeholders must monitor how carbon border adjustment mechanisms and evolving 45Q tax credit rules in North America reshape project economics and cross-border equipment sourcing decisions.
Market Dynamics
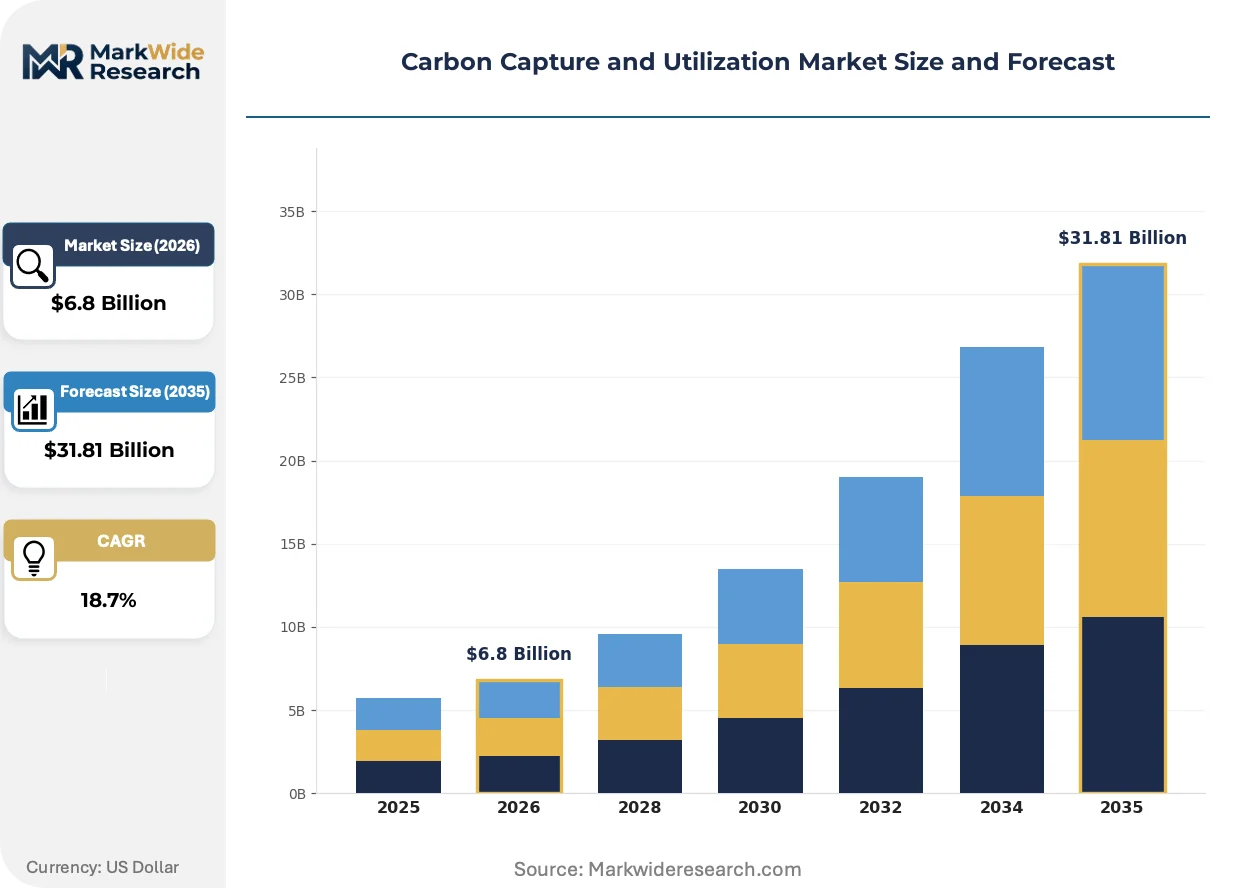
The EU Green Deal's binding industrial decarbonization mandates are compressing payback periods for carbon capture installations across European heavy industry, while direct air capture technology advances steadily reduce energy penalties per ton of CO2 separated from ambient air.
Growth Catalysts
- EU Green Deal mandates:Binding decarbonization targets for cement and steel producers are mandating CCU deployment across German, Dutch, and Norwegian industrial corridors.
- Carbon pricing frameworks:The EU Emissions Trading System and national carbon taxes in the Netherlands and Norway are improving project economics for capture-to-fuel pathways.
- Synthetic fuel offtake:Aviation and maritime sectors are contracting low-carbon drop-in fuels at substantial premiums over conventional kerosene and bunker fuel.
Market Restraints
- Energy cost volatility:Capture systems require substantial thermal and electrical input, exposing operators to natural gas and power price swings in European markets.
- Solvent supply concentration:Amine-based absorption chemicals rely on concentrated petrochemical feedstock suppliers in Germany and the Netherlands.
- Storage infrastructure gaps:Permanent geological sequestration requires pipeline networks and certified reservoirs concentrated in Norway and the North Sea region.
Strategic Opportunities
- Polish industrial corridor:Cement and chemicals clusters in Silesia remain underpenetrated for CCU deployment relative to Western European benchmarks.
- Membrane-cryogenic convergence:Hybrid separation systems combining polymer membrane selectivity with cryogenic distillation purity targets are opening modular deployment models.
- 45Q tax credit alignment:North American incentive structures are creating cross-border equipment sourcing opportunities for European engineering firms.
Industry Challenges
- Process integration engineering:Retrofitting capture skids onto existing cement kilns and refinery crackers requires custom heat integration without disrupting continuous operations.
- REACH compliance timelines:Novel capture solvents face extended ECHA registration and toxicity assessment periods before commercial deployment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Capture and Utilization Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Absorption, Adsorption, Membrane Separation, Cryogenic Distillation Product Type: CO2 Enhanced Oil Recovery, Carbonated Beverages, Fertilizers, Synthetic Fuels End User: Power Generation, Cement Production, Chemicals, Oil & Gas Application: Industrial Processes, Waste Management, Greenhouse Gas Mitigation, Renewable Energy |
| Companies Covered | Exxon Mobil Corporation, Linde plc, Shell plc, Fluor Corporation, Mitsubishi Heavy Industries, Ltd., Climeworks, Carbon Engineering, LanzaTech, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Capture and Utilization Market Trends and Innovations
Technology convergence between modular capture units and downstream utilization infrastructure is reshaping how project developers structure capital deployment and offtake risk across European industrial zones.
Solid adsorption systems utilizing metal-organic frameworks are overtaking conventional amine scrubbing in distributed capture applications. Food and beverage processors across Germany and the Netherlands are installing compact adsorption units for on-site CO2 recovery. The technology is overtaking liquid absorption in sub-100,000 ton-per-year installations by eliminating solvent degradation and thermal regeneration costs.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in cryogenic capture systems, forcing equipment suppliers to certify CO2-based and hydrocarbon alternatives. Industrial gas specialists are redesigning cold box architectures to accommodate lower-GWP refrigerant thermodynamics. Cement producers in Poland and the Czech Republic are delaying cryogenic capture investments until certified equipment becomes commercially available.
Power purchase agreements for renewable electricity are becoming standard contract terms for direct air capture developers seeking green hydrogen integration. Project sponsors in Norway and the Netherlands are bundling offshore wind offtake with electrolyzer capacity to supply synthetic fuel synthesis. This procurement pattern is most visible in Rotterdam's port industrial cluster, where capture-to-methanol projects now require documented renewable power sourcing for offtake qualification.
Carbon Capture and Utilization Market Segmentation
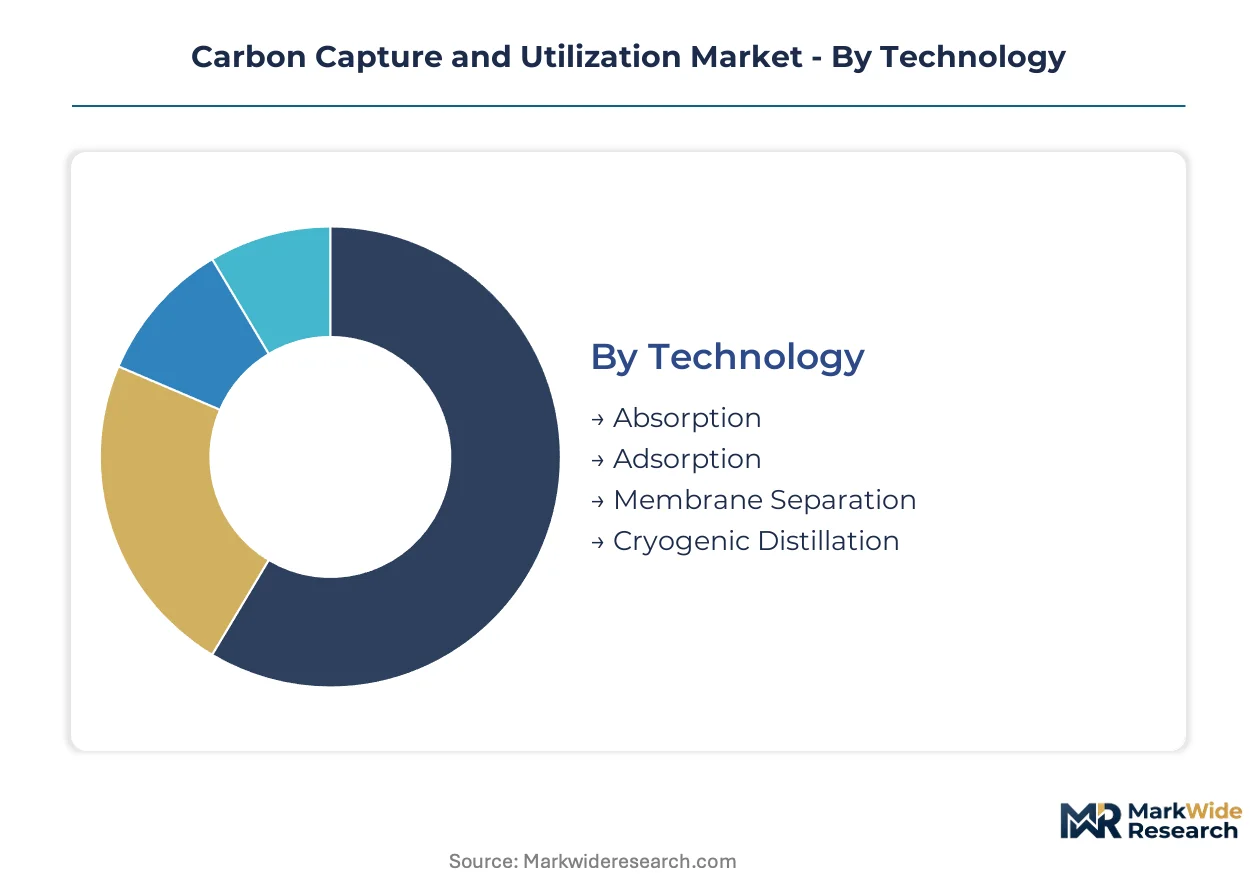
Carbon capture and utilization systems fragment across technology generations, product pathways, and industrial integration models. Each segmentation axis reveals distinct capital deployment patterns and regulatory exposure profiles that shape vendor positioning and project returns.
Technology:
Technology selection hinges on upgrade cycles from first-generation amine systems to modular membrane and solid sorbent configurations that reduce energy penalties and footprint constraints.
- Absorption:Amine-based liquid solvents dominate installed capacity through decades of operational maturity in natural gas processing and ammonia production. Cement producers across Germany and the Netherlands specify absorption skids for retrofit integration with existing kiln exhaust streams, though thermal regeneration costs expose operators to natural gas price volatility.
- Membrane Separation:Polymer and inorganic membrane materials achieve improving CO2 selectivity with reduced pressure-drop penalties in compact, modular deployments. Food and beverage processors in the Netherlands are adopting sub-100,000 ton-per-year membrane units for on-site CO2 recovery, displacing conventional absorption in distributed applications.
- Adsorption:Solid sorbent systems utilizing metal-organic frameworks eliminate solvent degradation and thermal regeneration requirements. Metal-organic framework systems are gaining traction in distributed capture applications across German industrial zones.
- Cryogenic Distillation:Cryogenic separation achieves high-purity CO2 streams through temperature-driven phase separation. The EU F-Gas Regulation is forcing equipment redesigns to accommodate lower-GWP refrigerant thermodynamics, delaying deployment in Poland and the Czech Republic until certified systems become available.
Absorption sits at the top of the volume ranking, with membrane separation climbing the fastest.
Product Type:
Product pathway selection determines margin capture and offtake risk, with synthetic fuels commanding premium pricing while enhanced oil recovery offers established demand anchors.
- Synthetic Fuels:Fischer-Tropsch and methanol synthesis pathways convert captured CO2 into aviation and maritime drop-in fuels. Project sponsors in Rotterdam's port cluster are bundling offshore wind power purchase agreements with electrolyzer capacity to supply synthetic fuel synthesis, securing offtake qualification through documented renewable sourcing.
- CO2 Enhanced Oil Recovery:Permian-style CO2 flooding operations in the North Sea region utilize captured streams for reservoir pressure maintenance and incremental crude production. Norwegian operators leverage existing pipeline infrastructure and certified geological reservoirs for permanent sequestration credits.
- Fertilizers:Urea and ammonium production incorporates captured CO2 as chemical feedstock. Ammonia producers in the Netherlands integrate capture systems with existing synthesis loops.
- Carbonated Beverages:Food-grade CO2 recovery serves beverage carbonation and food processing applications. German and Dutch processors are installing compact adsorption units for on-site supply security.
CO2 enhanced oil recovery holds the largest installed base, with synthetic fuels expanding most quickly.
End User:
End-user concentration reflects regulatory pressure gradients, with EU Green Deal mandates forcing deployment in cement and chemicals while power generation faces divergent national policy treatment.
- Cement Production:Kiln exhaust streams contain concentrated CO2 volumes ideal for capture retrofit. German, Dutch, and Norwegian cement corridors are mandating CCU deployment under binding decarbonization targets, though process integration engineering poses continuous operation challenges.
- Chemicals:Ammonia, ethylene, and methanol production generates process CO2 amenable to capture and downstream utilization. Chemicals clusters in Silesia remain underpenetrated relative to Western European benchmarks.
- Oil & Gas:Refinery crackers and hydrogen production units produce concentrated CO2 streams. Refining corridors are specifying capture skids for compliance with EU ETS obligations.
- Power Generation:Coal and gas-fired plants face divergent retrofit economics depending on remaining asset life and national phase-out schedules. New Source Performance Standards in the United States mandate CO2 monitoring and control at new facilities.
Cement production leads end-user deployment, with chemicals gaining share fastest.
Application:
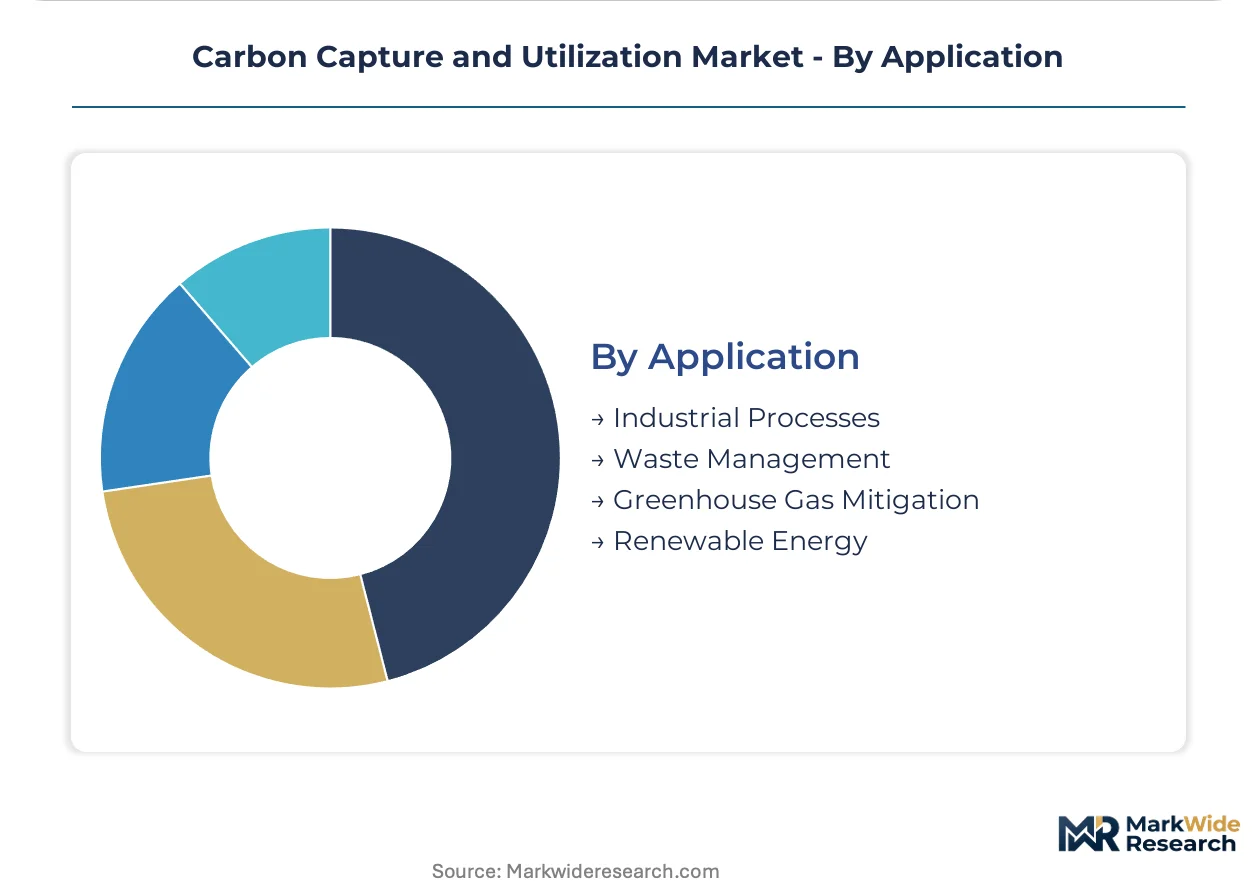
Application scope spans process integration, emissions compliance, and energy system coupling, with industrial processes offering the most mature deployment pathway.
- Industrial Processes:Direct integration of capture units with manufacturing operations enables closed-loop CO2 utilization. Industrial process applications dominate current deployment through established engineering protocols and measurable return thresholds.
- Greenhouse Gas Mitigation:Regulatory compliance and carbon credit monetization drive standalone capture investments. Greenhouse gas mitigation applications are expanding under tightening EU ETS caps and carbon border adjustment mechanisms.
- Renewable Energy:Coupling direct air capture with green hydrogen production creates synthetic fuel feedstocks. Renewable energy integration is visible in Norwegian and Dutch projects bundling offshore wind offtake with electrolyzer capacity.
- Waste Management:Landfill gas and waste-to-energy facilities capture biogenic CO2 for utilization or sequestration. Waste management applications remain nascent relative to industrial process integration.
Industrial processes command the largest deployment volume, with renewable energy coupling showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon capture and utilization technology first achieved industrial scale in the United States during enhanced oil recovery operations across the Permian Basin. European deployment accelerated under binding emissions frameworks, while Asian adoption concentrates in power generation corridors.
Germany
Cement and chemicals producers drive capture system procurement under EU ETS compliance deadlines. The Federal Environment Agency enforces Industrial Emissions Directive standards for kiln retrofits. The Rhine-Ruhr industrial corridor hosts multiple absorption technology deployments at ammonia and ethylene facilities.
United States
Refinery crackers and hydrogen production units supply concentrated CO2 streams for utilization pathways. EPA New Source Performance Standards mandate CO2 monitoring at new power generation facilities. The Gulf Coast petrochemical cluster anchors pipeline infrastructure connecting capture sites to enhanced oil recovery fields.
Netherlands
Rotterdam's port industrial cluster bundles offshore wind procurement with electrolyzer capacity for synthetic fuel synthesis. National carbon taxes supplement EU ETS pricing to improve project economics. Chemicals producers in the Maasvlakte zone integrate capture systems with existing synthesis loops.
Norway
North Sea operators leverage certified geological reservoirs for permanent sequestration credits alongside enhanced oil recovery. The government coordinates demonstration project funding through national CCUS roadmaps. Equinor and partners operate pipeline networks linking onshore capture to offshore storage infrastructure.
Japan
Power generation and steel producers deploy amine-based absorption systems under METI-coordinated national roadmaps. JIS equipment certification requirements shape domestic supplier qualification protocols. The Keihin industrial zone hosts integrated capture-to-utilization demonstrations at refinery and chemicals complexes.
Carbon Capture and Utilization Market Competitive Landscape
Capital-heavy engineering conglomerates compete with specialized technology developers for project development roles across industrial corridors. Market structure tilts toward consolidated equipment supply, with a handful of cryogenic gas separation and amine system specialists anchoring large-scale deployments. Three archetypes dominate: integrated oil and gas majors with carbon management platforms, industrial gas specialists leveraging cryogenic expertise, and modular direct air capture technology developers. Competitive moves center on strategic partnerships for integrated project delivery and technology licensing arrangements to accelerate geographic expansion.
Among integrated energy majors, Exxon Mobil Corporation and Shell plc occupy positions spanning capture through transport and storage endpoints. Industrial gas and engineering specialists include Linde plc and Mitsubishi Heavy Industries, Ltd., representing cryogenic separation and absorption system archetypes respectively. Modular technology developers such as Climeworks and Carbon Engineering exemplify the direct air capture segment, sitting within the fastest-expanding competitive tier as energy penalty reductions improve project economics.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Linde plc |
| Shell plc |
| Fluor Corporation |
| Mitsubishi Heavy Industries, Ltd. |
| Climeworks |
| Carbon Engineering |
| LanzaTech |
| Siemens Energy |
| Others |
Pricing and Supply Chain Analysis
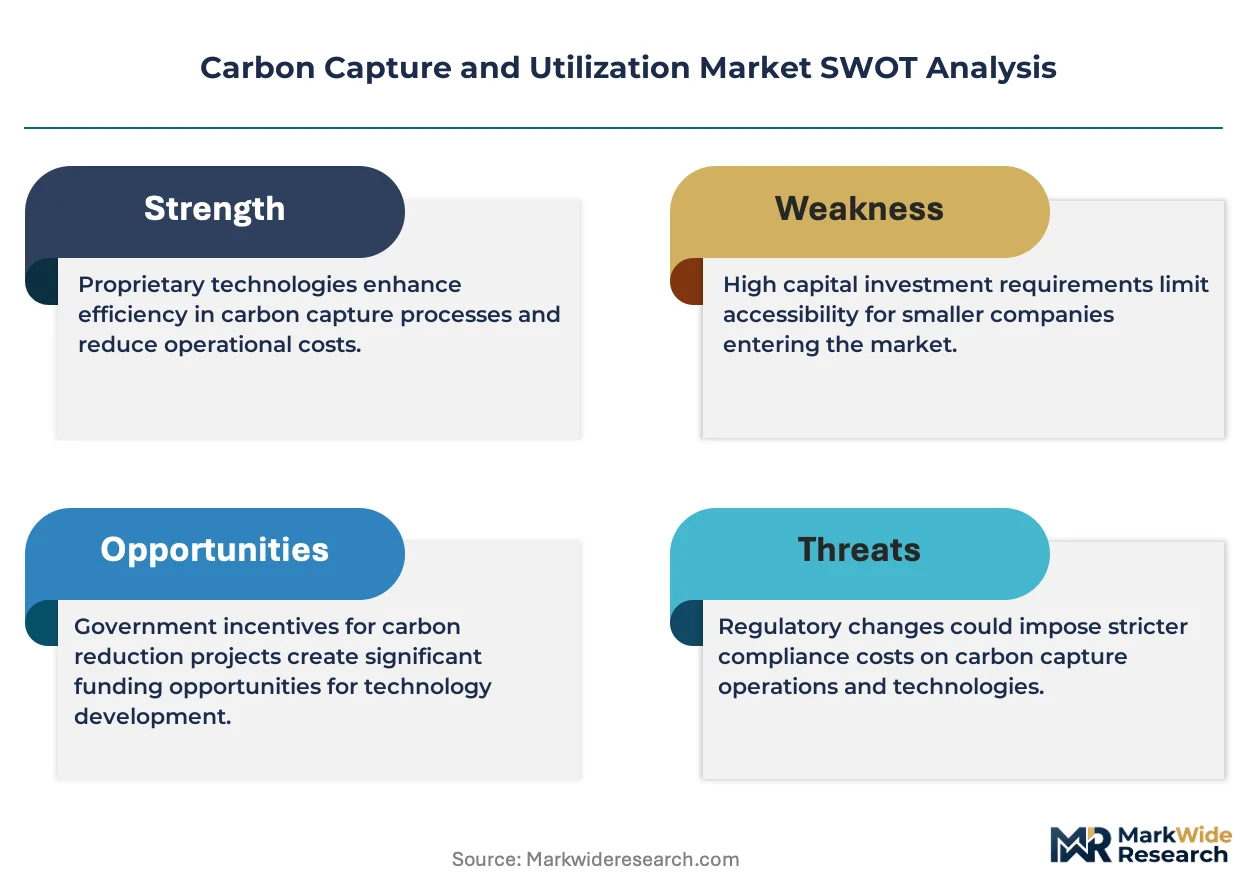
Membrane-cryogenic hybrid system commercialization is compressing capital costs per ton of captured CO2 while concentrating equipment procurement among German cryogenic specialists and Japanese membrane developers. This technology transition simultaneously reshapes project economics and supplier power across European industrial corridors.
Pricing Analysis
Project-based long-term offtake contracts dominate capital deployment, with pricing stratifying across premium, standard, and economy tiers based on carbon credit certification grade and renewable power sourcing documentation. Cost compression in economy-tier absorption systems is intensifying because amine solvent suppliers in Germany and the Netherlands face feedstock volatility. Cement producers exhibit highest price sensitivity due to thin margins and regulatory compliance deadlines, while aviation offtakers accept premium pricing for certified synthetic fuels.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Hamburg, and Antwerp anchor hub-and-spoke patterns for amine solvents, membrane modules, and cryogenic cold boxes. Manufacturing concentrates in Germany, Japan, and the United States, with specialized components drawing from precision engineering clusters in Switzerland and South Korea. Single-source vulnerability runs through German amine chemical suppliers and Norwegian geological reservoir certification bodies. Distribution runs through EPC contractor networks linking equipment suppliers to site-integrated project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Carbon Capture and Utilization Market reads as a late-cycle quality story as industrial offtakers shift procurement toward premium-grade synthetic fuels with documented renewable power provenance and permanent sequestration certification.
For Market Incumbents: Anticipate margin erosion from modular membrane developers by deepening captive supply of metal-organic framework sorbents and securing exclusive pipeline access to Norwegian storage reservoirs. Anchor market position through backward integration into green hydrogen production and electrolyzer capacity in Rotterdam's port cluster. For New Entrants and Emerging Players: Engineering procurement construction contractors represent the critical channel partner type for market access, particularly those with established relationships in Poland's underpenetrated Silesian cement corridor. Target distributed capture applications in food and beverage processing where compact adsorption units displace conventional absorption. Lead with power purchase agreement bundling as the go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among modular direct air capture technology developers with demonstrated energy penalty reductions but limited offtake contract visibility. Long-term viability hinges on synthetic fuel margin sustainability and carbon border adjustment mechanism enforcement breadth. Watch for inflection in aviation sector sustainable aviation fuel mandate implementation.| Strategic Initiative | Industry Significance |
|---|---|
| Green Hydrogen Integration | Rotterdam port developers bundle offshore wind procurement with electrolyzer capacity for synthetic fuel synthesis. |
| Membrane-Cryogenic Hybrid Deployment | German engineering firms capture modular installation contracts through reduced footprint and energy penalty advantages. |
| Permanent Sequestration Certification | Norwegian operators leverage certified geological reservoirs for compliance credit generation under EU ETS. |
| Amine Solvent Backward Integration | Industrial gas specialists secure captive supply chains against petrochemical feedstock volatility in German corridors. |
| Polish Industrial Corridor Expansion | Project developers target Silesian cement clusters with retrofit absorption skids ahead of EU Green Deal compliance deadlines. |
Research Methodology
Bottom-up cement and chemicals modeling reconciled against top-down equipment supply tracking forms the analytical core of this study. Primary interviews with EPC contractors, plant engineers at ammonia facilities, carbon credit verification specialists, and procurement leads at aviation fuel offtakers combined with secondary validation from EU ETS transaction databases, national CCUS roadmap filings, and equipment certification registries. Trade flow analysis from German and Dutch customs authorities anchored supply-side triangulation.
Historical trendline analysis across technology generation transitions informed projection frameworks, with segmentation across absorption, membrane, adsorption, and cryogenic systems plus product pathway differentiation in synthetic fuels, enhanced oil recovery, and chemical feedstocks. CAGRs derived from capacity deployment pipelines and carbon price trajectory assumptions. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and 45Q tax credit rule evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism implementation timing and sustainable aviation fuel mandate stringency. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
UAE Industrial Waste Management Market
Environment & Sustainability
Water Purifier/Filter Market
Environment & Sustainability
Sustainable Air Filter Market
Environment & Sustainability
Portable Filtration System Market
Environment & Sustainability
Water Filters Market
Environment & Sustainability
Indoor Air Purification Market
Environment & Sustainability
Canada Cloud Seeding Market
Environment & Sustainability
Ecological Wastewater Treatment Market
Environment & Sustainability
Green Cement Market
Environment & Sustainability
Industrial Waste Management Market
Environment & Sustainability
Eco Funnel Market
Environment & Sustainability
Track Carbon Footprint App Market
Environment & Sustainability
Philippines Gravity-Based Water Purifier Market
Environment & Sustainability
North America Water Sink Market
Environment & Sustainability
North America Trash Bags Market
Environment & Sustainability
ASEAN Waste Management Market