
 Emission Trading Schemes Market | 2026-2036
Emission Trading Schemes Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Trading Schemes Market Foresight
Buyer concentration among power utilities and heavy industry emitters is realigning procurement strategies across primary carbon exchanges. Intercontinental Exchange leverages its European energy derivatives infrastructure to anchor compliance contract liquidity. Xpansiv competes through its CBL spot marketplace, specializing in granular, technology-specific carbon credits for voluntary buyers.
Emission trading schemes constitute regulated market mechanisms that impose quantitative caps on greenhouse gas output while permitting trade of surplus allowances or verified offsets, with each credit representing one metric ton of carbon dioxide equivalent sequestered or avoided. These systems function as cost-minimization instruments, channeling abatement investment toward lowest-marginal-cost reduction opportunities across covered sectors. Cap-and-trade mechanisms dominate transaction value in mandatory markets where compliance buyers face binding reduction obligations, while voluntary carbon offset trading attracts corporate sustainability commitments seeking beyond-compliance claims. Carbon credit type segmentation reveals Verified Emission Reductions commanding structural preference from buyers prioritizing third-party audit trails.
The European Commission's ETS and Carbon Border Adjustment Mechanism, the EPA's evolving power plant standards under the Clean Air Act, and China's MEE-administered national ETS collectively determine market access rules and credit eligibility criteria across major trading jurisdictions. These frameworks directly shape demand by specifying which offset categories qualify for compliance surrender and which face quantitative or geographic restrictions. Stakeholders must monitor regulatory divergence between jurisdictions as credit fungibility rules determine arbitrage opportunities and portfolio valuation methodologies.
Market Dynamics
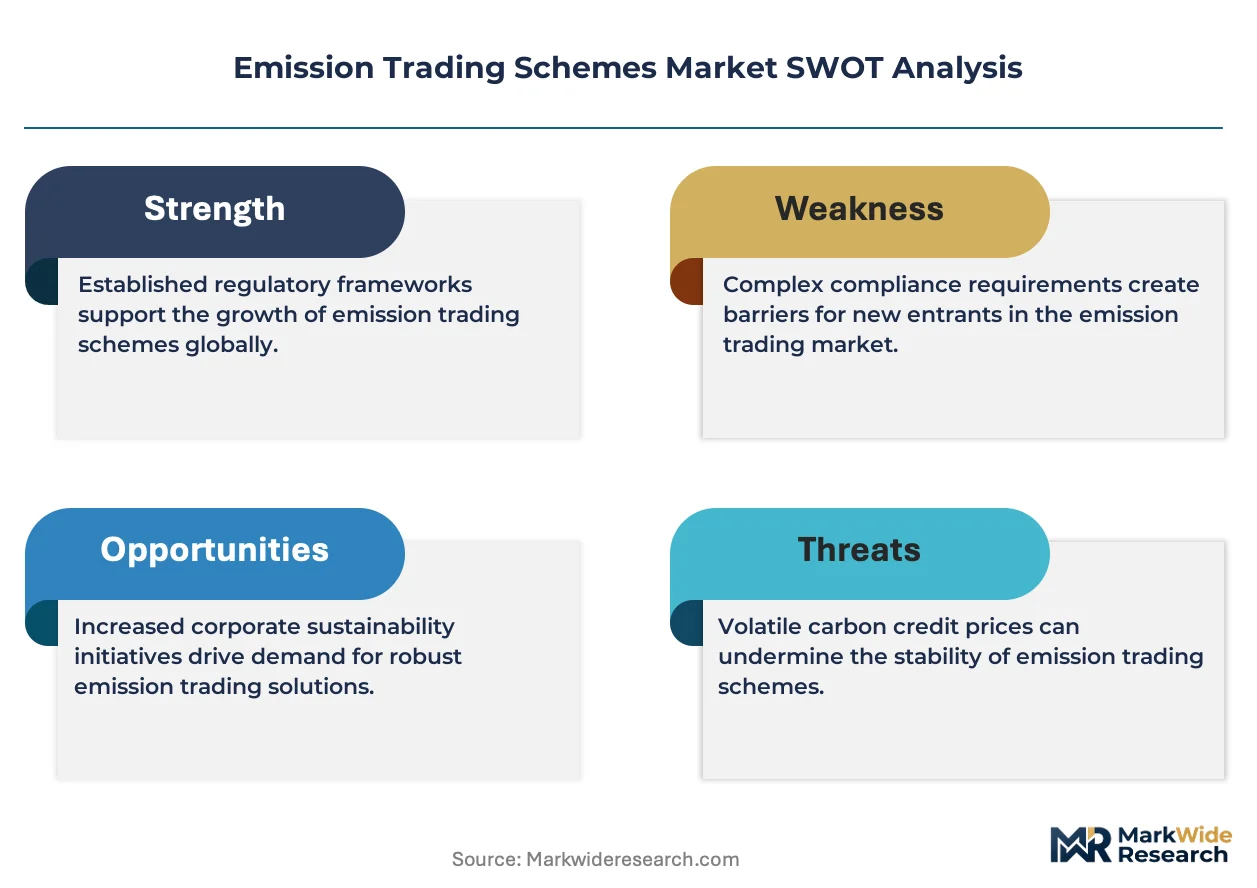
Compliance purchasing by power utilities across OECD member states is tightening allowance markets as national caps constrict supply. The EU ETS Carbon Border Adjustment Mechanism redirects import flows toward verified offset procurement, while China's provincial pilot consolidation concentrates liquidity on the national platform.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:Importers into the European Union must surrender verified offsets equivalent to embedded emissions, creating mandatory demand for third-party audited credits.
- Power utilities:Heavy emitters across Germany, Poland, and Japan are accelerating compliance purchasing ahead of tightening Phase IV allocation benchmarks.
- Blockchain-based MRV systems:Distributed ledger verification is expanding into voluntary offset registries, reducing transaction costs for granular project-level credits.
Market Restraints
- Natural gas price volatility:Fuel switching economics destabilize power sector abatement cost curves, compressing allowance demand during price spikes.
- Chinese provincial fragmentation:Lingering pilot scheme heterogeneity creates liquidity silos that impede national market price discovery.
- Additionality disputes:Baseline methodology controversies surrounding avoided deforestation credits trigger buyer hesitation in voluntary segments.
Strategic Opportunities
- India's emerging compliance framework:Bureau of Energy Efficiency carbon market pilots offer first-mover positioning before mandatory expansion.
- CCUS-ETS linkage:Carbon capture utilization and storage project crediting creates new offset categories for hard-to-abate industrial clusters.
- Corporate Scope 3 procurement:Supply chain emissions accounting mandates from EU CSRD drive voluntary offset demand beyond direct operations.
Industry Challenges
- Quantification expertise scarcity:Project developers face acute shortages of certified verification specialists capable of ISO 14064-2 compliant monitoring.
- Legacy registry interoperability:Incompatible serial numbering systems between Gold Standard, Verra, and national registries complicate portfolio aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Trading Schemes Market |
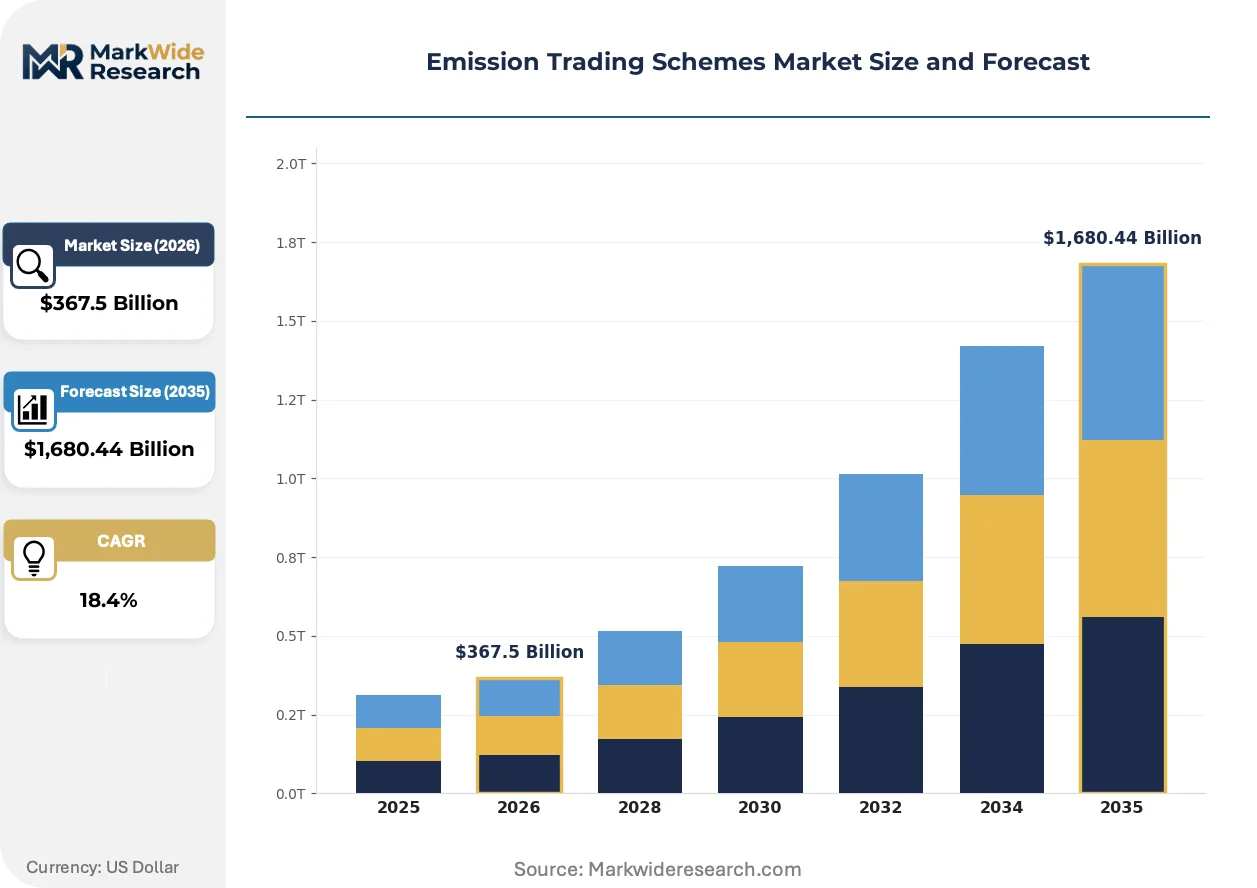
| Market Size in 2026 | $367.5 Billion |
| Market Size in 2035 | $1,680.44 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Scheme Type: Cap-and-Trade, Carbon Offset Trading, Renewable Energy Certificates, Market-based Instruments Participant Type: Compliance Buyers, Voluntary Sellers, Brokers, Market Makers Market Structure: Mandatory Market, Voluntary Market, Hybrid Market, Regional Schemes Carbon Credit Type: Verified Emission Reductions, Certified Emission Reductions, Gold Standard Credits, Others |
| Companies Covered | Intercontinental Exchange (ICE), Xpansiv, AirCarbon Exchange (ACX), European Energy Exchange (EEX), ESGCX, Numerco, ClearBlue Markets, Evolution Markets, Climate Impact Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Trading Schemes Market Shifts & Advancements
Digital infrastructure is compressing settlement cycles and enabling granular credit unbundling. Market participants deploy automated monitoring systems and smart contract settlement to reduce counterparty risk and transaction friction.
Remote sensing and satellite-based monitoring is expanding into forestry and soil carbon verification, replacing manual site inspections with continuous biomass measurement. Project developers in Indonesia and Brazil adopt these systems to reduce verification costs and accelerate credit issuance timelines. This technology is expanding into jurisdictional REDD+ programs, enabling national-scale baseline setting that supersedes project-level accounting.
The EPA's evolving power plant standards under the Clean Air Act tighten emission rate benchmarks for existing coal and gas facilities. Covered generators must surrender allowances or procure offsets, redirecting investment toward gas conversion or renewable substitution. Utilities in Texas and Ohio respond by hedging forward allowance positions through Intercontinental Exchange derivatives.
Corporate buyers increasingly bundle offset procurement with supplier sustainability audits, conditioning contract renewals on verified emission reductions. This pattern displaces transactional spot purchasing with multi-year offtake agreements tied to specific project vintages. Consumer-facing brands in Germany and the Netherlands lead this integration, embedding carbon neutrality claims into product certification schemes.
Emission Trading Schemes Market Segmentation
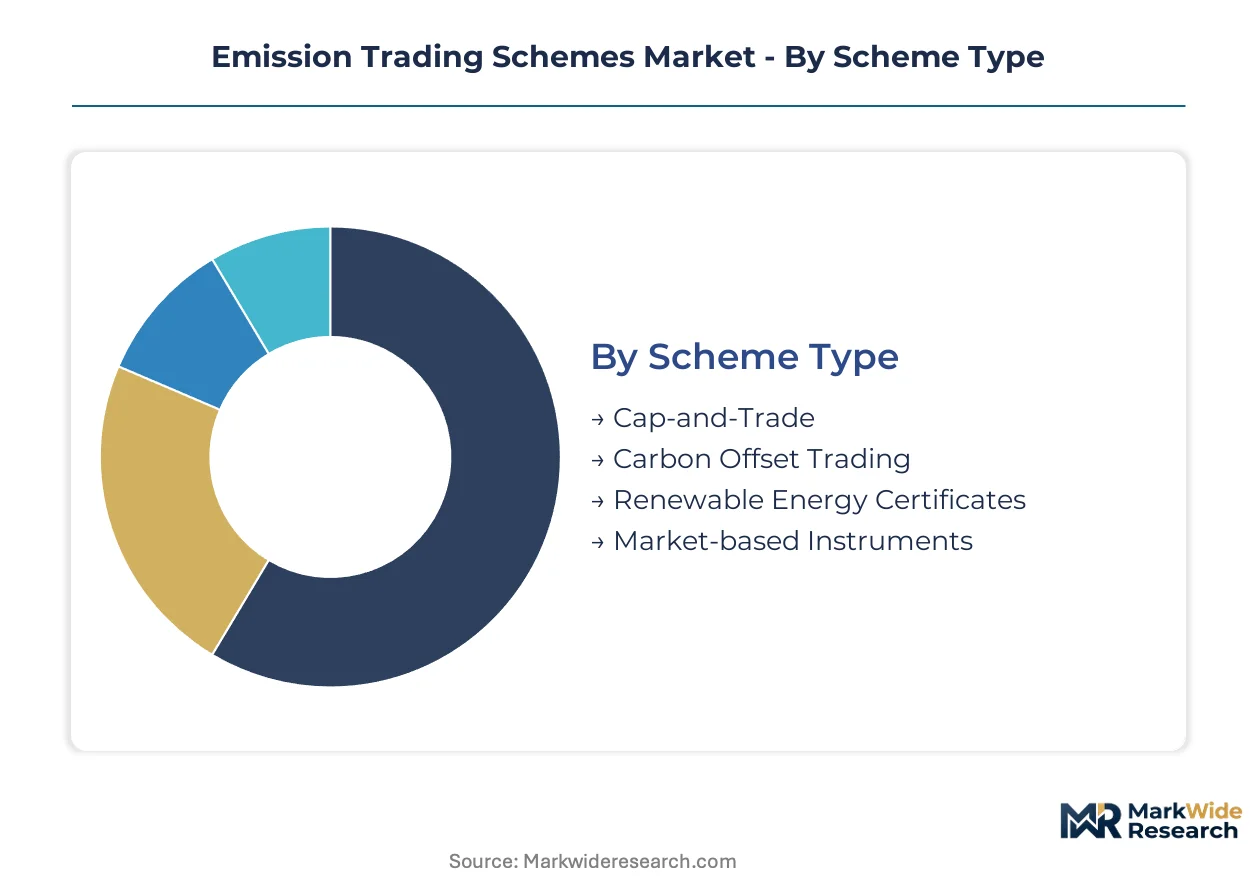
Segmentation in emission trading schemes reveals how regulatory architecture shapes transaction patterns across compliance and voluntary channels. Different scheme types, participant profiles, and credit categories command distinct liquidity profiles and pricing dynamics that determine portfolio construction strategies.
Scheme Type:
Standardization dominates cap-and-trade platforms with uniform allowance units, while carbon offset trading permits granular customization by technology and geography.
- Cap-and-Trade:Mandatory systems issue fungible allowances equal to the emissions cap, with each permit representing one metric ton of carbon dioxide equivalent. Power utilities across Germany, Poland, and Japan concentrate procurement here as Phase IV benchmarks tighten. The EU ETS anchors liquidity through Intercontinental Exchange derivatives.
- Carbon Offset Trading:Project-based credits from verified emission reductions trade in parallel voluntary markets, attracting corporate sustainability commitments beyond compliance obligations. Demand concentrates among consumer-facing brands in Germany and the Netherlands embedding neutrality claims into product certification.
- Renewable Energy Certificates:Attribute tracking instruments separate clean energy generation from physical power delivery, enabling location-flexible renewable claims.
- Market-based Instruments:Broader policy mechanisms including carbon taxes with trading components and baseline-and-credit systems.
Leading the category by volume: Cap-and-Trade. Growing fastest: Carbon Offset Trading.
Participant Type:
Cost tier separation distinguishes price-sensitive compliance purchasers from premium-seeking voluntary actors willing to pay for audit depth and storytelling value.
- Compliance Buyers:Heavy industry emitters and power generators facing binding reduction obligations under EPA, EU ETS, or China's MEE-administered frameworks. These participants prioritize allowance fungibility and settlement reliability over credit provenance.
- Voluntary Sellers:Project developers issuing verified offsets through Gold Standard, Verra, or national registries, capturing price premiums for technology-specific or community-benefit credits.
- Brokers:Intermediaries matching dispersed supply with fragmented demand, earning spreads on price discovery and counterparty risk absorption.
- Market Makers:Liquidity providers posting continuous two-way prices, essential for derivatives market functioning on ICE and comparable platforms.
Compliance buyers generate the largest transaction value. Voluntary sellers command the steepest expansion trajectory as corporate net-zero commitments multiply.
Market Structure:
Geographic scope determines credit fungibility rules and arbitrage opportunities across jurisdictional boundaries.
- Mandatory Market:Government-imposed caps with enforcement penalties, covering power generation, heavy manufacturing, and aviation under EU ETS and comparable frameworks.
- Voluntary Market:Unregulated offset procurement driven by corporate sustainability targets, supply chain mandates, and consumer brand positioning.
- Hybrid Market:Systems allowing limited offset use for compliance surrender, such as California's cap-and-trade linkage with Western Climate Initiative credits.
- Regional Schemes:Sub-national pilots including China's provincial ETS programs consolidating into the national MEE platform.
Mandatory markets dominate absolute value. Hybrid structures are gaining share fastest as regulators expand offset eligibility.
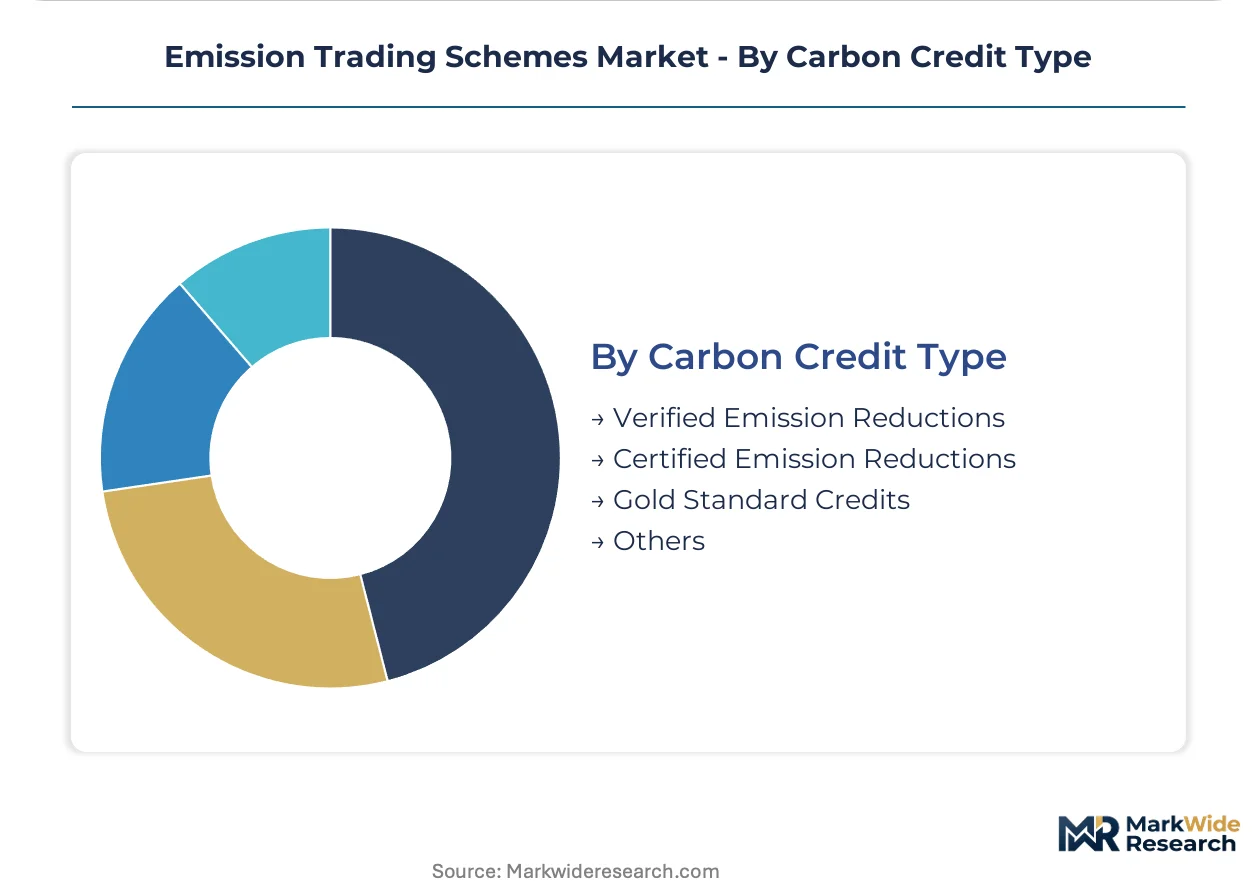
Carbon Credit Type:
Margin stratification separates premium third-party audited instruments from lower-cost alternatives with reduced verification depth.
- Verified Emission Reductions:ISO 14064-2 compliant credits with independent audit trails, commanding structural preference from buyers prioritizing risk mitigation. Project developers face acute shortages of certified verification specialists capable of maintaining this standard.
- Certified Emission Reductions:UNFCCC-issued units from Clean Development Mechanism projects, historically dominant in international compliance markets but facing eligibility restrictions under EU ETS Phase IV.
- Gold Standard Credits:Premium voluntary instruments with sustainable development co-benefit requirements, attracting corporate buyers bundling procurement with supplier sustainability audits.
- Others:Jurisdictional REDD+ units, bilateral crediting mechanisms, and emerging CCUS-linked offset categories.
Verified Emission Reductions lead by transaction volume. Gold Standard Credits are expanding most quickly in voluntary segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lignite deposits in Poland's Silesian Basin and hard coal reserves in Germany's Ruhr region anchor European carbon-intensive generation clusters where compliance purchasing concentrates. These fossil fuel localities drive allowance demand under tightening EU ETS Phase IV benchmarks.
United States
Power utilities in Texas and Ohio accelerate hedging activity through exchange-traded derivatives as EPA power plant standards tighten emission rate benchmarks. The Clean Air Act enforcement redirects investment toward gas conversion and renewable substitution across ERCOT and PJM interconnection zones.
Germany
RWE and Uniper operations in the Rhine-Ruhr industrial corridor face binding Phase IV allocation reductions. The national coal phase-out law accelerates allowance demand for remaining lignite units while Berlin-based traders arbitrage EU ETS price differentials against forward power curves.
China
Provincial pilot consolidation into the MEE-administered national ETS concentrates liquidity on the Shanghai-based platform. Power generators in Shandong and Jiangsu provinces dominate compliance purchasing as the national market absorbs regional scheme heterogeneity.
Japan
Tokyo and Saitama prefecture-level cap-and-trade systems generate baseline-and-credit demand from commercial building operators. METI's GX League corporate decarbonization program channels voluntary offset procurement toward domestic forest restoration credits.
India
Bureau of Energy Efficiency carbon market pilots in Gujarat and Maharashtra offer first-mover positioning before mandatory expansion. Heavy industry clusters in Mundra and Hazira anticipate compliance obligations under the proposed national ETS framework.
Emission Trading Schemes Market Competitive Landscape
Established exchanges occupy the standard tier; emerging entrants pursue blockchain-native settlement and granular credit unbundling. The vendor base stratifies across three tiers: incumbent financial exchanges with energy derivatives infrastructure, specialized carbon marketplaces with technology-specific registries, and technology-enabled challengers with automated MRV integration. Competitive moves center on registry interoperability partnerships and geographic exchange linkages that expand credit fungibility across jurisdictions.
Within the incumbent exchange tier, Intercontinental Exchange and European Energy Exchange exemplify archetypes leveraging existing energy derivatives infrastructure to anchor compliance contract liquidity. Xpansiv occupies a position representing the specialized marketplace vector, competing through granular, technology-specific carbon credits for voluntary buyers. These three entities collectively illustrate how regulatory divergence between EU, US, and Chinese frameworks creates parallel liquidity pools requiring distinct settlement and verification architectures.
| Leading Market Players |
|---|
| Intercontinental Exchange (ICE) |
| Xpansiv |
| AirCarbon Exchange (ACX) |
| European Energy Exchange (EEX) |
| ESGCX |
| Numerco |
| ClearBlue Markets |
| Evolution Markets |
| Climate Impact Partners |
| Others |
Supply & Pricing Matrix
ICE EUA futures pricing cascades through the carbon credit supply chain, compressing margins for project developers while amplifying procurement costs for compliance buyers in Germany and Poland. This benchmark volatility stratifies the market into premium-verified, standard-compliant, and economy-tier offset categories.
Pricing Analysis
Verification-bundling separates premium Gold Standard credits from unbundled spot market instruments, with ISO 14064-2 audit trails commanding structural premiums over self-certified alternatives. Price differentiation hinges on certification depth and geographic delivery risk, with EU ETS-linked allowances tightening faster than voluntary offsets. Pricing pressure stems from natural gas price volatility disrupting power sector abatement economics. Compliance buyers in heavy manufacturing exhibit acute price sensitivity, while voluntary corporate purchasers prioritize audit provenance over cost.
Supply Chain Analysis
Registry interoperability challenges create reverse-verification flows, with credits cycling through Gold Standard, Verra, and national registries for re-issuance and quality upgrades. Supply concentrates in Indonesia, Brazil, and Kenya for forestry offsets, while CCUS project development clusters in the United States and Norway. The supply chain draws from satellite-based MRV technology, certified verification labor, and jurisdictional baseline data. Single-source vulnerability sits with concentrated verification specialist pools. Distribution runs through exchange-traded derivatives for compliance buyers and bilateral offtake agreements for voluntary segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around registry interoperability and MRV technology scale, with regulatory fragmentation forcing smaller verification bodies into acquisition targets.
For Market Incumbents: Deploy registry interoperability partnerships to capture liquidity migrating between EU ETS, China's MEE-administered national platform, and voluntary channels. Incumbents should anchor exchange-traded derivatives infrastructure against emerging blockchain-native settlement challengers, while investing in automated MRV systems to offset verification specialist scarcity. For New Entrants and Emerging Players: Begin with India's Bureau of Energy Efficiency pilot schemes before mandatory national ETS expansion, targeting first-mover positioning in Gujarat and Maharashtra heavy industry clusters. New entrants should pursue CCUS-ETS linkage opportunities in hard-to-abate industrial sectors, leveraging jurisdictional REDD+ program development in Indonesia and Brazil as the most penetrable voluntary segment. For Investors and Strategic Acquirers: The window for entry favors technology-enabled challengers with automated MRV integration and granular credit unbundling capabilities over legacy registry operators. Long-term viability rests on capturing standardization benefits as provincial fragmentation resolves into national platforms. Watch for EU Carbon Border Adjustment Mechanism enforcement intensity as the inflection signal determining compliance demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Registry Interoperability Partnership | Resolves legacy serial numbering incompatibilities between Gold Standard, Verra, and national registries. |
| Automated MRV Technology Deployment | Compresses verification timelines for Indonesian and Brazilian forestry project developers. |
| CCUS-ETS Linkage Development | Creates new offset categories for German and Polish industrial cluster decarbonization. |
| Provincial-to-National Market Consolidation | Captures liquidity concentration on China's MEE-administered Shanghai-based platform. |
| Corporate Scope 3 Procurement Integration | Aligns voluntary offset demand with EU CSRD supply chain emissions accounting mandates. |
Research Methodology
Multi-period observation of EU ETS allowance auction clearances, ICE futures open interest, and provincial pilot trading volumes anchored the trend analysis, supplemented by interviews with exchange operations directors, project verification specialists, and compliance procurement managers at German and Polish power utilities. Secondary validation drew from EPA power plant standard filings, ETS regulatory gazettes, and carbon credit issuance databases. Bottom-up project pipeline assessments triangulated against top-down cap-and-trade market modeling.
Segment-weighting across scheme type, participant profile, and credit category dimensions shaped volume and value projections across the analysis window. CAGRs derived from regulatory cap trajectory analysis, fuel switching economics, and corporate net-zero commitment velocity. Forecast inputs incorporated EU Carbon Border Adjustment Mechanism phase-in schedules and China's provincial consolidation timeline.
Underlying measurement precision varies by segment; cap-and-trade allowance markets carry tighter precision than voluntary offset categories due to transparent auction data. Forecasts reflect assumptions regarding regulatory enforcement consistency and verification standard harmonization. Practitioners should monitor EU ETS Market Stability Reserve intervention thresholds and China's MEE platform liquidity metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market