
 Emission Management Market | 2026-2036
Emission Management Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Management Market Foresight
Advanced sensor materials are displacing electrochemical cells in stack monitoring hardware, and this substitution is broadening the addressable base for mid-tier industrial buyers. Siemens AG leverages its digital twin portfolio to anchor long-term service contracts across European refinery networks. ABB Ltd competes through integrated control systems that couple hardware with predictive analytics. Thermo Fisher Scientific Inc. specializes in high-precision optical analyzers for regulatory-grade certification.
Emission management encompasses the systematic measurement, reporting, and reduction of pollutant releases from industrial and mobile sources, typically employing continuous emissions monitoring systems with detection thresholds measured in parts per million and real-time data transmission protocols. Its primary purpose is to ensure operational compliance with environmental statutes while enabling process optimization that reduces fugitive losses. Software solutions and AI analytics now capture the fastest-expanding margin pools as operators shift from periodic manual sampling to automated predictive platforms. Sensors and monitoring equipment retain volume leadership but face commoditization pressure as IoT-enabled devices proliferate.
The EPA enforces methane performance standards under the Clean Air Act that mandate optical gas imaging surveys and repair timelines, directly shaping capital allocation toward leak detection infrastructure. EU Directives including the Industrial Emissions Directive and F-Gas Regulation impose technology-forcing requirements that determine product eligibility for market access across member states. ISO standards provide the measurement and verification protocols that underpin cross-border data credibility. Stakeholders must decide whether to build in-house analytics capabilities or partner with platform providers as regulatory granularity intensifies.
Market Dynamics
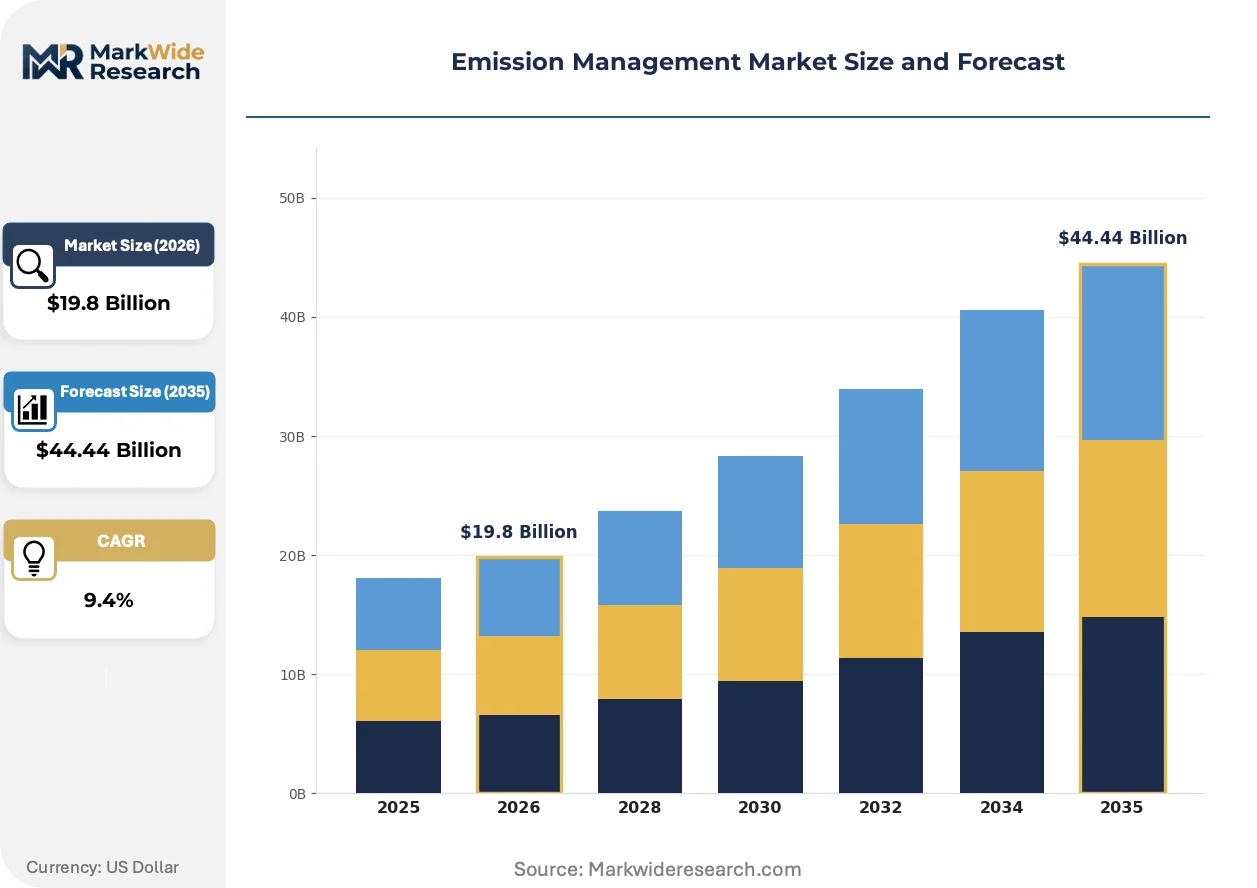
The transition from periodic manual sampling to continuous automated monitoring is restructuring capital deployment across industrial facilities, with operators prioritizing platforms that integrate hardware sensors with cloud-native analytics stacks.
Growth Catalysts
- EPA Methane Performance Standards:The Clean Air Act mandates optical gas imaging surveys and strict repair timelines, compelling oil and gas operators to upgrade leak detection infrastructure.
- Shale infrastructure retrofit cycles:US onshore producers are replacing legacy pneumatic controllers with automated detection systems to reduce fugitive emissions.
- EU F-Gas Regulation:Technology-forcing requirements for fluorinated gas monitoring are expanding the addressable base for mid-tier industrial buyers across member states.
Market Restraints
- Sensor material cost volatility:Rare earth elements and specialized optical components face supply concentration risk from Chinese processing facilities.
- Electrochemical cell substitution:Established incumbent hardware vendors resist platform transitions that cannibalize installed base service revenues.
- Cross-border data friction:GDPR and emerging national data sovereignty laws complicate real-time transmission protocols for multinational operators.
Strategic Opportunities
- EU Green Deal implementation gaps:Industrial clusters in Poland and Romania remain underpenetrated for continuous emissions monitoring relative to German or Dutch benchmarks.
- AI-analytics unbundling:Specialized software vendors can bypass hardware commoditization by selling predictive maintenance modules as standalone subscriptions.
- Carbon border adjustment mechanisms:Importers into the EU will require certified emissions data, creating demand for verification-grade monitoring systems.
Industry Challenges
- Field calibration expertise scarcity:Facilities struggle to recruit technicians qualified for optical analyzer maintenance and ISO 17025-aligned quality assurance.
- Legacy SCADA integration complexity:Brownfield sites face protocol mismatches when connecting new IoT sensors to decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Management Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $44.44 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Sensors, Monitoring Equipment, Control Systems End User: Manufacturers, Transportation, Energy Sector, Government Agencies Technology: IoT Solutions, Cloud-Based Systems, AI Analytics, Blockchain Applications Regulatory Compliance: ISO Standards, EPA Regulations, EU Directives, Local Laws |
| Companies Covered | ABB Ltd, Siemens AG, AMETEK, Inc, Emerson Electric Company, Baker Hughes, Horiba Ltd, Fuji Electric Co., Ltd., Rockwell Automation, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Management Market Shifts & Advancements
Hardware commoditization is compressing margins for standalone sensor manufacturers while value migrates toward software layers that aggregate multi-source data streams into actionable compliance dashboards.
Tunable diode laser absorption spectroscopy is overtaking nondispersive infrared methods for stack monitoring applications. Refinery operators in the US Gulf Coast and Rotterdam-Antwerp hub are deploying these systems at scale. The technology is overtaking electrochemical alternatives by enabling sub-ppm detection thresholds without consumable reagents.
The EU Industrial Emissions Directive is tightening monitoring requirements for large combustion plants. Operators must install automated measurement systems and report quarterly to competent authorities. German power generators and Czech steel mills are accelerating procurement timelines to meet the 2025 compliance checkpoint.
Service unbundling is fragmenting traditional vendor relationships. End-users now separate hardware procurement from analytics subscriptions and calibration contracts. This pattern is most pronounced among North American shale producers seeking operational flexibility without long-term capital commitments to single suppliers.
Emission Management Market Segmentation
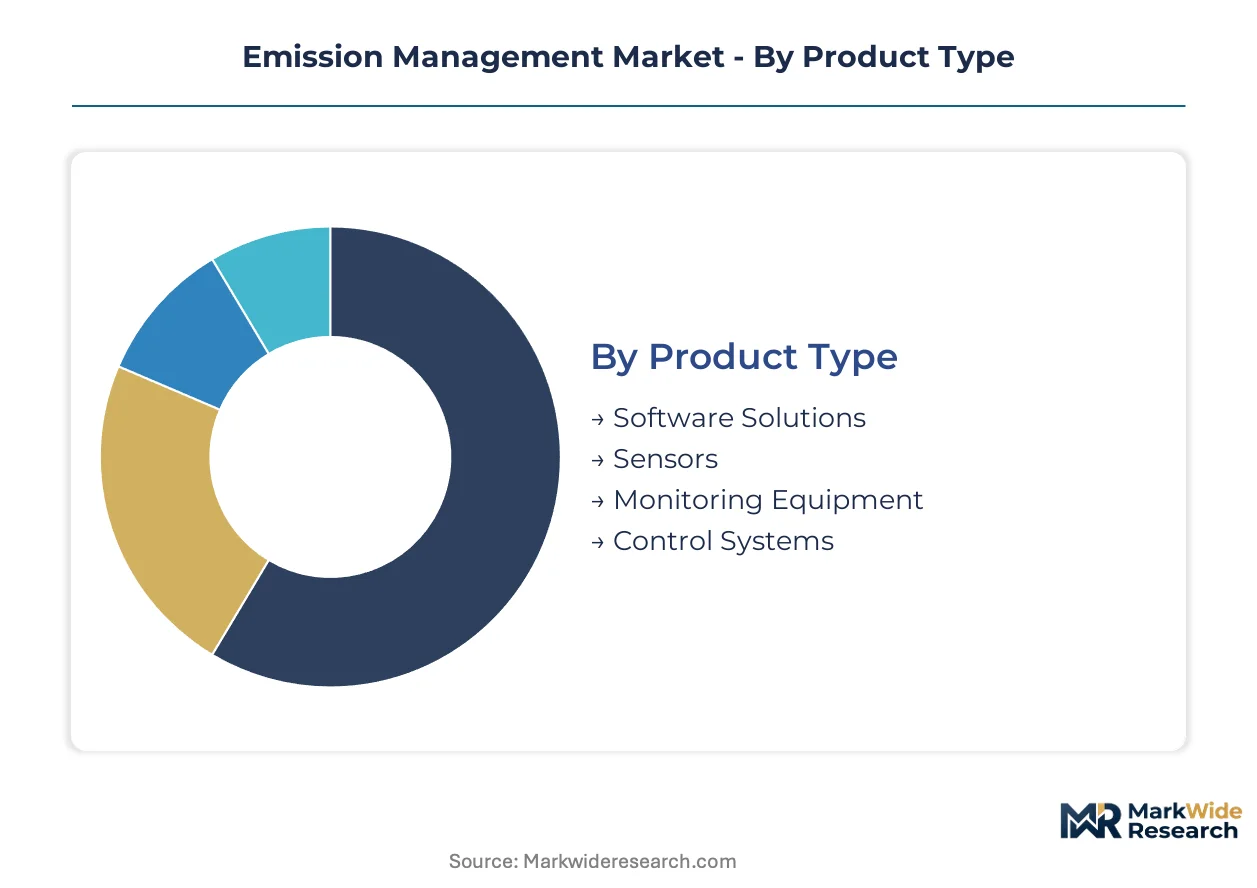
Emission management procurement splits across hardware, software, and service layers with divergent margin profiles. Buyers now unbundle these layers to optimize capital efficiency and avoid vendor lock-in.
Product Type:
Technology specifications determine integration complexity and lifecycle cost structures for industrial buyers.
- Software Solutions:Cloud-native platforms aggregate multi-source sensor data into compliance dashboards with predictive maintenance modules. North American shale producers favor subscription models that decouple analytics from hardware procurement, reducing long-term capital commitments.
- Sensors:Tunable diode laser absorption spectroscopy devices enable sub-ppm detection thresholds without consumable reagents. Refinery operators along the US Gulf Coast and in the Rotterdam-Antwerp hub deploy these at scale to replace electrochemical alternatives.
- Monitoring Equipment:Integrated continuous emissions monitoring systems with real-time transmission protocols serve large combustion plants under tightening EU Industrial Emissions Directive requirements.
- Control Systems:Distributed control architectures with SCADA integration capabilities address brownfield retrofit challenges where legacy protocol mismatches complicate IoT sensor deployment.
Monitoring Equipment leads on scale; Software Solutions lead on momentum.
End User:
Regulatory exposure and asset intensity shape procurement sophistication across buyer categories.
- Energy Sector:Oil and gas operators face EPA methane performance standards mandating optical gas imaging surveys and strict repair timelines. US onshore producers retrofit legacy pneumatic controllers with automated detection systems to reduce fugitive emissions.
- Manufacturers:Steel mills and chemical plants in Germany and the Czech Republic accelerate procurement to meet EU Industrial Emissions Directive checkpoints for large combustion plants.
- Government Agencies:Environmental regulators deploy verification-grade systems for certified emissions data to support carbon border adjustment mechanisms affecting EU importers.
- Transportation:Fleet operators and logistics providers adopt mobile monitoring for compliance with evolving tailpipe and refrigerant gas regulations.
Energy Sector dominates current deployment; Government Agencies show steepest expansion trajectory.
Technology:
Architecture choices determine data sovereignty risks and predictive capability depth.
- AI Analytics:Machine learning models predict equipment failure and optimize maintenance scheduling before threshold breaches occur. Specialized vendors sell these modules as standalone subscriptions to bypass hardware commoditization.
- IoT Solutions:Edge-connected sensor networks enable real-time emissions tracking with minimal latency for time-critical leak detection scenarios.
- Cloud-Based Systems:Centralized data lakes face friction from GDPR and emerging national data sovereignty laws complicating cross-border transmission protocols.
- Blockchain Applications:Immutable audit trails support verification-grade certification for carbon credit markets and regulatory reporting.
IoT Solutions anchor installed base; AI Analytics captures expanding margin pools.
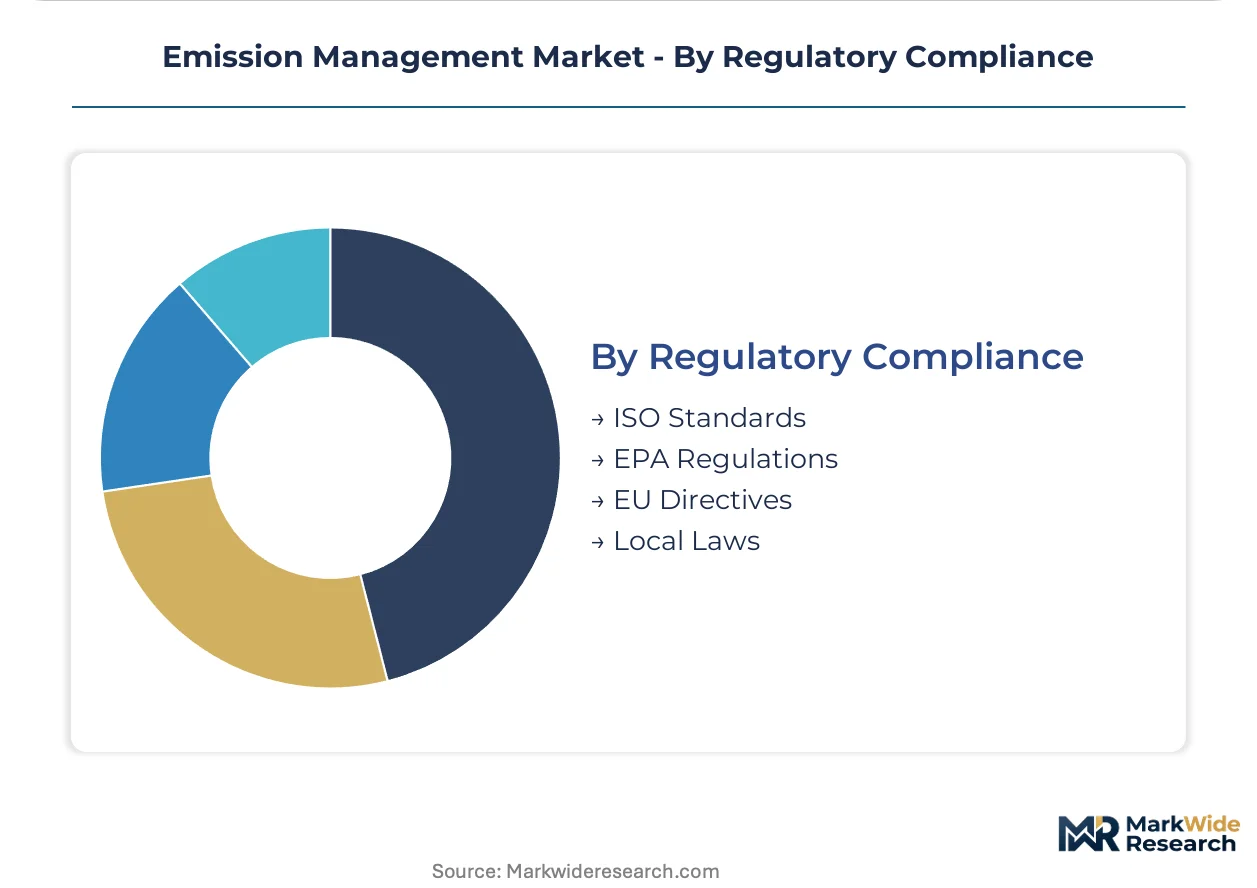
Regulatory Compliance:
Certification requirements fragment procurement specifications by jurisdiction.
- EPA Regulations:Clean Air Act methane performance standards mandate specific detection technologies and repair timelines for oil and gas facility operators.
- EU Directives:Industrial Emissions Directive and F-Gas Regulation impose technology-forcing requirements that determine product eligibility across member states.
- ISO Standards:Measurement and verification protocols underpin cross-border data credibility and quality assurance alignment.
- Local Laws:National implementations create variation in enforcement granularity and reporting frequency requirements.
EU Directives drive standardization; Local Laws create customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors near-term deployment as shale operators retrofit pneumatic controllers with automated detection systems. Regulatory pressure from the EPA's methane performance standards compels capital allocation toward continuous monitoring infrastructure. Industrial clusters in Germany and the Netherlands accelerate procurement ahead of EU compliance checkpoints.
United States
Shale producers in Texas and New Mexico dominate hardware procurement for leak detection systems. EPA methane performance standards under the Clean Air Act mandate optical gas imaging surveys with strict repair timelines. The Permian Basin and Appalachian Basin witness concentrated retrofit cycles as operators replace legacy pneumatic infrastructure.
Germany
Power generators and steel mills drive demand for automated measurement systems ahead of Industrial Emissions Directive deadlines. The EU Green Deal implementation tightens monitoring requirements for large combustion plants. Industrial clusters in the Ruhr region and Bavaria accelerate procurement timelines to meet 2025 compliance checkpoints.
Netherlands
Refinery operators in the Rotterdam-Antwerp hub deploy tunable diode laser absorption spectroscopy at scale. EU F-Gas Regulation imposes technology-forcing requirements for fluorinated gas monitoring. The Port of Rotterdam industrial complex serves as a testbed for integrated continuous emissions monitoring with real-time transmission protocols.
China
State-owned oil majors and chemical conglomerates expand adoption of continuous monitoring platforms. The Ministry of Ecology and Environment enforces dual carbon goals through enhanced emissions reporting requirements. Industrial zones in the Yangtze River Delta and Pearl River Delta pilot IoT-enabled sensor networks for regulatory-grade verification.
Saudi Arabia
Aramco and downstream operators invest in predictive analytics platforms for fugitive emissions reduction. The national oil company mandates digital transformation across upstream and midstream assets. The Eastern Province industrial corridor concentrates deployment of cloud-native compliance dashboards tied to international certification standards.
Emission Management Market Competitive Landscape
Global majors compete with regional champions across technology integration depth and service contract duration. The vendor base clusters around three tiers: diversified industrial conglomerates with digital twin portfolios, specialized sensor manufacturers with optical analyzer expertise, and software-native platforms selling predictive analytics subscriptions. Consolidation pressure favors players bundling hardware procurement with long-term calibration and maintenance agreements. Strategic moves center on service unbundling to capture recurring revenue streams and geographic expansion into underpenetrated EU industrial clusters.
Within the diversified industrial tier, ABB Ltd and Siemens AG exemplify platform providers anchoring long-term service relationships across refinery networks. Thermo Fisher Scientific Inc. occupies a position among specialized analytical instrument manufacturers serving regulatory-grade certification requirements. These three companies represent distinct competitive archetypes: integrated control systems, digital twin portfolios, and high-precision optical analyzers respectively.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| AMETEK, Inc |
| Emerson Electric Company |
| Baker Hughes |
| Horiba Ltd |
| Fuji Electric Co., Ltd. |
| Rockwell Automation, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
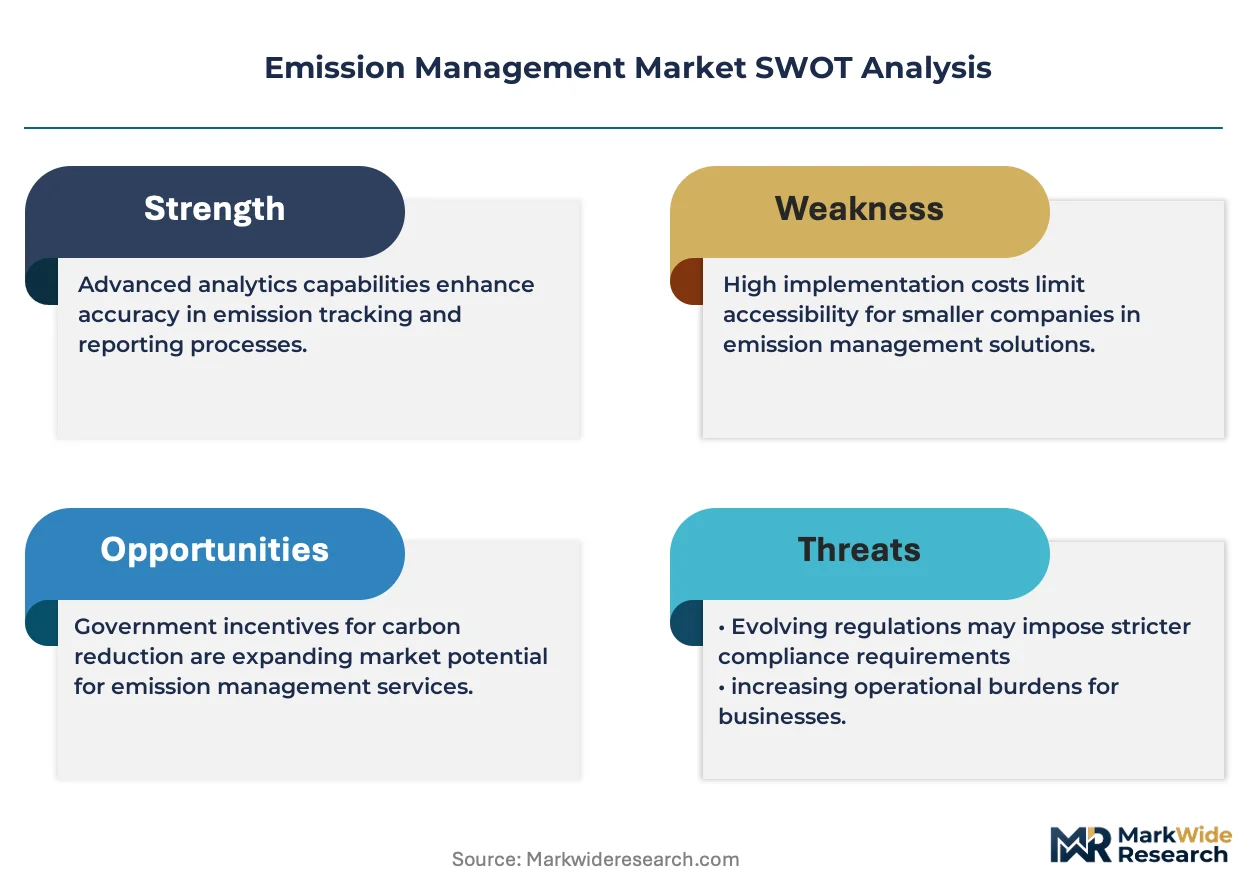
EPA-mandated optical gas imaging specifications are forcing mid-tier industrial buyers toward certified detection systems, compelling sensor manufacturers to absorb rare earth cost volatility while maintaining price accessibility for shale retrofit budgets.
Pricing Analysis
Input-cost pass-through from Chinese rare earth processing facilities and specialized optical component suppliers determines hardware pricing trajectories. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade certification systems from mid-tier industrial deployments and basic compliance modules. Cost compression in economy-tier sensors is intensifying because IoT-enabled device proliferation erodes standalone hardware margins. North American shale producers exhibit highest price sensitivity, favoring subscription-decoupled analytics, while EU power generators prioritize certification-grade systems with minimal cost elasticity.
Supply Chain Analysis
Reverse-logistics flows for optical analyzer refurbishment and electrochemical cell replacement create secondary service revenue streams for established vendors. Manufacturing concentration rests on China for rare earth element processing, Germany for precision optical components, and the United States for tunable diode laser assembly. Critical dependencies include neodymium-doped optical substrates, indium gallium arsenide detectors, and sapphire sensor windows. Single-source vulnerability from Chinese rare earth export controls threatens component availability. Distribution runs through authorized service networks that bundle calibration contracts with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The emission management market functions as a regulatory compounder where EPA methane performance standards and EU Industrial Emissions Directive deadlines create irreversible procurement cycles across energy and manufacturing sectors.
For Market Incumbents: Lock in long-term calibration and maintenance agreements with refinery operators before service unbundling fragments vendor relationships. Defensive consolidation through predictive analytics platform acquisitions counters specialized software vendors bypassing hardware commoditization. Capacity expansion in Poland and Romania addresses EU Green Deal implementation gaps before regional champions establish positions. For New Entrants and Emerging Players: Begin with AI-analytics subscriptions sold standalone to North American shale producers seeking operational flexibility without capital commitments to single suppliers. White-space concentration in Polish and Romanian industrial clusters offers lowest competitive density relative to German benchmarks. Government agency verification-grade procurement for carbon border adjustment mechanisms provides the most penetrable entry vector. For Investors and Strategic Acquirers: Asymmetric upside sits with software-native platforms possessing predictive maintenance modules that escape hardware margin compression. Five-to-ten year viability favors vendors bundling IoT sensor networks with cloud-native compliance dashboards. Acquisition target archetype: specialized optical analyzer manufacturers with ISO 17025-aligned quality assurance capabilities. Monitor EPA enforcement granularity and EU F-Gas Regulation technology-forcing updates as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Service Unbundling | Separates hardware procurement from analytics subscriptions to capture recurring revenue streams. |
| Geographic Expansion | Targets underpenetrated Polish and Romanian industrial clusters ahead of EU compliance deadlines. |
| AI Analytics Development | Builds predictive maintenance modules that bypass sensor hardware commoditization pressure. |
| Certification Investment | Secures ISO 17025 alignment for verification-grade systems serving carbon border mechanisms. |
| Platform Integration | Couples tunable diode laser hardware with cloud-native compliance dashboards for refinery networks. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with refinery operations directors, environmental compliance officers, sensor procurement managers, and calibration service technicians alongside secondary validation through EPA enforcement records, EU ETS transaction databases, SEC 10-K filings from industrial conglomerates, and customs data on optical component trade flows. Bottom-up installation base estimates triangulate against top-down regulatory mandate projections.
Rate-of-change decomposition separates volume growth from value migration across hardware, software, and service segments. The analytical framework models procurement patterns by product type, end-user sector, technology architecture, and regulatory compliance tier across the analysis window. CAGRs derive from facility retrofit cycle timing, compliance checkpoint schedules, and technology substitution curves for tunable diode laser absorption spectroscopy displacing electrochemical alternatives.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement moratoriums, rare earth export restriction escalations, and breakthrough detection technologies rendering current optical methods obsolete. Forecasts reflect assumptions about continued EPA methane rule durability and EU Industrial Emissions Directive implementation timelines. Practitioners should monitor EPA repair timeline enforcement patterns and EU carbon border adjustment mechanism technical documentation releases for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Emission Trading Schemes Market