
 Carbon Credit Trading Platform Market | 2026-2036
Carbon Credit Trading Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Credit Trading Platform Market Insights
Energy and heavy manufacturing procurement is consolidating around digital carbon credit infrastructure as Scope 3 tracking becomes a board-level priority. CME Group leverages its derivatives infrastructure to anchor North American voluntary carbon futures liquidity. Xpansiv competes through registry-agnostic API connectivity that spans multiple verification standards. Toucan Protocol differentiates via on-chain tokenization architecture that enables fractional retirement claims for smaller corporate buyers.
Carbon credit trading platforms are digital exchange infrastructure that matches buyers and sellers of verified emissions reductions, typically incorporating smart-contract settlement, automated registry reconciliation, and real-time price discovery across spot and forward instruments. Blockchain-based platform architecture is displacing manual over-the-counter workflows through immutable provenance tracking and atomic settlement, though hybrid models retain dominance where enterprise buyers require traditional custodial safeguards. Spot trading captures the deepest liquidity pool among trading models, while peer-to-peer structures are gaining traction among carbon offset developers seeking direct offtake relationships with corporate end-users.
The EU Green Deal and its accompanying CSRD disclosure mandates shape platform demand by forcing granular Scope 3 reporting across European supply chains. EPA greenhouse gas reporting protocols and California Air Resources Board cap-and-trade compliance obligations extend similar pressures across United States industrial participants. Stakeholders must monitor whether emerging jurisdictional registry standards fragment liquidity or converge toward interoperable verification protocols.
Market Dynamics
Scope 3 emissions disclosure mandates are forcing corporate procurement teams to abandon manual carbon accounting spreadsheets in favor of automated registry-reconciliation infrastructure. The shift compresses settlement cycles from weeks to minutes while embedding compliance directly into enterprise ERP systems.
Growth Catalysts
- EU Green Deal CSRD mandates:European supply chains must now track embedded emissions across Tier-2 and Tier-3 suppliers, driving demand for API-connected verification platforms that automate data ingestion from fragmented industrial sources.
- Heavy manufacturing decarbonization timelines:Steel, cement, and chemical producers face binding 2030 reduction targets that require immediate offtake of high-integrity carbon removals rather than conventional avoidance credits.
- Blockchain-based atomic settlement:Smart-contract infrastructure eliminates counterparty settlement risk and enables fractional credit retirement, opening voluntary markets to mid-market buyers previously excluded by minimum lot sizes.
Market Restraints
- Jurisdictional registry fragmentation:Divergent verification standards across Gold Standard, Verra, and emerging national registries create liquidity silos that complicate cross-border credit fungibility and price discovery.
- Verification bottleneck concentration:Third-party validation capacity concentrates among a handful of accredited bodies, creating multi-month queues that delay credit issuance and lock developer capital.
- Additionality assessment uncertainty:Evolving scientific consensus on baseline-setting methodologies threatens the legal defensibility of retired credits, exposing corporate buyers to reputational and regulatory clawback risk.
Strategic Opportunities
- India's voluntary carbon market emergence:The country's Bureau of Energy Efficiency carbon credit framework and corporate net-zero pledges create demand for localized trading infrastructure that bridges international standards with domestic verification.
- Carbon removal technology convergence:Direct air capture and biochar projects require long-dated offtake contracts that platforms can structure through tokenized forward instruments, unlocking institutional capital deployment.
- Supply chain Scope 3 data monetization:Industrial software vendors can embed carbon intensity metrics into procurement workflows, creating subscription revenue streams adjacent to transaction fees.
Industry Challenges
- Cross-functional talent scarcity:Platform operators struggle to hire professionals fluent in both environmental commodity markets and distributed systems engineering, slowing product development cycles.
- Legacy ERP integration complexity:Enterprise buyers demand seamless connectivity with SAP and Oracle environments, requiring expensive custom middleware that strains platform unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Credit Trading Platform Market |
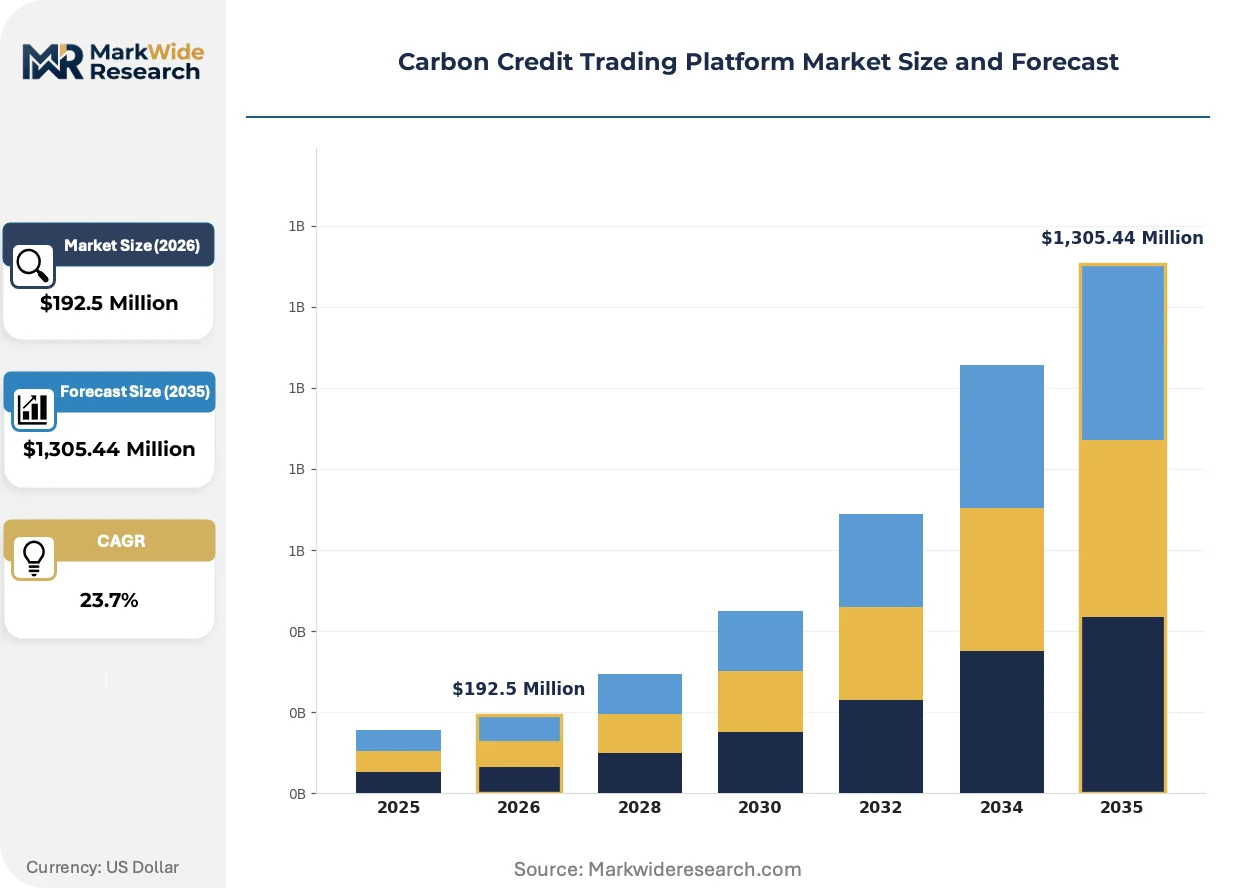
| Market Size in 2026 | $192.5 Million |
| Market Size in 2035 | $1,305.44 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Blockchain-based, Centralized, Decentralized, Hybrid User Type: Corporations, Governments, Environmental NGOs, Financial Institutions, Carbon Offset Developers Trading Model: Spot Trading, Forward Contracts, Auctions, Over-the-Counter, Peer-to-Peer Verification Method: Third-Party Audit, Automated Monitoring, Satellite Imaging, Self-Reporting |
| Companies Covered | CME Group, Carbon Trade Exchange (CTX), Xpansiv, Toucan Protocol, Carbonplace, AirCarbon Exchange (ACX), European Energy Exchange (EEX), Carbonmark, Intercontinental Exchange (ICE), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Credit Trading Platform Market Trends and Innovations
Digital infrastructure is collapsing the traditional separation between carbon credit origination, verification, and retirement. Automated pipeline tools now compress multi-month workflows into continuous settlement cycles that embed directly into corporate treasury operations.
On-chain tokenization architecture is electrifying carbon credit provenance tracking by creating immutable ownership records from project registration through final retirement. Corporate sustainability teams at industrial conglomerates are piloting these systems for 2025 compliance cycles, attracted by real-time audit trails that satisfy external assurance requirements. The technology is compressing due diligence timelines from quarters to weeks while enabling programmatic retirement scheduling that aligns with quarterly disclosure obligations.
California Air Resources Board cap-and-trade linkage negotiations with Quebec and Washington are creating cross-jurisdictional compliance instrument fungibility that extends platform addressable markets beyond single-state boundaries. Industrial facilities covered under multiple programs face complex position management requirements that favor centralized trading infrastructure over bilateral arrangements. Western US cement and refinery operators are consolidating procurement through platforms that automate regulatory submission formatting across divergent state reporting templates.
Corporate buyers are abandoning annual bulk credit purchases in favor of continuous procurement models that match retirement timing with monthly emissions calculations. This pattern disrupts traditional offtake structures that front-loaded developer revenue, forcing project sponsors toward platform-mediated spot markets or programmatic forward contracts. German automotive supply chains exhibit the most advanced adoption, where Tier-1 suppliers embed carbon cost pass-through mechanisms into component pricing that updates based on real-time credit indices.
Carbon Credit Trading Platform Market Segmentation
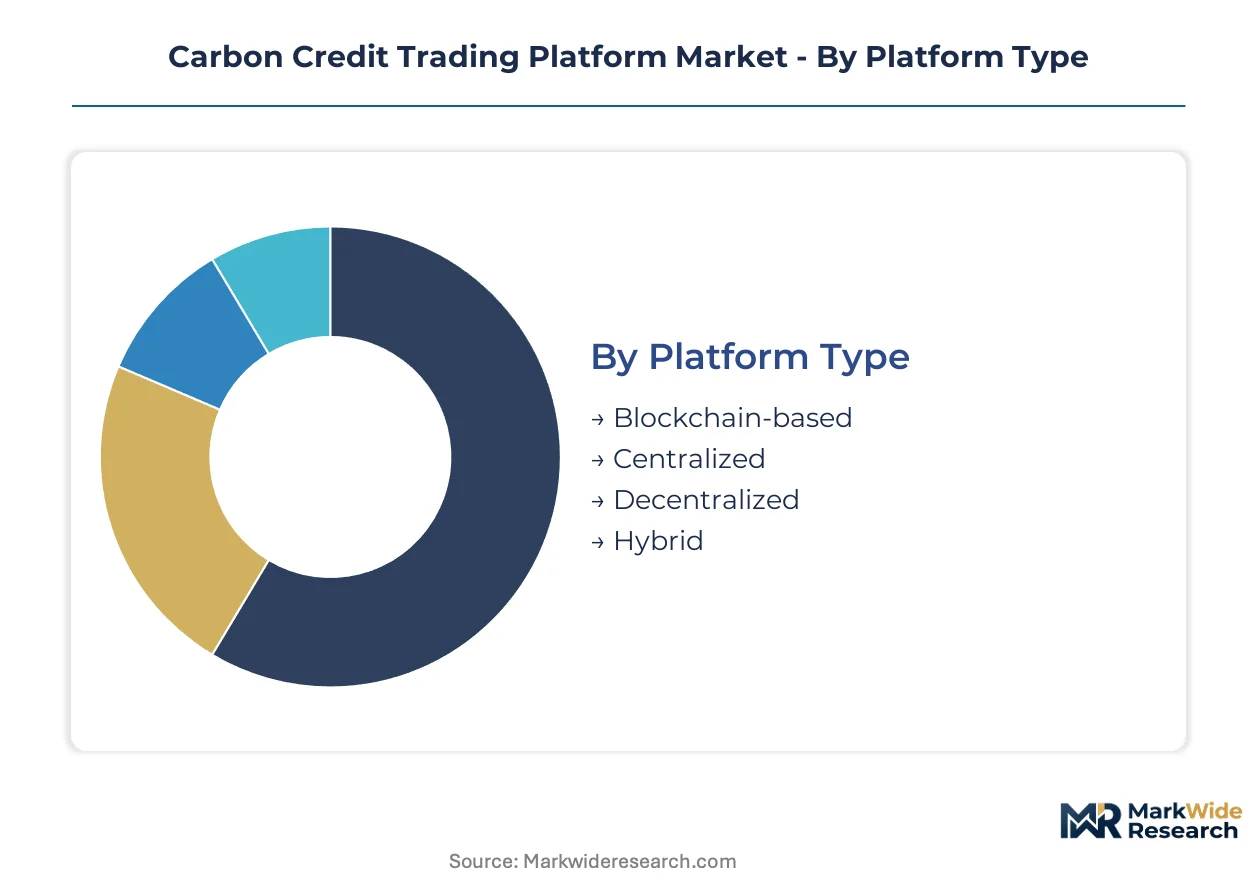
Carbon credit trading platforms fragment across four structural dimensions that determine buyer procurement workflows and platform architecture choices. Each segmentation axis carries distinct compliance implications and technology requirements that shape vendor competitive positioning.
Platform Type:
Enterprise procurement teams select platform architecture based on counterparty risk tolerance and audit trail requirements.
- Blockchain-based:Distributed ledger infrastructure creates immutable provenance records from project registration through retirement. German automotive suppliers and Dutch logistics operators pilot these systems for CSRD-compliant Scope 3 tracking.
- Centralized:Traditional exchange architecture with custodial asset management and regulated clearinghouse settlement. Heavy manufacturing buyers in regulated jurisdictions prefer these platforms for legal certainty and institutional-grade custody.
- Decentralized:Smart-contract matching without intermediary control, enabling permissionless access for smaller offset developers and mid-market corporate buyers.
- Hybrid:Combines on-chain settlement transparency with off-chain regulatory safeguards, bridging enterprise risk management needs with automation benefits.
Volume sits with centralized platforms; growth tilts toward hybrid architectures.
User Type:
Stakeholder category determines feature prioritization and contract structuring complexity.
- Corporations:Demand API connectivity into ERP systems and automated registry reconciliation for quarterly disclosure cycles. EU-based industrial conglomerates drive premium pricing for integrated compliance tooling.
- Financial Institutions:Seek derivatives infrastructure for carbon futures and options, requiring position management tools and cross-margining capabilities.
- Governments:Procure platforms for national registry administration and compliance market oversight, favoring sovereign data residency requirements.
- Environmental NGOs:Prioritize transparent pricing and project-level impact data for public accountability and donor reporting.
- Carbon Offset Developers:Require direct market access and forward contract structuring to secure project financing and offtake commitments.
Corporations generate the largest transaction volumes; carbon offset developers are expanding most quickly as project origination accelerates.
Trading Model:
Liquidity preferences and settlement timelines differentiate procurement patterns across instrument types.
- Spot Trading:Immediate delivery and settlement against verified registry holdings. Cement and steel producers in Germany and Poland use spot markets for urgent compliance gap filling.
- Forward Contracts:Fixed-price offtake agreements for future delivery, enabling direct air capture and biochar projects to secure long-dated financing.
- Auctions:Primary market issuance for government compliance instruments, with California Air Resources Board and RGGI states running scheduled allocation events.
- Over-the-Counter:Bilateral negotiation for large block trades and bespoke vintage requirements, retaining importance for sovereign buyers and major industrials.
- Peer-to-Peer:Direct matching between project developers and corporate end-users, reducing intermediary fees and enabling relationship-based offtake structures.
Spot trading commands the deepest liquidity; peer-to-peer structures are gaining share fastest among sustainability-focused supply chain initiatives.
Verification Method:
Integrity assurance mechanisms determine credit fungibility and buyer legal defensibility.
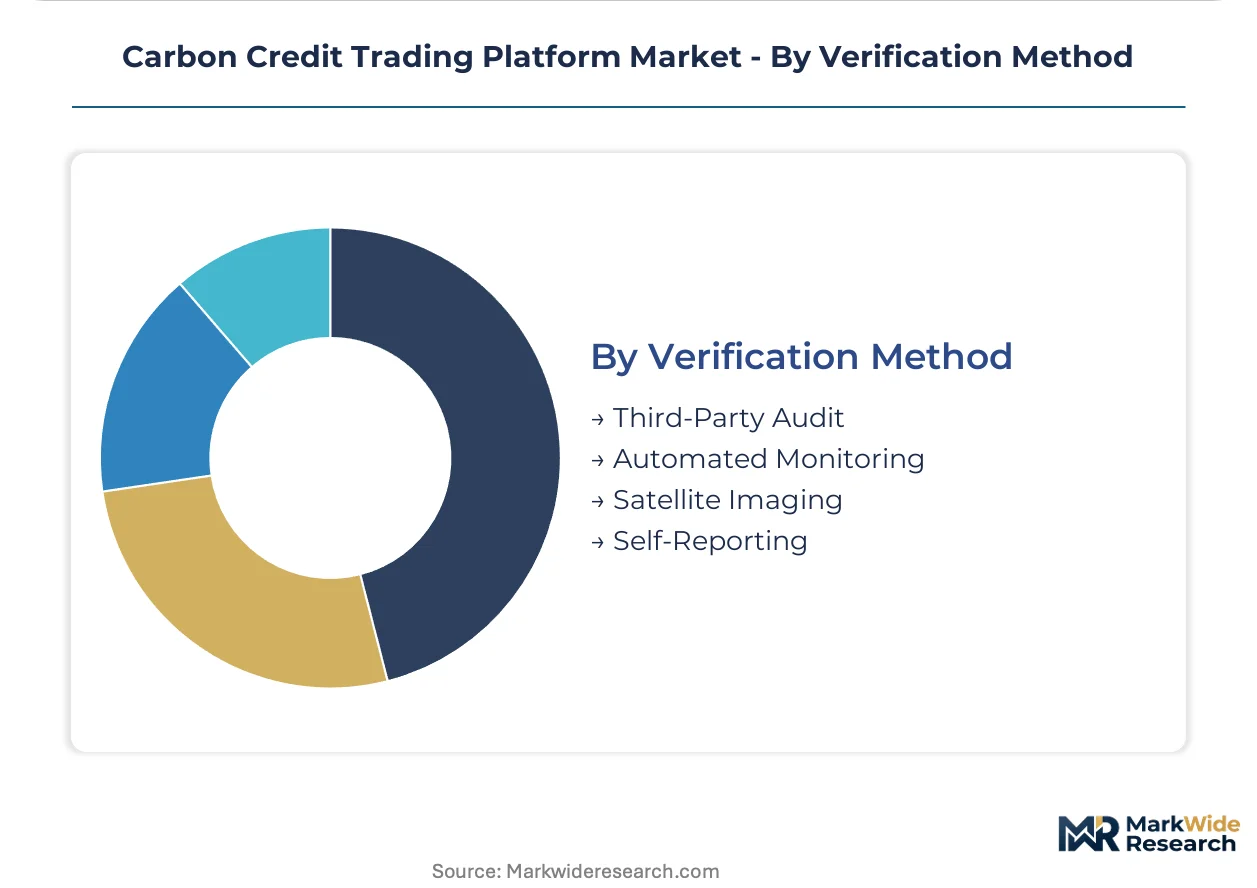
- Third-Party Audit:Accredited validation bodies conduct site visits and documentation review, remaining the standard for compliance-grade instruments under EU ETS and California cap-and-trade.
- Automated Monitoring:Sensor networks and IoT infrastructure provide continuous emissions data, reducing verification costs for industrial capture projects.
- Satellite Imaging:Remote sensing for forestry and land-use projects, enabling cost-effective coverage of dispersed geographic areas with machine-learning classification.
- Self-Reporting:Project developer-submitted data with post-hoc sampling verification, used primarily for pre-compliance voluntary credits with lower price points.
Third-party audit dominates transaction value; automated monitoring is climbing the fastest as sensor costs decline and methodology frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure concentrates in jurisdictions with mature compliance markets and binding corporate disclosure rules, while demand diffusion follows supply chain decarbonization mandates into industrial manufacturing clusters. Consumption patterns diverge between regulated cap-and-trade participants seeking legal certainty and voluntary buyers prioritizing fractional retirement flexibility.
United States
California cement and refinery operators drive demand for multi-jurisdictional compliance position management as the state's Air Resources Board negotiates linkage with Quebec and Washington. EPA greenhouse gas reporting protocols force Scope 1 disclosures across industrial facilities, embedding platform connectivity into enterprise ERP systems. Houston and Los Angeles house the densest concentrations of energy trading infrastructure.
Germany
Automotive supply chains embed carbon cost pass-through mechanisms into component pricing, with Tier-1 suppliers piloting real-time credit index updates. The EU Green Deal's CSRD mandates granular Scope 3 tracking across Tier-2 and Tier-3 suppliers, forcing procurement teams toward API-connected verification platforms. The Rhine-Ruhr industrial corridor exhibits the most advanced adoption of continuous procurement models.
United Kingdom
Financial institutions headquartered in London seek derivatives infrastructure for carbon futures and options, requiring cross-margining capabilities and position management tools. The country's post-EU carbon border adjustment mechanism shapes import-facing industrial demand for verified emissions documentation. The City of London anchors trading liquidity for voluntary carbon instruments.
India
Corporate net-zero pledges from energy and steel conglomerates create demand for localized trading infrastructure bridging international standards with domestic verification. The Bureau of Energy Efficiency carbon credit framework establishes methodological foundations for voluntary market expansion. Gujarat and Maharashtra industrial zones host pilot platform deployments for manufacturing supply chain tracking.
Singapore
Commodity trading houses leverage the jurisdiction's legal infrastructure for structuring long-dated offtake contracts for direct air capture and biochar projects. The Monetary Authority of Singapore's green finance taxonomy shapes platform compliance requirements for regional headquarters operations. The city-state serves as coordination hub for Southeast Asian carbon offset developer access to institutional capital.
Carbon Credit Trading Platform Market Competitive Landscape
Top-tier vendors anchor regulated exchange infrastructure, while specialized protocol developers and registry-agnostic intermediaries occupy distinct competitive tiers. Established financial exchanges leverage derivatives clearing capabilities to capture compliance-grade transaction flows. Three archetypes dominate: centralized exchanges with custodial safeguards, blockchain-native tokenization protocols, and API connectivity layers spanning multiple verification standards. Competitive moves concentrate on strategic partnerships with industrial software vendors and technology licensing for ERP integration middleware.
Within the exchange infrastructure tier, CME Group and Intercontinental Exchange exemplify institutional-grade derivatives architecture, while Xpansiv occupies a position as registry-agnostic connectivity infrastructure. Toucan Protocol represents the on-chain tokenization archetype enabling fractional retirement claims. European Energy Exchange anchors continental liquidity for compliance futures.
| Leading Market Players |
|---|
| CME Group |
| Carbon Trade Exchange (CTX) |
| Xpansiv |
| Toucan Protocol |
| Carbonplace |
| AirCarbon Exchange (ACX) |
| European Energy Exchange (EEX) |
| Carbonmark |
| Intercontinental Exchange (ICE) |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal CSRD disclosure mandates gate access to premium-tier platform modules by restricting API-connected verification workflows to providers with accredited registry interoperability. Heavy manufacturing procurement teams face tiered pricing barriers where automated Scope 3 tracking commands subscription premiums over manual spreadsheet alternatives.
Pricing Analysis
Margin tightening in the mid-market tier reflects verification bottleneck concentration and multi-month queue delays that lock developer capital. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-native settlement with real-time audit trails from centralized exchange custody and basic registry access. Cost compression accelerates in the standard tier as registry-agnostic API connectivity becomes commoditized. Carbon offset developers exhibit highest price sensitivity due to project financing constraints, while EU-based automotive conglomerates absorb premium pricing for CSRD-compliant ERP integration.
Supply Chain Analysis
Freight costs for sensor hardware and IoT infrastructure draw from concentrated manufacturing in Germany, China, and South Korea. Platform operators source blockchain node infrastructure, automated monitoring equipment, and enterprise middleware from these hubs. Single-source vulnerability concentrates in third-party validation capacity among accredited bodies. Distribution runs through direct SaaS deployment for enterprise buyers and API marketplace channels for mid-market accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform infrastructure is consolidating around providers with regulatory-grade registry interoperability as jurisdictional fragmentation forces weaker participants toward niche specialization or exit.
For Market Incumbents: Deploy backward integration into verification body partnerships to secure pipeline priority and reduce issuance queues that delay developer revenue. Anchor liquidity through long-dated offtake contract structuring for direct air capture projects, defending against registry-agnostic entrants with fractional tokenization capabilities. For New Entrants and Emerging Players: Automated satellite imaging verification for forestry credits offers the most penetrable wedge against incumbent audit-dependent workflows. Target India's Bureau of Energy Efficiency framework adoption by localizing API connectivity for domestic steel and energy conglomerates. Pursue channel partnerships with industrial software vendors embedding carbon intensity metrics into procurement workflows. For Investors and Strategic Acquirers: California-Quebec-Washington linkage completion is the leading indicator that multi-jurisdictional compliance position management will concentrate platform demand. Five-to-ten year viability favors hybrid architecture providers bridging on-chain settlement transparency with off-chain regulatory safeguards. Watch for Gold Standard-Verra methodological convergence as signal of liquidity unification enabling scale acquisitions.| Strategic Initiative | Industry Significance |
|---|---|
| Registry Interoperability Certification | Unlocks EU ETS and California cap-and-trade compliance-grade transaction flows. |
| ERP Integration Middleware Development | Captures SAP and Oracle procurement workflow embedding for automotive supply chains. |
| Verification Body Capacity Partnership | Reduces multi-month validation queues threatening developer project financing. |
| Tokenized Forward Instrument Launch | Structures long-dated offtake for direct air capture and biochar capital deployment. |
| India Localization Infrastructure | Bridges international standards with Bureau of Energy Efficiency domestic verification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with platform engineering leads, carbon offset developer finance officers, corporate sustainability procurement directors, and registry operations managers provided qualitative validation. SEC disclosures from exchange infrastructure providers, EPA greenhouse gas reporting protocols, EU ETS transaction registries, and California Air Resources Board compliance submissions supplied quantitative benchmarks. Bottom-up transaction volume modeling and top-down market sizing triangulated across these sources.
Granularity-level modeling segmented by platform architecture type, user category, trading instrument, and verification methodology across the projection horizon. Platform type splits captured blockchain-based, centralized, decentralized, and hybrid infrastructure adoption curves. User modeling distinguished corporate ERP integration requirements from financial institution derivatives needs and offset developer direct access preferences. CAGRs derived from regression analysis against compliance mandate implementation timelines and corporate net-zero pledge acceleration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under jurisdictional registry fragmentation or verification methodology disputes threatening credit fungibility. Forecasts reflect assumptions around CSRD disclosure enforcement consistency and California linkage negotiation completion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market