
 Smart Carbon Market | 2026-2036
Smart Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Carbon Market Analytics
The EU Green Deal is realigning procurement priorities across European industrial supply chains. Schneider Electric leverages its energy management platform to anchor enterprise carbon tracking services. SAP competes through embedded emissions accounting within its ERP architecture. ENGIE sustains project development pipelines across biogas and reforestation offset origination.
Smart carbon denotes digitally traceable carbon assets—offset credits, renewable energy certificates, and emissions allowances—registered on distributed ledgers with immutable issuance and retirement records, typically quantified in tonnes of carbon dioxide equivalent for compliance or voluntary neutralization purposes. Blockchain-based verification infrastructure commands premium pricing due to fraud-resistant provenance tracking, while AI Analytics segments grow fastest as buyers demand predictive portfolio optimization. Carbon Offset Credits remain the volume leader, though Carbon Futures attract speculative capital seeking price exposure.
The European Securities and Markets Authority, the EU's F-Gas Regulation, and ISO 14064 standards collectively shape product integrity requirements and market access conditions for cross-border credit trading. The US SEC climate disclosure rules and China's MEE emissions trading protocols extend this regulatory density into additional jurisdictions. Stakeholders must monitor interoperability standards between national registries as fragmentation risk threatens liquidity formation.
Market Dynamics
Blockchain-based verification infrastructure is compressing settlement timelines and collapsing fraud exposure across voluntary carbon markets, while the EU Green Deal tightens supply chain emissions accountability.
Growth Catalysts
- CSRD disclosure mandates:European manufacturers must report Scope 3 emissions, forcing procurement teams to source verified offset instruments with immutable provenance records.
- AI Analytics adoption:Enterprise buyers deploy predictive portfolio optimization tools to stress-test carbon credit valuations against price volatility and regulatory changes.
- German industrial corridor concentration:Steel and chemical producers in the Ruhr and Rhine regions anchor demand for high-integrity carbon removal credits.
Market Restraints
- Registry fragmentation:Interoperability gaps between national carbon registries in Germany, France, and the Netherlands threaten liquidity formation and price discovery.
- Verification cost inflation:Third-party audit fees for ISO 14064-compliant project validation have risen substantially, squeezing margins for smaller offset developers.
- Spot market illiquidity:Thin secondary trading volumes for nature-based credits concentrate price-setting power among a handful of large financial institutions.
Strategic Opportunities
- Carbon Futures instruments:Derivatives exchanges in London and Amsterdam are launching standardized contracts, attracting speculative capital seeking price exposure without physical delivery.
- Biogas project pipelines:Agricultural methane capture installations in Denmark and the Netherlands qualify for premium pricing under EU F-Gas Regulation compliance pathways.
- Embedded ERP accounting:Enterprise software architectures now integrate emissions tracking modules, creating captive demand for automated credit retirement workflows.
Industry Challenges
- Blockchain talent scarcity:Smart contract developers with domain expertise in environmental asset tokenization command premium compensation, constraining platform buildouts.
- Legacy system integration:Industrial emitters struggle to reconcile distributed ledger retirement records with existing enterprise resource planning systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Carbon Market |
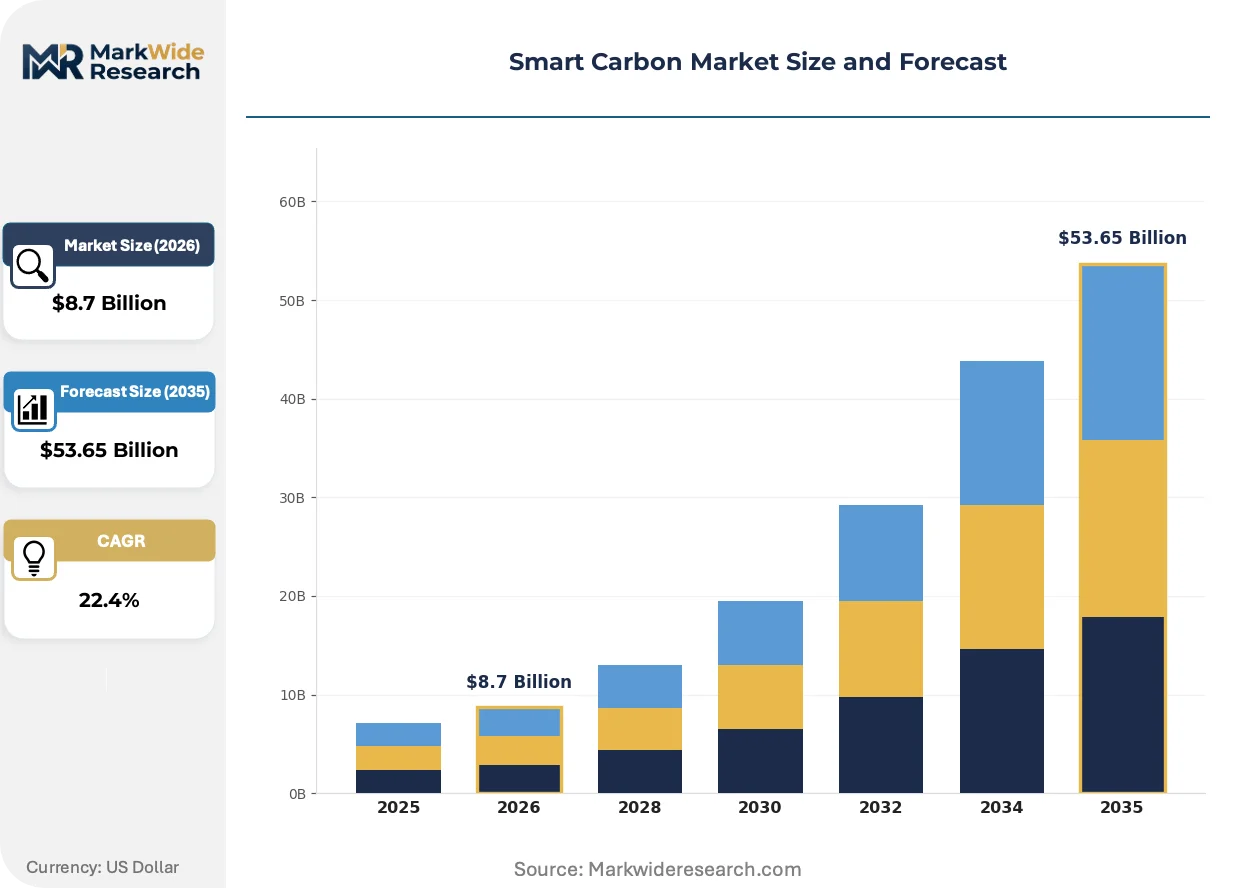
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Offset Credits, Renewable Energy Certificates, Carbon Futures, Emissions Allowances Technology: Blockchain, AI Analytics, Cloud Computing, IoT Sensors End User: Corporations, Governments, NGOs, Financial Institutions Service Type: Consulting, Verification, Trading Platforms, Auditing |
| Companies Covered | Schneider Electric, SAP, IBM, Salesforce, ENGIE, South Pole, ClimatePartner, Verra, Gold Standard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Carbon Market Evolving Landscape
Digitally native verification methods are compressing issuance timelines and collapsing the cost structure of carbon credit provenance tracking across European markets.
Automated Measurement, Reporting, and Verification (MRV) systems using satellite imagery and IoT sensors is overtaking manual site audits for reforestation and soil carbon projects. Forestry developers in Sweden and Finland deploy drone-based biomass monitoring to slash verification cycles from months to weeks. This compression is overtaking traditional audit firms' pricing power and forcing adaptation of service models.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon emissions, redirecting industrial compliance spending toward verified destruction credit purchases. Chemical manufacturers in Belgium and the Netherlands now procure these credits as operational hedges against quota scarcity. The regulation is compressing project development timelines for gas capture facilities.
Enterprise procurement teams now specify immutable retirement proof as a contractual requirement, displacing paper-based certificate handoffs. Technology sector buyers in Ireland and Germany lead this specification shift, embedding verification API access into supplier scorecards. This behavioral pivot concentrates contract awards on platforms with real-time ledger transparency.
Smart Carbon Market Segmentation
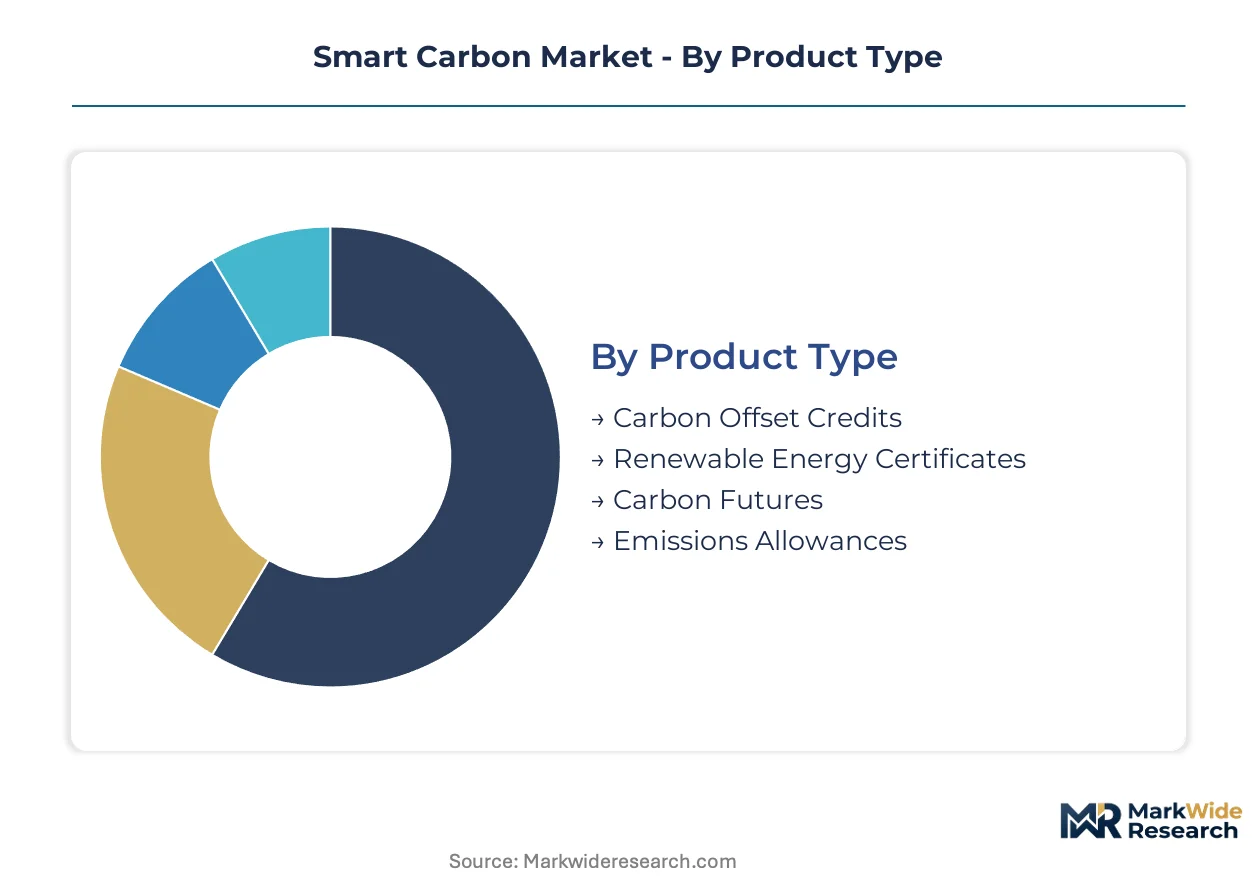
Segmentation in the Smart Carbon Market reflects divergent buyer priorities across compliance obligations, risk management needs, and operational integration requirements. Procurement teams select instruments based on regulatory jurisdiction, settlement speed, and provenance verification standards rather than commodity pricing alone.
Product Type:
Corporate buyers prioritize instrument liquidity and retirement flexibility when allocating carbon procurement budgets across voluntary and compliance markets.
- Carbon Offset Credits:Digitally traceable tonnes of CO2 equivalent from verified removal or avoidance projects, registered on distributed ledgers with immutable issuance records. Demand concentrates among German steel and chemical manufacturers seeking Scope 3 neutralization under CSRD disclosure mandates.
- Carbon Futures:Standardized derivative contracts traded on exchanges in London and Amsterdam, enabling price exposure without physical credit delivery. Financial institutions in the Netherlands deploy these instruments for portfolio hedging against voluntary carbon price volatility.
- Renewable Energy Certificates:Tradable proof of electricity generation from renewable sources, often bundled with carbon claims for corporate sustainability reporting.
- Emissions Allowances:Compliance market permits issued under cap-and-trade schemes, primarily acquired by utilities and heavy industry for regulatory surrender obligations.
Carbon Offset Credits lead on scale; Carbon Futures leads on momentum.
Technology:
Technology selection determines settlement speed, audit cost structure, and interoperability with legacy enterprise systems.
- Blockchain:Distributed ledger infrastructure providing immutable provenance tracking and automated retirement verification for carbon assets. Premium pricing persists due to fraud-resistant issuance records demanded by technology sector buyers in Ireland and Germany.
- AI Analytics:Predictive portfolio optimization tools stress-testing credit valuations against regulatory changes and price volatility. Corporations in Denmark deploy these systems for dynamic offset procurement timing.
- Cloud Computing:Scalable infrastructure for carbon registry operations and real-time transaction settlement.
- IoT Sensors:Automated data collection devices for project-level emissions monitoring and verification automation.
Blockchain dominates current contract value; AI Analytics is climbing the fastest.
End User:
End user category reflects divergent procurement authority, risk tolerance, and integration complexity requirements.
- Corporations:Voluntary and compliance-motivated buyers across manufacturing, technology, and energy sectors. Procurement teams in Germany's Ruhr industrial corridor anchor demand for high-integrity removal credits with immutable retirement proof.
- Financial Institutions:Banks, asset managers, and trading houses seeking carbon market exposure through futures, options, and spot trading. Amsterdam-based derivatives exchanges attract speculative capital for standardized contract trading.
- Governments:Public sector entities procuring offsets for operational neutrality or compliance market administration.
- NGOs:Non-governmental organizations originating and retiring credits for conservation or development objectives.
Corporations anchor procurement volume; Financial Institutions drive trading liquidity expansion.
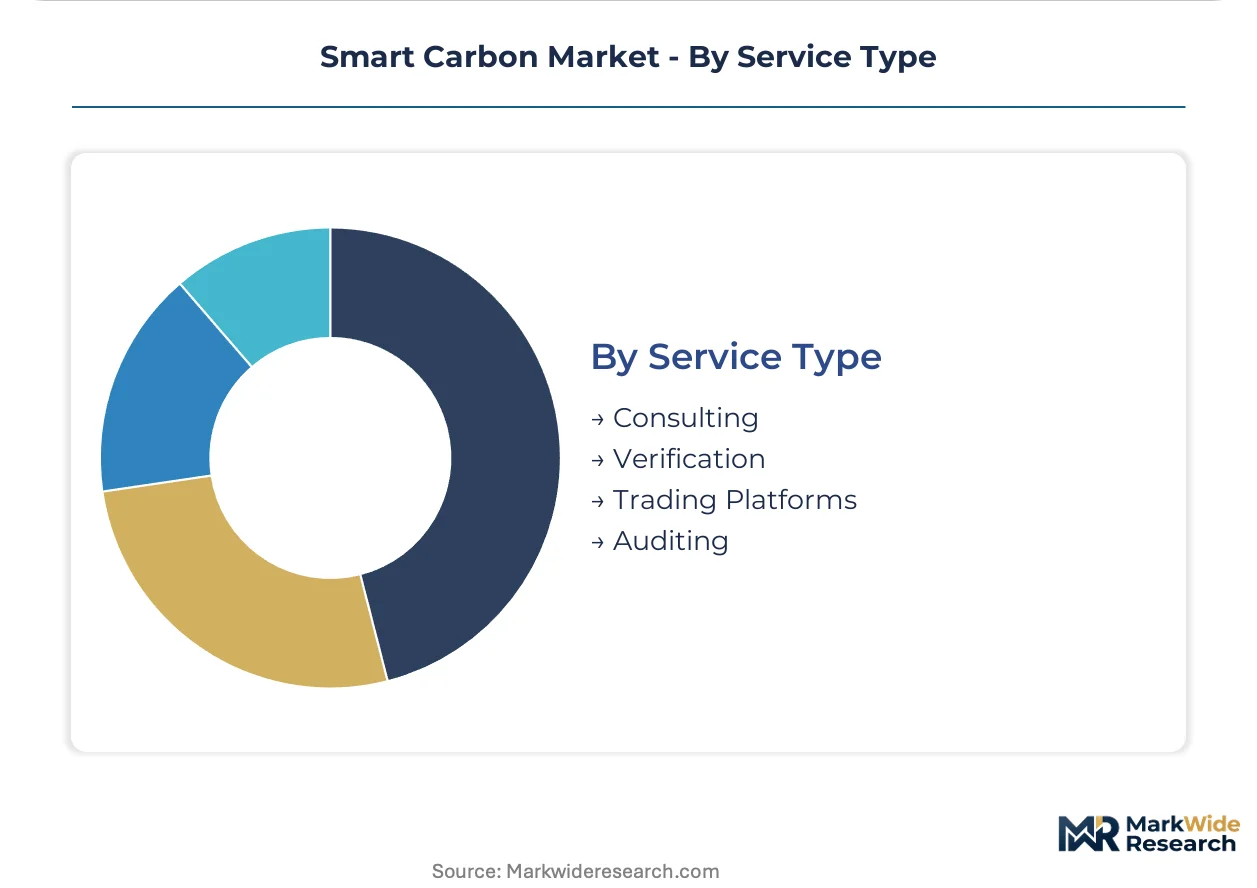
Service Type:
Service procurement decisions hinge on audit credibility, platform interoperability, and automation depth for credit lifecycle management.
- Verification:Third-party validation and verification of carbon project methodologies against ISO 14064 and registry standards. Audit fees have inflated substantially, compressing margins for smaller offset developers in Sweden and Finland.
- Trading Platforms:Digital marketplaces and exchange infrastructure for spot and forward carbon credit transactions. London and Amsterdam exchanges are launching standardized futures contracts to attract institutional participation.
- Consulting:Advisory services for carbon strategy development, project origination, and regulatory compliance navigation.
- Auditing:Independent assurance of emissions inventories and offset retirement claims for disclosure reporting.
Verification commands the highest per-transaction fees; Trading Platforms are gaining share fastest through automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart carbon industry traces its commercial origins to European carbon trading infrastructure established under the Kyoto Protocol mechanisms, with early registry development concentrated in Switzerland and Germany before blockchain verification platforms scaled through Ireland's technology corridor.
Germany
Steel and chemical manufacturers in the Ruhr and Rhine regions anchor demand for high-integrity removal credits with immutable retirement proof. The CSRD disclosure mandates force procurement teams to source verified offset instruments for Scope 3 reporting. Berlin-based software integrators embed carbon tracking modules into enterprise ERP architectures.
United Kingdom
Financial institutions in the City of London deploy carbon futures for portfolio hedging against voluntary market price volatility. The Financial Conduct Authority oversees emerging derivatives exchange infrastructure for standardized contracts. Edinburgh's fintech cluster develops predictive analytics tools for credit valuation stress-testing.
Netherlands
Amsterdam-based derivatives exchanges attract speculative capital seeking price exposure without physical credit delivery. The EU F-Gas Regulation redirects industrial compliance spending toward verified destruction credits from chemical manufacturers. Rotterdam's port logistics sector pilots blockchain-based supply chain emissions tracking.
France
ENGIE sustains biogas and reforestation project development pipelines across agricultural methane capture installations. The national energy regulator enforces compliance pathway eligibility for premium-priced offset instruments. Lyon and Grenoble anchor carbon software development clusters serving enterprise buyers.
Sweden
Forestry developers deploy drone-based biomass monitoring to compress verification cycles from months to weeks. The Swedish Energy Agency administers renewable energy certificate issuance with distributed ledger integration. Stockholm's technology sector leads procurement specifications demanding immutable retirement proof APIs.
Smart Carbon Market Competitive Landscape
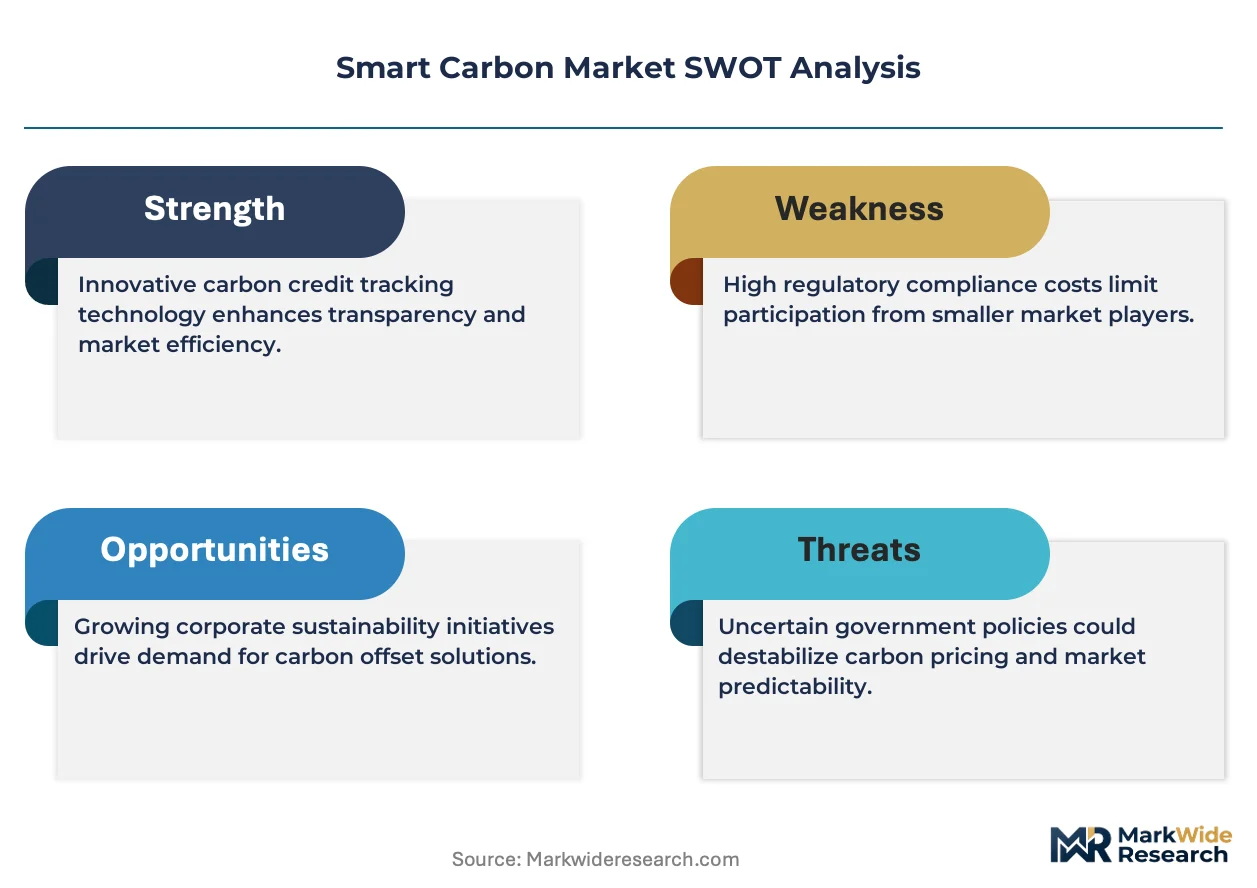
Capital-heavy infrastructure developers compete with asset-light software platforms for procurement budget allocation across enterprise carbon management. The market structure bifurcates between project originators with physical asset pipelines and digital verification platforms with scalable technology stacks. Three archetypes dominate: energy majors with captive offset development, enterprise software vendors with embedded emissions accounting, and specialized registries with blockchain-based issuance infrastructure. Competitive moves concentrate on strategic partnerships between software platforms and project developers, plus vertical integration into verification services to capture margin from audit fee inflation.
Among energy-sector developers with integrated project pipelines, ENGIE exemplifies the infrastructure-heavy archetype combining biogas capture with reforestation origination. Within the enterprise software tier, Schneider Electric and SAP occupy positions anchoring carbon tracking services to existing energy management and ERP customer bases. These three represent distinct strategic postures: physical asset ownership, platform ecosystem leverage, and embedded workflow integration.
| Leading Market Players |
|---|
| Schneider Electric |
| SAP |
| IBM |
| Salesforce |
| ENGIE |
| South Pole |
| ClimatePartner |
| Verra |
| Gold Standard |
| Others |
Value Network & Pricing Analysis
Blockchain-based verification infrastructure is simultaneously compressing issuance cost structures and redistributing pricing power toward platforms with immutable provenance capabilities. The technology shift collapses traditional audit firm margins while concentrating premium capture among digitized registry operators serving CSRD-mandated buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with blockchain-verified credits commanding substantial markups over paper-based certificates. Price differentiation hinges on ISO 14064 certification tier and real-time retirement API access, with technology sector buyers in Ireland and Germany showing lowest sensitivity. Cost compression in the standard tier is intensifying because verification fee inflation squeezes smaller offset developers. Manufacturing procurement teams in Germany's Ruhr corridor exhibit highest price sensitivity due to volume procurement mandates.
Supply Chain Analysis
Freight and logistics costs for physical project monitoring equipment and personnel deployment represent substantial cost drivers for verification-dependent supply chains. Geographic supply concentrates in Germany, France, and the Netherlands, with project origination pipelines drawing from Denmark's agricultural methane capture installations and Sweden's forestry biomass operations. Raw material dependencies span drone monitoring hardware, IoT sensor arrays, and satellite imagery subscriptions. Single-source vulnerability runs through concentrated third-party audit provider networks. Distribution runs through Amsterdam and London derivatives exchanges for financial buyers, with direct platform access for enterprise procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate on platforms achieving verification cost deflation through automated MRV systems while capturing premium pricing from immutable retirement proof specifications.
For Market Incumbents: To counter blockchain talent scarcity constraining platform buildouts, incumbents should secure captive supply of smart contract developers through specialized hiring pipelines in Ireland's technology corridor. Backward integration into drone-based biomass monitoring equipment reduces verification cycle dependencies on external hardware vendors. Certification investment in EU F-Gas Regulation compliance pathways secures premium pricing access for biogas destruction credits. For New Entrants and Emerging Players: Launch via embedded ERP accounting modules targeting mid-cap manufacturers in the Netherlands and Belgium lacking in-house carbon tracking capabilities. White-space availability concentrates in automated retirement workflow integration for procurement teams without API infrastructure. Agricultural methane capture project origination in Denmark offers penetrable supply concentration against established energy majors. Direct-to-enterprise sales through sustainability consulting partnerships bypasses exchange liquidity requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among verification-heavy service providers facing audit fee margin compression without technology differentiation. Long-term viability favors platforms combining physical project pipelines with digitized issuance infrastructure. Acquisition target archetype: regional registries with distributed ledger integration but limited enterprise sales capacity. The signal to watch is interoperability standard adoption between national carbon registries as fragmentation resolution catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Registry Integration | Immutable provenance tracking commands premium pricing from CSRD-mandated German manufacturers. |
| Automated MRV Deployment | Drone-based biomass monitoring compresses verification cycles for Swedish forestry developers. |
| ERP Embedded Accounting | SAP and Schneider Electric architectures create captive demand for automated credit retirement workflows. |
| Carbon Futures Exchange Launch | Amsterdam and London standardized contracts attract speculative capital seeking price exposure. |
| Biogas Project Pipeline Expansion | EU F-Gas Regulation compliance pathways redirect Belgian chemical manufacturer spending toward destruction credits. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carbon procurement officers at German steel and chemical manufacturers, sustainability directors at technology sector buyers, registry platform engineers, and third-party verification auditors with secondary validation. Sources included EU ETS transaction databases, ISO 14064 certification registries, CSRD disclosure filings, and project development pipeline trackers. Bottom-up credit volume tallies and top-down enterprise spending estimates were triangulated for consistency.
Comparable historical periods anchored growth rate derivation across the modeling period, with segmentation dimensions spanning product type, verification technology, end-user category, and service type. CAGRs were computed from fitted trend lines adjusted for regulatory inflection points. Forecast inputs incorporated CSRD implementation timelines, EU F-Gas Regulation phasedown schedules, and blockchain interoperability standard adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under registry fragmentation persistence or verification cost acceleration scenarios. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology adoption rates. A model refresh is warranted upon material change in EU Green Deal implementation pace or interoperability standard ratification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market