
 Voluntary Carbon Credits Market | 2026-2036
Voluntary Carbon Credits Market Size, Share, and Industry Trends Forecast 2026-2036
Voluntary Carbon Credits Market Insights
Capital-intensity divergence between registry operators and project developers is redrawing competitive boundaries in voluntary carbon markets. Verra leverages its Verified Carbon Standard infrastructure to sustain dominance in issuance volume across nature-based categories. Gold Standard Foundation anchors its position through rigorous sustainable development co-benefit requirements that differentiate its credit portfolio.
Voluntary carbon credits represent transferable instruments certifying quantified greenhouse gas reductions or removals, typically denominated in tonnes of CO2 equivalent and verified against third-party standards for permanence, additionality, and leakage prevention. Nature-based solutions currently command premium pricing due to co-benefit complexity and verification costs, while renewable energy credits face margin compression as the power sector decarbonizes and additionality thresholds tighten. Corporations drive end-user demand as Scope 3 supply chain accounting requirements expand liability exposure across value chains.
The EU Green Deal's Carbon Border Adjustment Mechanism and CSRD disclosure rules shape European corporate procurement patterns, while California's cap-and-trade linkage and Washington's Climate Commitment Act create compliance-adjacent demand spillovers into voluntary markets. ISO 14064-2 project quantification standards and the Integrity Council for the Voluntary Carbon Market's Core Carbon Principles now define baseline market access requirements. Stakeholders must monitor evolving permanence definitions and reversal buffer mechanisms as scientific consensus and buyer sophistication reshape credit quality hierarchies.
Market Dynamics
EU Green Deal disclosure mandates are restructuring buyer-producer power dynamics in voluntary carbon markets. The EU's CSRD rules now compel Scope 3 accounting across technology sector supply chains, redirecting procurement toward high-integrity credit categories with verifiable co-benefits.
Growth Catalysts
- CSRD Corporate Mandates:European disclosure rules now require granular Scope 3 emissions reporting, forcing technology firms into long-term offtake agreements with nature-based project developers.
- Brazil Amazon Restoration:Project concentration in the Amazon basin leverages existing monitoring infrastructure and indigenous land tenure frameworks to accelerate issuance timelines.
- Remote Sensing Verification:Satellite-based MRV systems are collapsing due diligence costs for forest carbon projects, expanding the addressable project pipeline.
Market Restraints
- Registry Concentration Risk:Verra's dominance in Verified Carbon Standard issuance creates single-point-of-failure exposure for buyers dependent on its methodology updates.
- Permanence Uncertainty:Wildfire and drought risks in fire-prone biomes are elevating reversal buffer requirements and insurance costs for nature-based credits.
- Renewable Energy Credit Compression:Grid decarbonization and tightening additionality tests are eroding margins for wind and solar offset projects.
Strategic Opportunities
- Soil Carbon Protocols:Agricultural carbon sequestration methodologies remain underdeveloped relative to forest carbon, offering first-mover positioning for regenerative farming aggregators.
- California Cap-and-Trade Linkage:Compliance market spillover demand creates premium pricing corridors for credits meeting both voluntary and compliance-grade specifications.
- Blockchain Settlement Rails:Tokenized carbon credit registries are enabling fractional ownership and automated retirement, opening retail and SME buyer segments.
Industry Challenges
- Methodology Revision Lag:Science-based updates to baseline calculations and leakage accounting are forcing project developers into costly re-verification cycles.
- Cross-Border Transfer Friction:Divergent national tax treatments and import restrictions on carbon credits complicate multinational corporate procurement consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voluntary Carbon Credits Market |
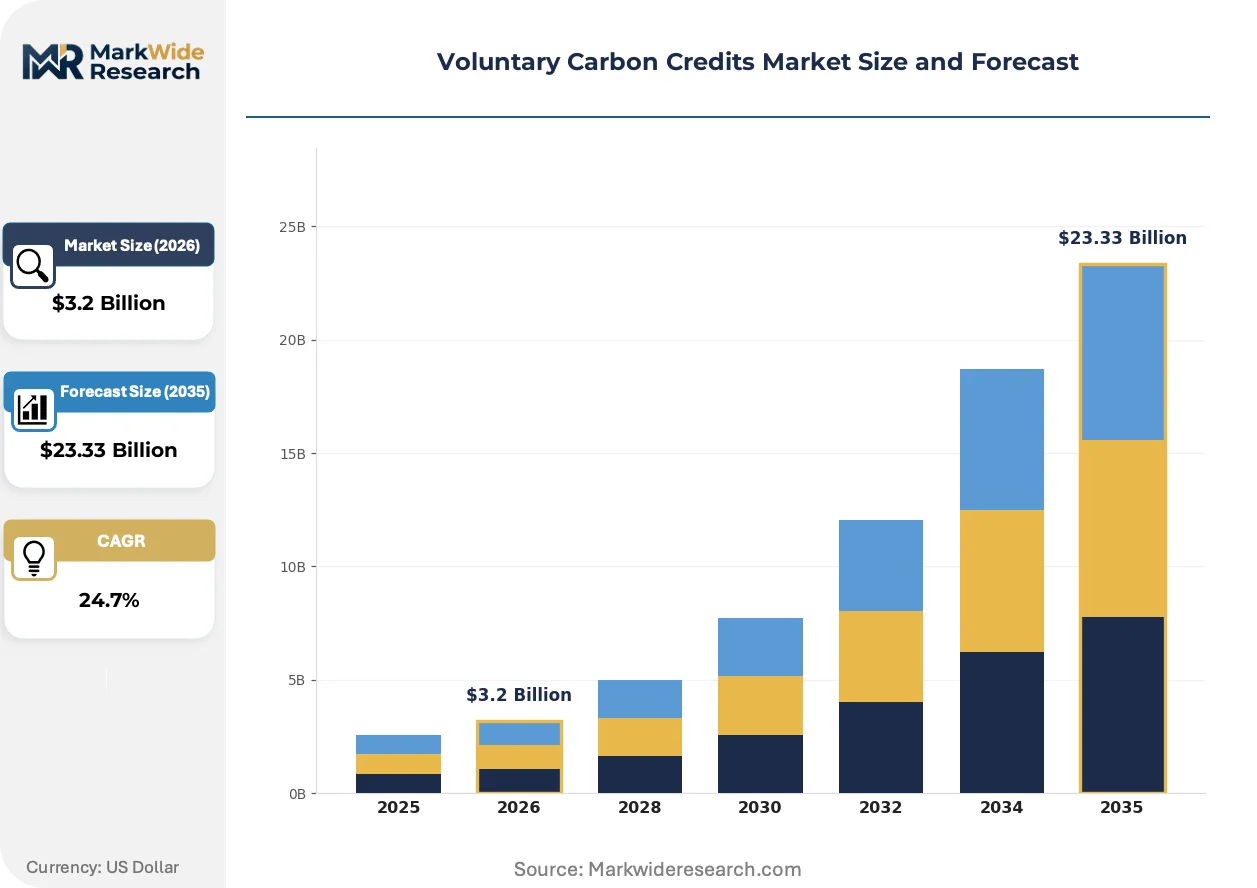
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $23.33 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Nature-Based, Renewable Energy, Energy Efficiency, Waste Management End User: Corporations, Non-Governmental Organizations, Government Agencies, Individuals Certification: Verra, Gold Standard, American Carbon Registry, Plan Vivo Carbon Footprint: Scope 1, Scope 2, Scope 3, Life Cycle Assessment |
| Companies Covered | Verra, Gold Standard Foundation, American Carbon Registry, Climate Action Reserve, South Pole, EcoSecurities, Puro.earth, Biofílica Ambipar, Xpansiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voluntary Carbon Credits Market Trends and Innovations
Verification technology and buyer sophistication are compressing the gap between premium nature-based credits and commoditized renewable energy offsets. Three developments are accelerating this restructuring.
Remote sensing platforms integrating LiDAR and hyperspectral imaging are displacing field-based biomass measurement for forest carbon projects. Gold Standard Foundation and Verra are both piloting satellite-only verification pathways for REDD+ initiatives. This compression in monitoring costs is enabling smaller landowners to access carbon finance previously gated by field survey expenses.
The EU's Carbon Border Adjustment Mechanism is reshaping import competitiveness for carbon-intensive goods entering European markets. Steel, cement, and aluminum producers in Turkey, Ukraine, and South Korea are now procuring voluntary credits to demonstrate embedded emissions reductions ahead of 2026 full implementation. This regulatory pull is elevating demand for industrial process carbon capture credits with ISO 14064-2 quantification.
Corporate buyers are consolidating procurement through specialized carbon credit funds and aggregators rather than direct project engagement. Technology sector sustainability teams in Seattle, Amsterdam, and Singapore are outsourcing due diligence to specialist intermediaries with embedded legal and scientific expertise. This channel shift is concentrating buyer power and squeezing margins for project developers lacking direct corporate relationships.
Voluntary Carbon Credits Market Segmentation
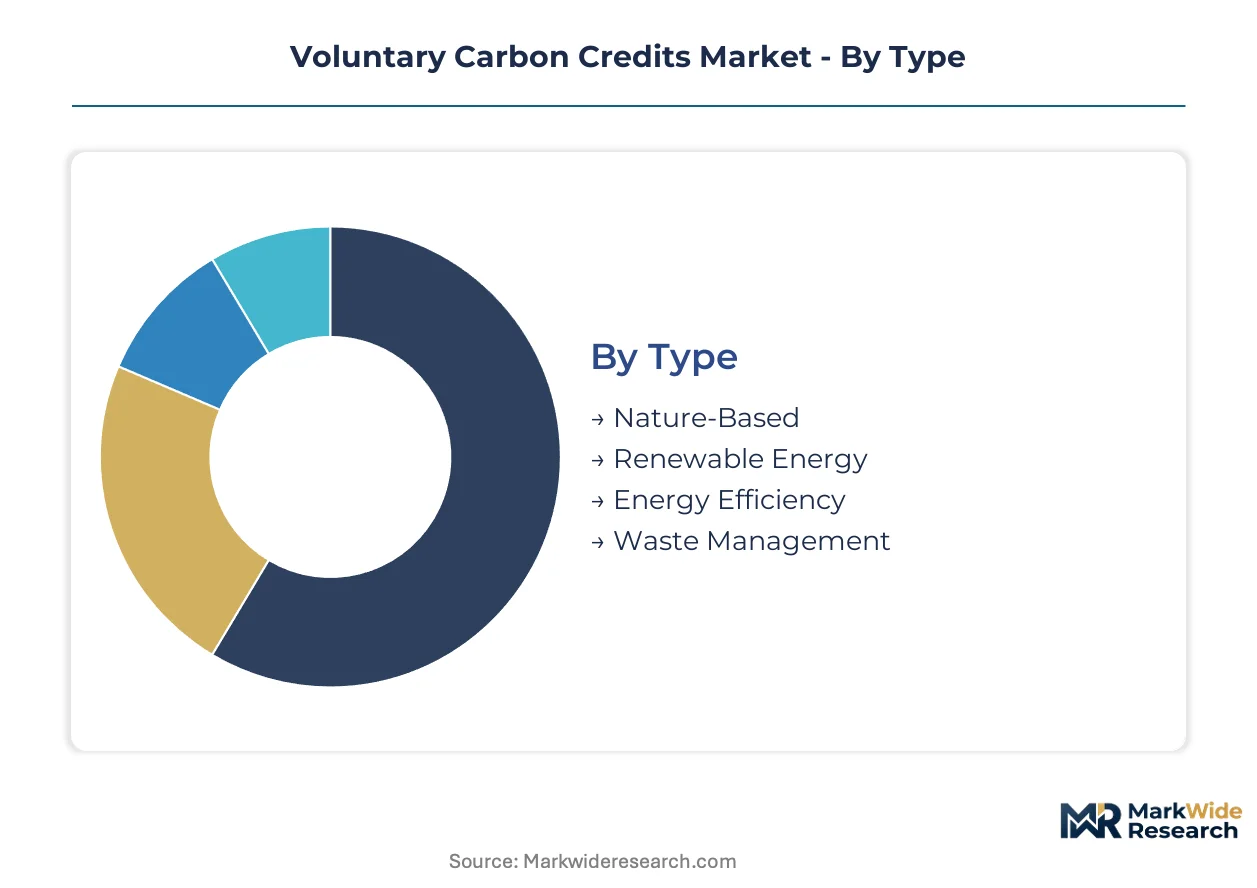
Segmentation in voluntary carbon markets determines credit pricing tiers, buyer procurement strategies, and registry methodology alignment. Distinct credit categories face divergent substitution pressures from compliance market instruments and internal abatement alternatives.
Type:
Renewable Energy credits face the most acute substitution threat as grid decarbonization erodes their additionality claims and corporate buyers pivot to harder-to-abate categories.
- Nature-Based:Forest conservation, reforestation, and soil carbon projects generate credits through biological sequestration with 20-100 year permanence horizons. Brazil's Amazon basin concentrates issuance volume as indigenous land tenure frameworks accelerate project development timelines.
- Renewable Energy:Wind, solar, and hydro displacement credits certify avoided grid emissions through clean power generation. Additionality thresholds from EU Green Deal disclosure mandates are compressing demand as buyers question whether projects would proceed without carbon finance.
- Energy Efficiency:Industrial process and building retrofit credits capture emissions reductions from fuel switching and demand optimization. Manufacturing clusters in Turkey and South Korea are procuring these credits to demonstrate embedded emissions reductions ahead of EU Carbon Border Adjustment Mechanism implementation.
- Waste Management:Methane capture from landfills and anaerobic digesters converts potent greenhouse gases into tradable offsets. Agricultural waste-to-energy projects leverage existing biogas infrastructure to lower verification costs.
Nature-Based anchors the volume base while Energy Efficiency gains share at the steepest rate as industrial process credits attract compliance-adjacent demand.
End User:
Procurement scale separates institutional buyers with dedicated sustainability teams from fragmented individual participation.
- Corporations:Technology sector sustainability teams in Seattle, Amsterdam, and Singapore drive the largest offtake volumes as CSRD Scope 3 accounting requirements expand liability exposure. These buyers consolidate procurement through specialized carbon credit funds with embedded scientific and legal expertise.
- Non-Governmental Organizations:Conservation-focused NGOs purchase credits to neutralize operational footprints and demonstrate organizational commitment. Their procurement prioritizes co-benefit verification over cost minimization.
- Government Agencies:Subnational jurisdictions including California and Washington state procure voluntary credits to supplement compliance market positions. Their purchases create premium pricing corridors for dual-use credits meeting both voluntary and compliance-grade specifications.
- Individuals:Retail buyers access fractional credit ownership through tokenized registries and automated retirement platforms. Blockchain settlement rails are collapsing minimum purchase thresholds that previously gated participation.
Corporations dominate absolute demand while Individuals expand most quickly as retail accessibility improves.
Certification:
Registry concentration risk elevates the strategic importance of methodology diversification across buyer portfolios.
- Verra:Verified Carbon Standard infrastructure sustains dominance in issuance volume across nature-based categories. Single-point-of-failure exposure intensifies as buyers become dependent on its methodology update cycles.
- Gold Standard:Rigorous sustainable development co-benefit requirements differentiate its credit portfolio and command premium pricing from ESG-focused procurement teams. The foundation pilots satellite-only verification pathways for REDD+ initiatives.
- American Carbon Registry:North American project focus with established methodologies for forestry and livestock methane. California cap-and-trade linkage creates compliance-adjacent demand spillovers.
- Plan Vivo:Community-based carbon certification emphasizing smallholder participation and local livelihood co-benefits. Indigenous land tenure frameworks in Latin America align with its participatory design principles.
Verra anchors the volume base while Gold Standard climbs the fastest as buyer sophistication reshapes quality hierarchies.
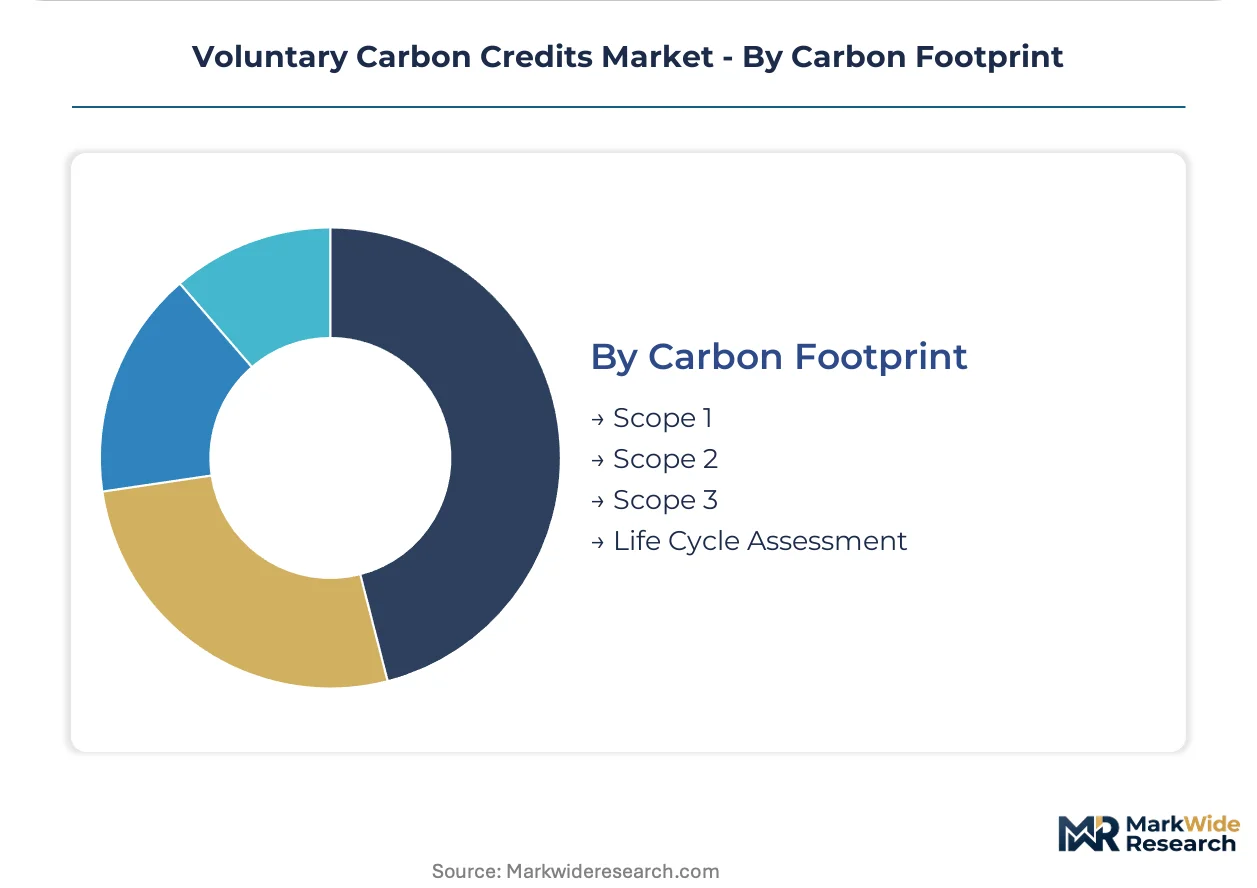
Carbon Footprint:
Regulatory disclosure mandates are restructuring demand concentration across emissions accounting categories.
- Scope 1:Direct emissions from owned or controlled sources including stationary combustion and industrial processes. Manufacturing facilities in carbon-intensive sectors procure credits to neutralize process emissions.
- Scope 2:Indirect emissions from purchased electricity, heat, or steam. Grid decarbonization is reducing offset demand as renewable energy procurement displaces market-based accounting.
- Scope 3:All other indirect emissions across upstream and downstream value chains. EU CSRD rules now compel granular reporting, forcing technology firms into long-term offtake agreements with nature-based project developers.
- Life Cycle Assessment:Comprehensive cradle-to-grave emissions quantification for products and services. Steel, cement, and aluminum producers use LCA-aligned credits to demonstrate embedded emissions reductions.
Scope 3 anchors the volume base while Life Cycle Assessment gains share at the steepest rate as product-level carbon accounting matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in voluntary carbon credits tilts toward Brazil's Amazon basin, where indigenous land tenure frameworks compress project development timelines, while European buyers under EU Green Deal mandates absorb premium markups for high-integrity nature-based credits.
United States
California's cap-and-trade market generates compliance-adjacent demand spillovers into voluntary channels. The EPA's stationary source regulations and Washington's Climate Commitment Act create dual-use credit corridors. Seattle-based technology sustainability teams consolidate procurement through specialized carbon funds with embedded scientific expertise.
Brazil
The Amazon basin concentrates nature-based project issuance as monitoring infrastructure and indigenous partnerships accelerate verification. Brazil's national climate framework and ANVISA-aligned environmental protocols shape project eligibility. São Paulo and Belém clusters host project developers leveraging satellite-based MRV systems to collapse due diligence costs.
Germany
Industrial process carbon capture credits attract steel and cement producers preparing for EU Carbon Border Adjustment Mechanism implementation. The EU Green Deal's CSRD disclosure rules compel granular Scope 3 reporting. The Ruhr industrial corridor and Hamburg trading hubs channel procurement toward ISO 14064-2 quantified removals.
United Kingdom
London's financial services sector anchors carbon credit fund structuring and aggregator consolidation. The UK's post-Brexit carbon accounting standards and FCA disclosure requirements reshape buyer due diligence. The City of London and Edinburgh clusters concentrate specialized intermediaries with legal and scientific embedded expertise.
Singapore
Southeast Asian headquarters for technology sector procurement teams drive offtake agreements with nature-based developers. Singapore's Monetary Authority guidelines on climate risk disclosure and green finance taxonomy align voluntary credit demand with regional project pipelines. The Marina Bay financial district hosts sustainability teams outsourcing verification to specialist aggregators.
Voluntary Carbon Credits Market Competitive Landscape
Concentration sits with registry operators whose methodology infrastructure governs market access. Verra's Verified Carbon Standard sustains dominance in issuance volume across nature-based categories, while Gold Standard Foundation commands premium positioning through rigorous sustainable development co-benefit requirements. Strategic moves center on satellite-only verification pathway pilots and blockchain settlement rail integration for fractional ownership enablement.
Within the registry operator tier, Verra and Gold Standard Foundation exemplify divergent competitive positioning—volume leadership versus premium differentiation—while South Pole occupies a position bridging project development and corporate advisory. Xpansiv represents the exchange-architecture archetype, anchoring digital infrastructure for credit trading and retirement automation. These three entities collectively illustrate how market structure fragments across methodological authority, project origination, and settlement technology layers.
| Leading Market Players |
|---|
| Verra |
| Gold Standard Foundation |
| American Carbon Registry |
| Climate Action Reserve |
| South Pole |
| EcoSecurities |
| Puro.earth |
| Biofílica Ambipar |
| Xpansiv |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between technology sector procurement teams and Brazil-based project developers lock in supply access and price visibility across 10-20 year horizons, insulating buyers from spot market volatility while securing developer financing for Amazon basin restoration initiatives.
Pricing Analysis
The customization-premium spread between Gold Standard-certified credits with verified sustainable development co-benefits and standard Verra-issued instruments spans significant price differentials driven by certification rigor and buyer ESG mandates. Three-tier pricing structure across premium, standard, and economy levels reflects methodology stringency, with nature-based solutions commanding top-tier positioning due to co-benefit complexity. Pricing pressure stems from renewable energy credit compression as grid decarbonization erodes additionality claims. Corporate buyers with CSRD disclosure obligations show least price sensitivity, while retail participants accessing tokenized fractional ownership exhibit highest elasticity.
Supply Chain Analysis
Brazil and Indonesia anchor nature-based credit origination through forest conservation and peatland restoration projects, while the United States and United Kingdom concentrate registry infrastructure and carbon fund structuring. Project development draws from satellite-based MRV systems, indigenous land tenure partnerships, and third-party verification auditor networks. Single-source vulnerability concentrates in Verra's methodology infrastructure dominance. Distribution runs through specialized carbon credit funds and aggregators with embedded legal and scientific expertise rather than direct project engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Voluntary carbon credit incumbents face substitution defense imperatives against internal abatement investments and compliance market instruments that corporate buyers may prioritize as integrity scrutiny intensifies.
For Market Incumbents: Consolidate procurement relationships with technology sector sustainability teams in Seattle, Amsterdam, and Singapore through multi-year offtake structures that preempt competitive displacement. Deepen backward integration into satellite-based MRV infrastructure to collapse verification costs and accelerate issuance timelines. Defensive positioning against Gold Standard's premium differentiation requires co-benefit quantification investments that match its sustainable development rigor. For New Entrants and Emerging Players: Lead with soil carbon protocol development in agricultural regions where methodologies remain underdeveloped relative to forest carbon standards. Target regenerative farming aggregators in North American grain belts and Australian rangelands as the most penetrable white space. Go-to-market positioning should emphasize blockchain settlement rails enabling fractional ownership and automated retirement for retail and SME buyer segments. For Investors and Strategic Acquirers: Specialist carbon credit aggregators with embedded legal and scientific expertise represent the most defensible acquisition archetype as buyer consolidation concentrates intermediary power. Long-term viability across the projection horizon hinges on methodology diversification beyond Verra concentration risk. Monitor permanence definition evolution and reversal buffer mechanism changes as the critical inflection signal for credit quality hierarchy reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite-Only Verification Pathway | Gold Standard and Verra piloting LiDAR-hyperspectral MRV collapses field survey costs for REDD+. |
| Blockchain Settlement Rail Integration | Tokenized registries enable fractional ownership and automated retirement for retail participation. |
| Soil Carbon Protocol Development | Agricultural sequestration methodologies unlock first-mover positioning in regenerative farming. |
| California Cap-and-Trade Linkage | Dual-use credit corridors create premium pricing for voluntary-compliance grade convergence. |
| Indigenous Land Tenure Partnership | Brazil's Amazon frameworks accelerate project timelines through established monitoring infrastructure. |
Research Methodology
The analysis maps nature-based solutions, renewable energy credits, energy efficiency instruments, and waste management offsets, each validated through registry methodology leads, project developer executives, corporate sustainability procurement officers, and carbon fund structuring specialists. Primary interview intelligence triangulates against Verra and Gold Standard methodology documentation, EU CSRD regulatory filings, EPA stationary source databases, and ANVISA-aligned environmental protocols. Bottom-up project pipeline quantification reconciles with top-down corporate disclosure mandate analysis.
Consistency checks validated volume and value outputs against external benchmarks including registry issuance databases and corporate offtake announcement tracking. The analytical framework segments by credit type, end user archetype, certification standard, and carbon footprint accounting category across the projection horizon. CAGRs derive from project pipeline build rates, methodology expansion timelines, and buyer procurement consolidation patterns. Forecast inputs incorporate EU Carbon Border Adjustment Mechanism implementation phasing and remote sensing verification cost compression curves.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, indigenous partnership stability in Brazil, or satellite MRV technology adoption would require recalibration. Forecasts reflect assumptions around methodology update cycles, permanence definition stability, and corporate Scope 3 liability expansion. Recalibration cycles align with material shifts in CSRD disclosure stringency and integrity council principle adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Carbon Credit Market