
 Asia-Pacific Carbon Dioxide Market | 2026-2036
Asia-Pacific Carbon Dioxide Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Carbon Dioxide Market Analytics
Enhanced oil recovery operators are reorganizing procurement priorities across the Asia-Pacific Carbon Dioxide Market, displacing traditional food-grade buyers as the dominant volume archetype. Air Liquide leverages integrated ammonia-carbon capture complexes along China's eastern seaboard to secure feedstock autonomy. Linde PLC sustains liquefaction capacity leadership through cold-chain infrastructure investments in India and Southeast Asia. TAIYO NIPPON SANSO CORPORATION anchors premium gaseous CO2 supply to Japanese semiconductor fabs and precision welding clusters.
Carbon dioxide is a colorless, non-flammable gas with a boiling point of minus 78.5 degrees Celsius at standard pressure, recovered primarily through ammonia synthesis off-gas purification, ethanol fermentation, or direct air capture for industrial applications spanning carbonation, refrigeration, chemical synthesis, and tertiary crude extraction. Liquid Carbon Dioxide dominates value pools due to cryogenic transport economics and bulk storage requirements across chemical manufacturing and beverage bottling networks. Supercritical Carbon Dioxide represents the fastest-expanding product category, driven by solvent replacement in pharmaceutical extraction and dry-cleaning applications across South Korea and Australia. Gaseous Carbon Dioxide retains mature, stable demand from metal fabrication shielding gas and wastewater pH neutralization.
China's MEE enforces mandatory carbon capture utilization thresholds for coal-to-chemical complexes, while Japan's METI subsidizes CCUS demonstration projects through green innovation funds. India's BIS certifies food-grade CO2 purity standards for beverage applications, creating compliance barriers for unorganized suppliers. Stakeholders must monitor how Australia's TGA therapeutic goods standards and South Korea's MFDS pharmaceutical-grade specifications reshape qualification requirements for supercritical extraction-grade product.
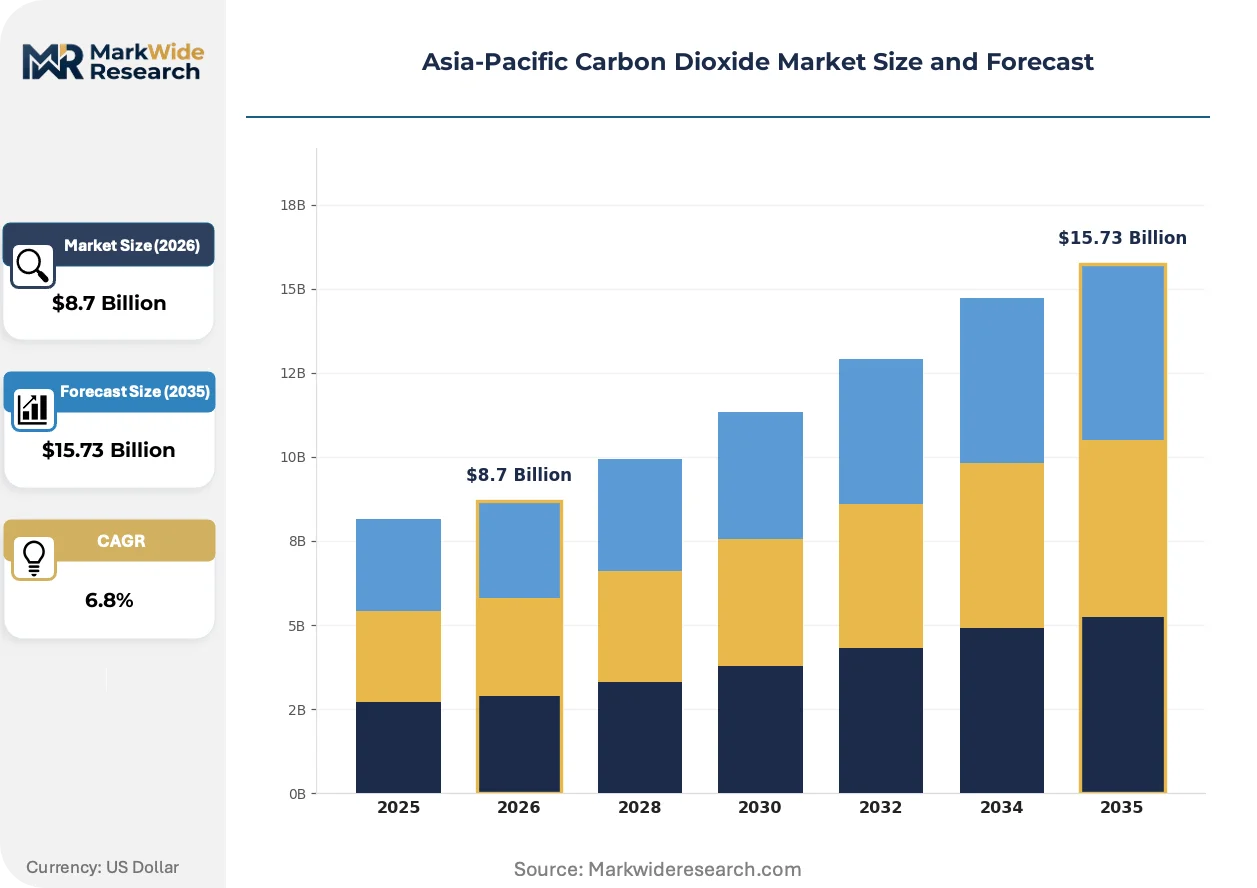
Market Dynamics
China's MEE carbon capture mandates are compressing supply timelines for coal-to-chemical complexes, forcing industrial gas operators to reconfigure purification capacity ahead of utilization thresholds. This regulatory pressure is redrawing competitive boundaries across the Asia-Pacific Carbon Dioxide Market.
Growth Catalysts
- Enhanced Oil Recovery:Tertiary crude extraction projects in eastern China's chemical corridor anchor bulk offtake volumes. Operators prioritize CO2 flood systems for mature reservoir pressure maintenance.
- METI Efficiency Mandates:Japan's green innovation funds subsidize CCUS demonstration infrastructure. Industrial gas suppliers capture demonstration-scale contracts with qualifying emission reduction credentials.
- Food-Grade Certification:India's BIS purity standards for beverage carbonation create compliance barriers. Organized suppliers consolidate market position against unorganized competitors lacking certification infrastructure.
Market Restraints
- Feedstock Concentration Risk:Ammonia synthesis off-gas dominates regional CO2 recovery. Dependence on fertilizer plant operating rates creates supply volatility during agricultural demand cycles.
- Transport Cost Structure:Cryogenic liquid CO2 requires specialized tanker fleets and bulk storage terminals. Last-mile distribution economics limit viable supply radius for small-volume buyers.
- Direct Air Capture Cost:DAC technology remains 3-4x more expensive than industrial off-gas recovery. Capital intensity constrains deployment to subsidy-eligible demonstration projects only.
Strategic Opportunities
- Supercritical Extraction:South Korea's MFDS pharmaceutical-grade specifications enable solvent replacement in API manufacturing. Suppliers qualify product for high-purity extraction contracts.
- Cold-Chain Infrastructure:India and Southeast Asia underinvest in liquefaction capacity. Greenfield terminal investments capture import substitution value as regional food processing expands.
- Semiconductor Shield Gas:Japanese fabs require ultra-high-purity gaseous CO2 for precision welding clusters. Premium pricing persists for qualified suppliers with fab-direct delivery capability.
Industry Challenges
- Cryogenic Engineering Talent:Specialized technicians for liquefaction plant operation and maintenance remain scarce across the region. Training pipeline lags capacity expansion timelines.
- Multi-Jurisdiction Certification:Suppliers must simultaneously maintain China's GB standards, Japan's JIS specifications, and Australia's TGA therapeutic goods compliance. Documentation overhead compresses margin on cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Carbon Dioxide Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Carbon Dioxide, Gaseous Carbon Dioxide, Solid Carbon Dioxide, Supercritical Carbon Dioxide Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets End User: Food & Beverage Industry, Chemical Manufacturing, Oil Recovery, Metal Production Application: Carbonation, Refrigeration, Fire Extinguishing, Enhanced Oil Recovery |
| Companies Covered | Air Liquide, Linde PLC, TAIYO NIPPON SANSO CORPORATION, Air Products and Chemicals, Inc., Messer SE & Co. KGaA, Coregas, Cosmo Engineering Co., Ltd., SS GASLAB ASIA PVT. LTD., Sicgil India Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Carbon Dioxide Market Evolving Landscape
Process intensification and purity-grade segmentation are fragmenting traditional supply contracts across the Asia-Pacific Carbon Dioxide Market. Buyers now specify application-matched product tiers rather than accepting commodity-grade uniformity.
Membrane-based CO2 separation is supplanting amine scrubbing in small-scale ethanol fermentation recovery. Australian winemakers and craft distillers adopt skid-mounted membrane units for on-site carbon capture. Distributed production models erode bulk terminal economics in rural supply zones.
China's dual carbon goals tighten MEE enforcement timelines for coal-to-chemical complexes. Mandatory utilization thresholds force emitters to contract with industrial gas processors or face production curtailments. Liquid CO2 suppliers with integrated capture infrastructure secure multi-year offtake agreements.
Spot purchasing contracts displace annual volume commitments among mid-size beverage bottlers. Procurement teams optimize working capital through just-in-time delivery apps linking tanker fleets to consumption sensors. This purchasing model concentrates in Vietnam and Thailand where third-party logistics platforms have digitized last-mile scheduling.
Asia-Pacific Carbon Dioxide Market Segmentation
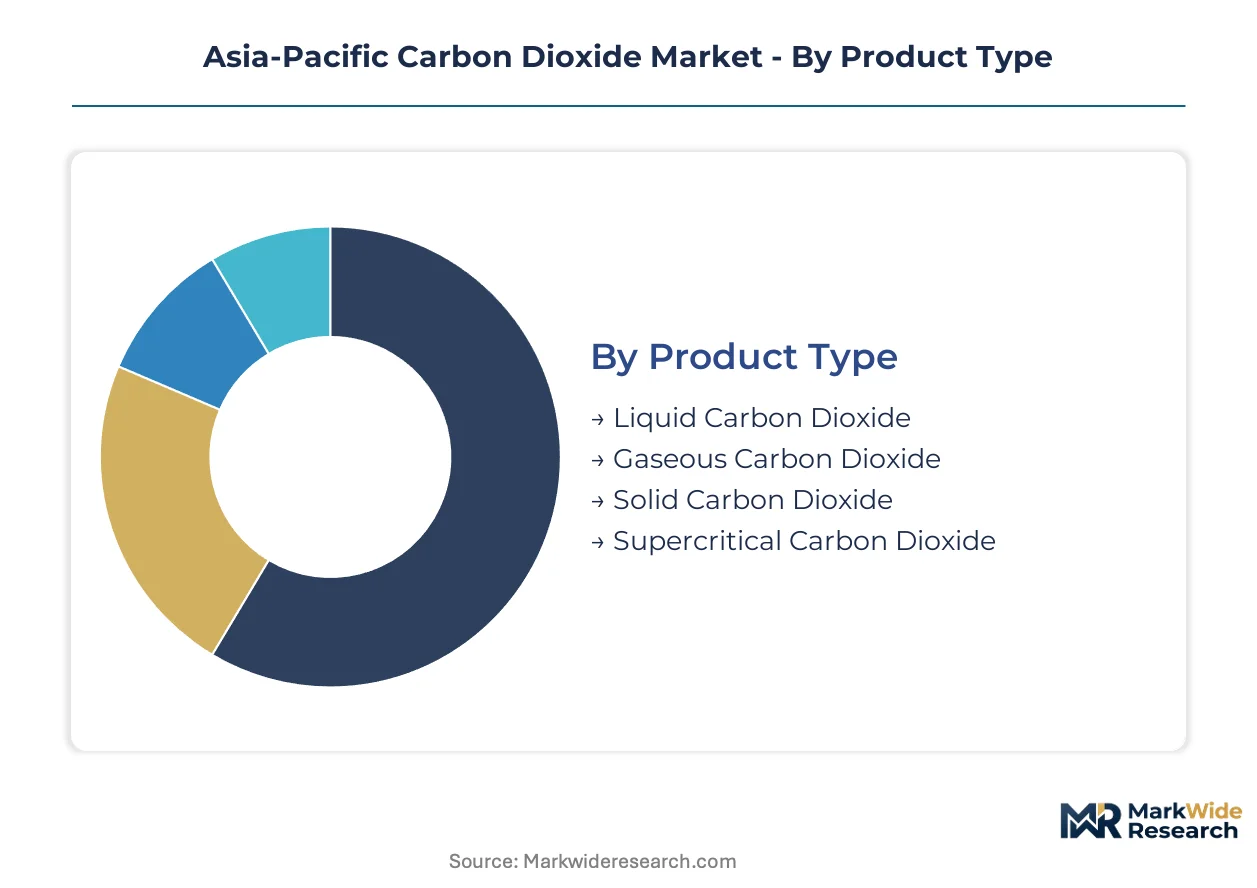
Product form and purity specifications determine logistics economics and buyer qualification requirements across the Asia-Pacific Carbon Dioxide Market. Segmentation reveals how cryogenic handling constraints and end-use certification standards reshape competitive boundaries between suppliers.
Product Type:
Domestic production dominates liquid and gaseous grades, while supercritical CO2 relies on import qualification for pharmaceutical-grade specifications in Australia and South Korea.
- Liquid Carbon Dioxide:Cryogenic liquid stored at minus 18 degrees Celsius under 20 bar pressure enables bulk transport via specialized tanker fleets. Demand concentrates in eastern China's chemical manufacturing corridor where ammonia synthesis off-gas feeds integrated liquefaction complexes. MEE utilization mandates force coal-to-chemical emitters to contract with processors possessing GB-certified purification infrastructure.
- Supercritical Carbon Dioxide:Fluid maintained above 31.1 degrees Celsius and 73.8 bar pressure dissolves organic compounds without residual solvent contamination. South Korea's MFDS pharmaceutical-grade specifications and Australia's TGA therapeutic goods standards drive qualification investments for API extraction contracts. Solvent replacement in dry-cleaning applications accelerates adoption across Australian urban centers.
- Gaseous Carbon Dioxide:Pipeline-delivered or cylinder-packaged gas serves metal fabrication shielding and wastewater pH neutralization with mature, stable demand curves.
- Solid Carbon Dioxide:Dry ice blocks and pellets sustain cold-chain logistics for pharmaceutical distribution and food preservation across India's expanding refrigerated transport networks.
Liquid Carbon Dioxide holds the largest share; momentum sits with Supercritical Carbon Dioxide.
Distribution Channel:
Channel selection tracks buyer scale and urgency requirements, with large-volume chemical processors favoring direct procurement while fragmented food processors rely on intermediaries.
- Direct Sales:Long-term offtake agreements link ammonia plant operators to enhanced oil recovery projects and chemical manufacturers. Contract structures incorporate take-or-pay clauses that guarantee minimum volumes through agricultural demand cycles.
- Distributors:Regional gas specialists maintain cylinder exchange networks and small-bulk delivery capability for metal fabrication shops and mid-size beverage bottlers across Southeast Asia.
- Online Sales:Digital platforms emerge for standardized cylinder orders and dry ice procurement among craft breweries and small-scale food processors in Vietnam and Thailand.
- Retail Outlets:Limited presence confined to welding supply stores and specialty gas counters serving hobbyist and maintenance applications.
Direct Sales generates the highest revenue per transaction; Online Sales is expanding most quickly.
End User:
Customer concentration varies sharply by sector, with oil recovery and chemical manufacturing anchoring bulk volumes while food and beverage spreads across thousands of bottling facilities.
- Oil Recovery:Tertiary crude extraction projects in China's Daqing and Shengli fields inject CO2 for reservoir pressure maintenance and residual oil mobilization. State-owned operators prioritize flood system suppliers with integrated capture infrastructure and multi-year delivery commitments.
- Chemical Manufacturing:Urea, methanol, and polycarbonate synthesis consume pipeline-scale gaseous deliveries. MEE carbon capture mandates compress procurement timelines for coal-to-chemical complexes seeking qualified processors.
- Food & Beverage Industry:Carbonation demand spreads across carbonated soft drink bottlers, breweries, and sparkling water producers. India's BIS purity standards create compliance barriers that consolidate supply toward organized players.
- Metal Production:Shield gas applications in electric arc furnaces and welding operations sustain steady cylinder demand from fabrication clusters in Japan and South Korea.
Oil Recovery commands the highest single-customer volumes; Food & Beverage Industry offers the broadest customer base expansion.
Application:
Application segmentation reveals how purity grades and delivery specifications fragment what commodity markets traditionally treat as uniform product.
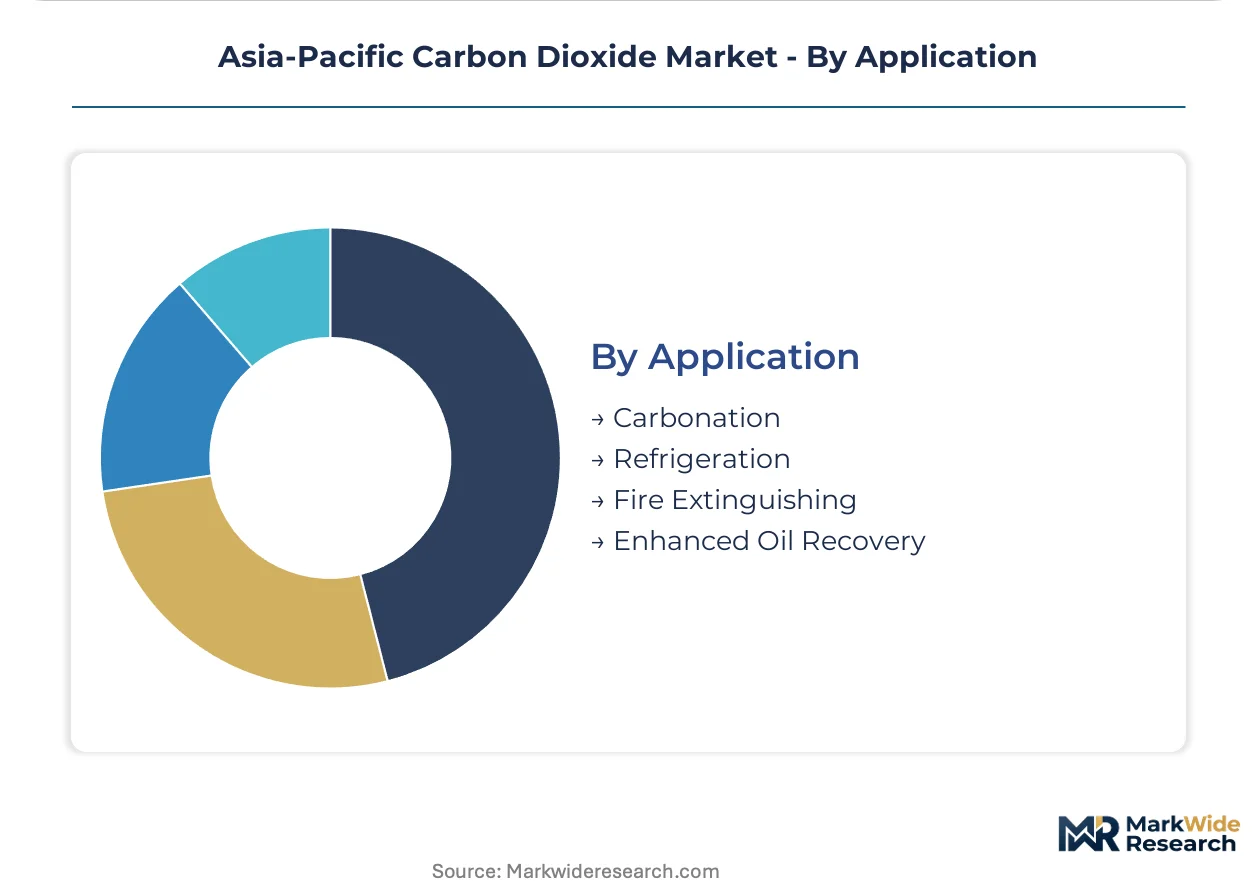
- Enhanced Oil Recovery:Flood systems require pipeline-grade gaseous CO2 at 95%+ purity with controlled moisture and hydrocarbon content. China's dual carbon goals accelerate project approvals for mature field rehabilitation.
- Carbonation:Food-grade liquid CO2 demands 99.9%+ purity with organoleptic certification. India's BIS standards and Japan's JIS specifications enforce contaminant thresholds that disqualify unorganized suppliers.
- Refrigeration:Secondary coolant applications in cold storage and transport favor liquid CO2 for its non-toxic, non-flammable properties with lower global warming potential than synthetic refrigerants.
- Fire Extinguishing:Fixed suppression systems and portable extinguishers utilize high-pressure liquid CO2 for clean-agent protection of electrical and archival facilities.
Enhanced Oil Recovery absorbs the greatest bulk volumes; Carbonation maintains the most stable pricing through premium certification tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial gas recovery infrastructure clusters along China's eastern seaboard, where ammonia synthesis complexes feed integrated liquefaction networks. Japan and South Korea anchor premium-grade demand through semiconductor fabrication and precision manufacturing. India's food-grade certification barriers concentrate supply toward organized players with BIS-compliant purification assets.
China
Enhanced oil recovery projects in the Daqing and Shengli fields absorb pipeline-scale gaseous deliveries for reservoir pressure maintenance. MEE utilization mandates force coal-to-chemical emitters to contract with qualified processors or face production curtailments. The Yangtze River Delta chemical corridor hosts integrated ammonia-carbon capture complexes serving bulk industrial offtake.
Japan
Semiconductor fabs and precision welding clusters sustain ultra-high-purity gaseous demand with premium pricing for qualified suppliers. METI green innovation funds subsidize CCUS demonstration infrastructure, creating demonstration-scale contract opportunities. Kanto and Kansai industrial zones concentrate fab-direct delivery capability for shield gas applications.
India
Carbonated beverage bottlers and expanding cold-chain logistics drive liquid and solid CO2 consumption across food processing networks. BIS purity standards for food-grade product create compliance barriers that consolidate supply toward organized players. Maharashtra and Gujarat host the primary liquefaction capacity serving western India's industrial corridor.
South Korea
Pharmaceutical-grade supercritical extraction demand accelerates as MFDS specifications enable solvent replacement in API manufacturing. Dry-cleaning applications adopt supercritical systems across urban centers seeking environmental compliance. The Seoul Capital Area anchors qualification investments for high-purity extraction contracts.
Australia
Therapeutic goods standards reshape qualification requirements for supercritical extraction-grade product in pharmaceutical applications. Membrane-based separation technology spreads among winemakers and craft distillers for distributed on-site capture. New South Wales and Victoria concentrate dry-cleaning solvent replacement adoption in metropolitan markets.
Asia-Pacific Carbon Dioxide Market Competitive Landscape
Concentration sits with multinational industrial gas conglomerates possessing integrated capture infrastructure and cross-border certification capabilities. Three archetypes dominate: ammonia-integrated processors with captive feedstock security, liquefaction specialists with cold-chain terminal networks, and premium-grade purifiers serving fab and pharmaceutical specifications. Capacity expansion and qualification investments constitute the dominant competitive moves as MEE deadlines and MFDS standards compress procurement timelines.
Among Asia-Pacific-based operators, TAIYO NIPPON SANSO CORPORATION exemplifies the premium-grade purifier archetype through its positioning in Japanese industrial gas supply. SS GASLAB ASIA PVT. LTD. represents regional specialists navigating India's BIS certification landscape. Sicgil India Limited occupies a position within the organized tier consolidating against unorganized competitors lacking food-grade compliance infrastructure.
| Leading Market Players |
|---|
| Air Liquide |
| Linde PLC |
| TAIYO NIPPON SANSO CORPORATION |
| Air Products and Chemicals, Inc. |
| Messer SE & Co. KGaA |
| Coregas |
| Cosmo Engineering Co., Ltd. |
| SS GASLAB ASIA PVT. LTD. |
| Sicgil India Limited |
| Others |
Value Network & Pricing Analysis
Long-term take-or-pay contracts between ammonia synthesis operators and enhanced oil recovery projects lock in feedstock access and price visibility across the Asia-Pacific Carbon Dioxide Market. These structures insulate bulk buyers from agricultural demand cycle volatility while compressing margins for processors lacking captive supply.
Pricing Analysis
Volume-discount tiering structures separate pipeline-scale enhanced oil recovery offtake from cylinder-packaged metal fabrication orders. Three-tier pricing stratifies across food-grade certified liquid, industrial gaseous, and supercritical extraction grades. Cost compression in standard industrial tiers intensifies as MEE utilization mandates force emitters to discount surplus volumes. Small beverage bottlers exhibit highest price sensitivity due to working capital constraints, while semiconductor fabs accept premium positioning for fab-direct ultra-high-purity delivery.
Supply Chain Analysis
China and Japan anchor regional CO2 recovery through integrated ammonia-carbon capture complexes and precision purification infrastructure. Feedstock draws from synthetic ammonia off-gas, ethanol fermentation streams, and emerging direct air capture demonstration units. Single-source vulnerability concentrates in eastern China's chemical corridor where fertilizer plant operating rates dictate regional supply availability. Distribution runs through bulk liquid tanker fleets for chemical processors, cylinder exchange networks for metal fabrication, and digital platforms for fragmented food-grade buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Carbon Dioxide Market constitutes a high-growth disruption as CCUS demonstration subsidies and mandatory utilization thresholds restructure industrial gas procurement. China's dual carbon goals and Japan's METI efficiency mandates compress timelines for capture infrastructure deployment.
For Market Incumbents: Shield market position through backward integration into ammonia synthesis feedstock and certification investments for pharmaceutical-grade supercritical product. Direct air capture technology threatens long-term feedstock security for off-gas-dependent processors. Capacity additions in India's western corridor and Southeast Asian cold-chain terminals capture import substitution value as food processing expands.
For New Entrants and Emerging Players: Differentiate on distributed membrane-based capture systems for Australian winemakers and craft distillers seeking on-site carbon independence. India's BIS-certified food-grade segment offers the most penetrable white space as unorganized suppliers face compliance barriers. Digital procurement platforms for small-bulk beverage carbonation contracts provide a channel-native go-to-market angle.
For Investors and Strategic Acquirers: Ammonia-integrated processors with captive feedstock security and multi-jurisdiction certification capabilities represent the priority acquisition archetype. Long-term viability hinges on positioning ahead of MEE enforcement timelines and MFDS qualification windows. Monitor contract announcement velocity for CCUS demonstration projects as the inflection indicator for subsidy-driven capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Synthesis | Captive feedstock security insulates processors from agricultural demand cycle volatility in China's eastern corridor. |
| Pharmaceutical-Grade Certification Investment | MFDS and TGA qualification unlocks supercritical extraction contracts in South Korea and Australia. |
| Cold-Chain Terminal Expansion | Greenfield liquefaction capacity in India and Southeast Asia captures food processing import substitution. |
| Digital Procurement Platform Development | Just-in-time delivery apps concentrate working capital optimization among Vietnamese and Thai bottlers. |
| CCUS Demonstration Project Partnership | METI green innovation fund access secures multi-year offtake agreements with emission reduction credentials. |
Research Methodology
The analysis maps liquid, supercritical, gaseous, and solid CO2 product tiers, each validated through interviews with ammonia plant operators, beverage procurement managers, enhanced oil recovery project engineers, and pharmaceutical extraction specialists. Secondary sources include MEE utilization mandate filings, METI green innovation fund disclosures, BIS certification registries, and customs trade data for cryogenic tanker movements. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Consistency checks validated outputs against external benchmarks across the projection horizon. The analytical framework segments by product form, distribution channel, end-user industry, and application, with purity-grade specifications as an additional industry-specific dimension. CAGRs derive from regression analysis of historical capacity utilization and forward projections of MEE enforcement timelines and food processing expansion. Key inputs include fertilizer plant operating rates and semiconductor fab construction pipelines.
The analysis sits within stated boundaries; outcomes outside sustained subsidy support for CCUS demonstration or accelerated MEE enforcement would require recalibration. Forecasts reflect documented assumptions regarding feedstock availability and certification timeline feasibility. Recalibration cycles align with material shifts in China's dual carbon policy implementation and pharmaceutical-grade specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Global Voluntary Carbon Credit Trading Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Europe Green Carbon Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market