
 Chile Water Consumption Market | 2026-2036
Chile Water Consumption Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Water Consumption Market Insights
A qualified hydrology and wastewater engineering workforce is collapsing across Chile's northern mining corridors, constraining expansion timelines for water-intensive projects. Aguas Andinas leverages its Santiago metropolitan concession to sustain the country's largest regulated customer base. ESSBIO anchors potable water distribution across south-central industrial cities including Concepción and Los Ángeles. Codelco dominates captive water sourcing for its Chuquicamata and Radomiro Tomic divisions, navigating complex priority rights under Chile's modified water code.
Chile Water Consumption encompasses the extraction, treatment, conveyance, and end-use of freshwater, brackish, and reclaimed water across agricultural, urban, and extractive systems, with total dissolved solids thresholds and hydraulic head requirements varying by application. Surface water and groundwater sources face structural scarcity in the Coquimbo-to-Antofagasta latitudes, while desalinated water represents the fastest-growing supply category as mining capex shifts toward seawater reverse osmosis. The industrial sector occupies the largest value share due to copper, lithium, and molybdenum processing requirements, whereas recycled water competes on cost positioning for non-potable municipal and agricultural reuse.
Chile's Dirección General de Aguas enforces extraction permits under the revised water code, while the Superintendencia de Servicios Sanitarios regulates tariff structures and quality standards for municipal utilities. The Ministry of Environment applies environmental impact assessment requirements to desalination projects and brine discharge protocols, shaping capital allocation toward lower-intensity technologies. Stakeholders must monitor constitutional court rulings on water rights adjudication and the pace of public-private partnerships for Atacama desalination infrastructure.
Market Dynamics
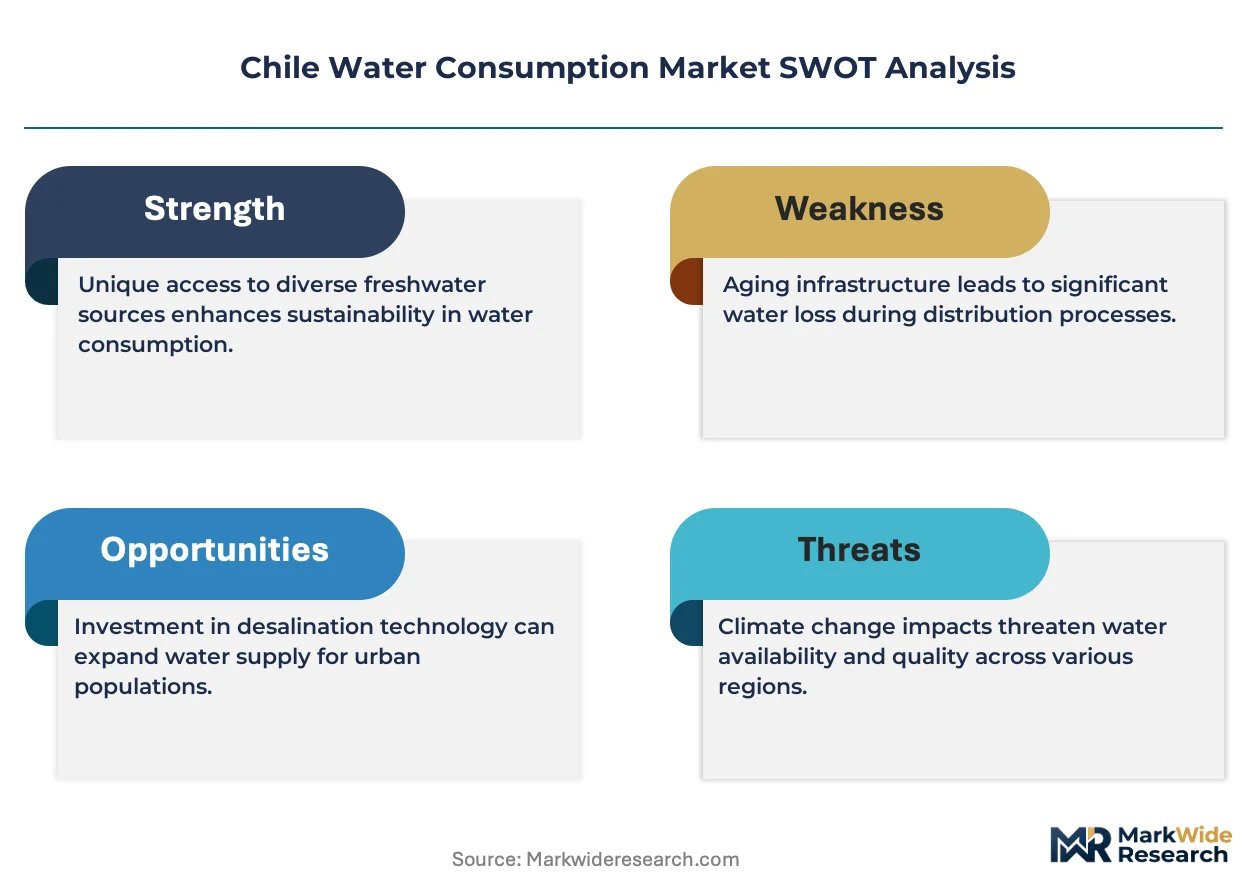
Chile's mining sector confronts a structural water scarcity squeeze as declining ore grades force copper and lithium operators to quadruple freshwater intensity per ton of output, triggering a capital reallocation toward desalination infrastructure that now dominates sectoral investment planning.
Growth Catalysts
- Seawater reverse osmosis capex surge:Mining operators in the Antofagasta Region are commissioning large-scale desalination plants to displace freshwater offtake, with seawater reverse osmosis now the default technology for new copper concentrate hydrometallurgy projects.
- 2022 constitutional water code reform:Chile's revised water code enforcement tightens extraction permits for non-consumptive uses, accelerating formalization of water rights trading and creating compliance-driven demand for alternative supply infrastructure.
- Lithium brine evaporation expansion:Battery-grade lithium carbonate and hydroxide production from Atacama salar brines requires sustained evaporative water management, locking in long-term offtake contracts for engineered water systems.
Market Restraints
- Energy cost volatility for desalination:Reverse osmosis operations are electricity-intensive, and Chile's northern grid dependence on imported natural gas exposes operating margins to fuel price swings that compress project returns.
- Hydrology workforce collapse:The qualified engineering talent pool for wastewater and water resource management is contracting across the Coquimbo-to-Antofagasta corridor, extending recruitment timelines and inflating labor costs.
- Brine discharge regulatory friction:Chile's Ministry of Environment applies stringent environmental impact assessment requirements to desalination brine disposal protocols, adding permitting delays and capital overhead to coastal projects.
Strategic Opportunities
- Recycled water for agricultural reuse:Treated municipal effluent from Santiago and Valparaíso metropolitan systems represents an underutilized supply source for Coquimbo Region irrigation districts facing groundwater overdraft.
- Public-private desalination partnerships:Chile's Ministry of Public Works is soliciting concession structures for Atacama coastal infrastructure, creating entry points for specialized water utilities and engineering firms.
- Digital water network convergence:Integration of SCADA systems with satellite-based evapotranspiration monitoring is enabling precision allocation across competing agricultural and mining offtakers in the Elqui River basin.
Industry Challenges
- Priority rights adjudication complexity:Mining operators navigating Chile's modified water code face protracted legal proceedings to secure non-consumptive use permits, with constitutional court rulings creating precedent uncertainty that stalls project financing.
- Legacy infrastructure integration:Urban water utilities in south-central industrial cities must retrofit aging distribution networks to accommodate blended supply from conventional and desalinated sources without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Water Consumption Market |
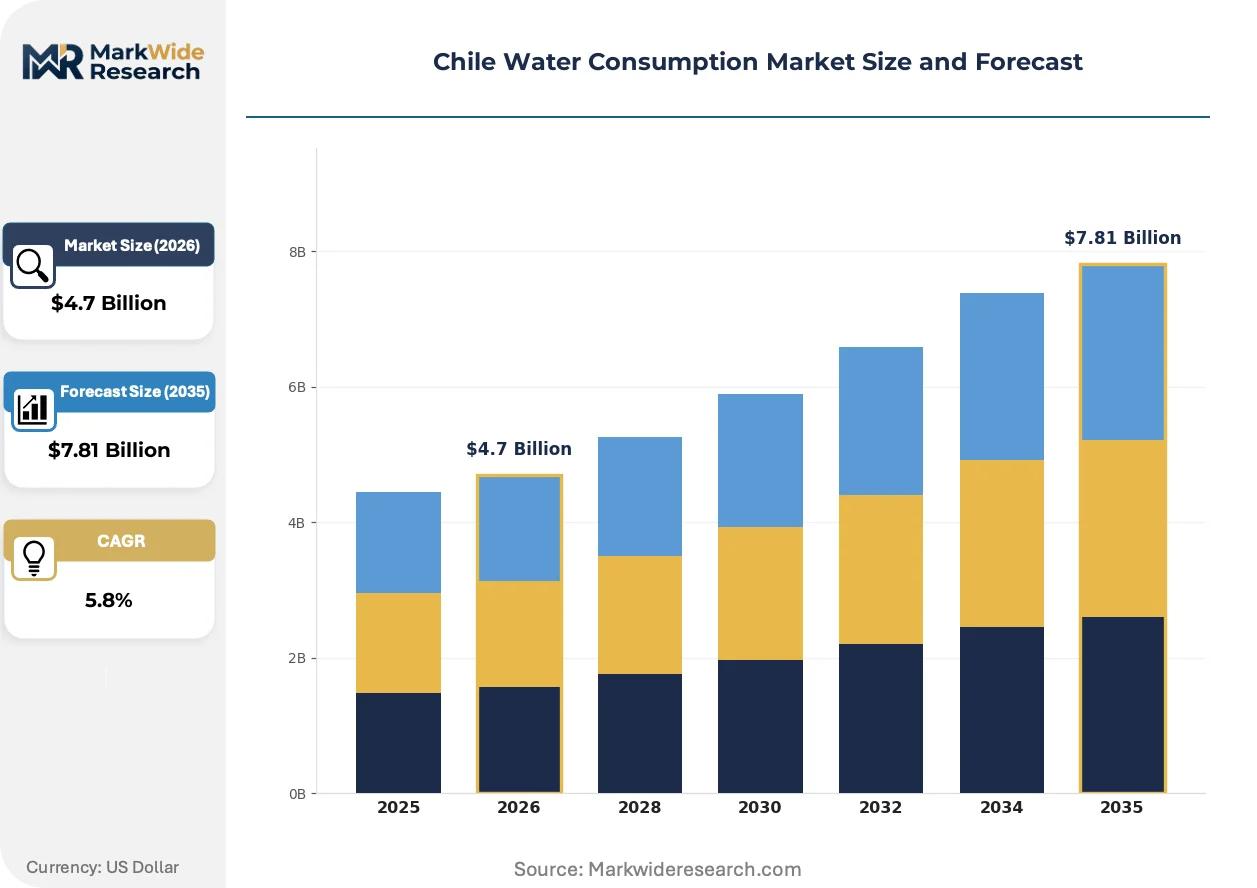
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $7.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sector: Agriculture, Industrial, Residential, Commercial Water Source: Surface Water, Ground Water, Desalinated Water, Recycled Water Usage Type: Irrigation, Domestic Use, Manufacturing, Power Generation Distribution Channel: Municipal Supply, Private Supply, Well Water, Tanker Supply |
| Companies Covered | Aguas Andinas, Empresa de Servicios Sanitarios del Bio-Bío (ESSBIO), Empresa Sanitaria de Valparaíso (ESVAL), Veolia Group, Empresas Públicas de Medellín (EPM), BHP Group, Codelco, Antofagasta Minerals, Anglo American, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Water Consumption Market Trends and Innovations
Water management in Chile's extractive corridor is pivoting from source extraction to engineered supply systems, with technology adoption patterns diverging sharply between mining majors deploying capital-intensive desalination and agricultural users pursuing efficiency-driven conservation.
Membrane bioreactor technology is fragmenting the conventional activated sludge market for mining camp wastewater treatment. Codelco and Antofagasta Minerals are deploying submerged membrane systems at remote operations to achieve direct reuse standards without large-footprint settling infrastructure. This technology compression is enabling modular plant designs that slash civil works costs and accelerate commissioning timelines for greenfield projects.
Chile's Dirección General de Aguas is enforcing extraction permit reductions under the constitutional reform's non-consumptive use provisions. The regulatory tightening is forcing mining operators to relinquish historical surface water rights and contract desalinated supply, with the Antofagasta Region's copper concentrate hydrometallurgy sector absorbing the most severe permit curtailments through accelerated seawater substitution investments.
Water procurement for lithium brine operations is consolidating around long-term supply agreements with integrated utilities rather than spot-market extraction permits. Albemarle and SQM are negotiating 15-20 year offtake contracts with desalination developers to lock in volume certainty, with the Atacama salar evaporation ponds representing the most visible geography for this contractual pivot away from historical self-supply models.
Chile Water Consumption Market Segmentation
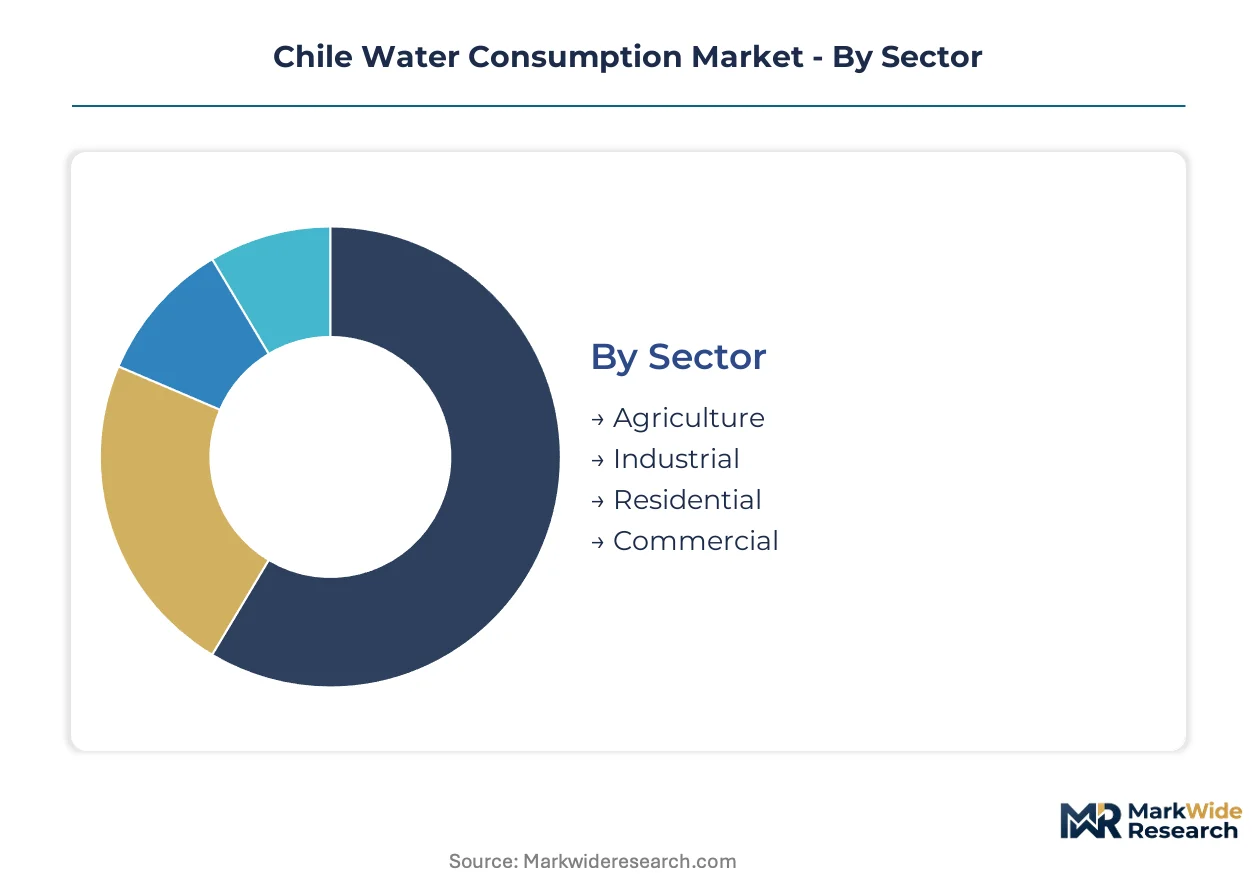
Water consumption patterns across Chile diverge sharply between extractive corridors and urban centers, with each segment facing distinct regulatory pressures and infrastructure investment cycles. Segmentation reveals where capital is concentrating and which supply categories are displacing legacy extraction models.
Sector:
Industrial applications face the most acute substitution pressure as mining operators abandon surface water rights for desalinated supply contracts under tightened extraction permits.
- Industrial:Copper concentrate hydrometallurgy and lithium brine evaporation dominate water intensity metrics, with Antofagasta Region operations consuming the largest engineered supply volumes as ore grades decline and processing requirements intensify. Codelco's Chuquicamata division anchors captive sourcing strategies while competitors contract third-party desalination.
- Agriculture:Irrigation districts in the Coquimbo Region confront groundwater overdraft constraints, shifting demand toward treated municipal effluent reuse from Santiago and Valparaíso metropolitan systems. Elqui River basin allocations increasingly compete with mining offtakers for limited surface flows.
- Residential:Aguas Andinas sustains the largest regulated customer base through its Santiago metropolitan concession, with tariff structures governed by the Superintendencia de Servicios Sanitarios.
- Commercial:South-central industrial cities including Concepción and Los Ángeles rely on ESSBIO distribution networks, requiring retrofitting to accommodate blended conventional and desalinated sources.
Industrial retains volume leadership; Agriculture holds the steepest expansion curve as recycled water integration accelerates.
Water Source:
Cost tier stratification separates capital-intensive engineered supply from legacy extraction, with desalination commanding premium positioning against diminishing surface water access.
- Desalinated Water:Seawater reverse osmosis now serves as the default technology for new copper concentrate hydrometallurgy projects in the Antofagasta Region, with electricity-intensive operations exposed to northern grid fuel price volatility.
- Surface Water:Structural scarcity defines the Coquimbo-to-Antofagasta latitudes, where the Dirección General de Aguas enforces permit reductions under constitutional reform non-consumptive use provisions.
- Ground Water:Overdraft conditions in northern agricultural districts constrain expansion, with extraction limits forcing substitution toward alternative supply categories.
- Recycled Water:Treated municipal effluent competes on cost positioning for non-potable reuse, with membrane bioreactor technology enabling modular designs that slash civil works costs for mining camp applications.
Surface Water retains volume leadership; Desalinated Water climbs the fastest as mining capex pivots toward coastal infrastructure.
Usage Type:
Application-driven demand concentration centers on processes with non-substitutable water intensity, where total dissolved solids thresholds and hydraulic head requirements dictate supply specifications.
- Manufacturing:Copper, lithium, and molybdenum processing requirements occupy the largest value share, with battery-grade lithium carbonate and hydroxide production from Atacama salar brines locking in long-term offtake contracts.
- Irrigation:Precision allocation systems integrating SCADA with satellite-based evapotranspiration monitoring enable competing agricultural and mining offtakers to optimize withdrawals in the Elqui River basin.
- Domestic Use:Metropolitan utilities manage quality standards under Superintendencia de Servicios Sanitarios oversight, with aging distribution networks requiring retrofit for blended supply integration.
- Power Generation:Cooling water requirements in northern grids dependent on imported natural gas face margin compression from fuel price exposure.
Manufacturing retains volume leadership; Irrigation gains share fastest as digital water network convergence expands.
Distribution Channel:
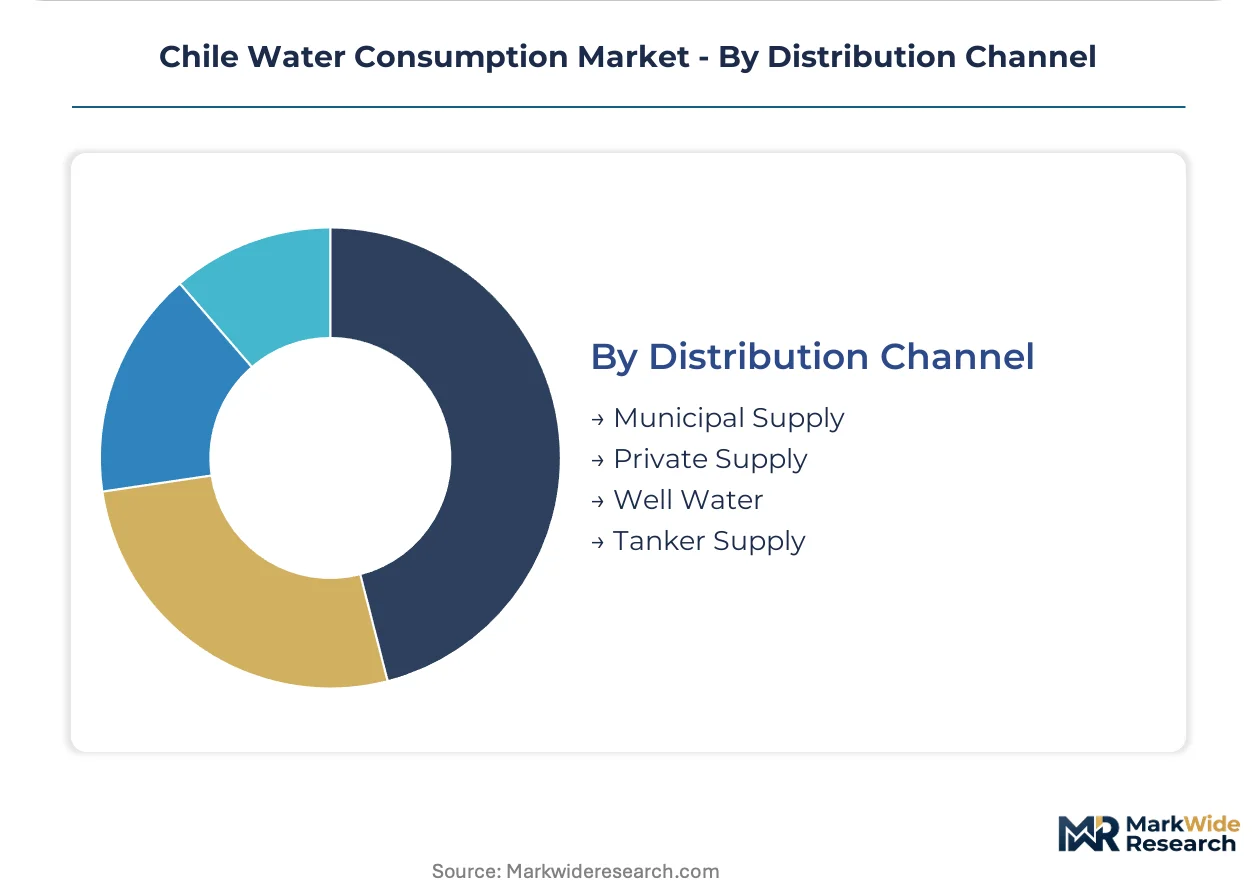
Customer type fragmentation separates regulated municipal concessions from self-supply mining operations, with public-private partnership structures emerging for Atacama coastal infrastructure.
- Municipal Supply:Regulated tariff structures govern Santiago and Valparaíso metropolitan systems, with the Ministry of Public Works soliciting concession structures for expanded service territories.
- Private Supply:Mining majors deploy capital-intensive desalination through integrated utilities, with Albemarle and SQM negotiating 15-20 year offtake contracts to lock in volume certainty.
- Well Water:Agricultural self-supply faces extraction permit tightening, with priority rights adjudication complexity stalling project financing for new withdrawals.
- Tanker Supply:Remote operations and emergency distribution rely on supplemental logistics, particularly in workforce camp settings where membrane bioreactor deployment reduces dependency.
Municipal Supply retains volume leadership; Private Supply shows the steepest expansion trajectory as contractual pivot away from historical self-supply models accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water pricing in the Antofagasta Region commands a 40-60% premium over Santiago metropolitan tariffs, reflecting desalination energy costs and priority rights scarcity that reshape procurement economics across Chile's northern mining corridor.
Antofagasta Region
Copper concentrate hydrometallurgy and lithium brine evaporation drive the steepest demand intensity, with Codelco's Chuquicamata division and Albemarle's Atacama operations consuming the largest engineered supply volumes. The Dirección General de Aguas enforces extraction permit reductions under 2022 constitutional reform non-consumptive use provisions. Calama and María Elena anchor the coastal desalination infrastructure cluster where seawater reverse osmosis now dominates new project development.
Santiago Metropolitan Region
Aguas Andinas sustains the country's largest regulated customer base through potable water distribution and wastewater treatment services. The Superintendencia de Servicios Sanitarios governs tariff structures and quality standards under consolidated concession frameworks. Santiago and Valparaíso metropolitan systems generate treated effluent streams that Coquimbo Region irrigation districts increasingly contract for agricultural reuse.
Coquimbo Region
Groundwater overdraft conditions in the Elqui River basin force irrigation districts toward alternative supply categories as surface allocations tighten. The Ministry of Public Works solicits concession structures for expanded service territories under public-private partnership frameworks. La Serena and Coquimbo city clusters face competing withdrawals between precision agriculture and mining offtakers deploying satellite-based evapotranspiration monitoring.
Bío-Bío Region
ESSBIO anchors potable water distribution across south-central industrial cities including Concepción and Los Ángeles. Aging distribution networks require retrofitting to accommodate blended supply from conventional and desalinated sources without service interruption. The Concepción metropolitan industrial cluster sustains manufacturing water demand alongside residential consumption patterns.
Valparaíso Region
ESVAL manages coastal water systems facing seasonal scarcity pressures and tourism-driven demand peaks. Brine discharge regulatory friction from the Ministry of Environment adds permitting delays to coastal desalination project development. The Valparaíso port cluster and Quintero industrial zone concentrate manufacturing and logistics water requirements.
Chile Water Consumption Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Chile's bifurcated water market. Regulated municipal utilities dominate volume through concession-protected service territories, while mining majors deploy capital-intensive desalination through integrated captive supply or long-term offtake contracting. Three archetypes define competitive positioning: metropolitan concession holders with tariff-governed revenue stability, mining-integrated water developers with project finance access, and specialized engineering firms deploying modular membrane systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with public-private concession structures emerging as the primary entry mechanism for coastal infrastructure.
Within the metropolitan concession tier, Aguas Andinas and ESSBIO exemplify regulated utility archetypes with protected service territories and tariff-governed revenue models. Among mining-integrated operators, Codelco occupies a position representing captive sourcing strategies for major copper divisions. At the specialized infrastructure end, Veolia Group sits within the international engineering firm archetype deploying capital and technical expertise through concession and service contract structures. These three player types collectively illustrate how market access depends on regulatory relationship depth, balance sheet scale, or technology integration capability rather than unified operational dominance.
| Leading Market Players |
|---|
| Aguas Andinas |
| Empresa de Servicios Sanitarios del Bio-Bío (ESSBIO) |
| Empresa Sanitaria de Valparaíso (ESVAL) |
| Veolia Group |
| Empresas Públicas de Medellín (EPM) |
| BHP Group |
| Codelco |
| Antofagasta Minerals |
| Anglo American |
| Others |
Pricing and Supply Chain Analysis
Chile's 2022 constitutional water code reform gates both supply qualification and price differentiation simultaneously, as tightened extraction permits for non-consumptive uses force mining operators to abandon historical surface water rights and contract desalinated supply at premium energy-indexed rates. The regulatory pivot creates a bifurcated procurement landscape where coastal desalination infrastructure commands tariff premiums while inland legacy sources face permit curtailment.
Pricing Analysis
Antofagasta Region water tariffs run 40-60% above Santiago metropolitan benchmarks, reflecting electricity-intensive reverse osmosis operations and priority rights scarcity. Contract-based long-term offtake structures dominate industrial procurement, with 15-20 year agreements locking in volume certainty for lithium brine and copper concentrate operations. Price differentiation hinges on desalination energy costs and extraction permit security, with northern grid fuel price volatility compressing margins. Agricultural irrigation districts exhibit highest price sensitivity, while mining majors with integrated captive supply show lowest sensitivity due to pass-through mechanisms in concentrate sales.
Supply Chain Analysis
Strategic stockpiling of membrane modules and energy hedging instruments supersedes just-in-time preferences given northern Chile's logistics constraints and equipment lead times. Supply concentrates in Chile's Antofagasta coastal corridor for desalination infrastructure, with critical membrane elements sourced from USA, Japan, and South Korea. The chain rests on specialized engineering labor pools, imported natural gas for grid power, and corrosion-resistant materials for brine handling. Single-source vulnerability in membrane bioreactor component supply poses structural risk. Distribution runs through integrated utility concessions for municipal supply and direct bilateral contracting for mining self-supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's water consumption market represents high-growth disruption as seawater reverse osmosis capex displaces century-old surface water extraction rights under constitutional reform enforcement. The technological inflection reconfigures competitive access for engineering firms and utilities alike.
For Market Incumbents: Compound regulatory relationship depth through priority rights adjudication expertise and accelerate membrane technology integration to defend against specialized engineering entrants. Expand capacity in Antofagasta coastal corridors where permit curtailments concentrate demand. Secure long-term energy supply agreements to stabilize desalination operating margins against northern grid fuel price swings.
For New Entrants and Emerging Players: Differentiate on modular membrane bioreactor deployment for remote mining camp applications, where civil works cost reduction and accelerated commissioning timelines create white-space entry. Target Coquimbo Region agricultural reuse contracts from Santiago-Valparaíso metropolitan effluent streams. Pursue public-private partnership concession structures for Atacama coastal infrastructure as the primary go-to-market mechanism.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across seawater reverse osmosis infrastructure as electricity costs and brine discharge compliance overhead expand project scale thresholds. Five-to-ten year viability favors mining-integrated water developers with project finance access and tariff-governed municipal utilities with protected concessions. Watch constitutional court rulings on water rights adjudication as the signal for permit security inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Seawater Reverse Osmosis Capacity Buildout | Antofagasta mining operators commission coastal plants to displace curtailed surface water rights. |
| Long-term Supply Agreement Structuring | Albemarle and SQM negotiate 15-20 year offtake contracts for Atacama lithium brine evaporation certainty. |
| Membrane Bioreactor Technology Deployment | Codelco adopts submerged systems at remote operations to achieve direct reuse without large-footprint infrastructure. |
| Public-Private Partnership Concession | Ministry of Public Works solicits Atacama coastal structures, creating entry for specialized engineering firms. |
| Digital Water Network Integration | SCADA-satellite evapotranspiration convergence enables precision allocation across Elqui River basin competitors. |
Research Methodology
A standing panel of desalination project developers, mining water procurement officers, DGA permitting specialists, and municipal utility planning directors provided ongoing calibration against secondary validation from SEC filings of listed water utilities, Chilean Ministry of Public Works concession databases, and Superintendencia de Servicios Sanitarios tariff rulings. Primary interviews with membrane technology suppliers and EPC contractors combined with bottom-up and top-down triangulation across extraction permit registries and coastal infrastructure investment tracking.
Consistency checks validated volume and value outputs against external benchmarks including desalination plant commissioning announcements, lithium brine expansion capex disclosures, and agricultural district reuse contract volumes. Segmentation dimensions spanned sector, water source, usage type, and distribution channel across the projection horizon. CAGRs derived from modeled supply-demand balances incorporating ore grade decline curves, constitutional reform implementation pacing, and energy cost scenario analysis.
Material uncertainties — constitutional court precedent shifts, northern grid fuel price volatility, and membrane supply chain disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions on permit curtailment schedules and desalination technology cost curves. Revision becomes warranted when constitutional reform enforcement intensity or energy price shocks cross threshold magnitudes that alter project finance viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Management
North America Water Sink Market
Water Management
Municipal Water Market
Water Management
Asia-Pacific Water Sink Market
Water Management
Middle East and Africa Water Sink Market
Water Management
NRW Smart Leak Management Market
Water Management
Global Water Market
Water Management
Spain Water Consumption Market
Water Management
Water Filters Market
Water Management
France Water Consumption Market
Water Management
Water Trading Market
Water Management
Mexico Water Consumption Market
Water Management
Smart Water Network Market
Water Management
US Water Leak Detection and Repair Services Market
Water Management
Water Utility Services Market
Water Management
Atmospheric Water Generator (AWG) Market
Water Management
Smart Water Management Market