
 Global Voluntary Carbon Credit Trading Market | 2026-2036
Global Voluntary Carbon Credit Trading Market Size, Share, and Industry Trends Forecast 2026-2036
Global Voluntary Carbon Credit Trading Market Outlook
The EU Carbon Border Adjustment Mechanism is repositioning how multinational corporations source offset coverage for Scope 3 emissions. Verra leverages its Verified Carbon Standard to dominate project certification across forestry and renewable energy methodologies. Gold Standard anchors its position through co-benefit certification requirements that attract premium buyers. Xpansiv competes through its CBL spot exchange infrastructure, which controls real-time price discovery for standardized contracts.
Voluntary carbon credit trading encompasses the issuance, verification, and exchange of emission reduction certificates measured in tonnes of CO2 equivalent, with each credit representing one tonne of greenhouse gas reduced, avoided, or removed through validated projects. The primary commercial purpose is to enable entities to neutralize residual emissions beyond reduction pathways while channeling capital into climate mitigation activities. Carbon offsets within the component dimension attract concentrated liquidity as buyers prioritize nature-based solutions with measurable permanence. The corporate sustainability application leads transaction volume, while climate neutrality commitments among financial institutions represent the fastest-growing demand pool. Exchange traded mechanisms within market type are gaining structural share as standardization reduces counterparty risk and improves price transparency.
The Integrity Council for the Voluntary Carbon Market's Core Carbon Principles is tightening baseline and additionality requirements that reshape which projects qualify for premium pricing. Article 6 of the Paris Agreement, administered by UNFCCC frameworks, is creating fungibility rules between compliance and voluntary markets that affect cross-border credit flows. The US Commodity Futures Trading Commission's proposed guidance on carbon credit derivatives is establishing position limits and disclosure standards for exchange-traded instruments. Stakeholders must monitor whether emerging jurisdictional integrity standards fragment liquidity or converge toward interoperable certification protocols.
Market Dynamics
The EU Carbon Border Adjustment Mechanism is forcing multinational corporations to restructure offset procurement for Scope 3 emissions coverage, creating urgent demand for verified credits that can demonstrate jurisdictional integrity and permanence.
Growth Catalysts
- EU Green Deal compliance mandates:Importers into the European Union must now document embedded emissions and secure offset coverage for residual carbon, accelerating procurement of Verra-certified forestry credits.
- Technology sector net-zero commitments:Cloud computing and semiconductor manufacturers are channeling capital into Indonesia peatland restoration to neutralize data center energy footprints.
- Brazil reforestation project concentration:Verified carbon standard methodologies applied to Amazon basin restoration generate liquidity premiums due to measurable co-benefits and permanence safeguards.
Market Restraints
- Integrity standard fragmentation risk:Divergent Core Carbon Principles interpretations across the Integrity Council for the Voluntary Carbon Market, Gold Standard, and Verra create certification arbitrage uncertainty.
- Permanence verification cost inflation:Satellite monitoring and ground-truthing requirements for nature-based solutions in Indonesia and Brazil drive project development expenses upward.
- Article 6 fungibility delays:UNFCCC framework negotiations on compliance-voluntary market interoperability stall cross-border credit flows and price convergence.
Strategic Opportunities
- India renewable energy offset expansion:Solar and wind project developers can access premium pricing through Gold Standard co-benefit certification as domestic corporate buyers activate climate neutrality pledges.
- US CFTC derivatives market formation:Proposed position limits and disclosure standards for exchange-traded carbon instruments will attract institutional capital seeking standardized exposure.
- Blue carbon methodology commercialization:Mangrove and seagrass restoration projects in Southeast Asia offer untapped supply for buyers prioritizing marine ecosystem co-benefits.
Industry Challenges
- Additionality assessment skill scarcity:Project developers struggle to recruit specialists capable of navigating baseline scenario modeling under tightening Integrity Council requirements.
- Legacy registry system integration friction:Carbon credit platforms face technical complexity connecting proprietary verification databases with emerging blockchain-based tracking infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Voluntary Carbon Credit Trading Market |
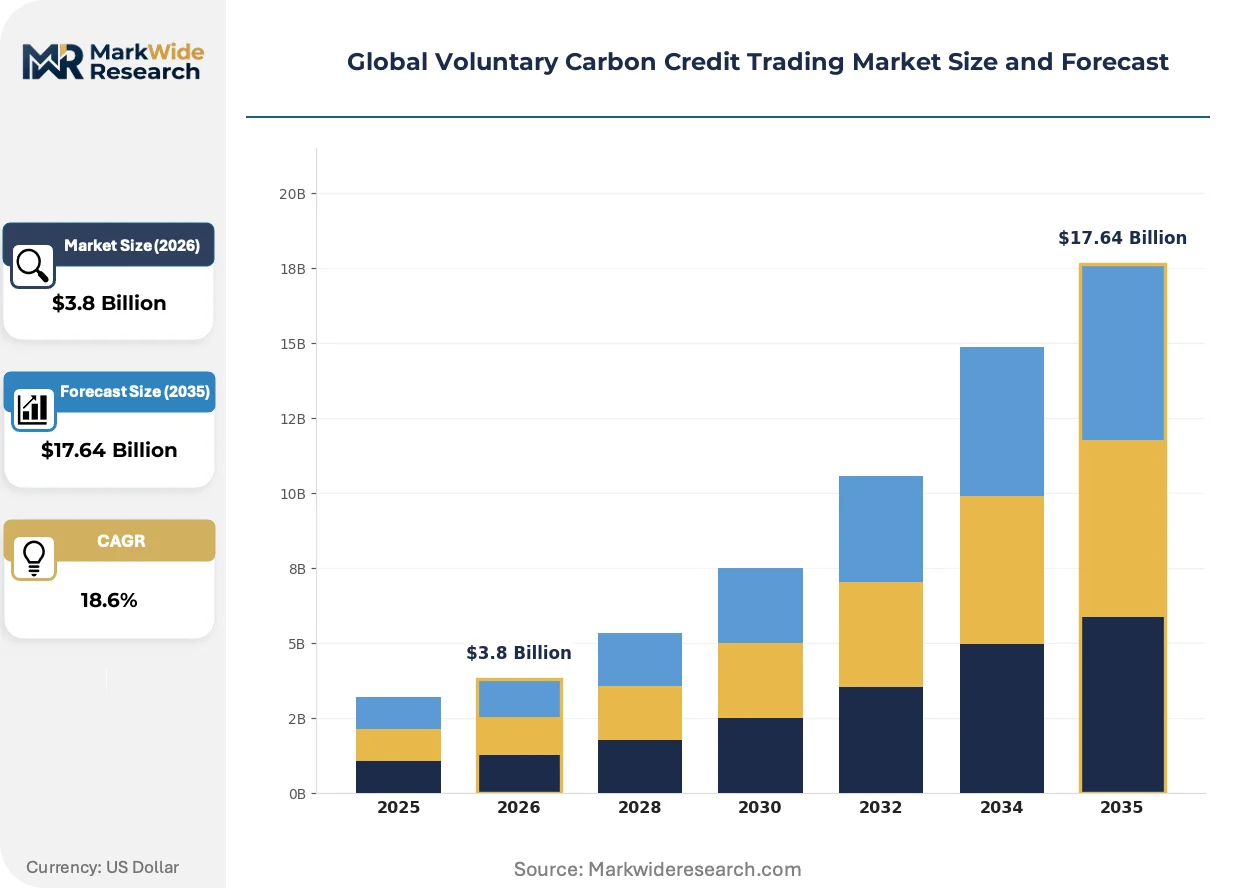
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Verification, Registry, Carbon Offsets, Trading Platform Application: Corporate Sustainability, Environmental Compliance, Energy Transition, Climate Neutrality End User: Corporations, NGOs, Governments, Financial Institutions Market Type: Exchange Traded, Over-the-Counter, Spot Market, Futures Market |
| Companies Covered | Verra, Gold Standard, Xpansiv, AirCarbon Exchange, 3Degrees, Climate Impact Partners, Carbon Trade Exchange, South Pole, Ecosecurities, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Voluntary Carbon Credit Trading Market Strategic Shifts
Digital measurement, reporting, and verification technologies are compressing certification timelines while regulatory frameworks in major economies create new compliance-linked demand channels for voluntary credits.
Blockchain-based carbon credit registries is unifying fragmented verification data across Verra, Gold Standard, and national registries into immutable ledgers. Exchange operators and institutional buyers are adopting these platforms to reduce double-counting risk. The technology is unifying previously siloed project documentation, enabling real-time permanence monitoring and automated retirement tracking.
REACH-aligned sustainability disclosure requirements in Europe are extending carbon reporting obligations through corporate value chains. The EU Green Deal's carbon border mechanism now requires embedded emissions documentation for steel, cement, aluminum, and fertilizer imports. Importers are responding by pre-purchasing verified offsets from Brazilian reforestation and Indonesian peatland projects to hedge compliance exposure.
Corporate buyers are consolidating offset procurement through long-term offtake agreements rather than spot market purchases. Financial institutions and technology companies are displacing project developers as direct negotiation counterparts, compressing intermediary margins. This concentration is most visible in Singapore and London, where sustainability-linked loan covenants now mandate verified offset coverage for residual emissions.
Global Voluntary Carbon Credit Trading Market Segmentation
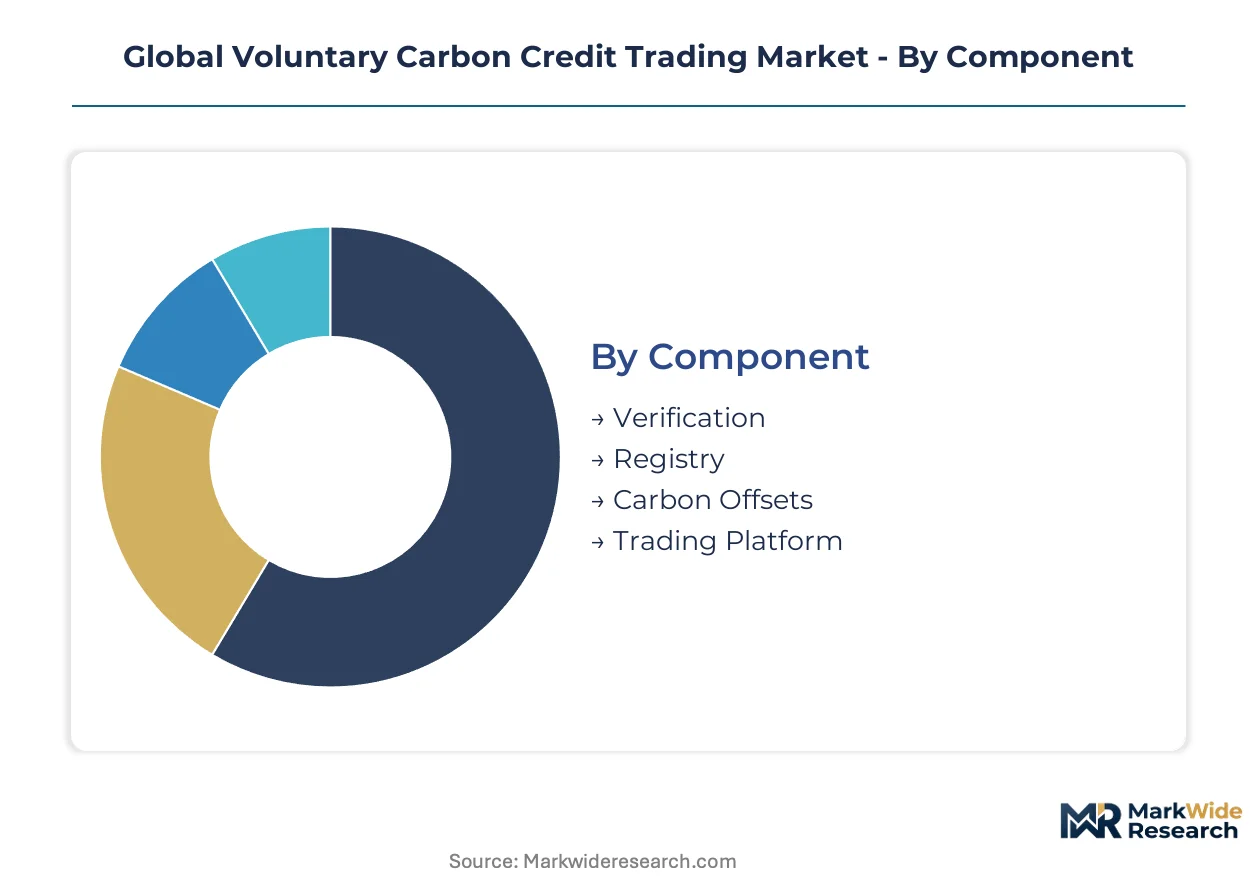
Segmentation in voluntary carbon credit trading reveals how value accrues differently across verification infrastructure, procurement channels, and end-user sophistication. Buyers with advanced climate accounting capabilities concentrate spend in vertically integrated segments, while compliance-driven entrants favor standardized access points.
Component:
Standardization dominates verification and registry services, whereas carbon offsets and trading platforms fragment across bespoke methodologies and proprietary infrastructure.
- Verification:Third-party validation bodies assess project additionality and baseline scenarios against Verra and Gold Standard protocols. Demand concentrates among Brazil reforestation developers seeking jurisdictional integrity certification for EU Carbon Border Adjustment Mechanism compliance.
- Registry:Distributed ledger systems track credit issuance, transfer, and retirement across immutable records. Indonesia peatland project developers prioritize registry interoperability with Singapore and London exchange infrastructure to reduce settlement friction.
- Carbon Offsets:Nature-based and technology-based emission reduction certificates trade at differentiated price tiers.
- Trading Platform:Exchange and bilateral matching systems connect buyers with project developers or secondary market liquidity.
Most installed capacity flows through Carbon Offsets. Expansion is steepest in Trading Platform infrastructure.
Application:
Cost tier stratification separates premium climate neutrality commitments from baseline environmental compliance spend.
- Corporate Sustainability:Technology and consumer goods companies procure verified credits to neutralize residual Scope 3 emissions beyond reduction pathways. Cloud computing providers channel capital into Indonesian peatland restoration to offset data center energy footprints.
- Environmental Compliance:Importers into the European Union document embedded emissions and secure offset coverage for carbon border adjustment exposure. Steel and cement traders pre-purchase Brazilian reforestation credits to hedge compliance liability.
- Energy Transition:Renewable energy developers generate offset revenues through Gold Standard co-benefit certification.
- Climate Neutrality:Financial institutions and sovereign entities commit to net-zero portfolios through long-term offtake agreements.
Transaction volume concentrates in Corporate Sustainability. Climate Neutrality is gaining share fastest among financial institution buyers.
End User:
Customer type determines procurement sophistication, with financial institutions displacing intermediaries in direct project negotiations.
- Corporations:Multinational technology and manufacturing entities consolidate offset procurement through sustainability-linked loan covenants. Semiconductor manufacturers negotiate directly with Brazil reforestation developers to secure permanence-guaranteed supply.
- Financial Institutions:Asset managers and insurance groups integrate carbon credit exposure into climate-aligned portfolios. Singapore-based banks mandate verified offset coverage for residual emissions in lending agreements.
- NGOs:Conservation organizations channel philanthropic capital into blue carbon and community forestry methodologies.
- Governments:National and sub-sovereign entities procure credits for Paris Agreement Article 6 international transfer mechanisms.
Primary liquidity originates with Corporations. Financial Institutions are climbing the fastest as direct negotiation counterparts.
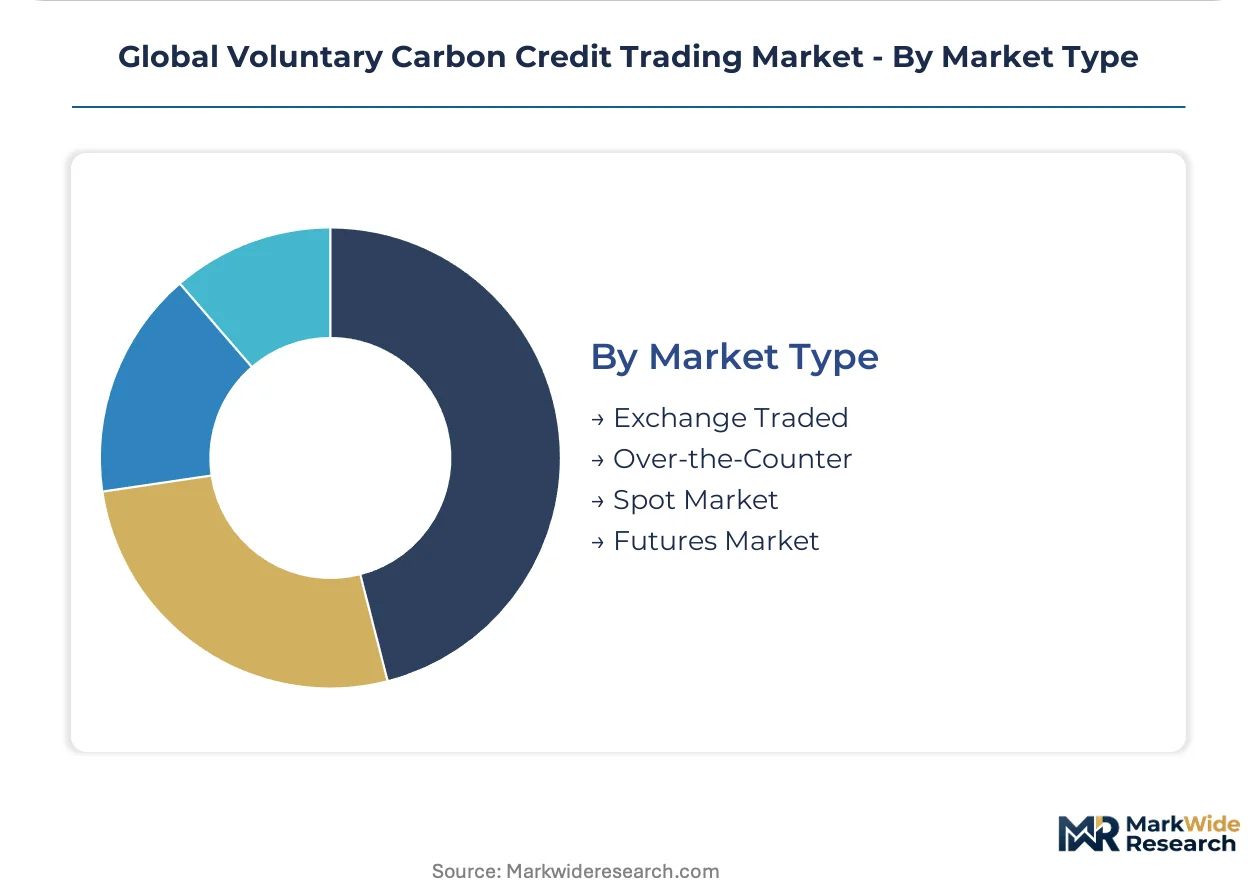
Market Type:
Maturity divides spot and over-the-counter channels from emerging exchange-traded standardization.
- Exchange Traded:Standardized contracts on regulated platforms enable real-time price discovery and reduced counterparty risk. US CFTC proposed guidance on position limits and disclosure standards attracts institutional capital seeking regulated exposure.
- Over-the-Counter:Bilateral negotiations between buyers and project developers dominate nature-based solution procurement. Brazil reforestation and Indonesia peatland credits trade predominantly through direct offtake structures with technology sector buyers.
- Spot Market:Immediate delivery transactions serve compliance-driven buyers with urgent offset requirements.
- Futures Market:Forward contracts hedge price exposure for project developers with multi-year verification timelines.
Over-the-Counter channels capture most nature-based solution volume. Exchange Traded mechanisms are expanding most quickly as standardization reduces settlement risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The voluntary carbon credit trading industry traces its commercial origins to the United States, where early emissions trading mechanisms and corporate sustainability programs established the foundational infrastructure for verified offset markets.
United States
Technology sector net-zero commitments and financial institution climate portfolios drive procurement volume. The US Commodity Futures Trading Commission proposes position limits and disclosure standards for exchange-traded carbon derivatives. New York and San Francisco sustainability-linked finance clusters channel capital into standardized offset contracts.
Brazil
Amazon basin reforestation projects attract premium pricing from multinational corporations seeking permanence-guaranteed supply. The national environmental regulator, IBAMA, oversees land-use verification protocols that align with international certification standards. São Paulo-based project developers negotiate directly with semiconductor manufacturers for long-term offtake agreements.
Indonesia
Peatland restoration initiatives neutralize data center energy footprints for cloud computing providers. The Ministry of Environment and Forestry administers jurisdictional integrity frameworks that facilitate cross-border credit flows. Jakarta and Singapore exchange infrastructure connects Indonesian project supply with Asian financial institution demand.
Germany
Industrial importers into the European Union pre-purchase verified offsets to hedge carbon border adjustment exposure. The EU Green Deal's embedded emissions documentation requirements reshape compliance strategies for steel and cement traders. Frankfurt sustainability finance clusters integrate offset procurement into lending covenant structures.
United Kingdom
Financial institutions mandate verified offset coverage for residual emissions in climate-aligned portfolios. The Financial Conduct Authority oversees disclosure standards for carbon credit derivative instruments. London exchange infrastructure controls real-time price discovery for standardized voluntary carbon contracts.
Global Voluntary Carbon Credit Trading Market Competitive Environment
Capital-heavy verification infrastructure providers compete with asset-light certification standard-setters for influence over market integrity protocols. The vendor base concentrates around three dominant certification bodies that control methodological approval and project registration. Two strategic archetypes define competitive positioning: vertically integrated registry-exchange operators and specialized verification consultancies. Dominant competitive moves include strategic partnerships between registries and satellite monitoring providers, plus geographic expansion of exchange infrastructure into Asian financial centers.
Within the certification standard tier, Verra and Gold Standard occupy positions as methodological gatekeepers whose protocols determine project eligibility for premium pricing. Xpansiv exemplifies the integrated registry-exchange archetype through its control over spot market infrastructure and real-time price discovery mechanisms. These three entities anchor the competitive structure by defining how carbon credits achieve verification, trade liquidity, and retirement tracking across fragmented national registries.
| Leading Market Players |
|---|
| Verra |
| Gold Standard |
| Xpansiv |
| AirCarbon Exchange |
| 3Degrees |
| Climate Impact Partners |
| Carbon Trade Exchange |
| South Pole |
| Ecosecurities |
| Others |
Value Chain & Pricing Dynamics
Satellite monitoring and ground-truthing labor costs cascade from project developers through Verra and Gold Standard verification tiers, compressing margins for Indonesian peatland and Brazil reforestation initiatives while elevating price premiums for permanence-guaranteed supply. This cost pressure stratifies the market into certification-grade pricing bands that reward jurisdictional integrity investments.
Pricing Analysis
Long-term offtake contracting dominates transaction structures, with three-tier pricing stratification across premium Gold Standard co-benefit credits, standard Verra-certified forestry offsets, and economy-grade renewable energy certificates. Price differentiation rests on certification stringency and permanence verification depth, with nature-based solutions commanding substantial premiums over technology-based alternatives. Pricing pressure intensifies in the spot market as corporate buyers consolidate procurement through direct negotiations, squeezing intermediary markups. Financial institutions demonstrate lowest price sensitivity, prioritizing jurisdictional integrity and retirement transparency over per-tonne cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from EU-based importers mandate project developers qualify credits across both Verra and Gold Standard registries to ensure carbon border adjustment compliance flexibility. Geographic supply concentration centers on Brazil, Indonesia, and India, with nature-based solution development drawing from satellite imagery providers, local land stewards, and third-party validation bodies. Supply chain risk accumulates around single-source vulnerability in jurisdictional integrity frameworks, where divergent national interpretations of Core Carbon Principles fragment fungibility. Distribution runs through Singapore and London exchange infrastructure for standardized contracts, while bilateral negotiations dominate premium nature-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Voluntary Carbon Credit Trading Market represents a late-cycle quality story as corporate buyers shift procurement toward permanence-verified, co-benefit-certified offsets that withstand tightening integrity standards.
For Market Incumbents: Lock in jurisdictional integrity positioning by securing IBAMA-aligned verification protocols for Brazil reforestation assets and satellite monitoring partnerships that compress certification timelines. Invest in backward integration into permanence monitoring infrastructure to defend margin position against Gold Standard's escalating co-benefit requirements. Prioritize registry interoperability with Singapore exchange infrastructure to capture financial institution demand migrating from over-the-counter channels. For New Entrants and Emerging Players: The EU Green Deal's carbon border adjustment mechanism in Germany opens a window for blue carbon methodology specialists to capture compliance-driven demand from steel and cement importers seeking marine ecosystem co-benefits. Target Indonesian mangrove restoration as the most penetrable supply segment, where verification infrastructure gaps create first-mover advantages for satellite-native monitoring platforms. Pursue direct offtake negotiations with cloud computing providers as the optimal go-to-market angle, bypassing intermediary-dominated spot markets. For Investors and Strategic Acquirers: Consolidation pressure builds where registry-exchange integration creates data moats that smaller verification consultancies cannot replicate independently. Frame long-term viability around five-to-ten year windows where jurisdictional integrity standards converge toward interoperable protocols, rewarding vertically integrated operators with captive project pipelines. Target acquisition profiles toward specialized verification consultancies with IBAMA or Ministry of Environment and Forestry relationships in Brazil and Indonesia. Watch Article 6 fungibility negotiations as the critical inflection signal determining whether compliance-voluntary market arbitrage sustains premium pricing tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Registry-Exchange Integration | Unifying Verra and Gold Standard data with CBL spot infrastructure reduces double-counting risk for institutional buyers. |
| Blue Carbon Methodology Development | Mangrove and seagrass protocols unlock Southeast Asian supply for marine ecosystem co-benefit seekers. |
| Satellite Monitoring Partnership | Remote sensing integration with IBAMA verification compresses certification timelines for Amazon basin projects. |
| Long-term Offtake Structuring | Direct negotiations with semiconductor manufacturers displace intermediary margins in Brazil reforestation procurement. |
| Jurisdictional Integrity Certification | EU Carbon Border Adjustment Mechanism alignment commands premium pricing from German steel and cement importers. |
Study Parameters
Multiple input streams — project developer interviews, registry operator disclosures, and exchange transaction data — were reconciled against regulatory filings and certification standard documentation. Primary fieldwork encompassed sustainability officers at technology and financial institutions, verification specialists at Verra and Gold Standard, and peatland restoration developers in Indonesia. Secondary validation drew from UNFCCC Article 6 negotiation records, EU Green Deal implementation guidance, US CFTC proposed rulemakings, and national registry statistics. Bottom-up project pipeline assessments were triangulated with top-down corporate procurement disclosure analysis.
Data-stream reconciliation across component, application, end-user, and market-type dimensions shaped the analytical framework over the projection horizon. Segmentation modeling captured verification infrastructure, carbon offset methodologies, procurement channels, and buyer sophistication tiers. CAGRs were derived from project issuance trajectories, corporate climate pledge activation rates, and regulatory compliance timeline assumptions. Forecast inputs incorporated satellite monitoring cost curves, permanence verification technology adoption, and jurisdictional integrity standard convergence scenarios.
Revisions become necessary when Article 6 fungibility negotiations stall, Core Carbon Principles interpretations fragment across certification bodies, or corporate net-zero commitment timelines accelerate beyond project development capacity. Forecasts reflect documented assumptions about regulatory enforcement intensity, verification technology cost compression, and financial institution portfolio allocation shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Carbon Management and Offsetting
Carbon Credit Trading Platform Market
Carbon Management and Offsetting
Smart Carbon Market
Carbon Management and Offsetting
Carbon Credit Market
Carbon Management and Offsetting
Asia-Pacific Carbon Dioxide Market
Carbon Management and Offsetting
Carbon Management System Market
Carbon Management and Offsetting
Emission Trading Schemes Market
Carbon Management and Offsetting
Carbon Verification Market
Carbon Management and Offsetting
Europe Carbon Dioxide Market
Carbon Management and Offsetting
Asia-Pacific Green Carbon Market
Carbon Management and Offsetting
Carbon Dioxide Market
Carbon Management and Offsetting
Emission Management Market
Carbon Management and Offsetting
Carbon Footprint Management Market
Carbon Management and Offsetting
Carbon Management Software Market
Carbon Management and Offsetting
Asia-Pacific Carbon Footprint Management Market
Carbon Management and Offsetting
Track Carbon Footprint App Market
Carbon Management and Offsetting
Voluntary Carbon Credits Market